
 Phosphorus Ore Market | 2026-2036
Phosphorus Ore Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphorus Ore Market Analytics
Fertilizer-grade ore is bifurcating the Phosphorus Ore Market into premium concentrate and standard-run-of-mine tiers. OCP Group S.A. leverages captive reserves in Morocco to dominate seaborne phosphate rock trade. The Mosaic Company anchors North American supply through integrated Florida mining and downstream processing. PhosAgro Group of Companies differentiates via low-cadmium ore output suited for EU fertilizer regulations.
Phosphorus ore denotes sedimentary or igneous rock containing phosphate minerals, typically quantified by bone phosphate of lime (B2O5) content ranging from 28% to 36% P2O5, which beneficiation plants upgrade through flotation or calcination for downstream phosphoric acid manufacture. Agriculture absorbs the dominant volume of processed phosphate rock, with diammonium phosphate commanding the largest fertilizer application share due to its nitrogen-phosphorus nutrient balance and established blending infrastructure. Direct sales channels control bulk fertilizer-grade transactions, while distributors manage smaller volumes to fragmented farmer bases across emerging agrarian economies.
EPA mining effluent guidelines in the United States and REACH chemical registration in Europe constrain cadmium and heavy metal thresholds in imported phosphate fertilizers. China's MEE enforces tailings dam standards and water recycling mandates at domestic phosphorus mining complexes. Stakeholders must monitor evolving regulatory thresholds for contaminant limits, as these specifications increasingly determine ore marketability and processing plant retrofit requirements across major import jurisdictions.
Market Dynamics
Supply concentration in Morocco's Khouribga basin is fragmenting competitive access to seaborne phosphate rock, as OCP Group S.A. leverages captive reserves to dictate term contract pricing and destination clauses across Atlantic and Indian Ocean trade lanes.
Growth Catalysts
- EU F-Gas Regulation:Tightening extraction emissions standards are forcing beneficiation plant upgrades that favor low-cadmium ore suppliers with existing compliance infrastructure.
- Brazilian agribusiness expansion:Soybean and corn cultivation in Mato Grosso and Goiás is pulling record fertilizer-grade phosphate concentrate volumes through Paranaguá and Santos port terminals.
- Flotation beneficiation:Advanced froth flotation circuits at Moroccan and Saudi processing complexes are upgrading run-of-mine ore from 28% to 36% P2O5 content, expanding merchantable supply.
Market Restraints
- Sulfuric acid cost volatility:Wet-process phosphoric acid production consumes 2.5-3.0 tonnes of sulfuric acid per tonne of P2O5, tying plant economics to volatile sulfur and energy input markets.
- Khouribga supply concentration:Over 70% of export-grade phosphate rock originates from a single Moroccan mining basin, creating geopolitical and logistics chokepoint exposure for importers.
- REACH cadmium thresholds:ECHA-enforced limits on heavy metal content in finished fertilizers are disqualifying standard-grade ore from EU import quotas, compressing addressable supply.
Strategic Opportunities
- India's nutrient-based subsidy reform:The government's shift toward customized fertilizer blends is opening demand for specialty phosphate products beyond standard diammonium phosphate.
- Direct shipping ore bypass:Bypassing traditional trader intermediaries to supply Indian and Brazilian fertilizer manufacturers through long-term offtake agreements is compressing working capital cycles.
- Phosphogypsum valorization:EU waste framework directives incentivizing circular economy applications for phosphoric acid byproducts are creating revenue streams from former tailings liabilities.
Industry Challenges
- Beneficiation chemical engineering talent:Specialized expertise in flotation reagent chemistry and calcination kiln optimization is concentrated among retiring cohorts at Moroccan and Florida processing facilities.
- Legacy dam safety retrofitting:China's MEE tailings dam integrity mandates and parallel EPA guidelines in Florida are forcing capital-intensive geotechnical reinforcement at aging storage facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphorus Ore Market |
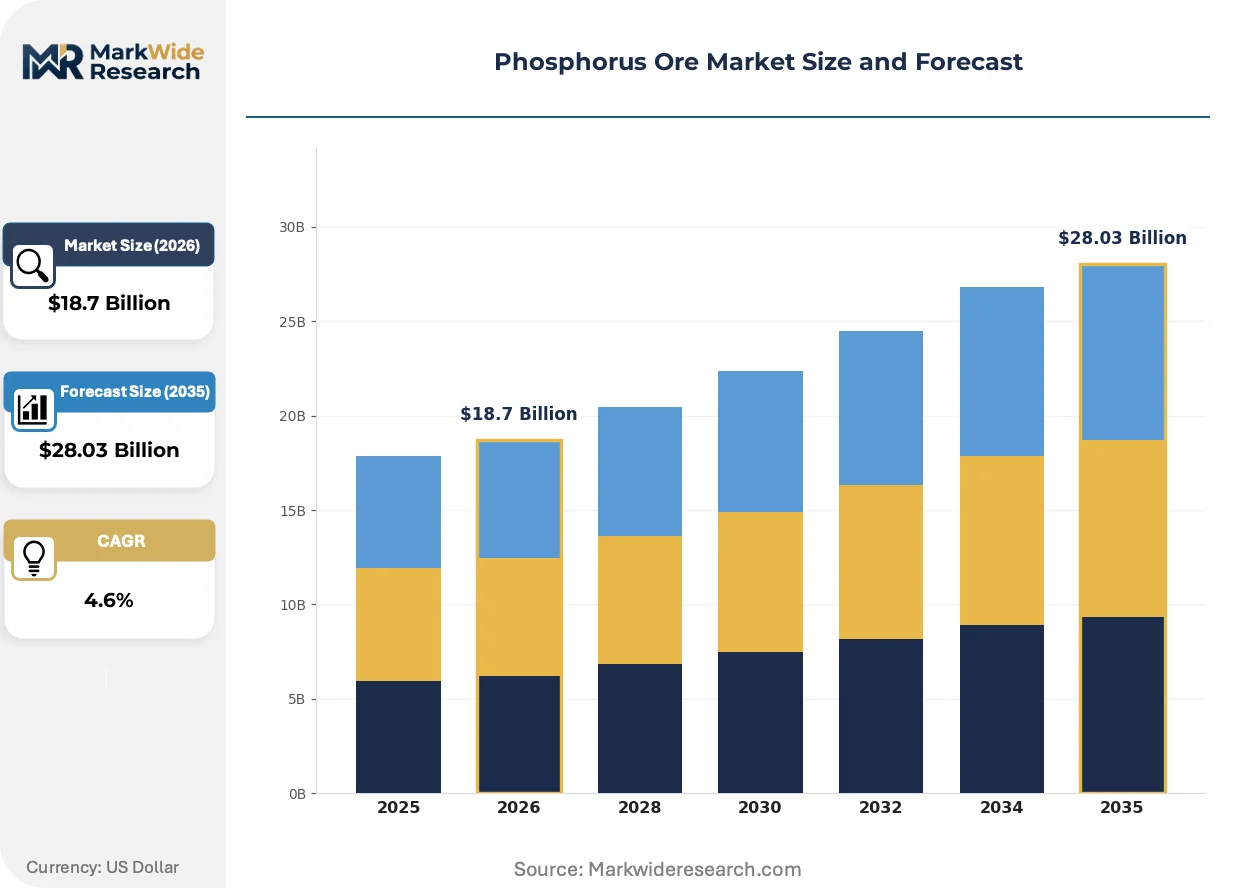
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphate Rock, Dicalcium Phosphate, Monoammonium Phosphate, Diammonium Phosphate Application: Agriculture, Food Industry, Animal Feed, Chemical Production End User: Farmers, Agribusiness, Chemical Manufacturers, Food Processors Distribution Channel: Direct Sales, Distributors, Retailers, Online Sales |
| Companies Covered | OCP Group S.A., The Mosaic Company, PhosAgro Group of Companies, Ma'aden, Nutrien Ltd., Wengfu Group Co., Ltd., Yuntianhua Group Co., Ltd., Guizhou Kailin Holdings (Group) Co., Ltd., Jordan Phosphate Mines Company (PLC), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphorus Ore Market Evolving Landscape
Beneficiation technology and regulatory chemistry specifications are fragmenting the formerly commoditized phosphate rock trade into tiered product categories with divergent pricing and destination access.
Sensor-based ore sorting is fragmenting traditional flotation-dominated beneficiation flowsheets. Mining operations in Saudi Arabia's Al-Jalamid deposit and Peru's Bayóvar project are deploying X-ray transmission and laser-induced breakdown spectroscopy units to pre-concentrate ore before grinding circuits. This technology compresses water and reagent consumption by 15-25% while enabling lower-grade ore bodies to achieve fertilizer-grade specifications.
REACH chemical registration and the EU Green Deal's carbon border adjustment mechanism are tightening heavy metal and embodied emissions documentation requirements for imported phosphate fertilizers. ECHA's cadmium limit proposals are forcing Moroccan and Russian exporters to segregate low-cadmium ore streams or invest in calcination-based de-cadmium processes. Fertilizer blenders in Germany and France are now requiring batch-level certificates of analysis, shifting procurement toward integrated miners with laboratory traceability systems.
Indian fertilizer importers are consolidating purchase volumes through pooled procurement platforms managed by the Department of Fertilizers and cooperative federations like IFFCO. This behavioral shift compresses spot market liquidity and extends contract tenors from annual to multi-year frameworks. Brazilian distributors in Mato Grosso and Rio Grande do Sul are responding by forming buying consortia to match Indian scale, forcing trader margins toward logistics and financing services rather than physical arbitrage.
Phosphorus Ore Market Segmentation
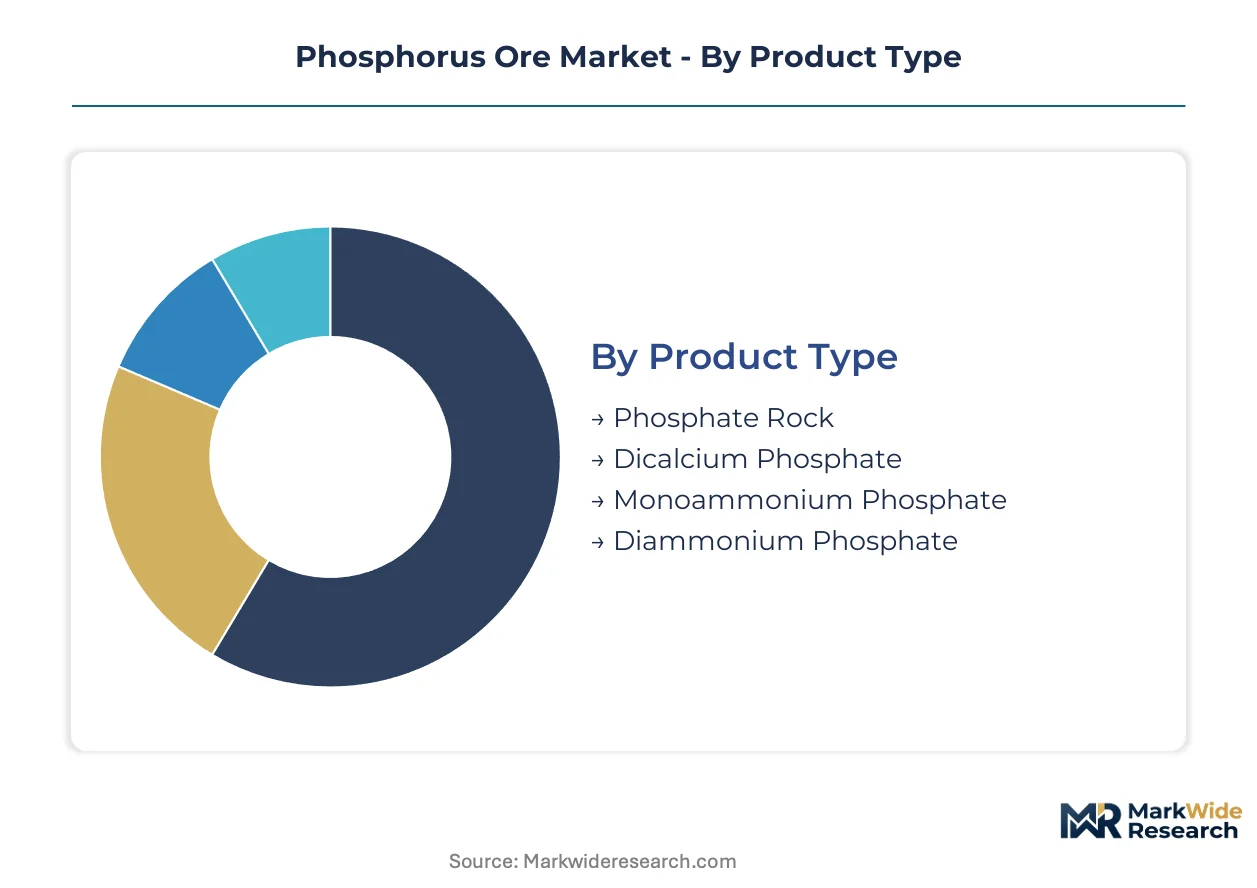
Phosphorus ore segmentation reveals how ore grade and processing intensity map to distinct commercial pathways. Product type determines beneficiation investment and destination market access. Application and end-user splits expose where regulatory thresholds and procurement scale reshape competitive positioning.
Product Type:
Export-led segments dominate Atlantic and Indian Ocean trade lanes, while domestic-processing grades concentrate in vertically integrated North American and Chinese supply chains.
- Phosphate Rock:Run-of-mine ore with 28-36% P2O5 content requiring flotation or calcination beneficiation. Brazilian fertilizer manufacturers at Paranaguá and Santos terminals pull record volumes for downstream phosphoric acid production, though Khouribga supply concentration creates logistics chokepoint exposure.
- Diammonium Phosphate:Granular fertilizer with 18-46-0 N-P-K formulation serving as the dominant finished phosphate product. Indian cooperative federations like IFFCO consolidate procurement through pooled platforms, compressing spot liquidity and extending contract tenors toward multi-year frameworks.
- Dicalcium Phosphate:Animal feed-grade material with controlled fluorine content for livestock mineral supplementation.
- Monoammonium Phosphate:Lower-nitrogen alternative used in specialty fertilizer blends and industrial applications.
Phosphate rock commands the established base. The steepest expansion runs through diammonium phosphate.
Application:
Volume concentration and margin structure diverge sharply between bulk commodity fertilizers and specification-driven industrial segments.
- Agriculture:Crop nutrient applications absorbing dominant processed phosphate volumes, with soybean and corn cultivation in Mato Grosso and Goiás driving Brazilian demand. EPA effluent guidelines and REACH cadmium thresholds increasingly disqualify standard-grade ore from key import markets.
- Food Industry:Food-grade phosphates for leavening agents, emulsifiers, and pH control requiring ultra-low heavy metal certification. EU EFSA specifications and China's national food safety standards enforce batch-level traceability that favors integrated miners with captive laboratory infrastructure.
- Animal Feed:Mineral supplements and feed additives with fluorine and heavy metal limits set by FDA Center for Veterinary Medicine and parallel EU feed hygiene regulations.
- Chemical Production:Industrial phosphates for detergents, metal treatment, and specialty chemicals facing substitution pressure from zeolites and biobased alternatives.
Agriculture anchors volume throughput. Food industry applications are climbing the fastest on regulatory premium capture.
End User:
Procurement scale and technical sophistication separate consolidated agribusiness buyers from fragmented farmer bases.
- Agribusiness:Large-scale farming operations and integrated cooperatives with direct import capacity and laboratory certification requirements. Brazil's buying consortia in Mato Grosso and Rio Grande do Sul now match Indian procurement scale, forcing trader margins toward logistics and financing services.
- Chemical Manufacturers:Phosphoric acid and downstream derivative producers with sulfuric acid integration and wet-process technology. Volatile sulfur input costs and energy pricing compress plant economics, favoring producers with captive sulfur recovery or proximity to low-cost sulfur sources.
- Farmers:Fragmented smallholder and mid-scale operators dependent on distributor networks and government subsidy programs.
- Food Processors:Bakers, dairy, and meat processors requiring certified food-grade phosphate specifications with full chain-of-custody documentation.
Agribusiness controls volume concentration. Chemical manufacturers are expanding most quickly on downstream integration incentives.
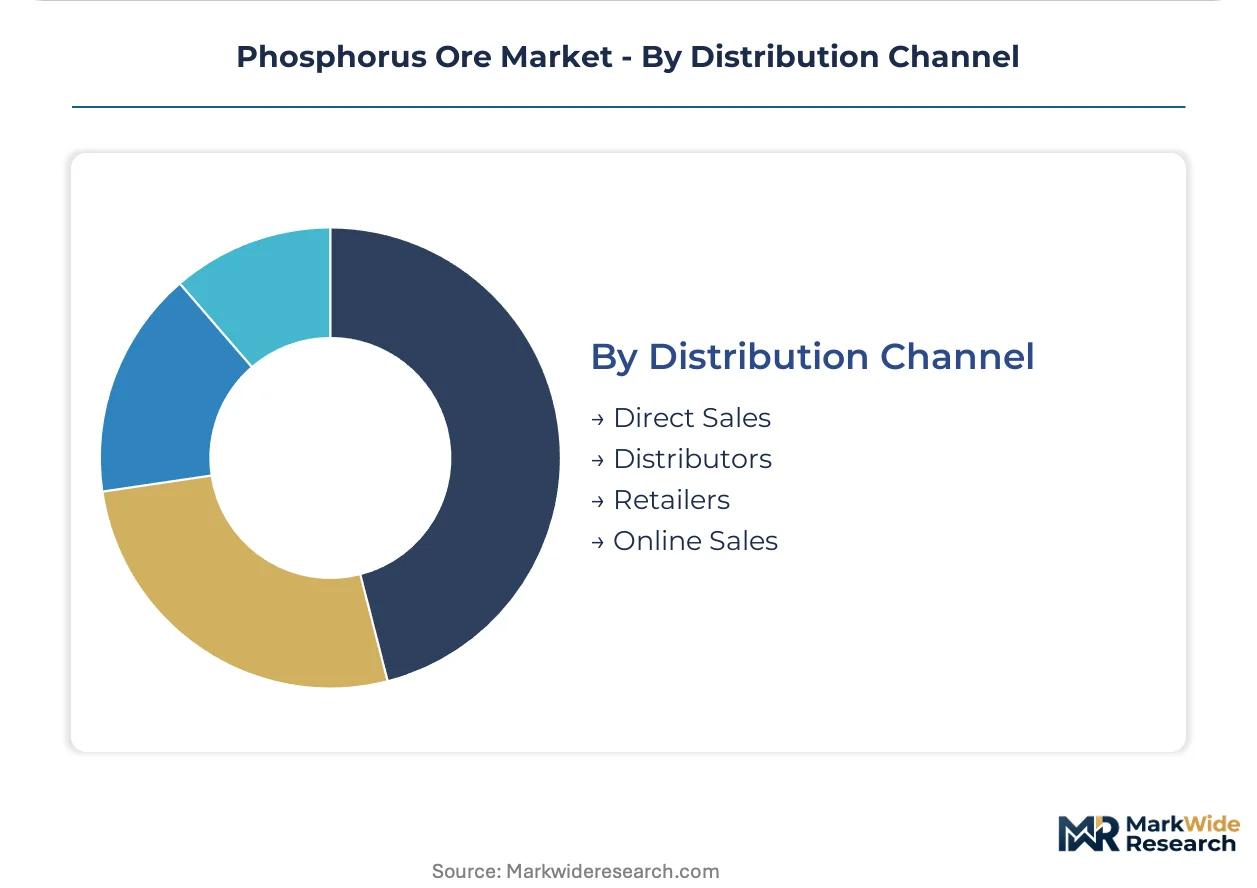
Distribution Channel:
Working capital efficiency and price discovery mechanisms vary across direct contract, intermediary, and digital pathways.
- Direct Sales:Long-term offtake agreements between miners and fertilizer manufacturers bypassing trader intermediaries. Indian Department of Fertilizers pooled procurement and Brazilian buying consortia compress working capital cycles and reduce price volatility exposure.
- Distributors:Regional intermediaries managing logistics, credit extension, and technical advisory for fragmented farmer bases across emerging agrarian economies.
- Retailers:Farm supply cooperatives and agricultural input stores serving smallholder procurement with bagged product and seasonal financing.
- Online Sales:Emerging digital platforms for price transparency and small-lot procurement, particularly in India's subsidy-linked fertilizer distribution reforms.
Direct sales anchor bulk fertilizer-grade transactions. Online sales channels are gaining share fastest on subsidy platform digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Khouribga's captive reserves concentrate seaborne phosphate rock supply in Moroccan hands, while import-dependent agrarian economies in Brazil and India reshape procurement patterns through consolidated buying platforms.
Morocco
OCP Group S.A. controls Khouribga mining basin output serving Atlantic and Indian Ocean trade lanes. The country's national mining regulator enforces tailings dam integrity standards at beneficiation complexes. Jorf Lasfar industrial port hosts phosphoric acid and fertilizer derivative plants processing captive ore.
Brazil
Soybean and corn cultivation in Mato Grosso and Goiás pulls record fertilizer-grade concentrate volumes through Paranaguá and Santos terminals. ANVISA oversees heavy metal thresholds in imported phosphate fertilizers. Buying consortia in Rio Grande do Sul now match Indian procurement scale, compressing trader margins toward logistics services.
India
Cooperative federations consolidate diammonium phosphate purchases through Department of Fertilizers pooled platforms. FSSAI enforces batch-level food-grade phosphate certification for downstream processors. Kandla and Mundra port terminals handle bulk import volumes for domestic fertilizer manufacturers.
China
Domestic phosphorus mining complexes face MEE tailings dam standards and water recycling mandates. The country's dual carbon goals tighten extraction emissions thresholds at Guizhou and Yunnan processing facilities. Yangtze River Delta chemical manufacturers integrate captive sulfuric acid capacity with wet-process phosphoric acid output.
United States
The Mosaic Company anchors North American supply through integrated Florida mining and downstream processing. EPA mining effluent guidelines constrain cadmium and heavy metal discharge at beneficiation plants. Tampa Bay and Mississippi River corridor facilities link phosphate rock output to corn belt fertilizer demand.
Phosphorus Ore Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the phosphorus ore value chain. Integrated miners with captive reserves dominate seaborne trade, while regional processors compete on sulfuric acid integration and logistics proximity to end markets. Strategic archetypes include reserve-backed volume players, low-cadmium specialty suppliers, and vertically integrated fertilizer manufacturers. Competitive moves concentrate on long-term offtake contracting and beneficiation plant upgrades to meet tightening EU and Chinese emissions standards.
Among reserve-backed Moroccan and Russian suppliers, OCP Group S.A. and PhosAgro Group of Companies occupy positions shaped by captive ore quality and regulatory compliance infrastructure. North American integrated players include The Mosaic Company, which exemplifies the sulfuric-acid-integrated processor archetype with Florida-based mining and downstream fertilizer production. Ma'aden represents the Saudi Arabian entrant leveraging Al-Jalamid deposit access and Red Sea logistics positioning for Indian and Asian market penetration.
| Leading Market Players |
|---|
| OCP Group S.A. |
| The Mosaic Company |
| PhosAgro Group of Companies |
| Ma'aden |
| Nutrien Ltd. |
| Wengfu Group Co., Ltd. |
| Yuntianhua Group Co., Ltd. |
| Guizhou Kailin Holdings (Group) Co., Ltd. |
| Jordan Phosphate Mines Company (PLC) |
| Others |
Value Network & Pricing Analysis
EU REACH cadmium thresholds gate both ore marketability and price differentiation simultaneously, forcing Moroccan and Russian exporters to segregate low-cadmium streams or invest in calcination-based de-cadmium processes that compress margins on standard-grade output. This regulatory filter bifurcates the seaborne trade into premium concentrate commanding destination access versus standard run-of-mine facing quota restrictions.
Pricing Analysis
REACH dictates the pricing tier structure across the Phosphorus Ore Market, separating low-cadmium certified concentrate from standard-grade ore facing EU import disqualification. Price differentiation rests on heavy metal certification level and volume scale, with Indian pooled procurement platforms and Brazilian buying consortia extracting discounts through multi-year offtake commitments. Cost compression in standard-grade tiers is intensifying because ECHA-enforced limits disqualify material from key Atlantic trade lanes. Smallholder farmers dependent on distributor networks exhibit highest price sensitivity, while integrated agribusiness buyers with direct import capacity show lowest.
Supply Chain Analysis
Inventory cycles at Moroccan Jorf Lasfar and Saudi Arabian Ras Al-Khair industrial ports extend lead times for Indian and Brazilian contract buyers, compressing working capital flexibility. Geographic supply concentrates in Morocco, Saudi Arabia, and Russia, with over 70 percent of export-grade phosphate rock originating from Khouribga basin. Raw material dependencies draw from sulfuric acid, flotation reagents, and calcination fuel feedstocks. Single-source vulnerability from Khouribga concentration creates geopolitical chokepoint exposure for Atlantic and Indian Ocean importers. Distribution runs through long-term offtake agreements, pooled procurement platforms, and regional distributor networks managing fragmented farmer bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Phosphorus Ore Market is approaching a platform-economics inflection as Indian pooled procurement platforms and Brazilian buying consortia consolidate purchase volumes, forcing trader intermediaries toward logistics and financing service models rather than physical arbitrage.
For Market Incumbents: Consolidate reserve-backed volume positions through captive beneficiation upgrades that meet tightening EU F-Gas Regulation and China MEE emissions standards. Deepen upstream control over low-cadmium ore streams to defend against PhosAgro's specialty-grade positioning. Prioritize laboratory traceability infrastructure to capture food industry premium tiers. For New Entrants and Emerging Players: Direct shipping ore bypass services where integrated incumbents under-serve represent the most penetrable white-space, particularly for mid-scale Brazilian fertilizer manufacturers outside Mato Grosso buying consortia. Target India's nutrient-based subsidy reform segment for specialty phosphate products beyond standard diammonium phosphate. Pursue long-term offtake agreements with Kandla and Mundra port terminal operators as primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from state-linked mining parents seeking to monetize non-core phosphate assets, particularly in Jordan and North Africa. Five-to-ten year viability favors integrated miners with captive sulfuric acid capacity and Red Sea logistics positioning. Watch for Indian Department of Fertilizers platform expansion into multi-year contract frameworks as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Indian pooled procurement platforms compress spot liquidity and extend contract tenors toward multi-year frameworks. |
| Backward Integration | Captive sulfuric acid capacity insulates phosphoric acid producers from volatile sulfur input cost swings. |
| Green Manufacturing Transition | Calcination-based de-cadmium processes enable EU market access for Moroccan and Russian ore streams. |
| Capacity Expansion | Flotation beneficiation upgrades at Saudi Al-Jalamid expand merchantable supply from 28% to 36% P2O5 content. |
| Joint Venture | Brazilian buying consortia in Rio Grande do Sul match Indian procurement scale, forcing trader margin compression. |
Research Methodology
Initial hypotheses were tested against primary input from mining operations executives, fertilizer manufacturer procurement leads, beneficiation plant engineers, and agricultural cooperative federations and refined through secondary validation against customs and trade data, OCP Group and Mosaic Company SEC filings, ECHA regulatory proposals, and Indian Department of Fertilizers procurement disclosures. Bottom-up volume modeling triangulated with top-down macroeconomic anchor checks.
Variance decomposition across ore grade tiers, end-use applications, regional production hubs, and beneficiation technology intensity shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs incorporated sulfuric acid cost volatility indices and EU cadmium limit proposal trajectories.
Forecasts assume regulatory continuity in EU REACH and China MEE regimes; material policy shifts would require re-modeling. Tailings dam integrity mandates and water recycling thresholds reflect current enforcement patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
US Lithium Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Diamond Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Sodium Tungstate Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Cesium Market
Metals & Minerals
Silver Mining Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market