
 2,2-Dimethylbutyryl Chloride Market | 2026-2036
2,2-Dimethylbutyryl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
2,2-Dimethylbutyryl Chloride Market Analytics
Multi-source procurement among pharmaceutical producers is expanding as API manufacturers diversify away from concentrated Chinese supply. Cabb Chemicals leverages its European manufacturing footprint to sustain long-term contracts with German and Swiss drugmakers. Thermo Fischer Scientific anchors North American distribution through its channel control over research-grade reagents. Shiva Pharma competes on cost-positioning in bulk intermediate volumes for agrochemical clients.
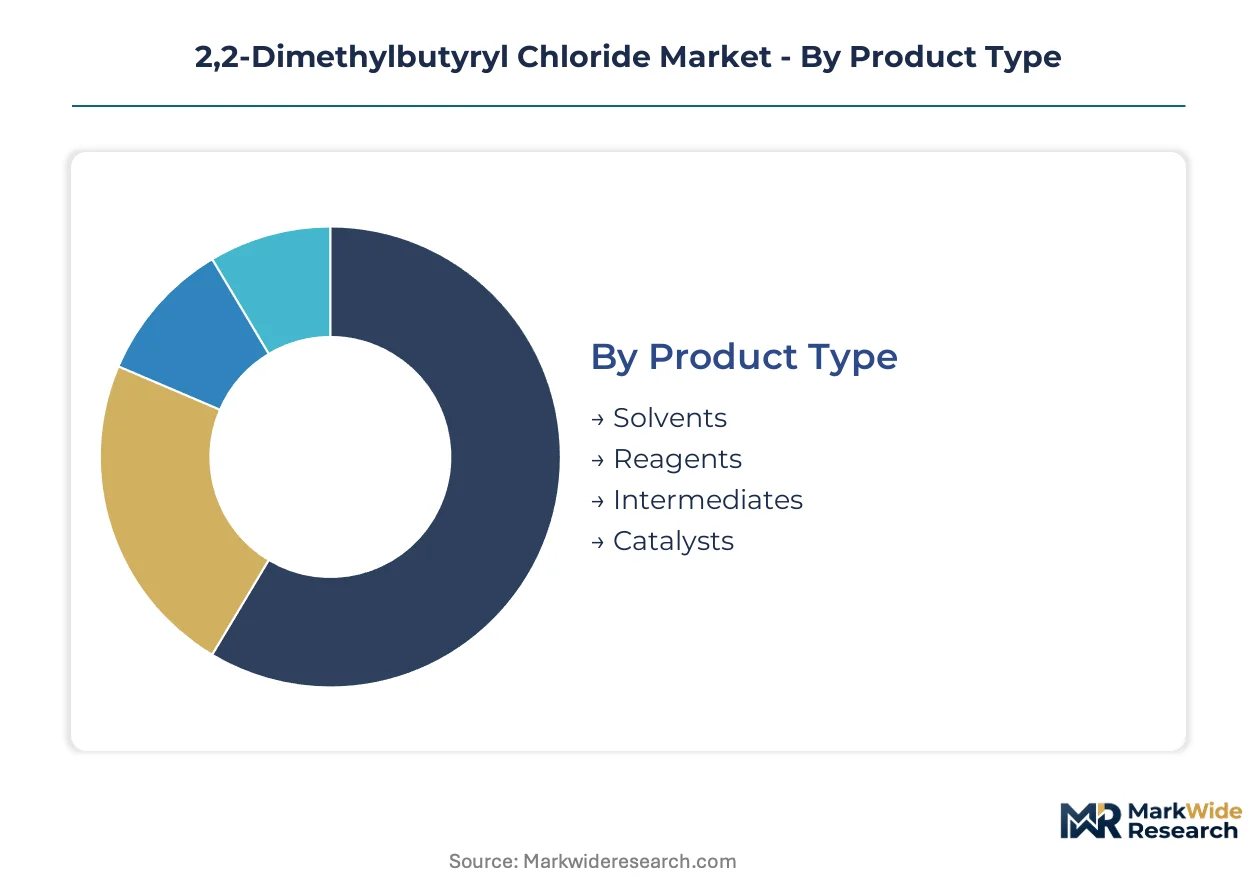
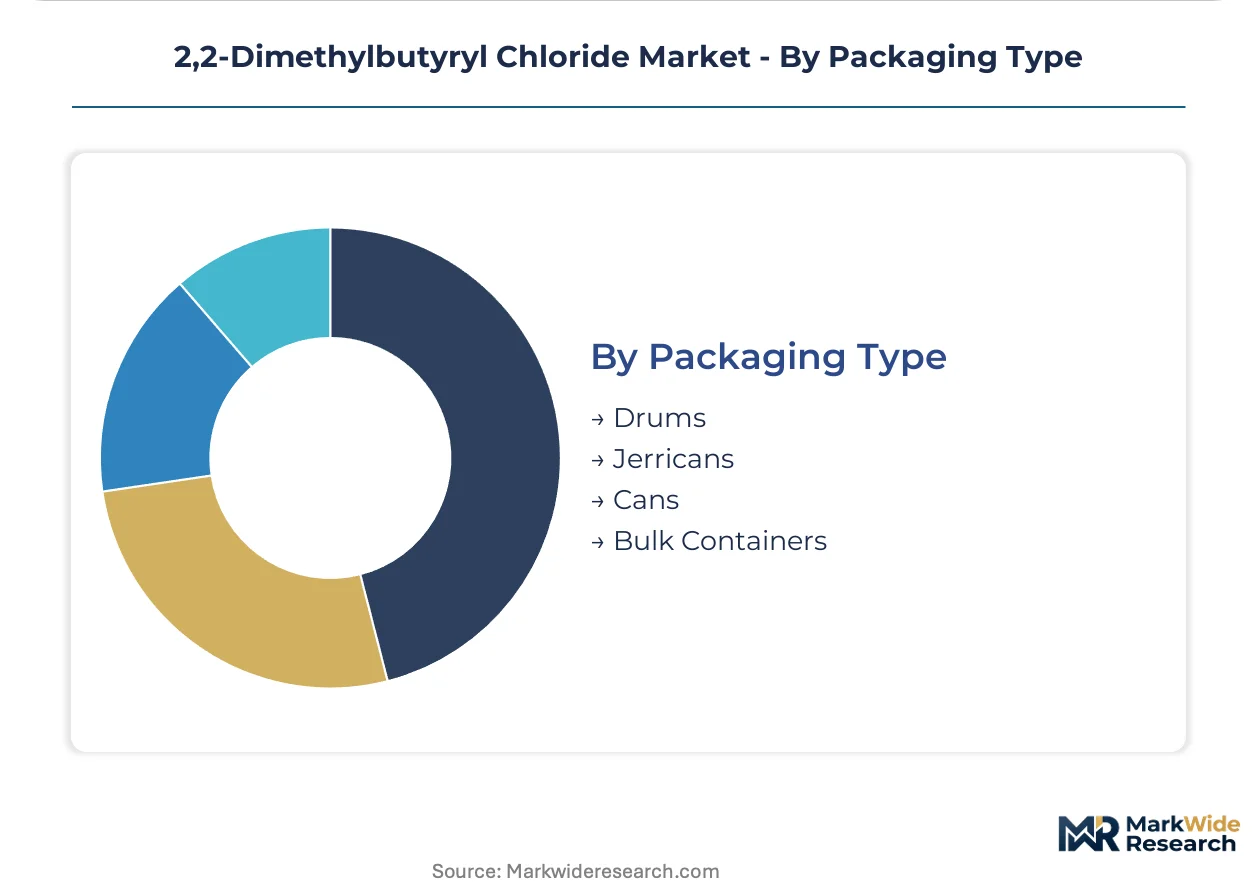
2,2-Dimethylbutyryl chloride is an acyl halide with the molecular formula C6H11ClO, synthesized via thionyl chloride-mediated chlorination of the corresponding carboxylic acid and employed primarily as an acylation reagent in organic synthesis. It functions as a building block for introducing dimethylbutyryl protecting groups and side chains in complex molecule construction. The reagents segment leads in value contribution due to stringent purity requirements for pharmaceutical applications, while intermediates represent the fastest-expanding category as CDMOs scale batch sizes for commercial API programs. Bulk containers dominate packaging demand in India and China, whereas drums and jerricans retain preference in European and North American laboratory and pilot-scale settings.
EPA oversight under TSCA governs manufacture and import thresholds in the United States, while REACH registration mandates in Europe impose full toxicological dossier requirements on volumes exceeding one tonne annually. China's MEE enforces emission controls on thionyl chloride utilization that directly affect production economics for domestic manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent purity and documentation standards will determine which suppliers qualify for multi-regional pharmaceutical supply agreements.
Market Dynamics
Pharmaceutical CDMOs are consolidating procurement around qualified acyl chloride suppliers capable of supporting commercial-scale API programs, compressing vendor lists and elevating purity specifications as the dominant market-shaping force.
Growth Catalysts
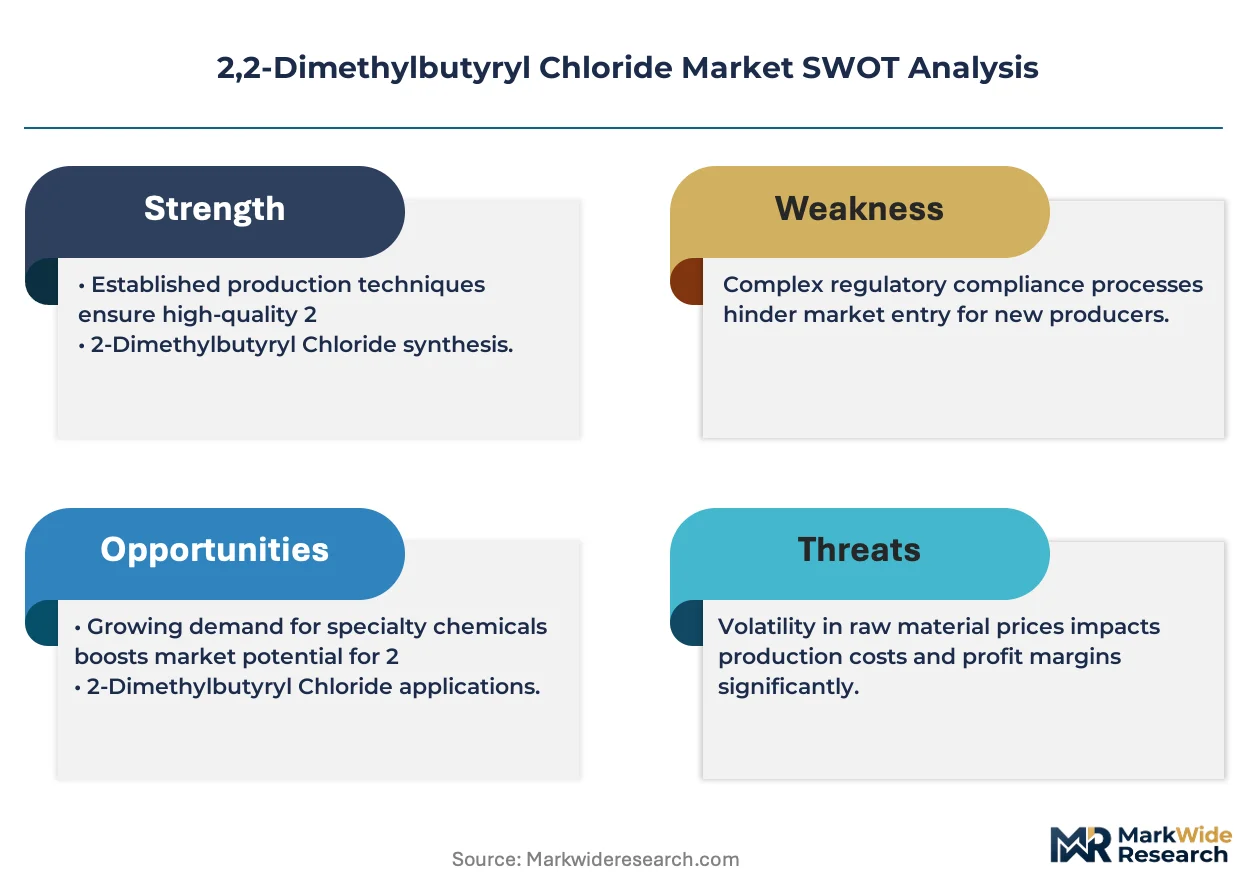
- REACH Registration Mandates:Full toxicological dossier requirements on volumes exceeding one tonne annually in Europe are filtering out unqualified suppliers and concentrating demand among compliant manufacturers with established registration packages.
- Thionyl Chloride Emission Controls:China's MEE enforcement is raising production economics for domestic manufacturers, creating procurement windows for external suppliers with cleaner process footprints.
- Advanced Intermediate Scaling:CDMOs in India are expanding batch sizes for commercial API programs, directly pulling higher volumes of reagent-grade acyl chlorides into long-term supply agreements.
Market Restraints
- Thionyl Chloride Price Volatility:Input cost swings for this chlorinating agent compress margin predictability for producers dependent on conventional synthesis routes.
- Chinese Supply Concentration:Domestic capacity clusters around thionyl chloride-dependent production, exposing buyers to disruption risks from emission-control enforcement waves.
- Regulatory Divergence Friction:Divergent purity and documentation standards between EPA TSCA, REACH, and China's MEE create qualification overhead that limits supplier flexibility across jurisdictions.
Strategic Opportunities
- Indian CDMO Expansion:Contract research and manufacturing organizations scaling commercial intermediate production present white-space demand for qualified acyl chloride suppliers with multi-tonne capacity.
- Green Chemistry Process Convergence:Catalytic chlorination methods combining flow chemistry with solid acid catalysts are opening pathways to lower-emission production qualifying for EU Green Deal-aligned procurement preferences.
- Research-Grade Channel Innovation:Direct-to-laboratory distribution platforms are compressing traditional distributor layers for small-volume pharmaceutical R&D customers in North America and Europe.
Industry Challenges
- Process Analytical Chemistry Talent Gap:Shortage of specialists capable of validating impurity profiling methods for pharmaceutical-grade acyl chloride release is extending qualification timelines for new suppliers.
- Multi-Jurisdictional Certification Complexity:Simultaneous pursuit of FDA drug master files, REACH registration, and CDSCO import approvals demands dedicated regulatory affairs infrastructure that mid-scale producers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2,2-Dimethylbutyryl Chloride Market |
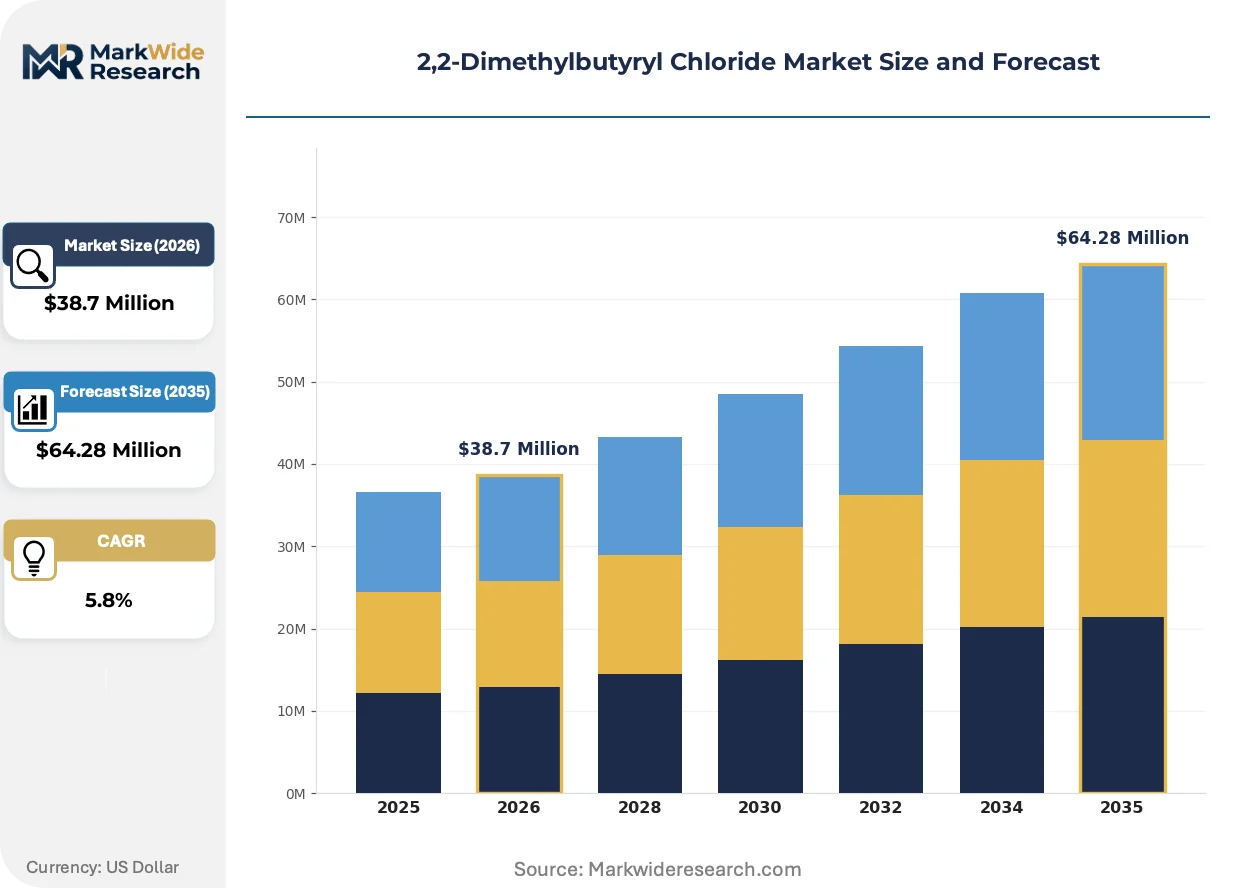
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $64.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Reagents, Intermediates, Catalysts Application: Chemical Synthesis, Agricultural Chemicals, Pharmaceuticals, Coatings End User: Chemical Manufacturers, Agrochemical Companies, Pharmaceutical Producers, Paint Manufacturers Packaging Type: Drums, Jerricans, Cans, Bulk Containers |
| Companies Covered | Thermo Fischer Scientific, TCI Chemicals, Cabb Chemicals, Manus Akkteva, Shiva Pharma, Conier Chem & Pharma, Santa Cruz Biotechnology, Acros Organics, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2,2-Dimethylbutyryl Chloride Market Evolving Landscape
Continuous processing technologies and emission-minimizing synthesis routes are actively restructuring production economics for acyl chloride manufacturing, while regulatory data requirements and procurement centralization reshape competitive access to pharmaceutical end-use segments.
Flow chemistry reactor systems employing in-situ chlorine generation are overtaking conventional batch thionyl chloride processes in new capacity investments. European and North American pharmaceutical intermediate producers are adopting these systems to preempt REACH-related emission liabilities. This technology is enabling on-demand production models that compress working capital requirements while satisfying tightened environmental audit standards from German and Swiss drugmakers.
REACH Article 33 supply chain communication obligations are extending documentary burden deep into acyl chloride distribution channels. Importers into Europe must now maintain substance volume tracking and safe-use information transmission across tiered supplier networks. Specialty chemical distributors serving laboratory and pilot-scale customers are responding by consolidating supplier bases around pre-registered manufacturers with established safety data sheet infrastructures.
Multi-year offtake agreements with embedded volume commitments and quality escalation clauses are replacing spot procurement for commercial API programs. CDMO procurement teams are disintermediating traditional chemical distributors to secure direct manufacturer relationships with batch traceability and audit rights. This pattern concentrates most visibly in India, where Piramal Pharma, Syngene, and similar organizations are locking in qualified acyl chloride supply for statin and antiviral intermediate pipelines.
2,2-Dimethylbutyryl Chloride Market Segmentation
Acyl chloride procurement patterns diverge sharply across end-use applications, with pharmaceutical-grade specifications commanding premium positioning while agrochemical volumes drive bulk logistics optimization. Segmentation reveals how purity thresholds, regulatory documentation burdens, and packaging economics reshape supplier competitive access across customer categories.
Product Type:
Supply concentration among registered manufacturers favors segments with established toxicological dossiers and validated impurity profiling capabilities.
- Reagents:High-purity grades exceeding 99.5% assay with specified moisture and acid chloride content limits serve pharmaceutical R&D and cGMP manufacturing. German and Swiss drugmakers anchor demand through long-term contracts with embedded audit rights and batch traceability requirements.
- Intermediates:Technical-grade material for downstream acylation reactions in commercial API programs, scaling from pilot to multi-tonne campaigns. Indian CDMOs at Piramal Pharma and Syngene are pulling volumes into direct manufacturer relationships with volume escalation clauses.
- Solvents:Diluted or stabilized formulations for specific reaction media applications.
- Catalysts:Modified acyl chloride derivatives employed in esterification and amidation protocols.
Today's leader: Reagents. Tomorrow's challenger: Intermediates.
Application:
Cost tier differentiation separates laboratory-scale chemical synthesis from commercial pharmaceutical manufacturing, with documentation and purity specifications widening the procurement gap.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis demands reagent-grade material with complete impurity characterization and regulatory filing support. FDA drug master files and REACH registration packages filter supplier pools to established manufacturers with dedicated analytical chemistry infrastructure.
- Chemical Synthesis:Academic and industrial research laboratories consume smaller volumes through distributor channels, prioritizing rapid delivery and certificate-of-analysis availability over long-term contract structures.
- Agricultural Chemicals:Technical-grade acyl chlorides for pesticide and herbicide intermediate production, with agrochemical companies negotiating on delivered cost and bulk logistics efficiency.
- Coatings:Modified ester formulations for specialty polymer and adhesive applications.
Pharmaceuticals command margin premiums. Agricultural Chemicals expand volume fastest.
End User:
Customer type determines procurement modality, with direct manufacturer relationships displacing traditional distribution for commercial-scale programs.
- Pharmaceutical Producers:Multi-source procurement strategies diversify supply away from concentrated Chinese production, with qualification timelines extending 18-24 months for new acyl chloride suppliers. CDMO procurement teams demand embedded volume commitments and quality escalation clauses.
- Chemical Manufacturers:Merchant producers of fine chemicals and advanced intermediates balance spot purchasing against annual contracts based on campaign scheduling.
- Agrochemical Companies:Volume-driven procurement with emphasis on bulk container logistics and just-in-time delivery to formulation plants.
- Paint Manufacturers:Specialized esterification applications for coating resin modification.
Direct supply to Pharmaceutical Producers tightens fastest. Chemical Manufacturers retain distributor flexibility longest.
Packaging Type:
Volume scale and geography dictate packaging economics, with regulatory documentation requirements extending to container labeling and safe-use information transmission.
- Bulk Containers:ISO tanks and dedicated tanker deliveries serve Indian and Chinese commercial intermediate production, minimizing per-unit logistics costs for multi-tonne campaigns. REACH Article 33 supply chain communication obligations extend to bulk shipment documentation and volume tracking.
- Drums:Standard 200-liter steel and HDPE containers dominate European and North American pilot-scale manufacturing, with UN certification and tamper-evident sealing meeting pharmaceutical customer audit standards.
- Jerricans:Laboratory-scale packaging for research-grade distribution through Thermo Fisher Scientific and specialty chemical distributors.
- Cans:Small-volume retail formats for academic and analytical chemistry applications.
Drums retain European preference. Bulk Containers capture Indian volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting acyl chloride production toward jurisdictions with lower compliance costs per tonne, as REACH registration burdens and EPA emission thresholds reshape where qualified supply originates. Manufacturers are migrating capacity to exploit gaps between European toxicological dossier requirements and emerging-market enforcement timelines.
United States
Pharmaceutical CDMOs in New Jersey and Massachusetts are expanding acyl chloride procurement for commercial API campaigns. EPA oversight under TSCA governs manufacture and import thresholds, tightening documentation for cross-border shipments. The Boston-Cambridge biotech corridor anchors demand for research-grade reagents with embedded audit rights.
Germany
Drugmakers in Ludwigshafen and Leverkusen sustain long-term contracts with acyl chloride suppliers possessing full REACH registration packages. ECHA mandates filter unqualified competitors from pharmaceutical supply chains. The Rhine-Ruhr chemical cluster concentrates advanced intermediate production requiring validated impurity profiling.
Switzerland
Swissmedic-regulated pharmaceutical producers in Basel prioritize suppliers with established safety data sheet infrastructures and batch traceability systems. The country's pharmaceutical export orientation demands multi-jurisdictional certification compatibility. Basel's Novartis-Roche ecosystem drives premium-tier reagent specifications.
India
Contract research organizations in Hyderabad and Bengaluru are scaling commercial intermediate production, pulling multi-tonne volumes into direct manufacturer relationships. CDSCO import approvals and state-level pollution control mandates shape supplier qualification timelines. The Genome Valley biotech cluster exemplifies CDMO procurement centralization.
China
Domestic capacity clusters around thionyl chloride-dependent production in Jiangsu and Zhejiang provinces, though MEE emission controls are compressing operating margins. The Yangtze River Delta retains concentration despite enforcement waves targeting chlorinating agent utilization. Shanghai-based distributors are consolidating around pre-registered export manufacturers.
2,2-Dimethylbutyryl Chloride Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue green chemistry certifications and flow-chemistry process patents to differentiate beyond conventional thionyl chloride routes. The vendor base stratifies across three archetypes: European-registered manufacturers with full REACH dossiers, Indian CDMO-aligned suppliers with multi-tonne commercial capacity, and research-grade distributors controlling North American laboratory channels. Competitive moves center on multi-year offtake agreements with embedded volume commitments and backward integration into chlorinating agent supply.
Within the European-registered tier, Cabb Chemicals and BASF SE exemplify manufacturers sustaining long-term pharmaceutical contracts through established toxicological documentation. Thermo Fischer Scientific anchors North American research-grade distribution, occupying a position between bulk intermediate producers and laboratory end-users. Shiva Pharma represents the India-aligned cost-positioning archetype, sitting within the bulk volume segment serving agrochemical and commercial API intermediate demand.
| Leading Market Players |
|---|
| Thermo Fischer Scientific |
| TCI Chemicals |
| Cabb Chemicals |
| Manus Akkteva |
| Shiva Pharma |
| Conier Chem & Pharma |
| Santa Cruz Biotechnology |
| Acros Organics |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Jiangsu and Zhejiang provinces anchor thionyl chloride-dependent production, compressing margin discipline through captive chlorinating agent supply while European-registered competitors offset higher REACH compliance costs through long-term pharmaceutical contracts with embedded price escalation clauses.
Pricing Analysis
Distributor margin layers in laboratory channels absorb 15-25 points before reaching end-users, while direct-to-CDMO contracts eliminate intermediary markups entirely. Three-tier pricing structure across reagent-grade, intermediate-grade, and technical-grade levels separates pharmaceutical audit-capable suppliers from commodity-positioned rivals. Pricing pressure stems from MEE emission enforcement in China raising domestic production costs. Agrochemical buyers exhibit highest price sensitivity; Swiss and German drugmakers prioritize certification reliability over unit cost.
Supply Chain Analysis
Direct-to-CDMO channels handle commercial-scale demand from Piramal Pharma and Syngene, bypassing traditional chemical distributors. Supply concentrates in China, India, and Germany, with thionyl chloride, dimethylbutyric acid, and chlorine gas feeding production economics. Single-source vulnerability runs through concentrated Chinese thionyl chloride capacity exposed to enforcement waves. Distribution runs through bulk ISO tank deliveries for Indian commercial campaigns and drum shipments for European pilot-scale manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as pharmaceutical CDMO procurement centralization locks qualified suppliers into multi-year offtake structures with embedded volume growth.
For Market Incumbents: Hedge thionyl chloride price volatility through backward integration into chlorinating agent production or long-term supply agreements with SO2/chlorine suppliers. Defend REACH-registered positioning against emerging flow-chemistry entrants by embedding audit rights and batch traceability deeper into Swiss and German pharmaceutical contracts. Prioritize analytical chemistry talent acquisition to compress qualification timelines for new CDMO customers. For New Entrants and Emerging Players: Begin with flow-chemistry reactor investments targeting EU Green Deal-aligned procurement preferences from German sustainability officers. The most penetrable white-space sits in Indian CDMO commercial intermediate supply, where Piramal Pharma and Syngene are disintermediating distributors. A direct-manufacturer go-to-market angle with embedded volume commitments and quality escalation clauses unlocks access. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian bulk intermediate producers lacking REACH registration but possessing multi-tonne commercial capacity and established CDMO relationships. Long-term viability frames around 5-10 year pharmaceutical outsourcing trends. The acquisition target archetype combines flow-chemistry process patents with pre-registered toxicological dossiers. Watch thionyl chloride emission enforcement intensity in China as inflection signal for external supplier opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorinating Agents | Captive thionyl chloride supply insulates margin from MEE enforcement volatility in Jiangsu province. |
| Flow Chemistry Capacity Investment | In-situ chlorine generation qualifies for EU Green Deal procurement preferences from German drugmakers. |
| REACH Registration Completion | Full toxicological dossiers filter competition from pharmaceutical supply chains under ECHA mandates. |
| Direct CDMO Relationship Formation | Disintermediation of distributors secures multi-year offtake with Piramal Pharma and Syngene. |
| Analytical Chemistry Talent Acquisition | Impurity profiling specialists compress 18-24 month supplier qualification timelines for new entrants. |
Research Methodology
Direct dialogue with pharmaceutical procurement directors, CDMO supply chain managers, acyl chloride plant managers, regulatory affairs leads, and specialty chemical distributors grounded qualitative insights. Secondary validation drew from ECHA registration databases, CDSCO import filings, customs trade data, and SEC disclosures from listed chemical producers. Bottom-up volume modeling across reagent, intermediate, and technical grades triangulated against top-down pharmaceutical intermediate demand projections.
Bottom-up modeling segmented by purity grade, end-use industry, packaging format, and regional production hub across the analysis window. CAGRs derived from weighted average of historical volume trajectories and forward pipeline visibility from disclosed CDMO expansion plans. Forecast inputs included thionyl chloride price indices, REACH registration timelines, and MEE enforcement intensity proxies.
Several conditions sit outside the modeled scope, including sudden regulatory reclassification of acyl chlorides under REACH Annex XIV, catastrophic thionyl chloride supply disruption from Yangtze River Delta enforcement waves, and breakthrough catalytic chlorination technology obsoleting conventional routes. Forecasts reflect assumptions about continued pharmaceutical outsourcing trends and stable chlorinating agent supply economics. Periodic stress-testing of base assumptions against MEE policy announcements and CDMO capital expenditure disclosures is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Aromatic Solvents Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Solvent Recovery Systems Market
Solvents
Decanol Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Benzylamine Market
Solvents
Methyl Ethyl Ketone (MEK) Market
Solvents
Allyl Cyanide Market
Solvents
Solvent Green 7 Market
Solvents
Global Glycol Market
Solvents
North America Acetonitrile Market
Solvents
Global Ink Solvents Market
Solvents
Fluid Neutralizing Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Global Xylenols Market
Solvents
GCC Acetonitrile Market