
 Global Coated Steel Market | 2026-2036
Global Coated Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coated Steel Market Foresight
Chinese integrated steelmakers is restructuring capacity allocation toward higher-margin coated products, shifting slab flows from commodity hot-rolled coil. ArcelorMittal S.A. sustains European leadership through proprietary coating formulations and automotive certification depth. POSCO Holdings anchors Asia-Pacific supply with dedicated galvalume lines serving renewable energy mounting systems. Tata Steel Limited leverages Indian domestic growth through coastal galvanizing facilities positioned near automotive clusters.
Coated steel comprises flat-rolled carbon steel substrates protected by metallic or organic layers, typically zinc at 60-275 g/m² coating weight or aluminum-zinc alloys at 55% aluminum content, applied through hot-dip, electrogalvanizing, or coil-coating processes to extend service life in corrosive environments. Galvanized steel dominates construction and appliance fabrication where cost-efficient sacrificial protection meets decades-long durability requirements. Organic polymer coatings, including epoxy and acrylic systems, command premium positioning in electrical equipment and furniture applications where aesthetic finish and chemical resistance justify higher unit economics. Zinc-aluminum alloy coatings represent the fastest-expanding metallic segment as solar tracker manufacturers specify extended corrosion warranties for desert and coastal installations.
EPA air quality standards and OSHA workplace exposure limits govern American coating line emissions and hexavalent chromium alternatives, while REACH and RoHS in Europe restrict hazardous substances in pretreatment chemistries and coil-coating formulations. China's MEE enforces dual carbon goals that elevate energy efficiency thresholds for continuous galvanizing lines, filtering smaller producers from qualification pools. Stakeholders must monitor regulatory divergence between jurisdictions to align coating chemistry roadmaps with diverging compliance baselines.
Market Dynamics
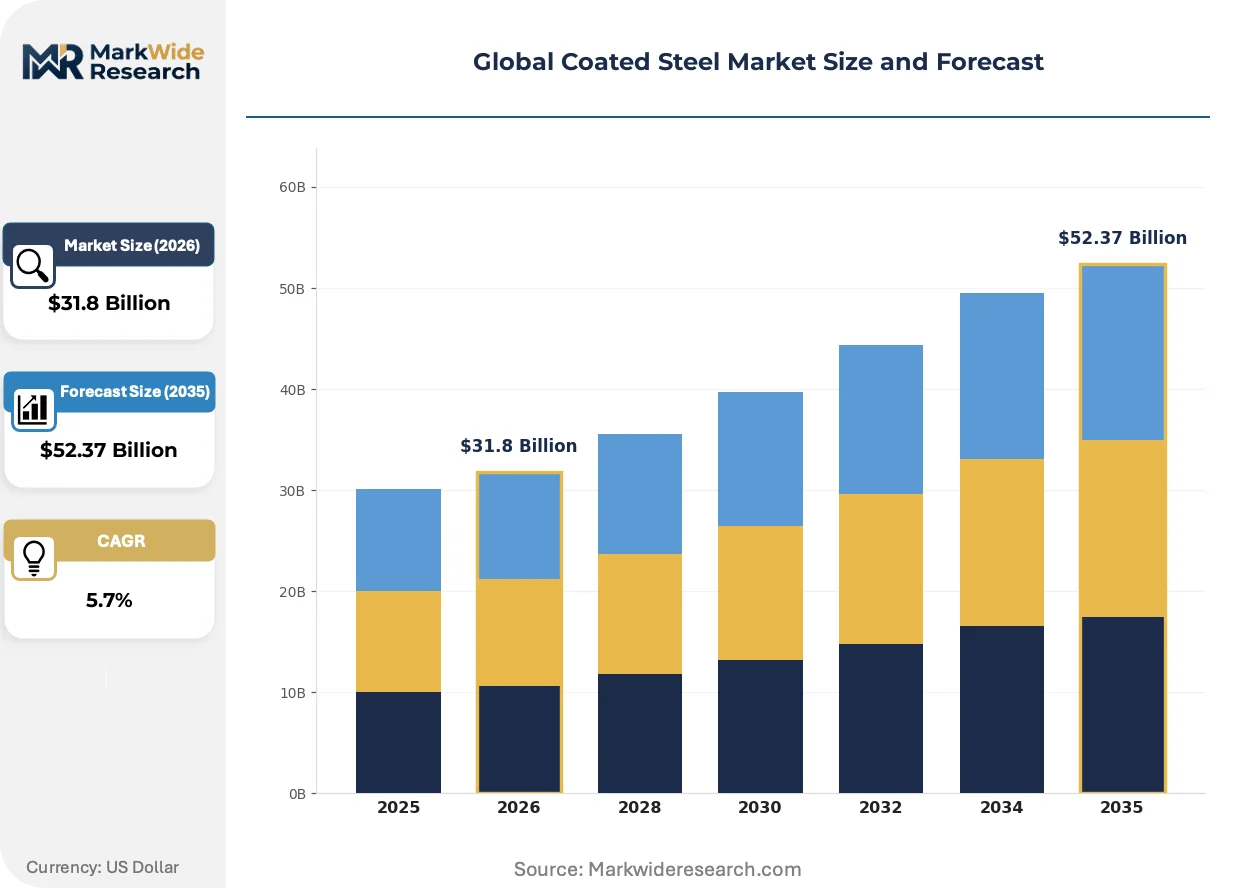
Chinese steelmakers are reallocating slab capacity from commodity hot-rolled coil toward higher-margin coated products, compressing supply availability for downstream processors while automotive and solar OEMs simultaneously expand corrosion-resistant procurement specifications.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany and Japan specify high-strength coated substrates to meet fleet emission targets, pulling volume from commodity grades.
- REACH coating compliance:ECHA restrictions on hexavalent chromium pretreatments force coating line upgrades across European suppliers, filtering qualified participants and consolidating procurement pools.
- Solar mounting corrosion warranties:Tracker manufacturers in India and Saudi Arabia specify 25-year aluminum-zinc alloy performance guarantees for desert and coastal installations, expanding premium coating demand.
Market Restraints
- Zinc price volatility:LME zinc fluctuations transmit directly to coating cost structures, squeezing galvanizing line margins and destabilizing contract pricing.
- Chinese supply concentration:Integrated steelmakers control 60% of Asian coated coil capacity, creating single-source dependency risks for Southeast Asian fabricators.
- Organic coating technical limits:Epoxy and acrylic systems face temperature degradation thresholds above 180°C, excluding them from automotive underhood applications.
Strategic Opportunities
- India domestic fabrication:Coastal galvanizing facilities near Pune and Chennai automotive clusters capture import substitution as OEMs localize supply chains.
- Green hydrogen infrastructure:Electrolyzer manufacturers specify super-duplex and specialized coated enclosures for corrosive operating environments.
- EU Green Deal steel procurement:Public infrastructure tenders increasingly mandate EPD-certified low-carbon coated products, creating premium tier qualification.
Industry Challenges
- Coating chemist skill scarcity:Formulation expertise for chromium-free pretreatment systems concentrates at European and Japanese technical centers, constraining global line expansion.
- Continuous galvanizing capex intensity:New 400,000-tonne annual capacity lines require $200-300 million investment with 4-5 year commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coated Steel Market |
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $52.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Galvanized Steel, Galvalume Steel, Electrogalvanized Steel, Zinc-Nickel Steel, Phosphated Steel Coating Material: Zinc, Aluminum, Zinc-Aluminum Alloy, Organic Polymer, Epoxy, Acrylic Application: Construction, Appliances, Packaging, Electrical Equipment, Furniture, Shipbuilding End User Industry: Renewable Energy, Heavy Equipment, Transportation Manufacturers, Consumer Goods, Electronics |
| Companies Covered | Thyssenkrupp AG, Salzgitter AG, ArcelorMittal S.A., United States Steel, Voestalpine AG, SSAB AB, Tata Steel Limited, POSCO Holdings, Nippon Steel & Sumitomo Metal Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coated Steel Market Shifts & Advancements
Coating chemistry and application technology are converging to extend service life while eliminating hazardous substances, compressing the gap between metallic protection and organic aesthetic performance.
Advanced aluminum-zinc-magnesium coating alloys are unifying corrosion resistance and cut-edge protection in a single layer, eliminating the need for separate post-treatment. Solar tracker manufacturers in Saudi Arabia and Australia specify these grades for 30-year desert warranties. The technology is unifying previously separate coating steps, reducing line complexity and capital requirements for new entrants.
China's MEE dual carbon enforcement elevates energy efficiency thresholds for continuous galvanizing lines, filtering smaller producers from qualification pools. GB standards revisions tighten coating weight tolerances and surface quality specifications. Indian automotive OEMs now require dual certification against both GB and BIS norms for imported substrate.
Automotive OEM procurement departments are consolidating supplier panels from 12-15 qualified mills to 4-6 strategic partners, compressing switching flexibility. Tier-1 stamping operations in Germany and Japan now mandate 5-year coating performance guarantees with penalty clauses. This concentration is most visible in premium electric vehicle platforms where battery enclosure corrosion protection carries liability exposure.
Global Coated Steel Market Segmentation
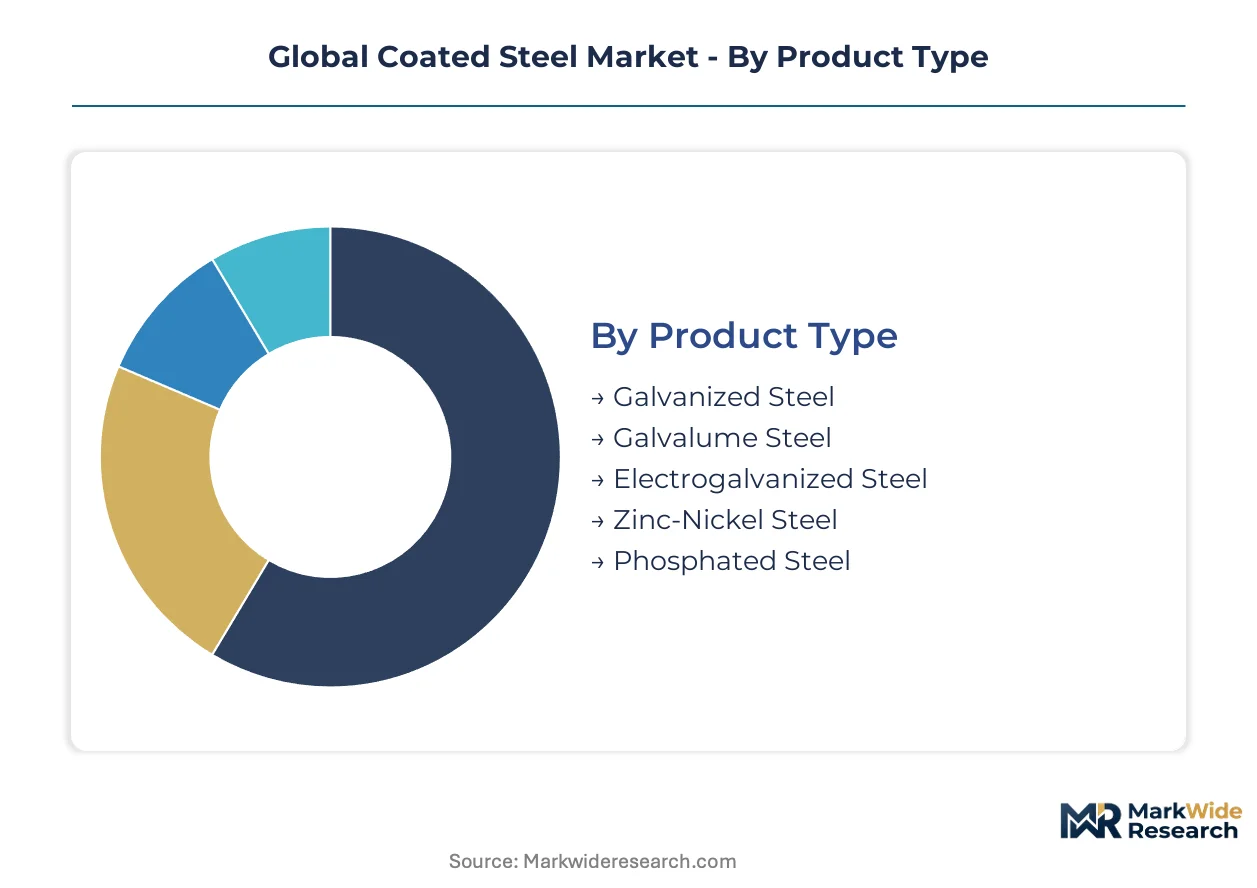
Coated steel procurement patterns diverge sharply across substrate chemistry, coating metallurgy, and end-use durability requirements. Buyers in construction prioritize sacrificial corrosion protection at lowest unit cost, while automotive and solar OEMs specify alloy formulations with decades-long performance guarantees.
Product Type:
Cost tier separates commodity construction buyers from premium-specification OEMs seeking extended corrosion warranties.
- Galvanized Steel:Zinc coating at 60-275 g/m² applied through hot-dip or electrogalvanizing processes delivers sacrificial protection for structural frameworks and appliance housings. Construction demand concentrates in India and Southeast Asia where urban infrastructure acceleration absorbs volumes from integrated steelmakers reallocating slab capacity.
- Galvalume Steel:Aluminum-zinc alloy at 55% aluminum content unifies barrier protection with cut-edge corrosion resistance for roofing and cladding applications. Solar tracker manufacturers in Saudi Arabia and Australia specify these grades for 30-year desert warranties, displacing pure zinc coatings in premium installations.
- Electrogalvanized Steel:Thin, uniform zinc layers suit automotive body panels requiring precise formability and paint adhesion.
- Zinc-Nickel Steel:Alloy coatings deliver enhanced weldability and corrosion resistance for underhood automotive components.
- Phosphated Steel:Chemical conversion coatings improve paint adhesion and corrosion resistance in appliance and furniture fabrication.
Volume sits with Galvanized Steel; growth tilts toward Galvalume Steel.
Coating Material:
Application temperature thresholds and aesthetic requirements determine material selection across metallic and organic systems.
- Zinc:Dominant metallic coating for cost-efficient sacrificial protection in construction and general fabrication. LME price volatility transmits directly to coating cost structures, squeezing galvanizing line margins.
- Aluminum:Pure aluminum coatings serve high-temperature exhaust and heat-resistant applications where zinc would alloy and degrade.
- Zinc-Aluminum Alloy:Fastest-expanding metallic segment as solar OEMs and coastal infrastructure projects specify extended corrosion warranties.
- Organic Polymer:Coil-coated systems combining corrosion resistance with color and finish customization for architectural and consumer goods.
- Epoxy:Chemical-resistant coatings for electrical equipment and industrial enclosures facing solvent exposure.
- Acrylic:UV-stable topcoats for outdoor furniture and signage applications requiring color retention.
Metallic coatings capture volume leadership; organic systems command premium positioning in aesthetic-critical segments.
Application:
Service life requirements and environmental exposure severity segment demand across infrastructure, consumer, and industrial end-uses.
- Construction:Roofing, cladding, and structural framing absorb the largest coated steel volumes globally. Southeast Asian urban infrastructure acceleration pulls supply from Chinese integrated mills restructuring toward higher-margin coated products.
- Appliances:Refrigerator panels, washing machine drums, and HVAC housings require formable substrates with cosmetic surface quality. REACH compliance and hexavalent chromium restrictions in Europe force coating line upgrades, filtering qualified suppliers.
- Packaging:Food and beverage cans utilize tin-free steel with organic coatings for corrosion and flavor protection.
- Electrical Equipment:Switchgear enclosures and transformer housings specify epoxy-coated grades for chemical resistance.
- Furniture:Office systems and outdoor furnishings utilize coil-coated steel for durability and design flexibility.
- Shipbuilding:Marine-grade coatings withstand saltwater immersion and atmospheric corrosion in hull and superstructure applications.
Construction maintains volume dominance; renewable energy infrastructure drives fastest expansion in corrosion-resistant specifications.
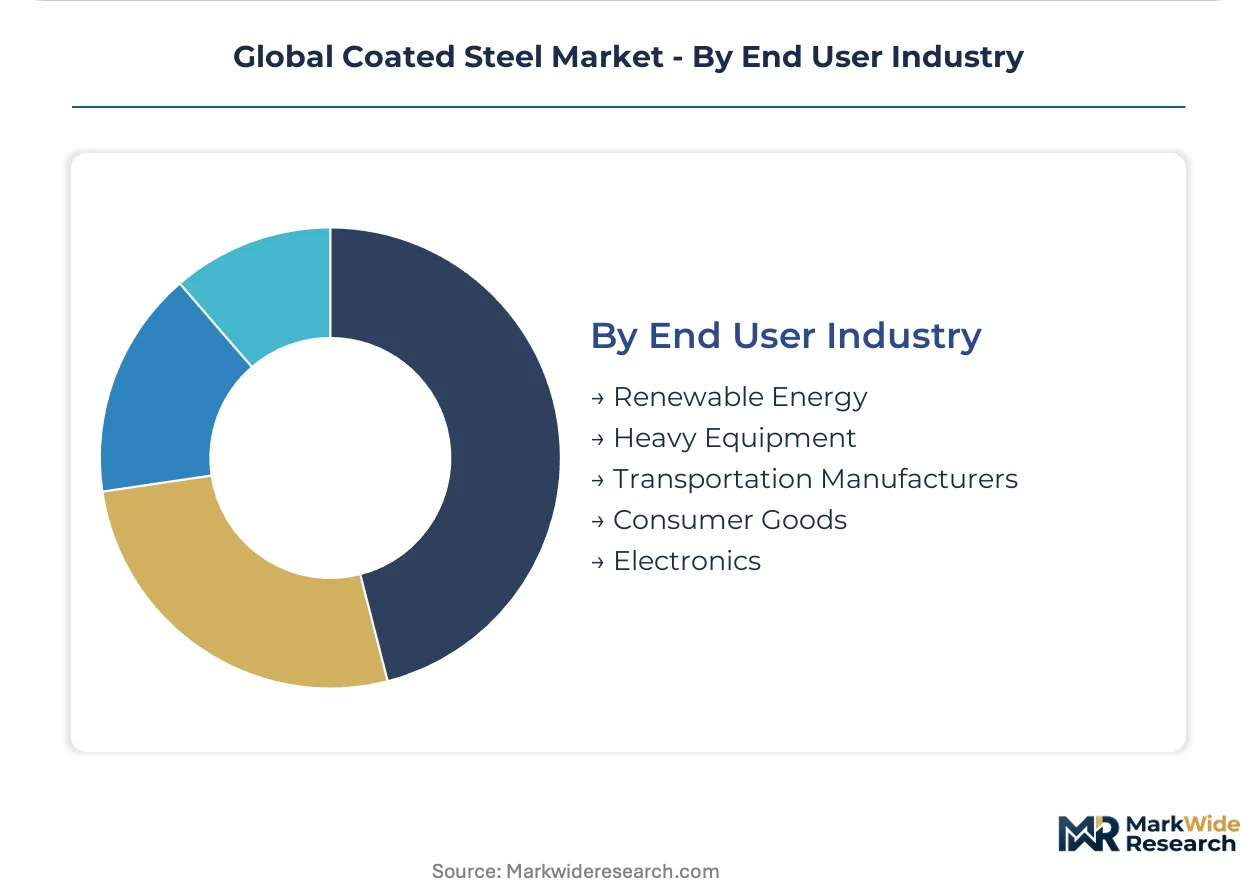
End User Industry:
Procurement consolidation and certification depth separate fragmented construction supply from concentrated automotive and energy OEM panels.
- Renewable Energy:Solar mounting manufacturers and wind tower fabricators specify aluminum-zinc alloys with multi-decade corrosion warranties. Indian and Saudi Arabian tracker producers expand procurement of desert-rated grades.
- Heavy Equipment:Construction machinery and agricultural equipment OEMs demand high-strength coated substrates for structural components facing abrasive environments.
- Transportation Manufacturers:Automotive OEMs in Germany and Japan consolidate supplier panels from 12-15 mills to 4-6 strategic partners, mandating 5-year coating performance guarantees with penalty clauses.
- Consumer Goods:Appliance and furniture producers prioritize unit economics and surface cosmetics over extended corrosion warranties.
- Electronics:Enclosure manufacturers for servers, telecommunications, and control systems specify epoxy and polymer-coated grades for chemical and electromagnetic protection.
Transportation Manufacturers concentrate procurement volume; Renewable Energy exhibits steepest expansion trajectory as solar deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits across Western Australia and Brazil anchor raw-material flows into coated steel production networks spanning Asia-Pacific, Europe, and North America. Regional demand patterns diverge sharply between mature automotive markets specifying high-strength substrates and emerging economies absorbing volumes for infrastructure buildout.
China
Automotive OEMs in Shanghai and Guangdong expand procurement of corrosion-resistant grades for electric vehicle platforms. MEE dual carbon enforcement elevates energy efficiency thresholds for continuous galvanizing lines, filtering smaller producers from qualification pools. Yangtze River Delta steelmakers restructure slab capacity toward higher-margin coated products, compressing commodity hot-rolled coil availability.
India
Solar tracker manufacturers and automotive fabricators in Pune and Chennai drive absorption of aluminum-zinc alloy grades with extended corrosion warranties. BIS norms tighten coating weight tolerances and surface quality specifications for imported substrate. Coastal galvanizing facilities near Tamil Nadu automotive clusters capture import substitution as OEMs localize supply chains.
Germany
Fleet emission targets pull volume toward high-strength coated substrates for automotive lightweighting mandates. ECHA REACH restrictions on hexavalent chromium pretreatments force coating line upgrades across European suppliers. Ruhr Valley and Bavarian steel processing centers consolidate supplier panels from 12-15 mills to 4-6 strategic partners with performance guarantees.
United States
Infrastructure spending and renewable energy deployment absorb galvanized volumes for structural frameworks and solar mounting systems. EPA air quality standards and OSHA workplace exposure limits govern coating line emissions and hexavalent chromium alternatives. Great Lakes industrial corridor fabricators face margin pressure from LME zinc volatility transmitting directly to coating cost structures.
Saudi Arabia
Desert-rated solar installations specify 25-30 year aluminum-zinc alloy performance guarantees for tracker manufacturers. SFDA and national standards authorities align with evolving Gulf technical regulations for construction materials. King Abdullah Economic City and Jubail industrial zones attract coated steel imports for mega-project construction and energy infrastructure.
Global Coated Steel Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty alloy formulations and regional certification depth. The vendor base stratifies between integrated steelmakers controlling captive substrate flows and independent coaters dependent on merchant coil supply. Three archetypes dominate: scale-driven integrated mills, technology-licensed regional processors, and niche specialists in super-premium organic coatings. Competitive moves concentrate on M&A-driven geographic expansion and backward integration into zinc refining to hedge raw material volatility.
Among European-based integrated producers, Thyssenkrupp AG and ArcelorMittal S.A. exemplify scale-driven archetypes with proprietary coating formulation depth. Salzgitter AG occupies a position within the German automotive supply tier, representing certification-heavy positioning against OEM performance guarantees. POSCO Holdings anchors Asia-Pacific supply architecture through dedicated galvalume capacity serving renewable energy mounting systems. Tata Steel Limited sits within the emerging market expansion archetype, leveraging coastal Indian galvanizing assets for domestic automotive cluster proximity.
| Leading Market Players |
|---|
| Thyssenkrupp AG |
| Salzgitter AG |
| ArcelorMittal S.A. |
| United States Steel |
| Voestalpine AG |
| SSAB AB |
| Tata Steel Limited |
| POSCO Holdings |
| Nippon Steel & Sumitomo Metal Corporation |
| Others |
Supply & Pricing Matrix
Captive zinc refining and substrate integration at Chinese integrated mills anchors supply positioning while compressing pricing power for independent coaters dependent on merchant coil. LME zinc volatility transmits directly to coating cost structures, squeezing margins for European and North American processors lacking backward integration into metal production.
Pricing Analysis
Warranty bundling separates premium alloy grades with 25-30 year corrosion guarantees from unbundled commodity zinc coatings sold on spot metal terms. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, coating weight tolerances, and automotive OEM qualification status. Cost compression in the standard tier intensifies because Chinese integrated mills reallocate slab capacity toward higher-margin coated products, flooding Southeast Asian construction markets. Construction fabricators in India and Indonesia exhibit highest price sensitivity; automotive OEMs in Germany and Japan demonstrate lowest sensitivity due to liability exposure on battery enclosure corrosion failures.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs in Germany and Japan force qualification of 4-6 strategic mill partners, filtering single-source dependency risks. Supply concentrates in China, India, and South Korea, with Chinese integrated steelmakers controlling captive substrate flows for 60% of Asian coated coil capacity. Raw material dependencies center on zinc ingot, aluminum alloy, and chromium-free pretreatment chemistries. Single-source vulnerability concentrates around Yangtze River Delta slab allocation decisions. Distribution runs through mill-direct contracts for automotive OEMs and merchant distributors serving fragmented construction fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum-zinc-magnesium alloy coatings are displacing pure zinc systems across solar and coastal infrastructure applications, compressing the technology transition window for legacy galvanizing investments.
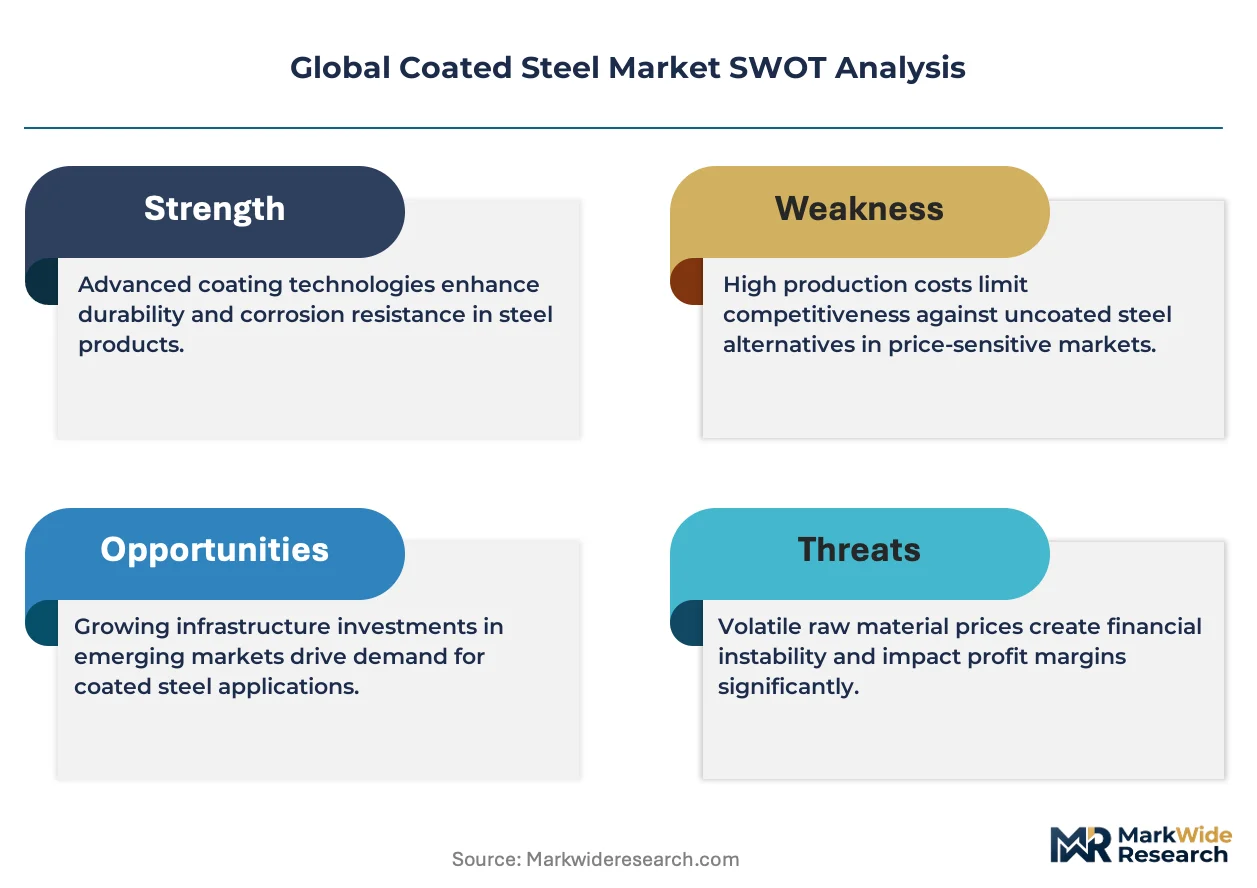
For Market Incumbents: Anticipate coating chemistry obsolescence risks from REACH-compliant chromium-free pretreatment systems by accelerating R&D partnerships with European technical centers. Consolidate supplier panel positions through captive zinc refining investments that hedge LME volatility exposure. Defensive capacity additions in Tamil Nadu and Gujarat capture Indian automotive cluster localization trends before import substitution closes the window. For New Entrants and Emerging Players: Capture white-space in Saudi Arabian and Australian desert-rated solar tracker supply by qualifying aluminum-zinc-magnesium grades for 30-year warranty specifications. Target coastal galvanizing facilities near Chennai and Pune automotive clusters where BIS certification barriers filter smaller competitors. Pursue technology licensing partnerships with Japanese coating formulation specialists to bypass European chromium-free expertise concentration. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale Indian coaters with BIS certification depth and coastal logistics positioning. Long-term viability favors assets with dual automotive and renewable energy OEM qualification rather than pure construction exposure. Watch for MEE enforcement intensity in China as the inflection signal determining whether integrated mill restructuring accelerates or reverses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Refining | Hedges LME volatility for European coaters facing margin compression from Chinese integrated mills. |
| Chromium-Free Pretreatment Line Upgrade | Qualifies European suppliers for REACH-compliant automotive procurement pools filtering legacy chemistries. |
| Coastal Galvanizing Facility Expansion | Captures Indian automotive OEM localization mandates near Chennai and Pune manufacturing clusters. |
| Aluminum-Zinc-Magnesium Alloy Certification | Unlocks 30-year warranty specifications from Saudi Arabian and Australian solar tracker manufacturers. |
| Dual GB-BIS Norm Qualification | Enables substrate imports into India as automotive OEMs tighten coating weight tolerance requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with coating line engineers, automotive OEM procurement directors, solar tracker manufacturing executives, and zinc alloy technical specialists. ECHA REACH documentation, MEE dual carbon enforcement notices, and BIS standard revision records provided regulatory trajectory inputs. SEC filings from integrated steelmakers and quarterly production disclosures from POSCO Holdings and Tata Steel Limited supplied capacity utilization benchmarks. Bottom-up coating line capacity modeling triangulated against top-down end-use demand estimates from construction, automotive, and renewable energy sector associations.
Data-stream reconciliation across customs import records, mill production schedules, and OEM procurement disclosures validated volume estimates across the analysis window. Segmentation modeling incorporated coating metallurgy, substrate chemistry, end-use durability requirements, and regional regulatory clusters. CAGRs derived from weighted average of historical capacity expansion trajectories and forward-looking OEM procurement specifications. Industry-specific forecast inputs included solar deployment pipeline data from Middle Eastern project developers and automotive lightweighting content-per-vehicle trends from German OEM platform disclosures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE enforcement intensity, REACH amendment timelines, and zinc price volatility regimes. Deviation in Chinese integrated mill restructuring pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Hull Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
High Temperature Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
North America Epoxy Powder Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Functional Coil Coating Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Global Battery Coating Market
Coatings
Coating Market
Coatings
France Protective Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Nigeria Protective Coatings Market