
 Recycled Lead Market | 2026-2036
Recycled Lead Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Lead Market Analysis
Skilled smelter technicians and metallurgical engineers is redrawing competitive boundaries across the recycled lead landscape. Gravita India leverages its integrated battery-to-lead recovery network across Gujarat and Rajasthan to dominate South Asian supply. Aqua Metals sustains differentiation through proprietary AquaRefining electrochemical technology that eliminates high-temperature smelting. Ecobat Technologies anchors European collection infrastructure with multi-country logistics spanning Germany, France, and the United Kingdom.
Recycled lead denotes secondary lead metal recovered from spent lead-acid batteries, industrial scrap, and end-of-life electronics through pyrometallurgical reduction or hydrometallurgical dissolution, typically yielding purity levels of 99.97% or higher for battery-grade remelting. Its primary commercial purpose centers on displacing primary mined lead in energy storage, radiation shielding, and alloy production where circular material flows reduce energy intensity by roughly two-thirds versus virgin extraction. Lead-acid batteries command the dominant product category given their standardized collection infrastructure and high metal recovery rates exceeding 95%. Battery manufacturers represent the most concentrated end-user pool, locking in multi-year offtake agreements that compress spot market liquidity for smaller foundries.
EPA hazardous waste rules under RCRA, the EU REACH chemical registry, and China's MEE emissions standards collectively shape facility permitting, cross-border scrap movements, and smelter technology investment thresholds across major producing jurisdictions. India's BIS certification and PLI scheme for advanced chemistry cells are simultaneously raising quality bars and redirecting capital toward cleaner secondary lead pathways. Stakeholders must monitor how regional carbon border adjustments and evolving battery extended producer responsibility frameworks reshape arbitrage economics between primary and recycled lead sourcing.
Market Dynamics
Battery manufacturers are consolidating secondary lead sourcing as primary mining faces tightening environmental constraints, redirecting capital toward closed-loop recovery infrastructure and electrochemical refining technologies that slash smelter emissions.
Growth Catalysts
- China's dual carbon goals:Beijing's MEE emissions standards are accelerating smelter retrofits and mandating closed-loop battery recycling, forcing domestic OEMs to secure certified secondary lead streams.
- Lead-acid battery replacement cycles:Automotive and stationary storage sectors are standardizing 3-5 year battery turnover protocols, generating predictable feedstock volumes for pyrometallurgical processors.
- Hydrometallurgical advancement:Electrochemical dissolution methods are achieving 99.99% purity without high-temperature reduction, attracting ESG-focused offtake agreements from radiation shielding manufacturers.
Market Restraints
- Feedstock price volatility:Spent battery collection costs fluctuate with lead LME pricing, compressing margins for independent smelters lacking long-term OEM contracts.
- Smelter concentration risk:Secondary lead capacity clusters in China's Henan and Shandong provinces, creating geographic vulnerability to regional power rationing or environmental shutdowns.
- Lithium-ion substitution:Stationary storage and light mobility segments are piloting lithium iron phosphate replacements, threatening long-term lead-acid demand in premium applications.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:New Delhi's production-linked incentives are channeling investment toward integrated battery recycling parks in Gujarat and Tamil Nadu.
- Carbon border adjustment mechanisms:The EU's CBAM is penalizing primary lead imports, creating arbitrage windows for certified secondary metal with verified Scope 3 emissions data.
- Industrial scrap digitization:Blockchain-tracked collection networks are emerging in Germany and France, enabling real-time inventory visibility for smelter procurement teams.
Industry Challenges
- Metallurgical technician scarcity:Pyrometallurgical and electrochemical operations face recruitment gaps for skilled furnace operators and process engineers, delaying capacity ramp-ups.
- BIS certification timelines:Indian secondary lead producers encounter 12-18 month approval cycles for battery-grade purity accreditation, blocking domestic market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Lead Market |
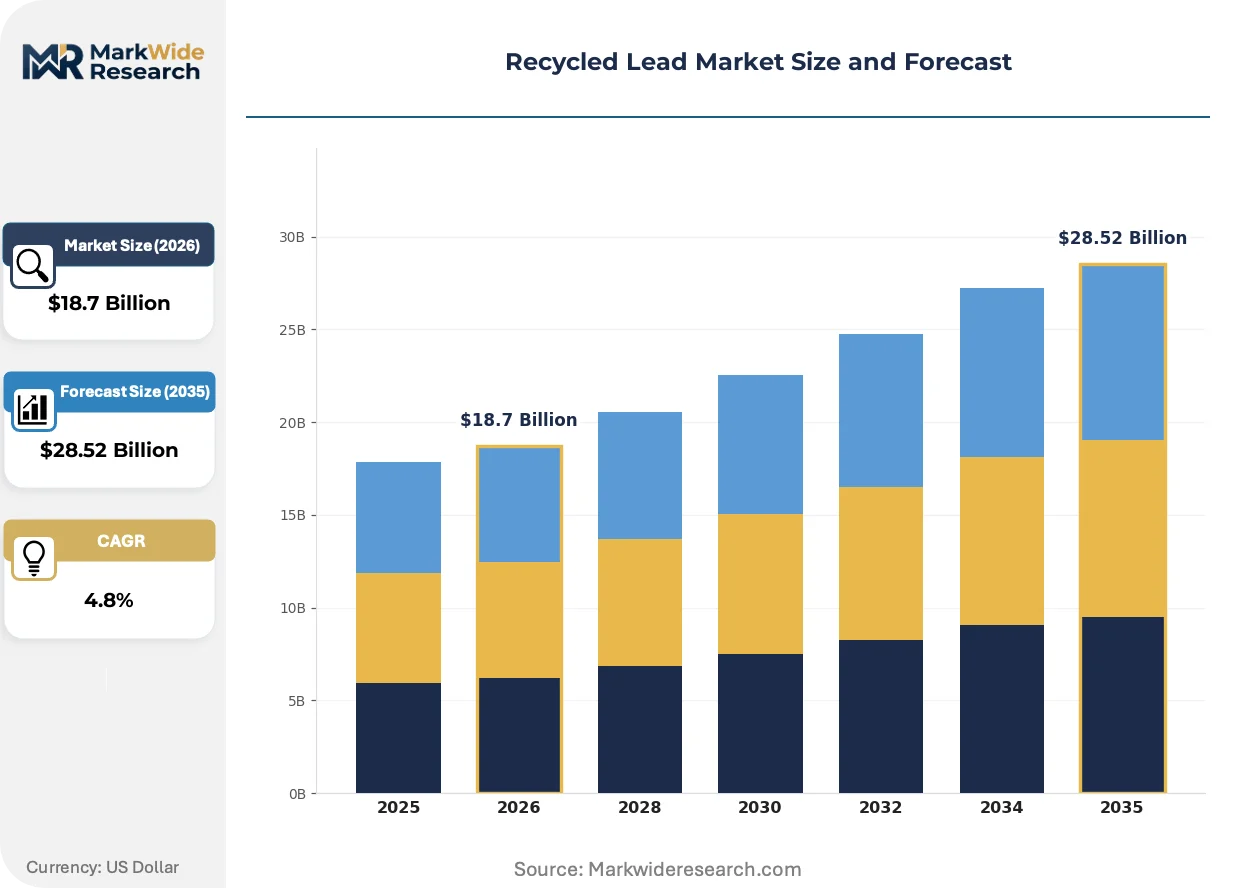
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-acid Batteries, Sheet Lead, Lead Pigments, Lead Alloys Application: Automotive, Construction, Electronics, Renewable Energy End User: Battery Manufacturers, Foundries, Construction Companies, Electronics Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retail, Exporters |
| Companies Covered | Gravita India, RSR Corporation, Aqua Metals, Terrapure Environmental, The Doe Run Company, Ecobat Technologies, Johnson Controls, EnerSys, Exide Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Lead Market Emerging Trajectories
Electrochemical refining and digital traceability systems are fragmenting traditional smelter economics, while regulatory carbon accounting forces transparency through every collection and remelting stage.
AquaRefining and analogous electrochemical technologies are bifurcating the recovery landscape. These systems dissolve lead compounds in aqueous solution at ambient temperatures, eliminating sulfur dioxide emissions entirely. European radiation shielding manufacturers are piloting offtake from electrochemical facilities to meet Scope 3 reduction targets. The technology is bifurcating capital allocation between legacy pyrometallurgical smelters and modular electrochemical plants with lower permitting barriers.
REACH chemical registry expansions and the EU Battery Regulation are mandating recycled content disclosures and due diligence across supply chains. Smelters must now document feedstock origins and emissions intensity to access European automotive OEM contracts. German and French battery producers are restructuring procurement to prioritize certified secondary lead with blockchain-verified chain-of-custody records.
Long-term offtake contracting is displacing spot market purchasing among tier-one battery manufacturers. OEMs are locking in 5-7 year supply agreements directly with integrated recyclers, squeezing independent foundries dependent on merchant metal sales. This concentration is most pronounced in India's automotive battery sector, where Exide and Amara Raja are securing captive secondary lead streams through equity stakes in recycling ventures.
Recycled Lead Market Segmentation
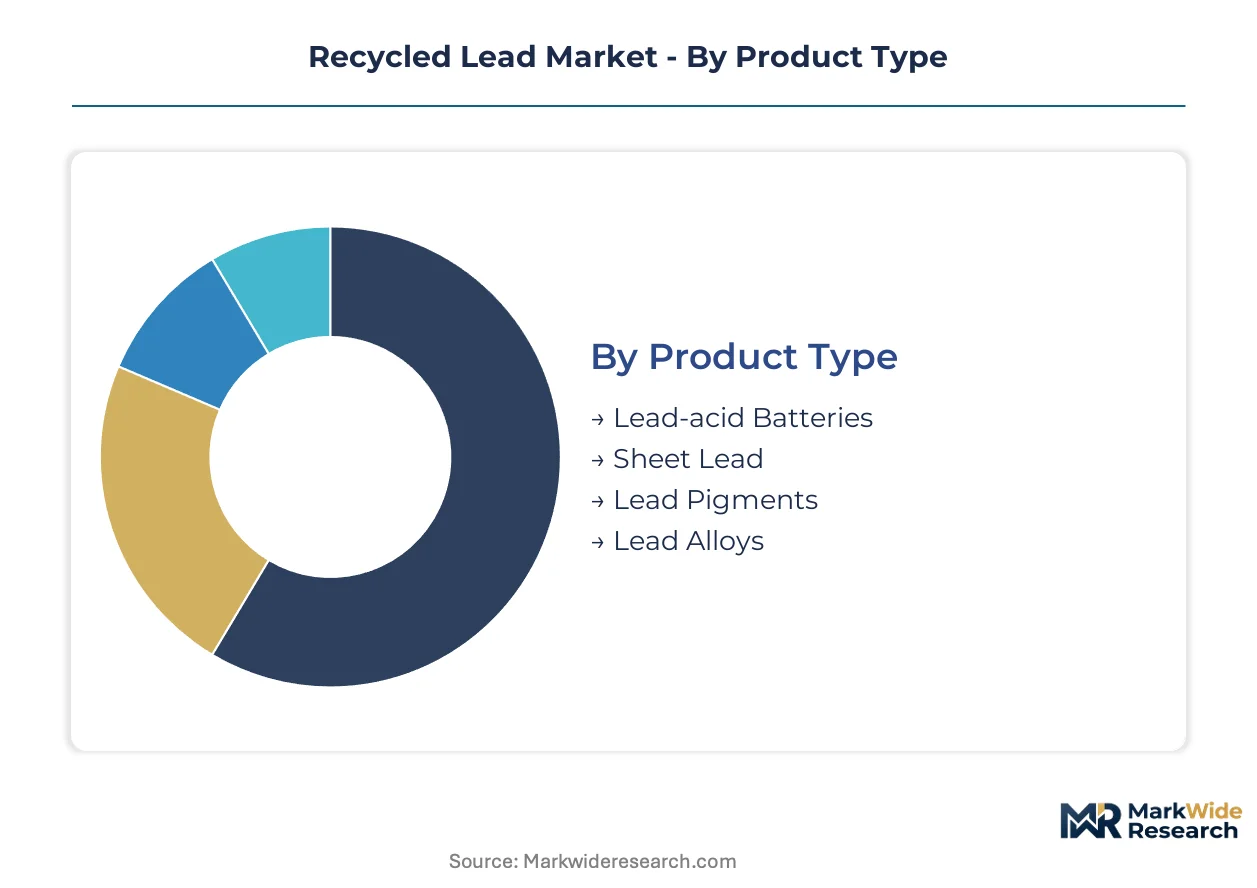
Segmentation in recycled lead markets reveals how feedstock quality tiers and end-use purity requirements reshape procurement economics. Battery-grade specifications dominate volume flows, while specialty alloys and radiation shielding command premium spreads based on metallurgical certification.
Product Type:
Lead-acid batteries anchor domestic supply chains across India and China, while sheet lead and specialty alloys travel longer export corridors to European radiation shielding and U.S. construction markets.
- Lead-acid Batteries:Spent automotive and industrial batteries yield 95% metal recovery through pyrometallurgical reduction. China's MEE emissions standards are retrofitting smelters in Henan and Shandong to process these feedstocks under closed-loop mandates.
- Sheet Lead:Rolled lead sheets serve radiation shielding in medical imaging and nuclear containment. European OEMs are sourcing certified secondary sheet lead with blockchain-tracked emissions data to meet EU Battery Regulation disclosure rules.
- Lead Pigments:Oxide compounds for industrial coatings and glass manufacturing.
- Lead Alloys:Antimony and calcium additions for battery grids and cable sheathing.
Lead-acid batteries command the established base. The steepest expansion runs through sheet lead for medical shielding applications.
Application:
Cost tier segmentation separates mass-market automotive replacement cycles from premium renewable energy storage and medical construction projects demanding traceable metallurgical certificates.
- Automotive:Starter battery replacement generates predictable 3-5 year feedstock cycles. India's automotive OEMs are locking 5-7 year offtake agreements with Gujarat-based recyclers to secure battery-grade lead under BIS certification timelines.
- Construction:Radiation shielding, roofing, and sound dampening drive architectural lead demand. German and French construction firms are restructuring procurement to prioritize secondary lead with REACH-compliant chain-of-custody documentation.
- Electronics:Solder and component shielding for consumer devices.
- Renewable Energy:Stationary storage for solar and wind installations.
Automotive absorbs the highest tonnage volumes. Renewable energy storage is climbing the fastest as grid-scale battery deployments accelerate.
End User:
Customer type concentration creates divergent contracting patterns: battery OEMs demand multi-year supply security while foundries and construction buyers operate on shorter spot-adjacent terms.
- Battery Manufacturers:Exide and Amara Raja in India are acquiring equity stakes in recycling ventures to secure captive secondary lead streams. These OEMs are displacing merchant market purchases with integrated recovery networks across Rajasthan and Tamil Nadu.
- Foundries:Casting operations for industrial components and ammunition.
- Construction Companies:Shielding contractors for healthcare and nuclear facilities.
- Electronics Manufacturers:Solder and component producers with lower volume, higher purity requirements.
Battery manufacturers lock in the longest contract tenors. Foundries are gaining share fastest as industrial casting demand recovers.
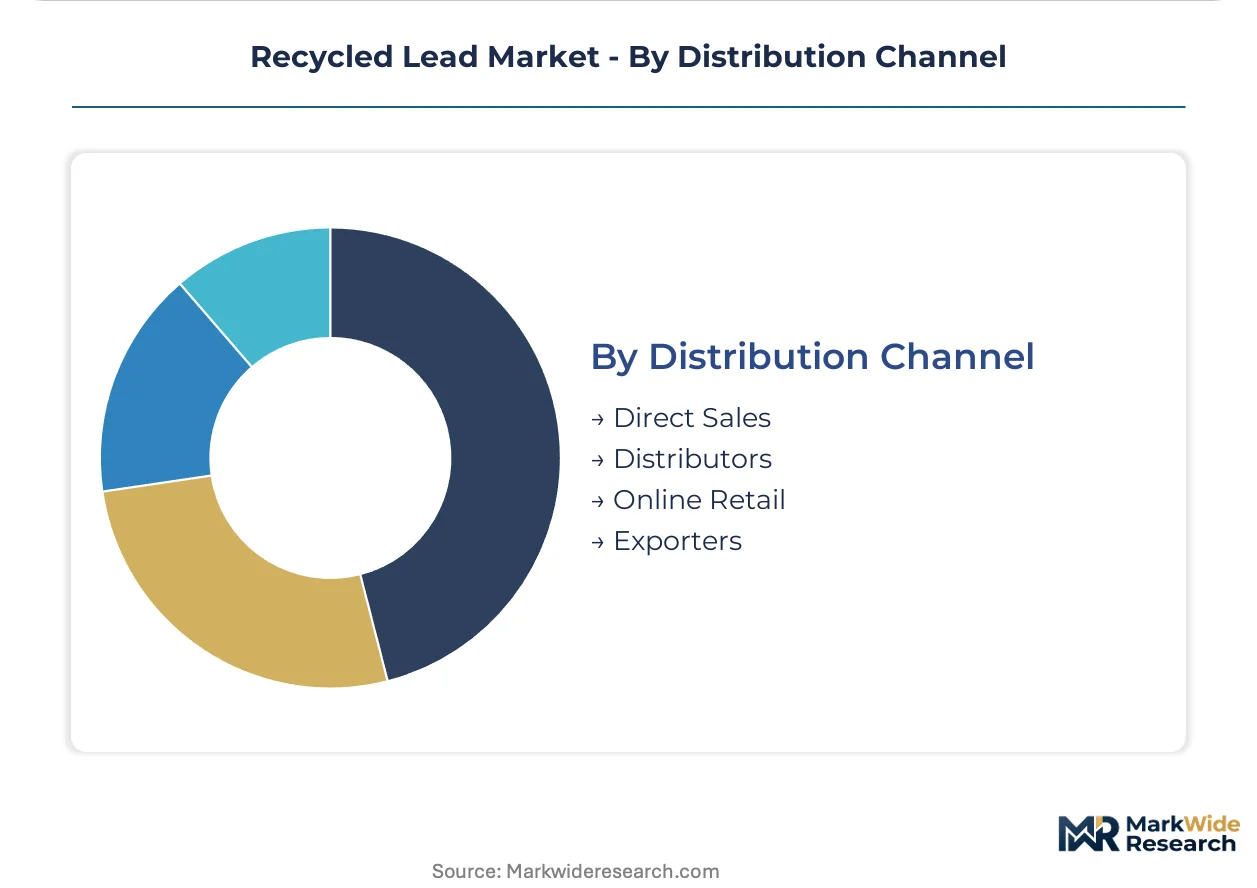
Distribution Channel:
Supply concentration determines channel economics: direct sales dominate high-volume battery OEM relationships, while distributors and exporters handle fragmented construction and electronics accounts.
- Direct Sales:Long-term offtake agreements between integrated recyclers and tier-one battery OEMs. These contracts compress spot market liquidity and squeeze independent foundries dependent on merchant metal.
- Distributors:Regional metal traders serving construction and foundry accounts with smaller lot sizes.
- Online Retail:Emerging platforms for specialty alloys and small-batch industrial buyers.
- Exporters:Cross-border flows of certified secondary lead to European radiation shielding manufacturers under CBAM-adjusted pricing.
Direct sales capture the contract value. Exporters are expanding most quickly as carbon border adjustments reshape arbitrage economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes recycled lead predominantly for domestic battery manufacturing, while India and European markets diverge toward export-oriented specialty alloys and radiation shielding with stricter carbon accounting requirements.
China
Henan and Shandong provinces host dense secondary smelter clusters serving domestic automotive OEMs. The Ministry of Ecology and Environment enforces dual carbon-aligned emissions caps that shutter non-compliant facilities. Tianjin's port infrastructure channels certified secondary lead toward Southeast Asian battery assemblers under cross-border e-waste protocols.
India
Gujarat and Rajasthan smelter networks process spent batteries from Exide and Amara Raja under captive offtake structures. The Bureau of Indian Standards mandates 12-18 month certification cycles for battery-grade purity accreditation. Tamil Nadu's emerging recycling parks attract PLI scheme capital for integrated battery-to-lead recovery.
Germany
Radiation shielding manufacturers in Bavaria and North Rhine-Westphalia source blockchain-tracked secondary sheet lead. The EU REACH chemical registry and Battery Regulation mandate recycled content disclosures across supply chains. Hamburg's logistics hub consolidates multi-country collection flows from France and the Benelux region.
United States
EPA hazardous waste rules under RCRA shape interstate scrap movements toward Missouri and Texas smelter concentrations. Stationary storage deployments in California and Texas generate predictable battery replacement feedstocks. The Inflation Reduction Act channels investment toward cleaner secondary lead pathways with verified emissions data.
Japan
Automotive battery OEMs in Kansai and Chubu regions maintain closed-loop collection contracts with designated recyclers. METI industrial standards enforce strict purity thresholds for remelted lead in precision electronics. Kyushu's smelter operators pilot hydrometallurgical methods to eliminate sulfur dioxide emissions from traditional reduction.
Recycled Lead Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in firms controlling collection-to-smelter networks. The market structure separates consolidated battery OEM recyclers from independent pyrometallurgical processors and emerging electrochemical technology developers. Strategic archetypes include vertically integrated battery manufacturers, regional smelter operators, and modular refining technology licensors. Competitive moves center on long-term offtake contracting and geographic expansion into underserved recycling jurisdictions.
Within the integrated battery OEM tier, Johnson Controls and Exide Technologies exemplify captive supply structures where recycling operations feed internal manufacturing requirements. Among independent specialists, Gravita India occupies a position representing South Asian pyrometallurgical scale, while Aqua Metals anchors the electrochemical technology vector with ambient-temperature refining systems. Ecobat Technologies sits within the European logistics-anchored archetype, consolidating multi-country collection infrastructure.
| Leading Market Players |
|---|
| Gravita India |
| RSR Corporation |
| Aqua Metals |
| Terrapure Environmental |
| The Doe Run Company |
| Ecobat Technologies |
| Johnson Controls |
| EnerSys |
| Exide Technologies |
| Others |
Supply Flow & Price Mechanics
Thirty-to-forty-five day lead times for battery-grade lead shipments from Henan and Shandong smelters compress margin buffers for independent foundries lacking captive collection networks. This inventory compression concentrates pricing power with integrated recyclers holding multi-year OEM contracts while spot-dependent operators absorb feedstock volatility.
Pricing Analysis
Long-term offtake contracts between tier-one battery manufacturers and integrated recyclers dominate transaction structures, displacing spot market liquidity. Price differentiation separates BIS-certified battery-grade streams from industrial-grade remelted lead based on purity thresholds and carbon intensity documentation. Pricing pressure stems from lithium-ion substitution threats in stationary storage applications. Battery OEMs exhibit lowest price sensitivity given captive supply security priorities, while independent foundries face acute margin compression from feedstock cost swings.
Supply Chain Analysis
Inventory cycles for spent battery collection run through informal aggregator networks in India and formal reverse-logistics systems in Germany and France. Supply concentration centers on China's Henan and Shandong provinces, India's Gujarat and Rajasthan clusters, and Germany's North Rhine-Westphalia processing hubs. Feedstock flows draw from automotive battery replacement cycles, industrial scrap generation, and end-of-life electronics recovery. Single-source vulnerability concentrates in China's smelter belt where MEE emissions enforcement triggers abrupt capacity curtailments. Distribution runs through direct sales channels for high-volume battery OEMs and regional distributors serving fragmented construction and foundry accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
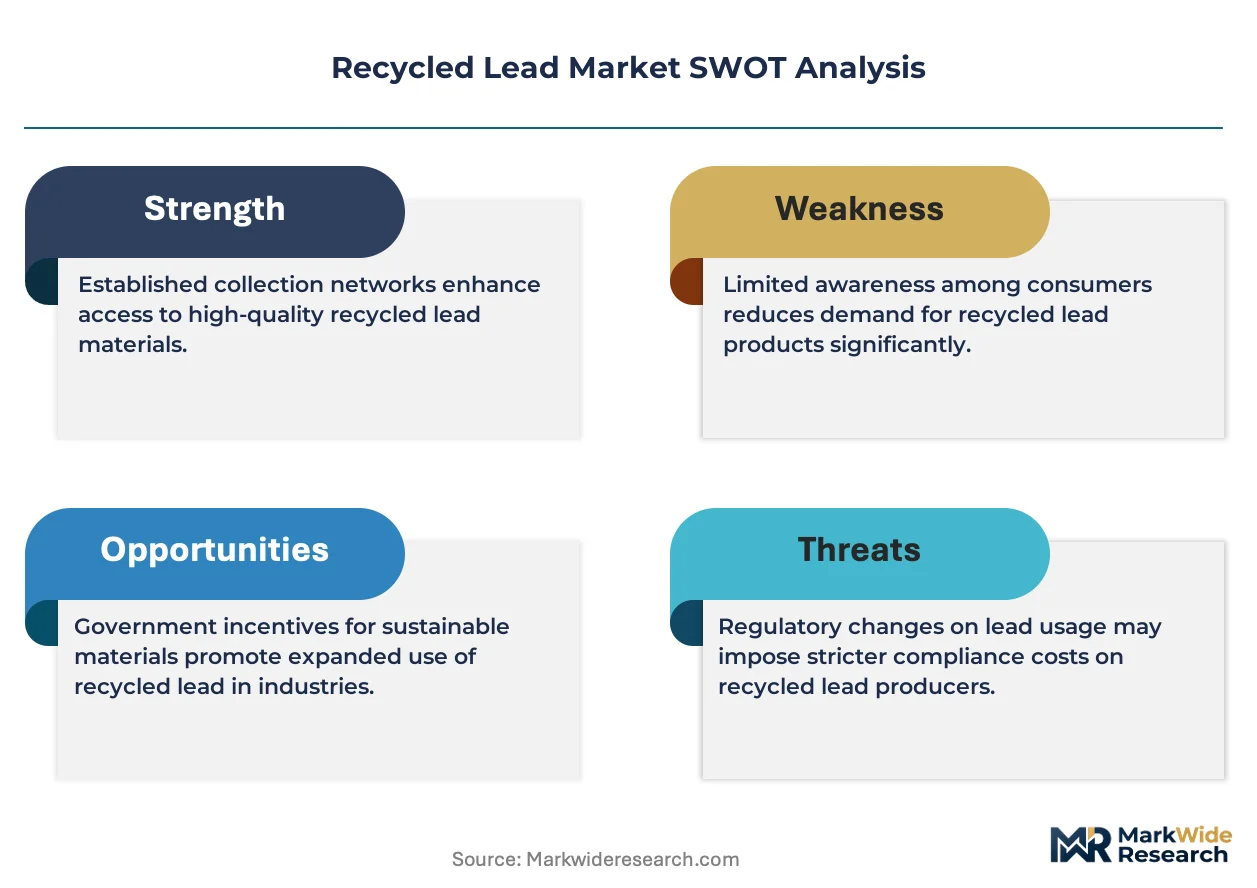
Recycled lead markets sit in early-cycle expansion as carbon border adjustments and closed-loop mandates accelerate secondary metal displacement of primary mining. India's PLI scheme for advanced chemistry cells channels capital toward integrated battery recycling parks with captive offtake structures.
For Market Incumbents: Consolidate collection infrastructure in underserved Indian states and invest in BIS certification pipelines to defend against emerging electrochemical competitors. Hydrometallurgical technology developers threaten pyrometallurgical margins through zero-emission refining claims. Backward integration into spent battery aggregation networks in Tamil Nadu and Rajasthan secures feedstock security. For New Entrants and Emerging Players: Lead with modular electrochemical refining systems targeting European radiation shielding manufacturers under CBAM-adjusted procurement rules. White-space opportunity concentrates in blockchain-tracked specialty alloy production for medical construction applications. Germany and France construction firms restructure procurement toward certified secondary lead with REACH-compliant chain-of-custody documentation. For Investors and Strategic Acquirers: Long-term, this sits as a circular infrastructure play because regulatory carbon accounting and extended producer responsibility frameworks embed secondary lead into battery supply chain economics. Acquisition targets include regional collection-network operators with multi-country logistics footprints. The signal to watch is lithium-ion penetration rates in automotive starter battery segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captive feedstock security insulates margins from LME price volatility for Indian smelters. |
| Hydrometallurgical Technology Licensing | AquaRefining systems eliminate sulfur dioxide emissions to access ESG-focused European offtake. |
| Carbon Certification Investment | Blockchain-tracked emissions data unlocks CBAM-adjusted premium pricing in German markets. |
| Multi-Country Logistics Expansion | Ecobat's France-Germany-Benelux network demonstrates scale advantages in European collection. |
| Long-term Supply Agreement Restructuring | Exide and Amara Raja's equity stakes in recycling ventures displace merchant metal dependence. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with smelter operations managers, battery OEM procurement leads, metallurgical engineers, and regulatory compliance officers. Secondary validation drew from MEE emissions filings, BIS certification registries, EU REACH chemical disclosures, and customs trade data for secondary lead movements. Bottom-up capacity modeling triangulated against top-down consumption estimates across automotive, construction, and electronics end-uses.
Across the analysis window, volume and value outputs segmented by product type, application tier, end-user category, and distribution channel. CAGRs were derived from regression-based demand modeling incorporating battery replacement cycle frequencies, smelter capacity expansion pipelines, and regulatory enforcement intensity indices. Industry-specific forecast inputs included lithium-ion substitution elasticities and carbon border adjustment implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of closed-loop mandates or accelerated lithium-ion cost parity would require recalibration. Forecasts reflect documented assumptions regarding MEE emissions standard adherence and PLI scheme capital deployment timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Selenium Mining Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Selenium Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Rare Earth Elements Recycling Market