
 Global Thin and Ultra-Thin Films Market | 2026-2036
Global Thin and Ultra-Thin Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thin and Ultra-Thin Films Market Foresight
Modular deposition tool configurations is realigning how semiconductor fabs and photovoltaic producers evaluate capital equipment purchases. Applied Materials leverages its integrated process equipment portfolio to anchor high-volume manufacturing contracts across Asia-Pacific fabs. First Solar competes through cadmium telluride thin-film specialization that sustains cost leadership in utility-scale solar installations. Lam Research Corporation differentiates via etch and deposition technology leadership in sub-7 nanometer logic device production.
Thin and ultra-thin films constitute engineered material layers ranging from several nanometers to few micrometers in thickness, fabricated through vacuum deposition, chemical synthesis, or epitaxial growth processes to deliver precise optical, electrical, thermal, or barrier properties. These films enable miniaturization, functional integration, and performance optimization across electronics, energy, and protective coating applications. Inorganic films dominate current revenue contribution due to established silicon oxide, nitride, and metal layer demand in semiconductor fabrication, while nanostructured films represent the fastest-expanding category driven by quantum dot, graphene, and two-dimensional material integration in next-generation sensors and photonic devices. Physical vapor deposition technology occupies the largest installed equipment base, though atomic layer deposition commands premium pricing for atomic-scale thickness control in advanced memory and logic stacks.
EPA regulations in the United States restrict perfluorinated compound emissions from chemical vapor deposition processes, compelling equipment upgrades and alternative precursor adoption. REACH substance authorization requirements in Europe filter market access for films containing restricted heavy metals or persistent organic pollutants. Japan's METI energy efficiency standards accelerate photovoltaic thin-film conversion efficiency targets that reshape R&D allocation across manufacturers. Stakeholders must monitor evolving precursor chemical regulations and deposition equipment energy intensity standards as dual levers that will determine competitive viability and geographic production economics.
Market Dynamics
Atomic layer deposition equipment is capturing capital allocation from legacy physical vapor deposition systems as semiconductor fabs prioritize atomic-scale thickness control for sub-7 nanometer logic and 3D NAND memory architectures.
Growth Catalysts
- Advanced node semiconductor fabrication:Logic and memory manufacturers are expanding atomic layer deposition capacity to enable vertical device scaling and reduced leakage currents in sub-5 nanometer transistors.
- REACH substance authorization frameworks:European electronics-grade material purity mandates are filtering market access and consolidating supplier bases toward qualified high-purity film producers.
- South Korean captive consumption:Samsung and SK Hynix drive concentrated demand for dielectric and conductive films in domestic memory and foundry operations.
Market Restraints
- Precursor chemical supply concentration:Specialty metal-organic precursor manufacturing concentrates among German and Japanese chemical suppliers, creating single-source vulnerability for hafnium and zirconium-based films.
- EPA perfluorinated compound emission caps:Chemical vapor deposition process restrictions in the United States compel costly abatement equipment retrofits or precursor formulation changes.
- Technical limitation in 2D material uniformity:Graphene and transition metal dichalcogenide films face wafer-scale thickness variation challenges that constrain integration into commercial photonic devices.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor and display fabrication are attracting deposition equipment investments and local film sourcing requirements.
- Perovskite photovoltaic stack integration:Tandem cell architectures combining silicon and perovskite active layers create demand for ultra-thin electron and hole transport films with precise band alignment.
- AI-driven process control convergence:Machine learning algorithms paired with in-situ metrology enable real-time thickness adjustment, reducing yield loss in high-mix production environments.
Industry Challenges
- Atomic-scale process engineering talent scarcity:The intersection of surface chemistry, vacuum physics, and semiconductor device physics requires specialized expertise that outpaces academic program output.
- Multi-year equipment qualification cycles:Automotive and medical device certifications for film reliability extend sales timelines and delay revenue recognition for new material introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thin and Ultra-Thin Films Market |
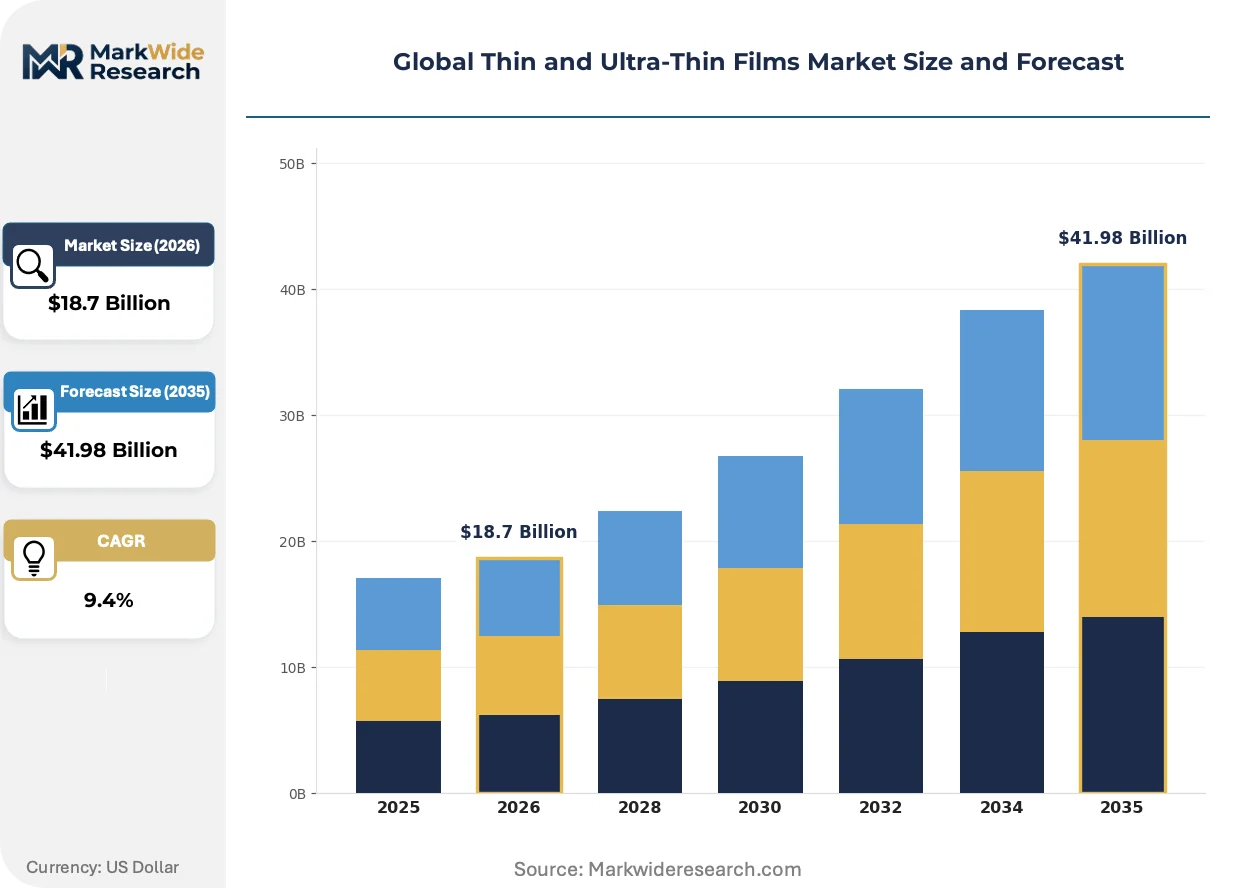
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Films, Inorganic Films, Composite Films, Nanostructured Films Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Atomic Layer Deposition, Spin Coating Application: Electronics, Packaging, Solar Cells, Coatings, Sensors End User Industry: Semiconductor Manufacturers, Aerospace Suppliers, Consumer Electronics Companies, Photovoltaic Firms |
| Companies Covered | Applied Materials, First Solar, Corning Incorporated, Kaneka Corporation, Ascent Solar Technologies, American Elements, Hanergy Thin Film Power Group, Lam Research Corporation, Tokyo Electron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thin and Ultra-Thin Films Market Shifts & Advancements
Process equipment architecture is shifting from standalone batch systems toward integrated cluster platforms that combine deposition, etch, and metrology modules within single vacuum envelopes.
Spatial atomic layer deposition is overtaking conventional temporal ALD in high-throughput manufacturing environments. This technology deposits films using continuous substrate motion through separated precursor zones rather than sequential pulsing. Solar panel and flexible electronics manufacturers in Taiwan and China are adopting spatial ALD for roll-to-roll barrier coatings. The structural consequence is compressing capital cost per unit area for atmospheric-sensitive encapsulation films.
Europe's F-Gas Regulation is tightening quotas on fluorinated greenhouse gases used in plasma-enhanced chemical vapor deposition cleaning processes. Equipment suppliers must qualify nitrogen trifluoride alternatives or abatement systems to maintain market access. Semiconductor fabs in Ireland and the Netherlands face accelerated retrofit timelines as phase-down schedules tighten through 2030.
Memory manufacturers are consolidating supplier relationships around qualified film vendors capable of supporting multi-generational technology roadmaps. Long-term supply agreements with Samsung and SK Hynix now span five-year horizons with embedded joint development clauses. This behavioral shift concentrates procurement leverage among South Korean device makers and locks out second-tier film suppliers lacking qualification history.
Global Thin and Ultra-Thin Films Market Segmentation
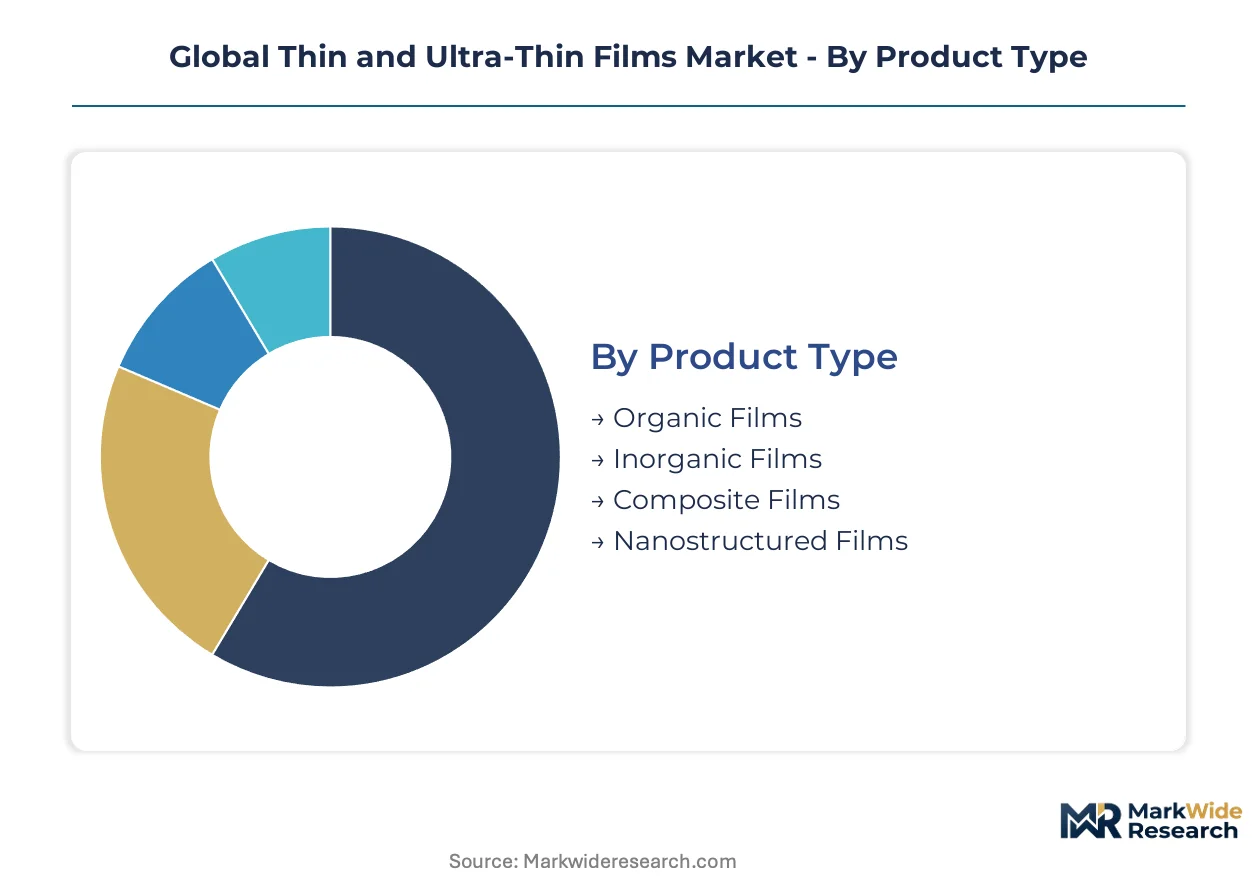
Thin and ultra-thin films serve divergent performance requirements across semiconductor fabrication, energy conversion, and protective barrier applications. Segmentation reveals how material composition, deposition precision, and end-use specifications determine procurement patterns and supplier qualification pathways.
Product Type:
Standardization dominates high-volume electronics-grade films while nanostructured variants command premium customization for emerging photonic and quantum applications.
- Inorganic Films:Silicon oxide, nitride, and metal layers form the backbone of semiconductor interconnects and gate dielectrics. Samsung and SK Hynix in South Korea drive concentrated procurement for memory cell stack fabrication where thickness uniformity specifications reach atomic precision.
- Nanostructured Films:Quantum dots, graphene, and two-dimensional materials enable next-generation sensor sensitivity and photonic device performance. Integration challenges around wafer-scale uniformity constrain commercial deployment despite superior optical and electrical properties.
- Organic Films:Polymer-based barriers serve flexible electronics encapsulation where mechanical compliance matters more than thermal tolerance.
- Composite Films:Hybrid organic-inorganic architectures balance barrier performance with processing flexibility in multilayer packaging stacks.
Most installed capacity flows through Inorganic Films. Expansion is steepest in Nanostructured Films.
Technology:
Capital intensity separates batch-processing heritage tools from continuous-throughput systems reshaping photovoltaic and flexible electronics manufacturing.
- Physical Vapor Deposition:Sputtering and evaporation systems constitute the largest installed base across semiconductor and optical coating facilities. Equipment from Applied Materials and ULVAC dominates high-volume manufacturing lines where mature process libraries reduce qualification risk.
- Atomic Layer Deposition:Sequential self-limiting surface reactions enable angstrom-level thickness control critical for sub-7 nanometer logic transistors and 3D NAND charge trap layers. South Korean memory fabs prioritize ALD capacity expansion for vertical scaling roadmaps.
- Chemical Vapor Deposition:Plasma-enhanced and thermal CVD systems serve dielectric and conductive film deposition where conformality requirements are less stringent than ALD-demanding applications.
- Spin Coating:Photoresist and sol-gel deposition for research-scale prototyping and display manufacturing where substrate size and material waste trade-offs favor simplicity over throughput.
Physical Vapor Deposition retains the largest equipment footprint. Atomic Layer Deposition is climbing the fastest as logic and memory nodes advance.
Application:
Performance specifications fragment across functional requirements from electrical insulation to optical transmission and hermetic sealing.
- Electronics:Interconnect metallization, gate dielectrics, and passivation layers in integrated circuits and printed circuit boards. Taiwan Semiconductor Manufacturing Company and Intel drive specifications for low-k dielectrics and copper diffusion barriers.
- Solar Cells:Anti-reflection coatings, transparent conductive oxides, and passivation layers in silicon and thin-film photovoltaic architectures. First Solar's cadmium telluride specialization sustains cost leadership in utility-scale installations.
- Packaging:Oxygen and moisture barrier films for food, pharmaceutical, and flexible electronics protection where aluminum oxide and silicon oxide layers extend product shelf life.
- Coatings:Wear-resistant and decorative films for automotive, aerospace, and consumer goods where hardness and optical properties determine selection.
- Sensors:Functional layers for gas detection, biosensing, and pressure measurement where surface area and selectivity engineering dominate design priorities.
Electronics absorbs the greatest film volume by value. Solar Cells is gaining share fastest as tandem perovskite-silicon architectures mature.
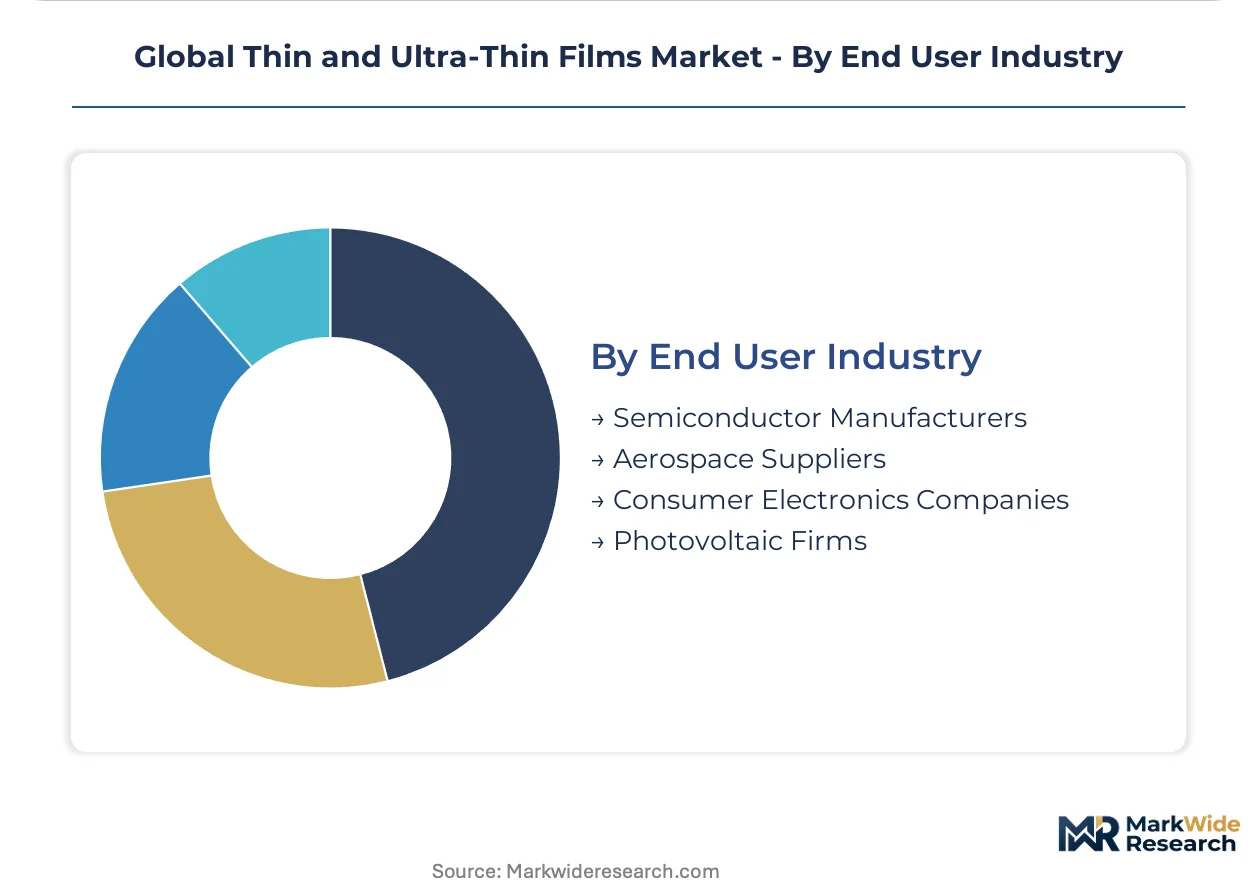
End User Industry:
Qualification timelines and technical collaboration intensity separate captive semiconductor fabrication from merchant supply relationships in aerospace and consumer electronics.
- Semiconductor Manufacturers:Integrated device foundries and memory producers operate captive deposition capacity with direct film supplier integration. Long-term agreements now span five-year horizons with embedded joint development clauses.
- Photovoltaic Firms:Cell and module producers balance conversion efficiency targets against manufacturing cost in commodity solar markets. India's PLI scheme subsidies are attracting deposition equipment investments and local film sourcing requirements.
- Consumer Electronics Companies:Display panel and device assembly operations procure barrier and conductive films through tiered supplier networks where cost and delivery reliability outweigh technical co-development.
- Aerospace Suppliers:Thermal barrier and erosion-resistant coatings for turbine blades and airframe components where AS9100 certification and multi-year reliability testing extend sales cycles.
Semiconductor Manufacturers command the largest procurement value. Photovoltaic Firms is expanding most quickly as capacity regionalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thin-film deposition technology originated in Bell Labs during the 1960s semiconductor revolution, with subsequent scaling concentrated in East Asian manufacturing clusters. Contemporary production geography reflects this lineage through specialized equipment hubs and captive fabrication networks.
United States
Silicon Valley and Austin semiconductor corridors drive demand for atomic layer deposition systems in sub-5 nanometer logic fabrication. EPA perfluorinated compound emission caps compel costly abatement retrofits at Intel and Applied Materials facilities. Arizona's emerging Phoenix-Tucson corridor attracts TSMC and Intel megafabs requiring localized precursor chemical supply chains.
South Korea
Samsung and SK Hynix operate the world's most concentrated captive thin-film consumption for 3D NAND and DRAM cell stacks. METI-aligned energy efficiency standards influence photovoltaic R&D allocation through technology transfer agreements. Pyeongtaek and Yongin host vertically integrated memory complexes where five-year supplier qualification cycles lock in preferred film vendors.
Japan
Tokyo Electron and ULVAC anchor equipment manufacturing in Kyoto-Osaka and Nagoya industrial zones. METI energy efficiency standards accelerate photovoltaic conversion efficiency targets that reshape manufacturer R&D budgets. Tsukuba science city concentrates national laboratory research on graphene and two-dimensional material uniformity solutions.
Germany
Merck KGaA and BASF dominate specialty metal-organic precursor supply for hafnium and zirconium-based films. REACH substance authorization frameworks filter market access toward qualified high-purity producers. Dresden's Silicon Saxony cluster hosts X-FAB and GlobalFoundries operations requiring localized precursor just-in-time delivery.
China
Yangtze Memory Technologies and SMIC expand domestic ALD capacity for memory and logic independence. MIIT dual carbon goals pressure deposition equipment energy intensity standards through 2030. Shanghai's Zhangjiang Hi-Tech Park concentrates SME equipment development and joint ventures with Tokyo Electron.
Global Thin and Ultra-Thin Films Market Competitive Landscape
Premium-margin players sit above commodity-margin players across equipment precision tiers and material purity grades. The vendor base stratifies between integrated process equipment conglomerates, specialized deposition tool builders, and captive chemical precursor suppliers. Three archetypes dominate: equipment-integrated platforms spanning deposition-etch-metrology clusters, material-pure specialists commanding qualification premiums, and geographic-captive producers serving regional fab networks. Competitive moves center on five-year joint development agreements with memory manufacturers and spatial ALD technology licensing to photovoltaic roll-to-roll producers.
Within the integrated equipment tier, Applied Materials and Lam Research Corporation occupy positions anchoring high-volume semiconductor manufacturing contracts. Tokyo Electron exemplifies the precision-tool archetype through its dominance in batch-processing heritage systems. First Solar represents the specialization vector through cadmium telluride thin-film cost leadership in utility-scale solar installations.
| Leading Market Players |
|---|
| Applied Materials |
| First Solar |
| Corning Incorporated |
| Kaneka Corporation |
| Ascent Solar Technologies |
| American Elements |
| Hanergy Thin Film Power Group |
| Lam Research Corporation |
| Tokyo Electron |
| Others |
Supply & Pricing Matrix
Captive precursor production at Merck KGaA and BASF anchors both supply security and premium pricing power for hafnium and zirconium-based films in European semiconductor corridors. This backward integration into specialty metal-organic chemistry insulates qualified suppliers from spot volatility while locking out second-tier competitors lacking REACH authorization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates qualified high-purity film vendors from merchant suppliers and spot-market traders. Premium tiers command certification-grade margins through embedded joint development clauses with Samsung and SK Hynix, while economy tiers face cost compression from China's domestic ALD capacity buildout. Price differentiation hinges on atomic-scale thickness control precision and REACH substance authorization status. Memory manufacturers exhibit lowest price sensitivity due to five-year qualification cycles, whereas photovoltaic firms in India negotiate aggressively under PLI scheme cost benchmarks.
Supply Chain Analysis
Regional distribution centers in Dresden, Pyeongtaek, and Phoenix-Tucson operate hub-and-spoke patterns for just-in-time precursor delivery to captive fab networks. Supply concentrates in Germany, South Korea, and the United States for equipment and qualified chemicals, while China expands domestic SME tool production through Zhangjiang joint ventures. Raw material dependencies rest on hafnium and zirconium metal-organic precursors, fluorinated cleaning gases, and high-purity carrier substrates. Single-source vulnerability from German and Japanese chemical suppliers creates structural risk for memory manufacturers. Distribution runs through long-term offtake agreements with embedded volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA perfluorinated compound caps in the United States compress margins faster than MIIT energy intensity standards in China, redirecting capacity expansion toward Asia-Pacific corridors.
For Market Incumbents: To counter spatial ALD technology displacement in photovoltaic barrier coatings, Applied Materials and Lam Research Corporation should anchor high-volume manufacturing contracts through integrated cluster platform upgrades. Backward integration into precursor chemical production insulates margin position from German and Japanese supply concentration.
For New Entrants and Emerging Players: Capture India's PLI scheme subsidies for localized deposition equipment investments and qualified film sourcing requirements. The most penetrable white-space sits in perovskite tandem cell electron transport layers where band alignment engineering demands outpace incumbent qualification speed. Go-to-market leverage through joint development partnerships with domestic photovoltaic module producers accelerates certification timelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where five-year supplier qualification cycles and REACH authorization barriers strand second-tier film vendors without Samsung or SK Hynix procurement history. Long-term viability favors equipment-integrated platforms with captive chemical relationships. Watch spatial ALD licensing velocity to photovoltaic roll-to-roll producers as inflection indicator for barrier coating margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Spatial ALD Technology Licensing | Compresses capital cost per unit area for Taiwan and China solar manufacturers. |
| Backward Integration into Precursor Chemistry | Merck KGaA and BASF secure REACH-compliant supply chains against regulatory filtration. |
| Integrated Cluster Platform Deployment | Applied Materials anchors sub-7 nanometer logic contracts through single-vacuum architectures. |
| Long-term Supply Agreement Restructuring | Five-year horizons with Samsung and SK Hynix lock out unqualified competitors. |
| Perovskite Tandem Cell Film Qualification | First Solar and Hanergy capture utility-scale solar efficiency gains through band alignment engineering. |
Research Methodology
Bottom-up electronics and photovoltaic modeling reconciled against top-down deposition equipment and precursor chemical tracking forms the analytical core of this study. Primary interviews with semiconductor fab process engineers, photovoltaic cell manufacturing directors, deposition equipment procurement leads, and specialty chemical regulatory affairs managers combined with secondary validation from SEC 10-K filings, MIIT capacity disclosure databases, REACH substance authorization registries, and customs trade flow records. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Historical trendline analysis of installed equipment base expansion and captive consumption patterns across memory and logic fabrication established baseline growth trajectories. The projection framework models product type, technology, application, and end-user industry dimensions alongside regional regulatory cluster differentiation. CAGRs derive from equipment shipment forecasts, fab capacity buildout announcements, and precursor chemical volume disclosures. Industry-specific inputs include atomic layer deposition tool utilization rates and perovskite photovoltaic conversion efficiency roadmaps.
EPA emission cap revisions, REACH substance list expansions, and MIIT dual carbon goal accelerations are the dominant revision risks for thin and ultra-thin film demand projections. Forecasts reflect documented assumptions regarding qualification cycle duration and equipment energy intensity standards. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Functional Acids Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Global Smart Material Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Smart Card Materials Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Functional Composites Market