
 Testing Inspection and Certification TIC for the Metals and Minerals Market | 2026-2036
Testing Inspection and Certification TIC for the Metals and Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Testing Inspection and Certification TIC for the Metals and Minerals Market Insights
The capital-intensity divergence between full-service laboratories and specialized niche operators is redrawing competitive boundaries in metals and minerals TIC. SGS SA leverages its integrated global network to dominate bulk commodity inspection at extraction points. Bureau Veritas SA anchors its position through deep relationships with European steel producers requiring continuous casting verification. Intertek Group plc differentiates via proprietary digital platforms that streamline certificate management for mid-tier alloy distributors.
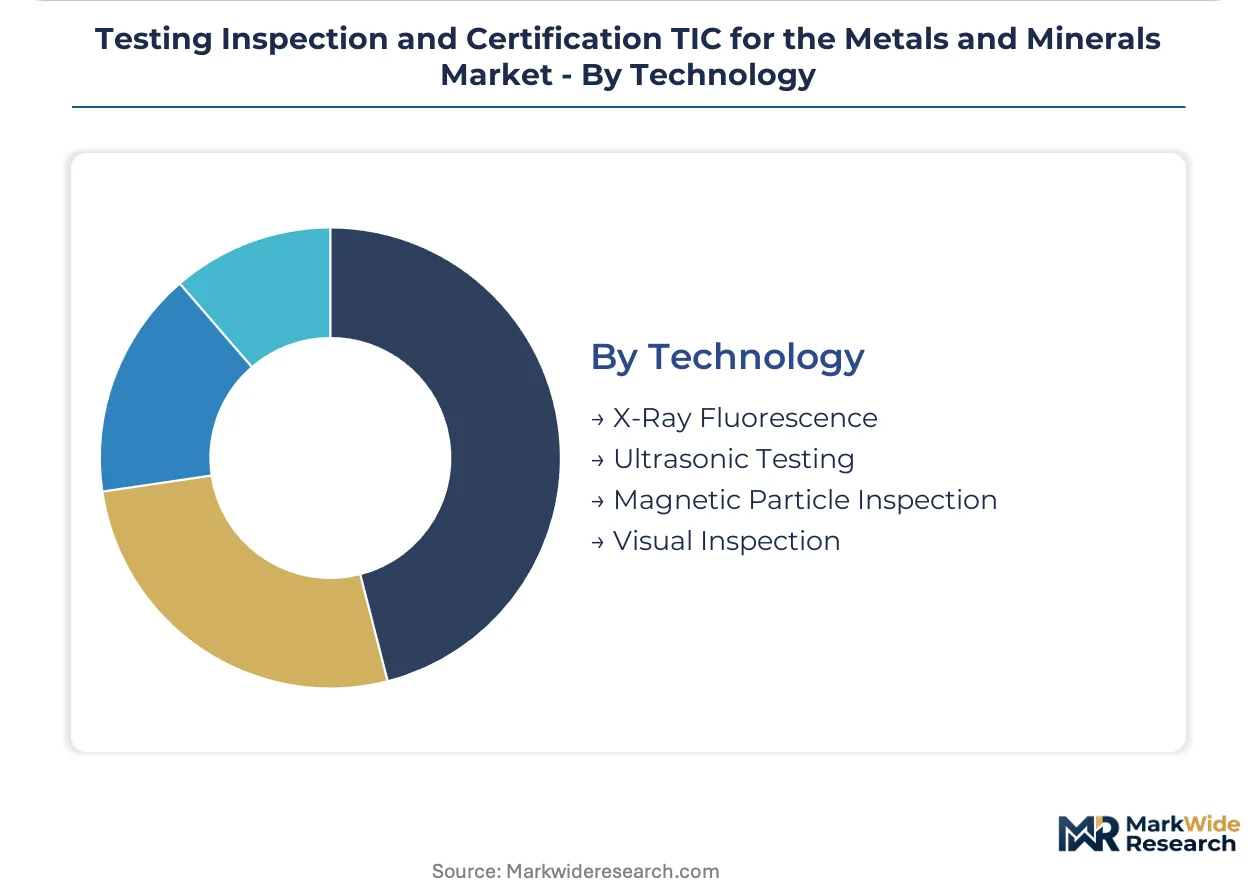
Testing Inspection and Certification for metals and minerals encompasses analytical verification of elemental composition, mechanical properties, and structural integrity across ferrous and non-ferrous supply chains, employing techniques such as X-ray fluorescence spectrometry to detect trace contaminants below 10 parts per million. The primary purpose is to ensure material conformance to ASTM, ISO, or client-specific specifications before downstream fabrication or export clearance. Service type segmentation shows testing and inspection commanding the majority of revenue due to recurring volume-based contracts at mine sites and ports, while certification services extract premium margins from specialized alloy grades and defense-aerospace material qualifications. Technology segmentation reveals X-ray fluorescence and ultrasonic testing leading adoption curves as non-destructive methods replace slower wet chemistry protocols, with magnetic particle inspection retaining strongholds in pipeline and pressure vessel weld verification.
REACH in Europe, GB standards administered by SAMR in China, and ASTM International specifications collectively dictate elemental disclosure thresholds and test method acceptability across cross-border metal trade. These frameworks compel smelters and traders to maintain accredited laboratory partnerships or risk customs detention and downstream liability. Stakeholders must monitor the divergence between regional digital certification platforms and legacy paper-based systems as a determinant of future market access friction.
Market Dynamics
The aerospace sector's third-party metallurgical verification mandates are compressing certificate turnaround times while expanding analytical scope requirements for trace element detection below 10 parts per million.
Growth Catalysts
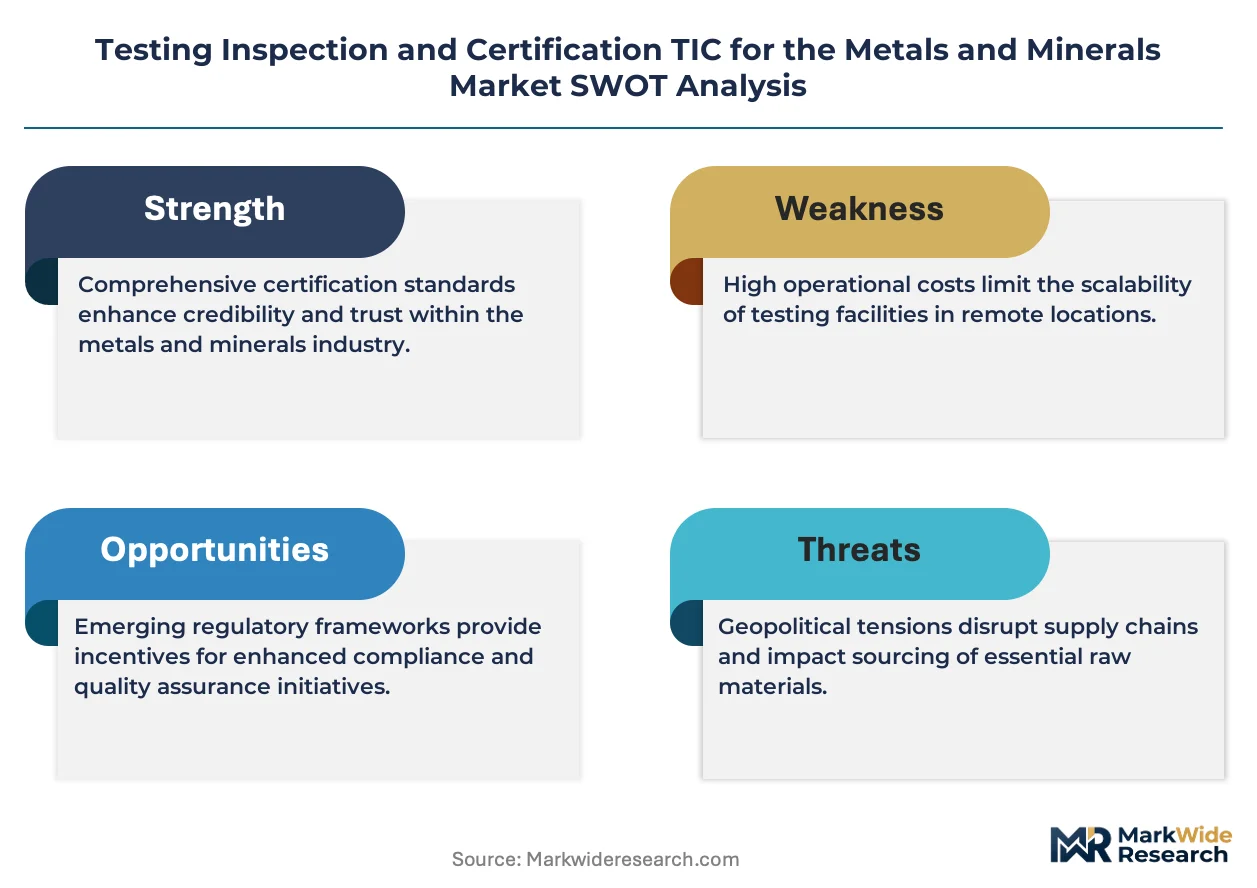
- REACH material traceability:ECHA disclosure thresholds for SVHCs in metal alloys compel smelters to maintain accredited laboratory partnerships across ferrous supply chains.
- X-ray fluorescence spectrometry:Non-destructive elemental analysis at extraction points eliminates wet chemistry delays, accelerating port clearance timelines for bulk mineral shipments.
- Ruhr-Bavaria testing corridor:Germany's concentrated industrial laboratory infrastructure supports continuous casting verification for European steel producers requiring ISO 17025 accreditation.
Market Restraints
- Helium supply volatility:Inductively coupled plasma mass spectrometry depends on helium carrier gas, with price spikes constraining high-precision trace analysis capacity.
- Accreditation concentration:ISO 17025 certification bodies cluster in Western Europe and North America, creating access bottlenecks for African and Central Asian mining operations.
- Portable analyzer substitution:Handheld XRF devices enable in-situ screening at mine sites, eroding volume-based contracts for central laboratory wet chemistry services.
Strategic Opportunities
- EU AI Act compliance:Automated material classification systems for high-risk applications create demand for algorithmic audit and training dataset verification services.
- India's PLI scheme:Specialty steel and aluminum manufacturing incentives generate new accredited testing requirements for automotive and defense alloy grades.
- Blockchain-anchored certificates:Immutable traceability records from smelter to fabricator address downstream liability concerns in cross-border titanium and nickel trade.
Industry Challenges
- Spectroscopy technician scarcity:ICP-MS and GD-MS operation requires specialized training pipelines that lag behind instrument deployment rates in emerging extraction regions.
- Legacy LIMS integration:Laboratory information management systems at established operators resist API connectivity with customer ERP platforms, delaying automated certificate delivery.
- Defense-aerospace qualification timelines:Nadcap accreditation for specialty alloys extends 18-24 months, locking out mid-tier laboratories from premium-margin contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testing Inspection and Certification TIC for the Metals and Minerals Market |
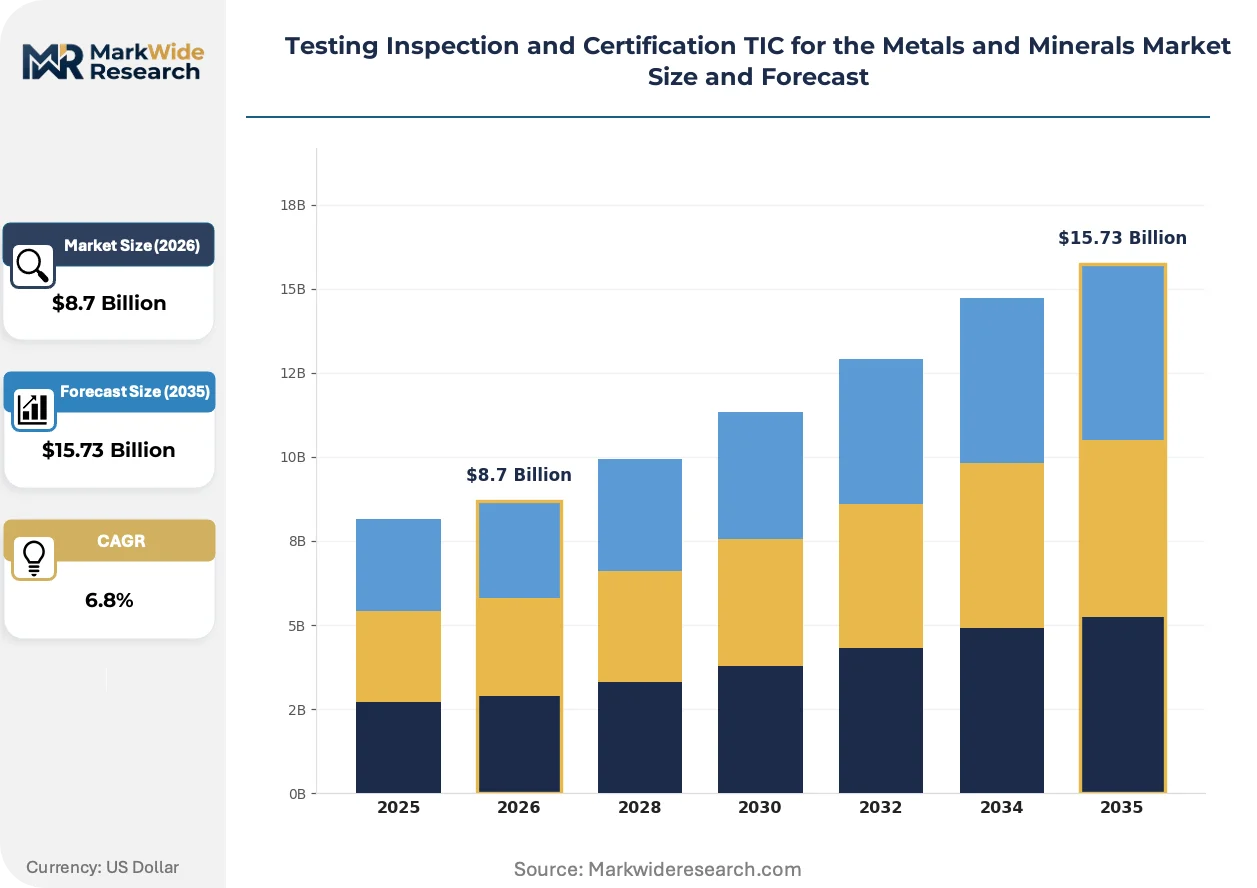
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing, Inspection, Certification, Compliance Material Type: Metals, Alloys, Minerals, Composites End User: Mining Companies, OEMs, Distributors, Contractors Technology: X-Ray Fluorescence, Ultrasonic Testing, Magnetic Particle Inspection, Visual Inspection |
| Companies Covered | SGS SA, Bureau Veritas SA, Intertek Group plc, TÜV SÜD AG, TÜV Rheinland AG, ALS Limited, Element Materials Technology Group Ltd, Applus+ Servicios Tecnológicos SL, CCIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testing Inspection and Certification TIC for the Metals and Minerals Market Trends and Innovations
Digital certification platforms and automated analytical instrumentation are compressing the traditional laboratory-to-customer workflow while fragmenting service delivery models across the value chain.
Artificial intelligence-assisted spectral interpretation is decomposing the historical bottleneck of trained analyst review for X-ray fluorescence and optical emission spectroscopy results. Tier-one aluminum smelters in the Persian Gulf region deploy machine learning models for real-time alloy grade classification. This compression of analytical judgment into algorithmic decision-making threatens the premium pricing of specialist metallurgist interpretation services.
REACH authorization requirements for chromium VI compounds in surface treatment processes are tightening disclosure obligations for stainless steel and galvanized product importers into the European Economic Area. Downstream fabricators now demand batch-level test reports documenting hexavalent chromium content below detection limits. German automotive stamping operations have responded by mandating supplier laboratory accreditation to ISO/IEC 17025 with specific scope for EN 1676 aluminum alloy verification.
Consolidated procurement of testing services through integrated supply chain platforms is displacing bilateral laboratory contracts for mid-tier alloy distributors. Digital marketplaces connecting verified laboratories with spot-testing requirements are capturing volume from traditional inspection houses in Singapore and Rotterdam hub markets. This channel disintermediation is most pronounced among traders of copper cathode and zinc concentrate seeking rapid certificate turnaround for arbitrage windows.
Testing Inspection and Certification TIC for the Metals and Minerals Market Segmentation
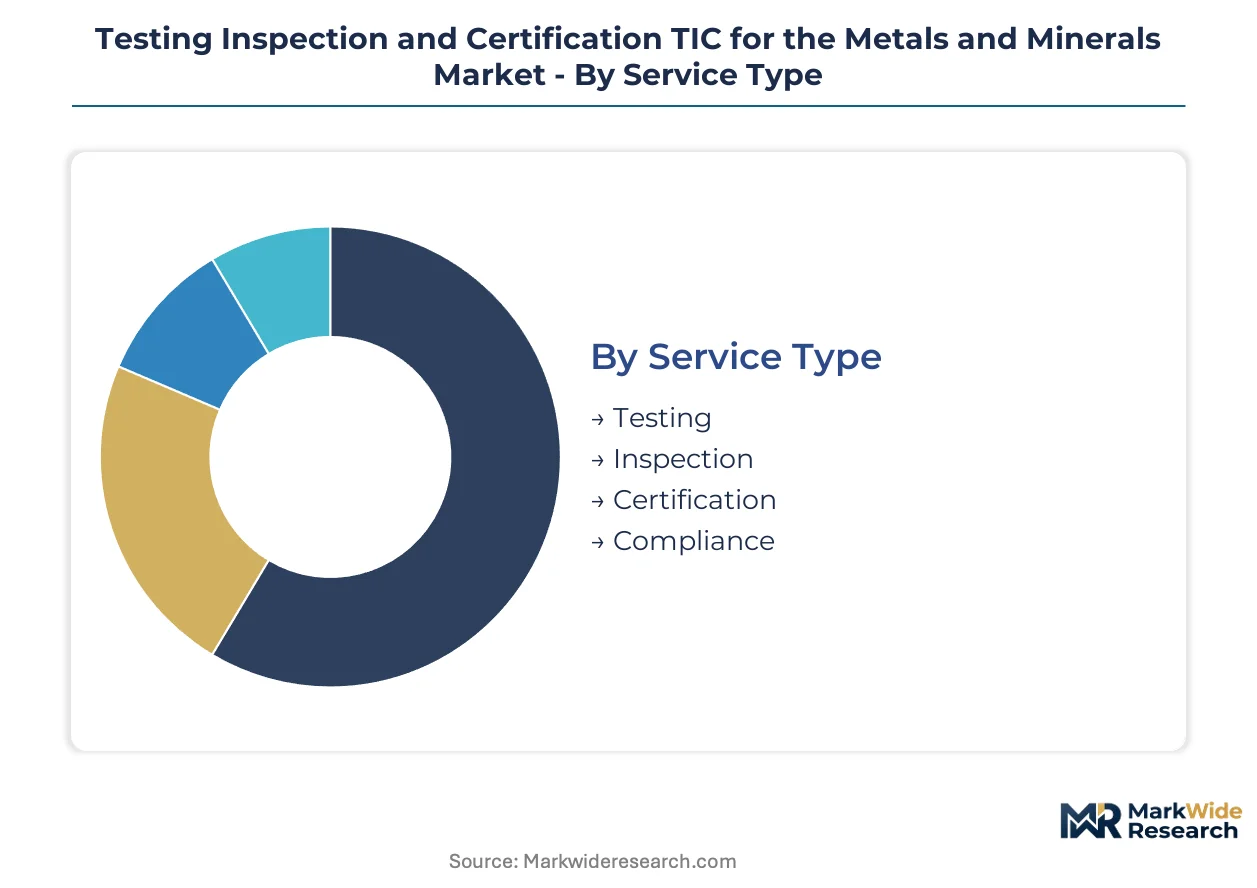
Service configuration in metals and minerals TIC diverges sharply between bulk commodity flows and precision-engineered material qualifications. Segment selection determines accreditation requirements, instrumentation investment, and margin structure across the value chain.
Service Type:
Domestic regulatory compliance services cluster around national accreditation bodies, while export-facing certification demands international laboratory networks with multi-jurisdictional recognition.
- Testing:Analytical verification of elemental composition, mechanical properties, and structural integrity through wet chemistry, spectrometry, and mechanical stress protocols. Volume concentrates at extraction points and port facilities in Germany, China, and Australia, driven by customs clearance requirements and downstream liability mitigation. Testing commands the majority of revenue through recurring volume-based contracts.
- Inspection:Physical examination of material condition, dimensional conformance, and packaging integrity across mining, shipping, and fabrication stages. Demand clusters at Rotterdam and Singapore hub markets where traders require rapid certificate turnaround for arbitrage windows. Inspection extracts premium margins from time-critical spot contracts.
- Certification:Formal attestation of material conformance to ASTM, ISO, or client-specific specifications with documented traceability. Export-led demand from European aerospace and automotive OEMs mandates Nadcap or ISO/IEC 17025 scope for specialty alloy grades.
- Compliance:Advisory and documentation services navigating REACH, GB standards, and defense-aerospace qualification frameworks. Domestic concentration in regulatory consulting for SAMR-administered standards in China and ECHA disclosure thresholds in Europe.
Testing holds the largest share; momentum sits with Certification as defense-aerospace material qualifications tighten.
Material Type:
Cost tier differentiation separates commodity-grade verification from premium-margin specialty material qualifications requiring advanced instrumentation.
- Metals:Ferrous and non-ferrous base materials including steel, copper, aluminum, and nickel requiring elemental composition verification. Volume concentrates in bulk commodity inspection at extraction points, with SGS SA and Bureau Veritas SA dominating port-based contracts through integrated global networks.
- Alloys:Engineered metallic mixtures with precise elemental specifications for aerospace, automotive, and energy applications. Demand concentrates in Germany's Ruhr-Bavaria testing corridor for continuous casting verification of European steel grades, extracting premium margins from ISO 17025-accredited specialty scope.
- Minerals:Unprocessed or partially processed ores and concentrates requiring grade verification and contamination screening. Export-led demand from African and Central Asian mining operations faces accreditation access bottlenecks due to ISO 17025 certification body concentration in Western Europe.
- Composites:Multi-material systems combining metallic and non-metallic constituents for lightweight structural applications. Emerging demand from aerospace OEMs expanding third-party metallurgical verification programs with trace element detection below 10 parts per million.
Metals commands the largest share; composites are climbing the fastest as aerospace lightweighting accelerates.
End User:
Customer type determines contract structure, with integrated mining majors favoring long-term framework agreements and spot traders prioritizing turnaround speed.
- Mining Companies:Extraction-stage operators requiring grade control, resource estimation, and shipment certification. Volume concentrates at mine sites and loading ports, with X-ray fluorescence spectrometry displacing slower wet chemistry protocols for real-time decision-making.
- OEMs:Original equipment manufacturers in aerospace, automotive, and energy sectors mandating material traceability from smelter to fabrication. German automotive stamping operations now require supplier laboratory accreditation to ISO/IEC 17025 with specific scope for EN 1676 aluminum alloy verification.
- Distributors:Mid-tier alloy traders seeking rapid certificate turnaround for arbitrage windows. Digital marketplaces connecting verified laboratories with spot-testing requirements are capturing volume from traditional inspection houses in Singapore and Rotterdam.
- Contractors:Fabrication and construction firms requiring weld verification, pressure vessel inspection, and structural integrity assessment. Magnetic particle inspection retains strongholds in pipeline and pressure vessel weld verification for energy infrastructure projects.
Mining Companies hold the largest share; momentum sits with OEMs as supply chain traceability mandates tighten.
Technology:
Technology maturity stratifies between established non-destructive methods and emerging automated platforms compressing analytical workflows.
- X-Ray Fluorescence:Non-destructive elemental analysis detecting trace contaminants below 10 parts per million without sample destruction. Adoption accelerates at extraction points, eliminating wet chemistry delays and accelerating port clearance timelines for bulk mineral shipments.
- Ultrasonic Testing:High-frequency sound wave propagation detecting internal flaws, thickness variations, and material discontinuities. Volume concentrates in pipeline and pressure vessel inspection for energy infrastructure, with portable units enabling field deployment.
- Magnetic Particle Inspection:Surface and near-surface defect detection in ferromagnetic materials through magnetic field disturbance visualization. Retains strongholds in weld verification for defense-aerospace and energy applications requiring Nadcap-accredited procedures.
- Visual Inspection:Direct optical examination of surface condition, dimensional conformance, and packaging integrity. Lowest-cost method dominates high-volume, low-risk commodity flows where elemental verification is unnecessary.
X-Ray Fluorescence holds the largest share; momentum sits with Ultrasonic Testing as infrastructure integrity mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates aerospace-grade alloy verification workflows, while China anchors bulk mineral inspection volume at extraction points. Australia and Chile dominate mining-stage certification demand. India emerges as a specialty steel testing growth vector under industrial policy incentives.
Germany
REACH authorization requirements for chromium VI compounds in surface treatment processes tighten disclosure obligations for stainless steel importers. ECHA disclosure thresholds compel smelters to maintain ISO/IEC 17025-accredited laboratory partnerships. The Ruhr-Bavaria testing corridor supports continuous casting verification for European steel producers.
China
SAMR-administered GB standards dictate elemental disclosure thresholds for cross-border metal trade. GB standards compliance compels traders to maintain accredited laboratory partnerships or risk customs detention. X-ray fluorescence spectrometry accelerates port clearance timelines at bulk mineral loading facilities.
Australia
Mining-stage grade control and resource estimation drive demand for real-time elemental analysis at extraction points. The country's national mining regulator mandates documented traceability for export shipments. Perth and Queensland mining clusters deploy portable XRF units for in-situ screening.
Chile
Copper cathode and concentrate exports require rapid certificate turnaround for arbitrage windows. The country's national mining regulator enforces contamination screening protocols for cross-border shipments. Antofagasta and Santiago laboratory networks face accreditation access bottlenecks due to ISO 17025 certification body concentration.
India
The PLI scheme for specialty steel and aluminum manufacturing generates new accredited testing requirements for automotive and defense alloy grades. BIS standards compliance tightens material traceability mandates for downstream fabricators. Maharashtra and Gujarat industrial corridors anchor emerging laboratory infrastructure expansion.
Testing Inspection and Certification TIC for the Metals and Minerals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in metals and minerals TIC. Full-service operators leverage global laboratory networks to dominate bulk commodity inspection at extraction points and ports. Niche specialists extract premium margins from defense-aerospace material qualifications requiring extended accreditation timelines. Competitive moves concentrate on digital platform deployment and strategic partnerships with smelter consortiums.
Within the integrated tier, SGS SA, Bureau Veritas SA, and Intertek Group plc occupy positions as archetypal network-scale operators. SGS SA exemplifies the extraction-point dominance model through integrated global coverage. Bureau Veritas SA represents the European steel producer relationship anchor. Intertek Group plc sits within the digital platform differentiation vector for mid-tier alloy distributor workflows.
| Leading Market Players |
|---|
| SGS SA |
| Bureau Veritas SA |
| Intertek Group plc |
| TÜV SÜD AG |
| TÜV Rheinland AG |
| ALS Limited |
| Element Materials Technology Group Ltd |
| Applus+ Servicios Tecnológicos SL |
| CCIC |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between European steel producers and accredited laboratories lock in multi-year testing capacity and price visibility, insulating specialty alloy verification from spot-market volatility while binding smelters to ISO/IEC 17025 partnership commitments across the Ruhr-Bavaria corridor.
Pricing Analysis
After-sales service bundling for instrument calibration and certificate re-issuance drives lifetime value beyond initial testing fees. Three-tier pricing structure across premium, standard, and economy levels separates Nadcap-accredited aerospace qualifications from routine port-based mineral screening. Pricing pressure stems from portable XRF device proliferation enabling mine-site substitution. Mid-tier alloy distributors exhibit highest price sensitivity; defense-aerospace OEMs demonstrate lowest.
Supply Chain Analysis
Germany and China anchor laboratory instrument manufacturing and bulk mineral inspection capacity respectively. The supply chain draws from helium carrier gas production, rare earth spectrometer components, and certified reference materials. Single-source vulnerability concentrates in ISO 17025 accreditation bodies clustered in Western Europe. Distribution runs through digital marketplaces displacing bilateral contracts in Singapore and Rotterdam hub markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as REACH compliance complexity and EU AI Act material traceability mandates splinter demand into specialized niches beyond integrated players' coverage.
For Market Incumbents: Compound defensive positioning through captive helium supply arrangements and accelerated Nadcap scope expansion. Portable analyzer substitution threatens volume-based wet chemistry contracts. Vertical integration into blockchain-anchored certificate platforms preserves margin structure against digital marketplace disintermediation. For New Entrants and Emerging Players: ISO 17025 fast-track partnerships with German automotive stamping operations unlock immediate revenue traction. White-space concentrates in India's PLI scheme specialty steel verification and African mining accreditation access bottlenecks. Go-to-market leverages digital-first certificate delivery targeting spot traders in copper cathode arbitrage windows. For Investors and Strategic Acquirers: Capital is best deployed toward niche laboratories with established aerospace OEM relationships and defensible accreditation timelines. Long-term viability centers on algorithmic audit capabilities for EU AI Act compliance services. Watch for consolidation signals when mid-tier players face helium cost compression beyond operational hedging capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Scope Expansion | Nadcap and ISO/IEC 17025 credentials unlock defense-aerospace premium contracts with 18-24 month qualification timelines. |
| Digital Platform Deployment | API-connected LIMS integration automates certificate delivery for Rotterdam and Singapore hub market traders. |
| Helium Supply Hedging | Long-term carrier gas contracts preserve ICP-MS capacity margins against price volatility in high-precision trace analysis. |
| Blockchain Certificate Anchoring | Immutable smelter-to-fabricator records address downstream liability in cross-border titanium and nickel trade. |
| AI-Assisted Spectral Interpretation | Machine learning models for real-time alloy classification compress analyst review bottlenecks at Persian Gulf aluminum smelters. |
Research Methodology
Initial hypotheses were tested against primary input from laboratory operations directors, aerospace quality assurance managers, mining procurement leads, and smelter technical directors and refined through secondary validation against customs trade data, ECHA REACH filings, SEC 10-K disclosures from listed TIC operators, and national mining regulator export documentation. Bottom-up segment sizing triangulated with top-down macroeconomic drivers across the analysis window.
Variance-decomposition modeling isolated volume and value contributions across service type, material category, end-user vertical, and analytical technology dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating REACH regulatory tightening timelines, PLI scheme implementation phases, and aerospace OEM verification mandate expansion. Industry-specific inputs included helium price volatility indices and ISO 17025 accreditation body capacity constraints.
Decision-makers should treat outputs as directional under sustained REACH enforcement and helium supply normalization assumptions; material deviation would warrant model refresh. Forecasts reflect base-case regulatory continuity without abrupt trade policy disruption. Recalibration cycles align with material shifts in EU AI Act implementation timelines and emerging market laboratory infrastructure buildout.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Rare Earth Elements Market
Metals & Minerals
Selenium Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Global Fabricated Metal Products Market