
 US Cancer Biopsy Market | 2026-2036
US Cancer Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
US Cancer Biopsy Market Intelligence
Multi-source procurement of biopsy instruments and consumables is expanding as US health systems diversify supplier relationships beyond single-vendor dependencies. Becton, Dickinson and Company leverages its integrated manufacturing scale to dominate needle-based specimen collection. Johnson & Johnson Services, Inc. anchors its position through broad surgical biopsy portfolios spanning open and minimally invasive techniques. Medtronic competes by extending interventional oncology platforms that bridge diagnostic sampling with therapeutic delivery.
Cancer biopsy encompasses the extraction and histopathological examination of tissue or fluid specimens to confirm malignancy, grade tumors, and guide targeted therapy selection, with specimens preserved in formalin and embedded in paraffin for immunohistochemical staining against protein biomarkers such as HER2, PD-L1, and Ki-67. The primary commercial purpose centers on generating actionable diagnostic data that determines surgical margins, chemotherapy regimens, and immunotherapy eligibility. Liquid biopsy represents the fastest-expanding technology segment as circulating tumor DNA analysis enables serial monitoring without repeated tissue harvesting. Molecular diagnostics anchored by next-generation sequencing commands the deepest margin pools due to reimbursement premiums for comprehensive genomic profiling. Surgical biopsy retains volume leadership in solid tumor confirmation despite gradual displacement by percutaneous techniques.
FDA premarket notification pathways and CLIA laboratory certification requirements govern commercialization of biopsy devices and downstream testing services, with CMS national coverage determinations directly shaping adoption velocity for novel molecular assays. HIPAA privacy standards and state laboratory licensing boards impose additional operational constraints on specimen handling and data transmission across integrated delivery networks. Stakeholders must monitor evolving FDA guidance on artificial intelligence-assisted pathology review and anticipated CMS reimbursement recalibration for companion diagnostic pairings.
Market Dynamics
Hospital systems in Texas, California, and New York are consolidating pathology services under single enterprise licenses, compressing vendor access points and forcing instrument suppliers to restructure field service networks around integrated delivery network procurement hubs.
Growth Catalysts
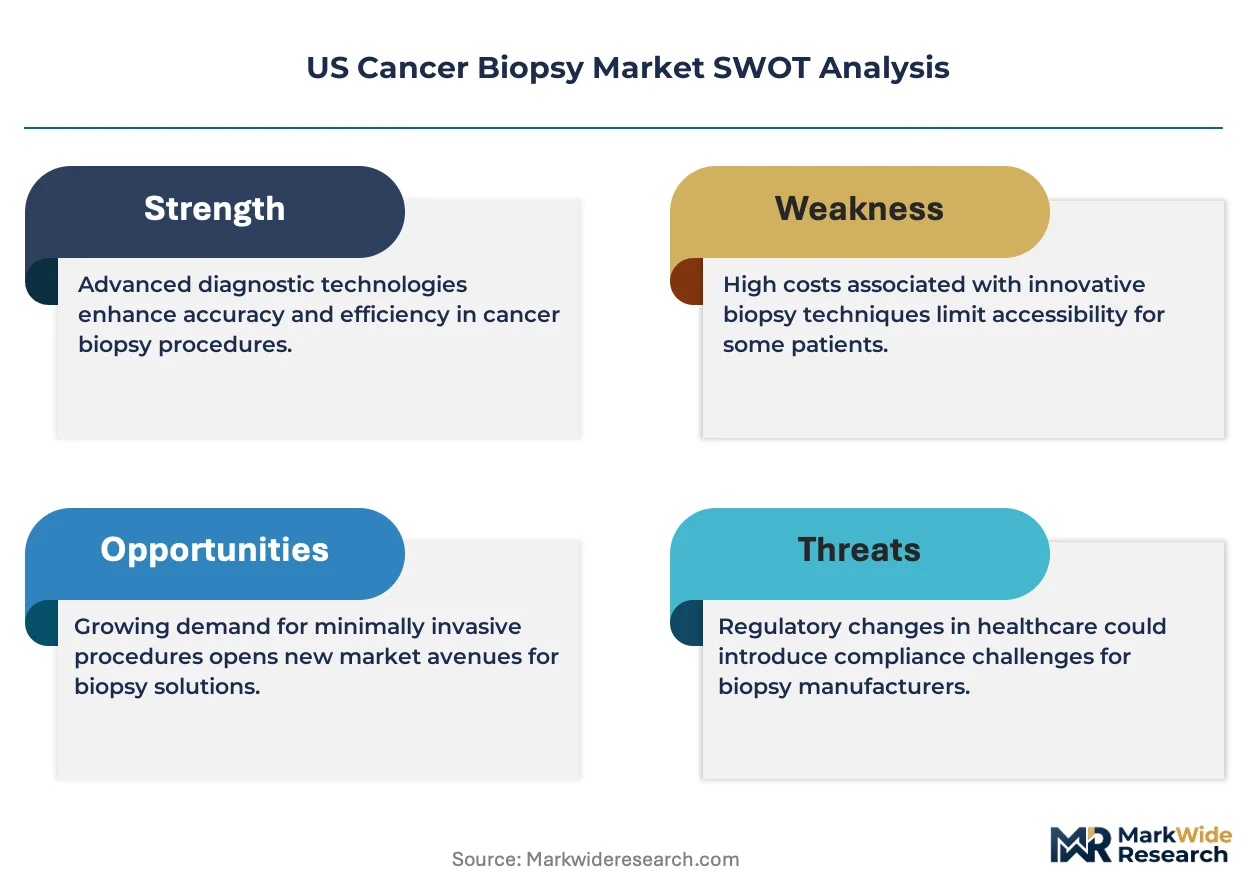
- IRA Medicare price negotiation:Expanded coverage for molecular diagnostic testing accelerates companion diagnostic adoption in oncology practices across Medicare Advantage networks.
- Liquid biopsy serial monitoring:Circulating tumor DNA platforms enable repeat biomarker tracking without invasive tissue harvesting, driving demand in metastatic patient management.
- Metropolitan hospital network expansion:Texas Medical Center, MD Anderson, and Memorial Sloan Kettering anchor regional hub-and-spoke pathology models that concentrate specimen volume.
Market Restraints
- Reimbursement compression:CMS national coverage determinations for comprehensive genomic profiling impose prior authorization requirements that delay test adoption.
- Supply concentration in needle manufacturing:Becton, Dickinson and Company controls dominant share of core needle biopsy devices, creating single-source vulnerability for health systems.
- Technical limitation in tissue adequacy:Fine-needle aspiration yields insufficient material for next-generation sequencing in 15-20% of lung and pancreatic lesions.
Strategic Opportunities
- Artificial intelligence-assisted pathology:FDA breakthrough device designation pathways for computational diagnostic algorithms create expedited market entry for image analysis platforms.
- Community oncology penetration:Underpenetrated ambulatory surgery centers in Florida and Arizona present white space for percutaneous biopsy service expansion.
- Remote pathology consultation:Telepathology platforms enable subspecialist sign-out across state lines, addressing rural pathologist shortages in Mountain West regions.
Industry Challenges
- Molecular pathologist workforce scarcity:Fellowship-trained specialists in genomics interpretation remain concentrated in academic medical centers, limiting community hospital test menu expansion.
- Laboratory information system integration:Disparate electronic health record architectures between hospital systems and reference laboratories create data interoperability friction for genomic test ordering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cancer Biopsy Market |
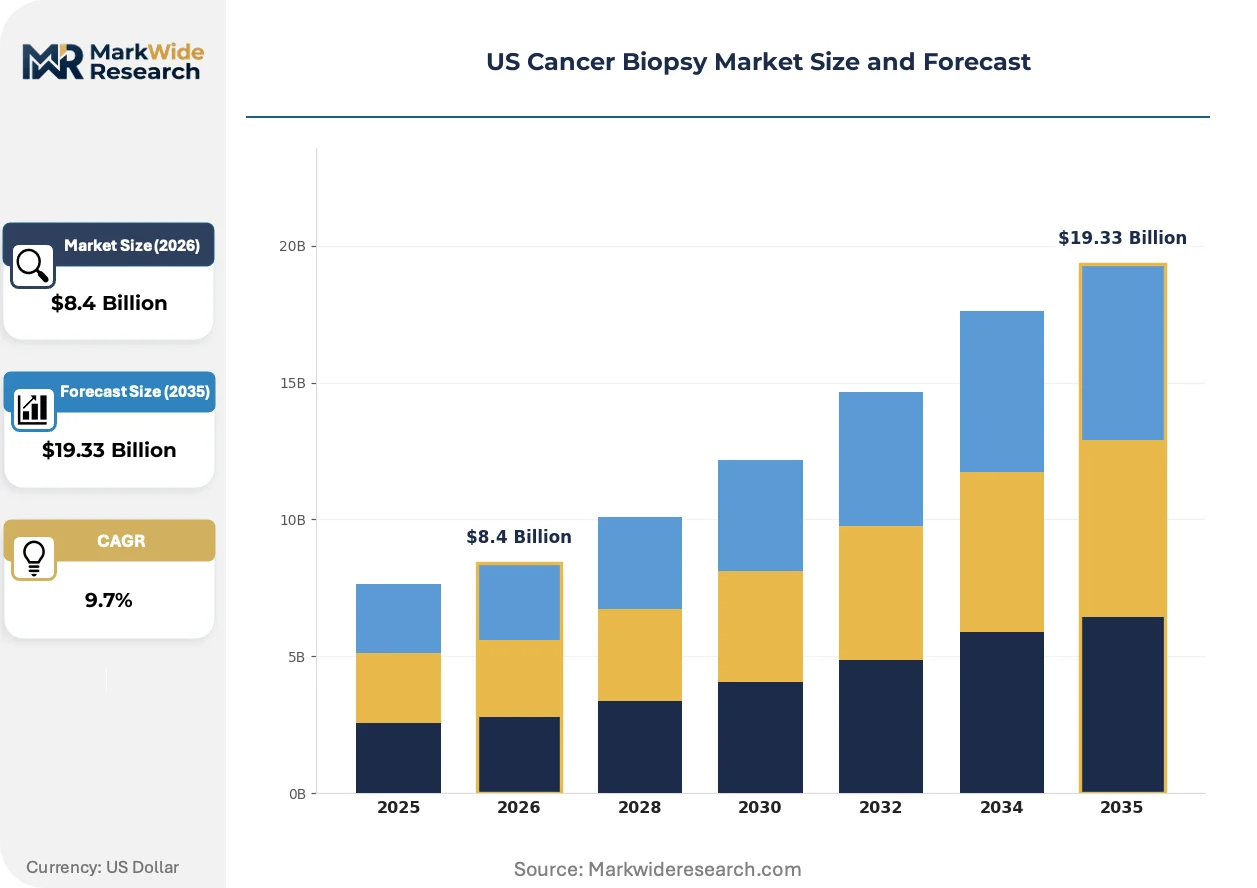
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy, Surgical Biopsy, Liquid Biopsy, Endoscopic Biopsy Technology: Molecular Diagnostics, Immunohistochemistry, Next-Generation Sequencing, PCR End User: Hospitals, Diagnostic Laboratories, Cancer Research Centers, Outpatient Clinics Application: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer |
| Companies Covered | Becton, Dickinson and Company, IZI Medical Products, Johnson & Johnson Services, Inc., Argon Medical Devices, SPECTRA MEDICAL DEVICES, LLC, Medtronic, Boston Scientific Corporation, CONMED Corporation, INRAD, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cancer Biopsy Market Strategic Shifts & Innovations
Diagnostic workflows are fragmenting across point-of-care, hospital-based, and centralized reference laboratory nodes, with technology vendors restructuring platforms to serve heterogeneous specimen routing requirements.
Next-generation sequencing-based comprehensive genomic profiling is converging with immunohistochemistry multiplexing to create integrated biomarker reports that guide both targeted therapy and immunotherapy selection. Large oncology practices in California and New York are adopting these combined workflows within 18-month technology refresh cycles. This convergence is compressing the competitive window for standalone single-analyte testing platforms.
FDA draft guidance on artificial intelligence-assisted diagnostic devices is requiring locked algorithm versions and prospective clinical validation studies for software-as-a-medical-device pathology tools. Commercial laboratories must maintain separate quality systems for AI-augmented versus traditional histopathology review. Academic medical centers with internal algorithm development programs face the steepest compliance burden under the new framework.
Health system procurement committees are consolidating biopsy instrument and consumable contracts under multi-year enterprise agreements, displacing the previous department-level purchasing autonomy that favored best-of-breed device selection. Integrated delivery networks in Texas and Florida are piloting this centralized model first. The shift is most visible in hospital systems with more than ten affiliated oncology service lines.
US Cancer Biopsy Market Segmentation
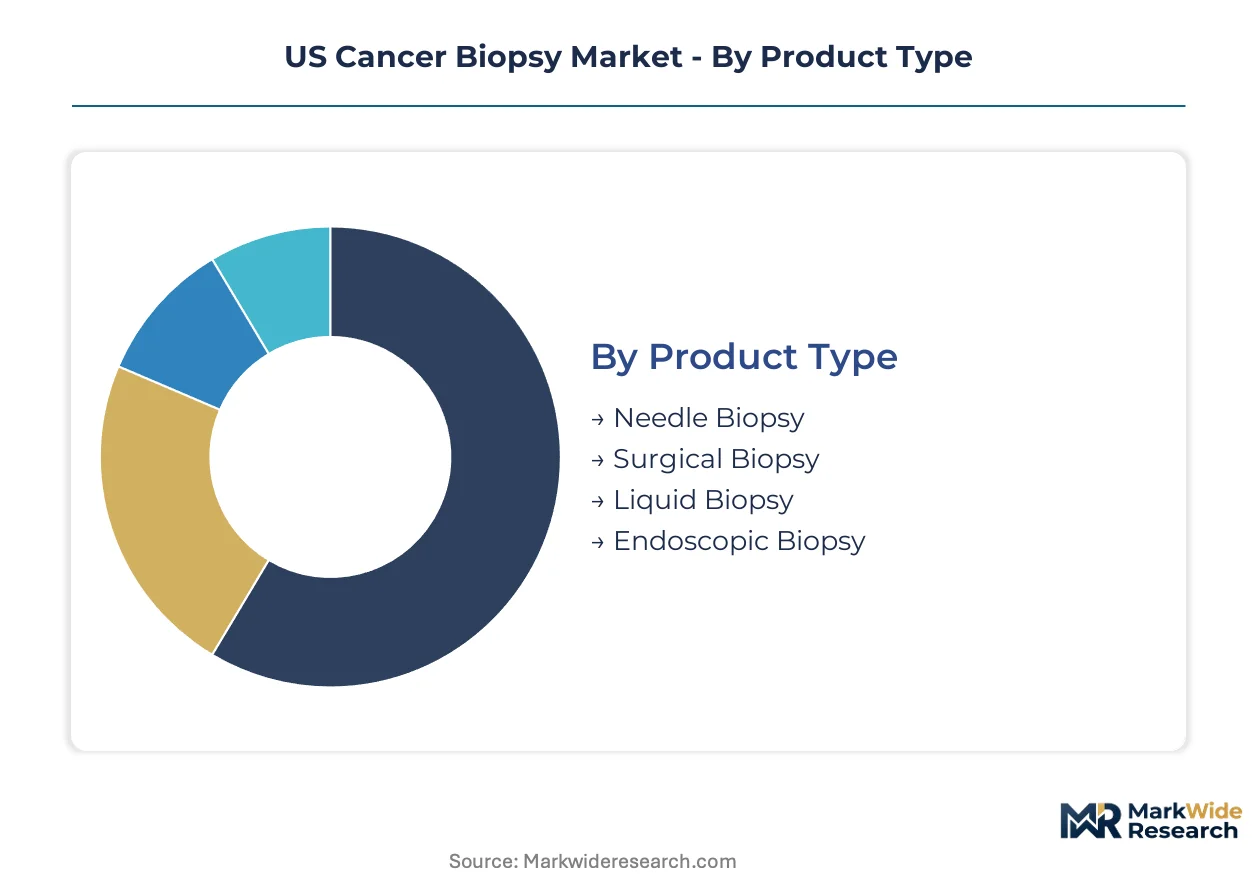
Segmentation in the US Cancer Biopsy Market reveals how procurement authority, reimbursement pathways, and specimen routing requirements differ across clinical settings and technology platforms. Hospital systems prioritize integrated instrument-consumable contracts while reference laboratories compete on test menu breadth.
Product Type:
Needle-based and fluid-based sampling technologies diverge sharply in capital requirements, reimbursement codes, and clinical workflow integration.
- Needle Biopsy:Core needle and fine-needle aspiration devices extract tissue specimens through percutaneous access. Texas Medical Center and MD Anderson anchor concentrated demand for vacuum-assisted breast biopsy systems.
- Surgical Biopsy:Open and incisional techniques remain essential for adequate tissue acquisition in bone, brain, and retroperitoneal lesions. Academic medical centers in California maintain higher surgical biopsy volumes due to complex case referrals.
- Liquid Biopsy:Circulating tumor DNA platforms enable serial monitoring without invasive harvesting.
- Endoscopic Biopsy:Forceps and brush cytology devices integrate with flexible endoscopy suites for gastrointestinal and pulmonary access.
Needle biopsy leads on scale; liquid biopsy leads on momentum.
Technology:
Reimbursement premiums and FDA premarket pathways stratify margin pools across analytical platforms.
- Molecular Diagnostics:Fluorescence in situ hybridization and gene expression profiling detect chromosomal rearrangements and fusion transcripts. Medicare Advantage networks in Florida drive companion diagnostic adoption for targeted therapy eligibility.
- Immunohistochemistry:Antibody-based protein detection remains the workhorse for PD-L1, HER2, and mismatch repair protein assessment. Community hospital laboratories in Arizona rely on IHC for rapid turnaround on standard biomarker panels.
- Next-Generation Sequencing:Comprehensive genomic profiling commands the deepest reimbursement but faces prior authorization friction.
- PCR:Quantitative amplification techniques deliver rapid mutation detection for EGFR and BRAF hotspot analysis.
Immunohistochemistry leads on scale; next-generation sequencing leads on momentum.
End User:
Procurement centralization and CLIA certification requirements reshape competitive access across delivery settings.
- Hospitals:In-house pathology laboratories within integrated delivery networks consolidate instrument purchasing under enterprise contracts. Memorial Sloan Kettering and affiliated systems in New York exemplify hub-and-spoke specimen routing models.
- Diagnostic Laboratories:Reference laboratories compete on NGS panel breadth and turnaround time for community oncology practices. Quest Diagnostics and LabCorp processing sites in California and Texas handle high-volume comprehensive genomic profiling.
- Cancer Research Centers:Academic medical centers with internal CLIA laboratories develop laboratory-developed tests for investigational biomarkers.
- Outpatient Clinics:Ambulatory surgery centers in Florida and Arizona present white space for percutaneous biopsy service expansion.
Hospitals lead on scale; outpatient clinics lead on momentum.
Application:
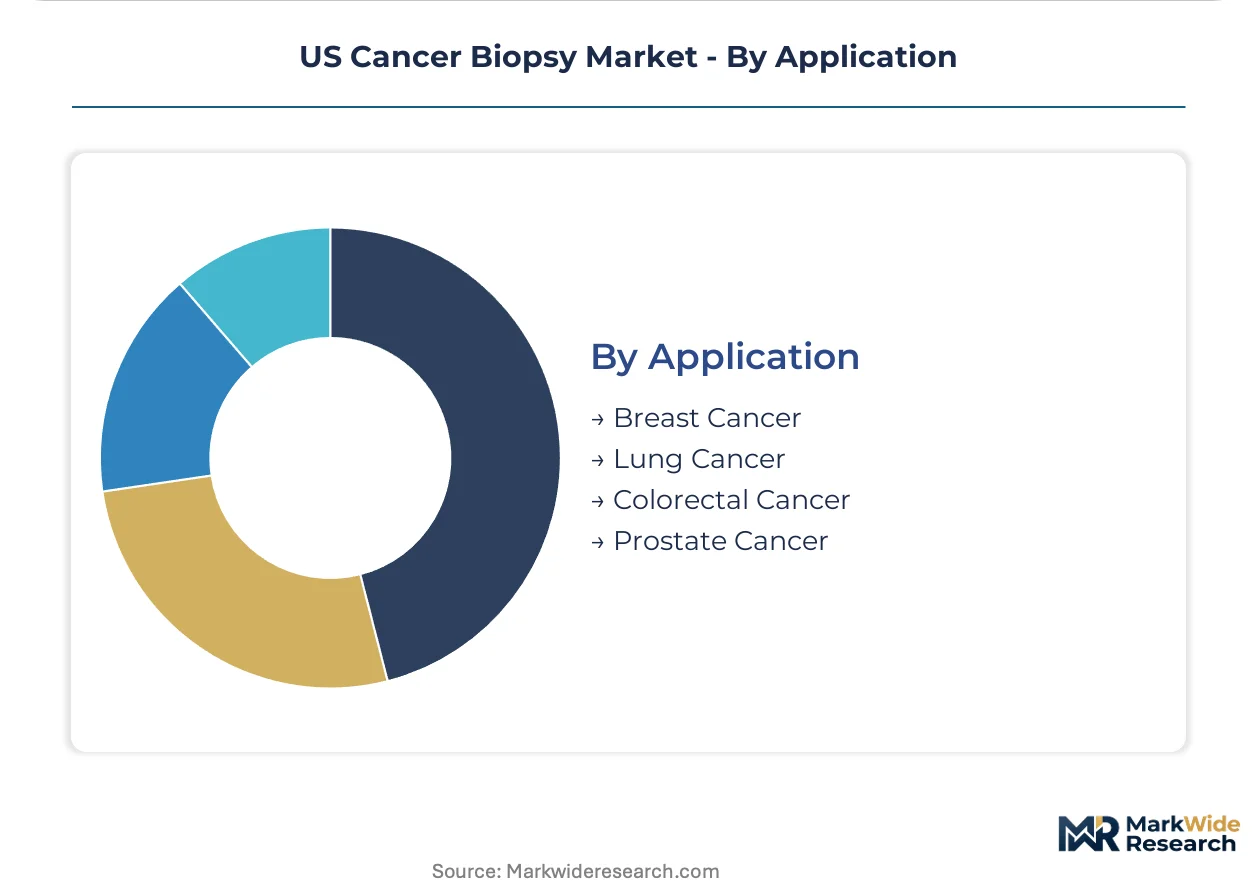
Tumor biology and screening infrastructure determine biopsy volume distribution across malignancy types.
- Breast Cancer:Image-guided core needle biopsy dominates initial diagnosis with vacuum-assisted devices standardizing specimen adequacy. Screening mammography programs in Texas and California generate high procedural volumes.
- Lung Cancer:Navigational bronchoscopy and CT-guided transthoracic approaches compete for peripheral lesion access. Academic medical centers in New York report 15-20% insufficient yield rates for fine-needle aspiration in small pulmonary nodules.
- Colorectal Cancer:Endoscopic biopsy integrates with screening colonoscopy workflows for simultaneous polypectomy and histopathology.
- Prostate Cancer:MRI-ultrasound fusion biopsy systems target suspicious lesions identified on multiparametric imaging.
Breast cancer leads on scale; lung cancer leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Medical Center anchors specimen volume concentration through hub-and-spoke pathology models that integrate MD Anderson's referral networks with regional hospital systems. Metropolitan clusters in California and New York concentrate precision diagnostic infrastructure and molecular pathologist expertise.
Texas
MD Anderson Cancer Center and Texas Medical Center drive vacuum-assisted breast biopsy system demand through high-throughput screening programs. CMS national coverage determinations for comprehensive genomic profiling shape prior authorization workflows across Medicare Advantage networks. Houston anchors enterprise procurement consolidation under integrated delivery network contracts.
California
Academic medical centers maintain elevated surgical biopsy volumes for complex case referrals from western states. FDA premarket notification pathways for artificial intelligence-assisted devices create compliance burdens for laboratories with internal algorithm development. Los Angeles and San Francisco Bay Area concentrate next-generation sequencing reference laboratory capacity.
New York
Memorial Sloan Kettering exemplifies hub-and-spoke specimen routing with enterprise-licensed pathology services across affiliated systems. HIPAA privacy standards and state laboratory licensing boards constrain telepathology platforms crossing state lines. New York City metropolitan area concentrates immunohistochemistry multiplexing adoption within 18-month technology refresh cycles.
Florida
Ambulatory surgery centers present white space for percutaneous biopsy service expansion in underpenetrated community oncology settings. Medicare Advantage networks drive companion diagnostic adoption for targeted therapy eligibility determination. Miami and Tampa Bay metropolitan areas anchor regional hub-and-spoke models for liquid biopsy serial monitoring.
Arizona
Community hospital laboratories rely on immunohistochemistry for rapid turnaround on standard biomarker panels. CLIA laboratory certification requirements limit test menu expansion without fellowship-trained molecular pathologist recruitment. Phoenix metropolitan area concentrates outpatient clinic procedural volume for image-guided core needle biopsy.
US Cancer Biopsy Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue artificial intelligence-augmented pathology platforms. The vendor base stratifies across integrated instrument-consumable suppliers, interventional oncology platform developers, and standalone diagnostic test manufacturers. Three archetypes dominate: diversified medical technology conglomerates with manufacturing scale, surgical device specialists with open and minimally invasive portfolios, and molecular diagnostic laboratories with comprehensive genomic profiling menus. Competitive moves center on enterprise contract consolidation under multi-year agreements and FDA breakthrough device designation pursuit for computational algorithms.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Johnson & Johnson Services, Inc. represent scale-driven archetypes with integrated manufacturing and broad surgical portfolios. Medtronic occupies a position bridging diagnostic sampling with therapeutic delivery platforms. These three entities exemplify the consolidation pressure forcing field service network restructuring around integrated delivery network procurement hubs.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| IZI Medical Products |
| Johnson & Johnson Services, Inc. |
| Argon Medical Devices |
| SPECTRA MEDICAL DEVICES, LLC |
| Medtronic |
| Boston Scientific Corporation |
| CONMED Corporation |
| INRAD, Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up pathology service platforms have consolidated regional laboratory networks across Texas and Florida, compressing procurement leverage for instrument vendors while standardizing reimbursement-negotiated pricing tiers across integrated delivery networks. This ownership concentration simultaneously tightens supply chain discipline and anchors pricing power with enterprise-scale buyers.
Pricing Analysis
Input-cost pass-through from stainless steel and precision-machined needle components flows unevenly across the three-tier pricing structure across premium, standard, and economy levels. FDA breakthrough device designation and CLIA laboratory certification tier create price differentiation between academic medical centers and community hospital laboratories. Pricing pressure stems from CMS reimbursement compression on comprehensive genomic profiling, forcing reference laboratories to absorb margin erosion. Community oncology practices exhibit highest price sensitivity, while National Cancer Institute-designated centers maintain lowest sensitivity due to grant-funded research budgets.
Supply Chain Analysis
Domestic-content mandates under the IRA Medicare price negotiation framework reshape sourcing for precision diagnostic consumables toward US-based manufacturing. Needle-based biopsy device production concentrates in the United States, Mexico, and Ireland, with specialized cannula manufacturing anchored in German and Japanese precision metalworking hubs. Supply chains draw from medical-grade stainless steel, polymer biopsy valves, and sterile barrier packaging materials. Single-source vulnerability concentrates in vacuum-assisted breast biopsy systems controlled by Becton, Dickinson and Company. Distribution runs through integrated delivery network procurement hubs consolidating multi-year enterprise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Medicare Advantage network expansion shifts demand toward comprehensive genomic profiling with premium reimbursement specifications. The transition from single-analyte testing to integrated biomarker reports favors laboratories with capital-intensive NGS infrastructure.
For Market Incumbents: Cement enterprise contract renewals through multi-year instrument-consumable bundling that locks out emerging AI-augmented pathology platforms. Expand field service networks around Texas Medical Center and Memorial Sloan Kettering procurement hubs to defend against interventional oncology platform developers. Prioritize CLIA laboratory certification investments in Florida and Arizona to preempt community oncology penetration by reference laboratories. For New Entrants and Emerging Players: Begin with ambulatory surgery center partnerships in Florida and Arizona where percutaneous biopsy service penetration remains underdeveloped relative to metropolitan hospital networks. Target liquid biopsy serial monitoring workflows in Medicare Advantage networks where prior authorization friction disadvantages centralized reference laboratories. Deploy telepathology platforms with HIPAA-compliant interstate data transmission to address Mountain West pathologist shortages. For Investors and Strategic Acquirers: Valuations sit cheapest among community hospital laboratory networks lacking fellowship-trained molecular pathologists yet facing CLIA certification requirements for test menu expansion. Long-term viability hinges on consolidation into hub-and-spoke pathology models with enterprise licensing across affiliated systems. Watch FDA artificial intelligence-assisted device guidance finalization as inflection signal for computational diagnostic algorithm commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Memorial Sloan Kettering's hub-and-spoke model concentrates specimen volume and procurement authority. |
| FDA Submission | Breakthrough device designation pathways expedite market entry for AI-assisted pathology review platforms. |
| Reimbursement Strategy | CMS national coverage determinations directly shape prior authorization workflows for comprehensive genomic profiling. |
| Software Companion Development | Locked algorithm versions for computational diagnostics require separate quality systems from traditional histopathology. |
| CE Marking Pathway | European regulatory alignment supports global scale for NGS-based liquid biopsy platforms. |
Research Approach
Direct dialogue with molecular pathologists, hospital procurement committee chairs, GPO contracts managers, and biomedical engineers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) premarket notification databases, CMS national coverage determination records, hospital procurement databases, and CLIA laboratory certification registries. Bottom-up and top-down triangulation cross-checked instrument shipment data against Medicare reimbursement claims.
Bottom-up modeling segmented volume and value across needle biopsy, liquid biopsy, and surgical biopsy modalities, then stratified by immunohistochemistry, next-generation sequencing, and molecular diagnostics technology tiers. End-user splits tracked hospitals, diagnostic laboratories, cancer research centers, and outpatient clinics throughout the forecast period. CAGRs derived from procedure volume growth in metropolitan hospital networks and reimbursement rate trajectories for precision diagnostics.
Several conditions sit outside the modeled scope, including unforeseen FDA artificial intelligence guidance revisions, state-level telepathology licensing barriers, and supply disruptions in medical-grade stainless steel. Forecasts reflect documented assumptions about Medicare Advantage network expansion and molecular pathologist workforce pipeline recovery. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Global Clinical Oncology NGS Market
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market