
 Europe Bladder Cancer Therapeutics and Diagnostics Market | 2026-2036
Europe Bladder Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bladder Cancer Therapeutics and Diagnostics Market Foresight
European biopharmaceutical manufacturing capacity for antibody-drug conjugates and immune checkpoint inhibitors is expanding. Bristol-Myers Squibb Company leverages its European development network to sustain clinical trial density across multiple member states. AstraZeneca PLC anchors its oncology portfolio through deep specialization in PD-L1 directed therapies. F. Hoffmann-La Roche Ltd dominates companion diagnostic development, controlling regulatory submission pathways for co-approved theranostic pairs.
Europe Bladder Cancer Therapeutics and Diagnostics encompasses systemic treatments, localized interventions, and molecular detection systems used to manage urothelial malignancies from Ta through T4 stages. The field relies on monoclonal antibody engineering, platinum-based cytotoxic formulations, fluorescence cystoscopy platforms, and PCR-based urinary biomarker panels to guide treatment selection and monitor recurrence. Immunotherapy now leads product type revenue generation as checkpoint inhibitors displace first-line chemotherapy in cisplatin-ineligible patients across major European centers. Liquid biopsy technology represents the fastest-expanding diagnostic segment, though biomarker-validated imaging retains the deepest margin pools due to reimbursement security and established clinical utility.
The European Medicines Agency (EMA) governs centralized marketing authorization for novel therapeutics, while the EU Medical Device Regulation (MDR) and In Vitro Diagnostic Regulation (IVDR) impose strengthened clinical performance requirements on diagnostic platforms. These frameworks compel manufacturers to generate Europe-specific evidence packages, raising barriers for non-EU developers while creating protected commercial windows for compliant incumbents. Stakeholders must monitor EMA accelerated assessment pathways and national health technology assessment divergence to anticipate access timelines and pricing negotiations.
Market Dynamics
Combination immunotherapy-chemotherapy protocols are displacing single-agent regimens across European oncology centers, forcing manufacturers to restructure clinical trial designs and companion diagnostic co-development timelines. Hospital procurement committees now prioritize theranostic bundles that link checkpoint inhibitor eligibility to validated biomarker status, compressing traditional sales cycles into integrated pathway contracts.
Growth Catalysts
- EMA Accelerated Assessment:The pathway compresses marketing authorization timelines for novel bladder cancer therapeutics, enabling earlier patient access and faster commercialization across EU member states.
- PD-L1 Biomarker Expansion:Pathology laboratories in Germany and France are scaling automated immunohistochemistry platforms to handle rising testing volumes for checkpoint inhibitor eligibility.
- Cisplatin-Ineligible Patient Pool:Aging demographics across Western Europe are expanding the addressable population for immunotherapy-first treatment protocols in muscle-invasive disease.
Market Restraints
- IVDR Clinical Evidence Burden:The In Vitro Diagnostic Regulation mandates extensive performance studies for urinary biomarker panels, elevating development costs and extending time-to-market for diagnostic developers.
- Platinum Supply Concentration:Reliance on South African and Russian platinum group metal outputs creates formulation cost volatility for carboplatin and cisplatin manufacturers.
- Fluorescence Cystoscopy Limitation:Photosensitizer agent shortages and specialized equipment requirements restrict adoption outside tertiary referral centers in Italy and Spain.
Strategic Opportunities
- Eastern European Network Expansion:Poland and Romania present underpenetrated markets where centralized oncology networks are consolidating diagnostic and therapeutic procurement under single-contract frameworks.
- Liquid Biopsy-Imaging Convergence:PCR-based circulating tumor DNA platforms paired with advanced MRI protocols enable non-invasive recurrence monitoring, opening ambulatory care channels.
- EU Cancer Plan Funding:The European Commission's billion-euro research initiative creates grant-funded development windows for novel antibody-drug conjugate programs targeting urothelial carcinoma.
Industry Challenges
- Companion Diagnostic Synchronization:Therapeutic developers face execution risk when biomarker assay validation lags behind drug approval timelines, fragmenting patient access across member states.
- Cross-Border Reimbursement Complexity:Divergent health technology assessment methodologies between NICE in the United Kingdom, HAS in France, and IQWiG in Germany create pricing and access fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bladder Cancer Therapeutics and Diagnostics Market |
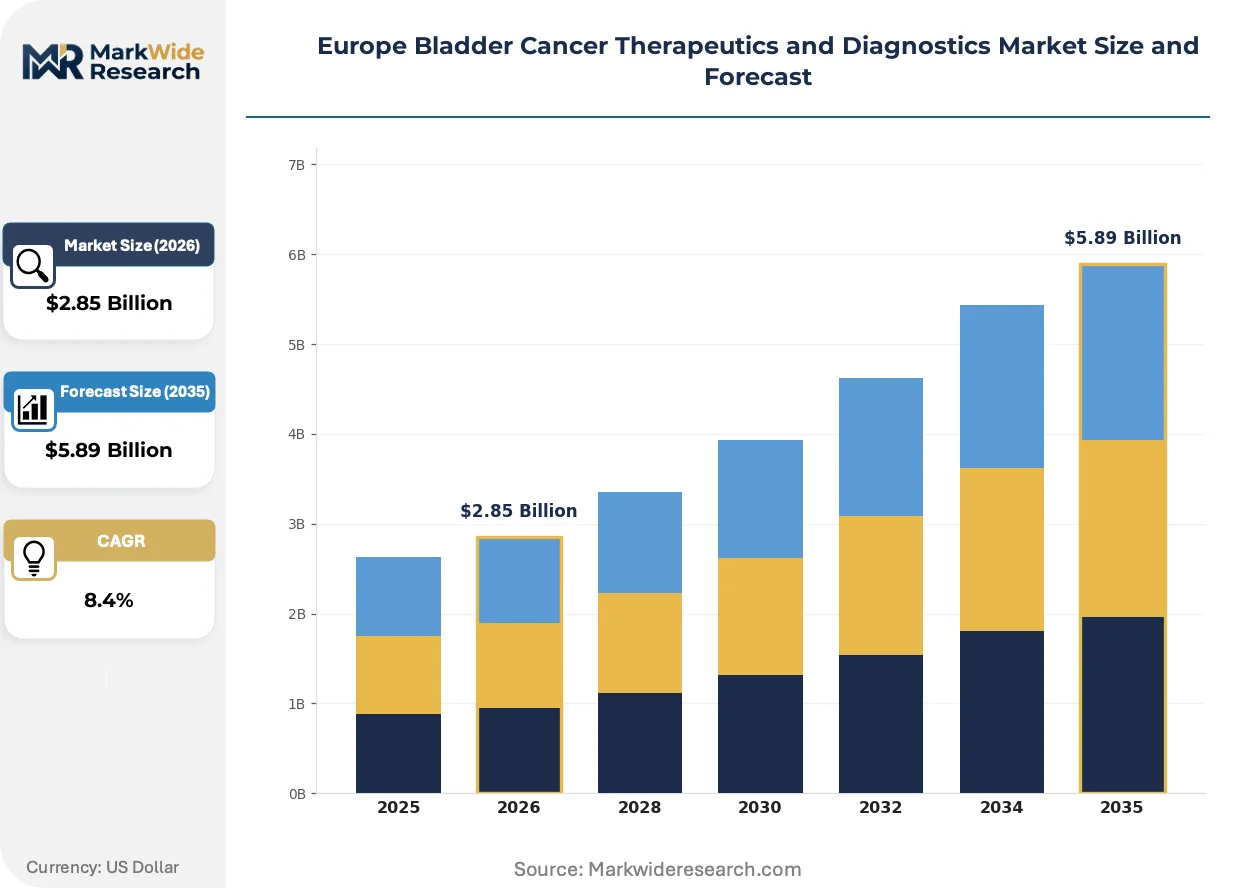
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Radiation Therapy, Surgical Therapy Application: Early-stage, Advanced-stage, Maintenance Therapy, Palliative Care End User: Hospitals, Clinics, Outpatient Facilities, Research Laboratories Technology: Biomarkers, Imaging Techniques, Genomic Sequencing, Liquid Biopsy |
| Companies Covered | F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, AstraZeneca PLC, Johnson & Johnson, Endo International plc, Merck KGaA, Novartis AG, Pfizer Inc., Sanofi SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bladder Cancer Therapeutics and Diagnostics Market Shifts & Advancements
Artificial intelligence is penetrating diagnostic workflows and treatment planning systems across European urology departments, compressing interpretation times and standardizing staging accuracy. These shifts are restructuring competitive positioning around data integration capabilities rather than device hardware alone.
Digital pathology platforms are automating slide interpretation for PD-L1 scoring and tumor-infiltrating lymphocyte quantification. Pathology departments in the Netherlands and Sweden are deploying these systems to manage rising biomarker testing volumes without proportional staffing expansion. The technology is automating routine scoring tasks while reserving complex cases for specialist review, flattening laboratory cost curves.
The EU Medical Device Regulation is tightening post-market surveillance requirements for fluorescence cystoscopy systems and endoscopic platforms. Manufacturers must now generate real-world performance data across diverse clinical settings, elevating compliance infrastructure investments. German and French notified bodies are processing certification renewals more selectively, extending timelines for non-compliant incumbents.
Hospital purchasing consortia are consolidating antibody-drug conjugate and immune checkpoint inhibitor procurement under multi-year framework agreements. Academic medical centers in the United Kingdom and Belgium are leading this transition, displacing single-product contracts with bundled pathway pricing. This concentration is most visible in England, where NHS England's specialized commissioning function aggregates demand across cancer alliance networks.
Europe Bladder Cancer Therapeutics and Diagnostics Market Segmentation
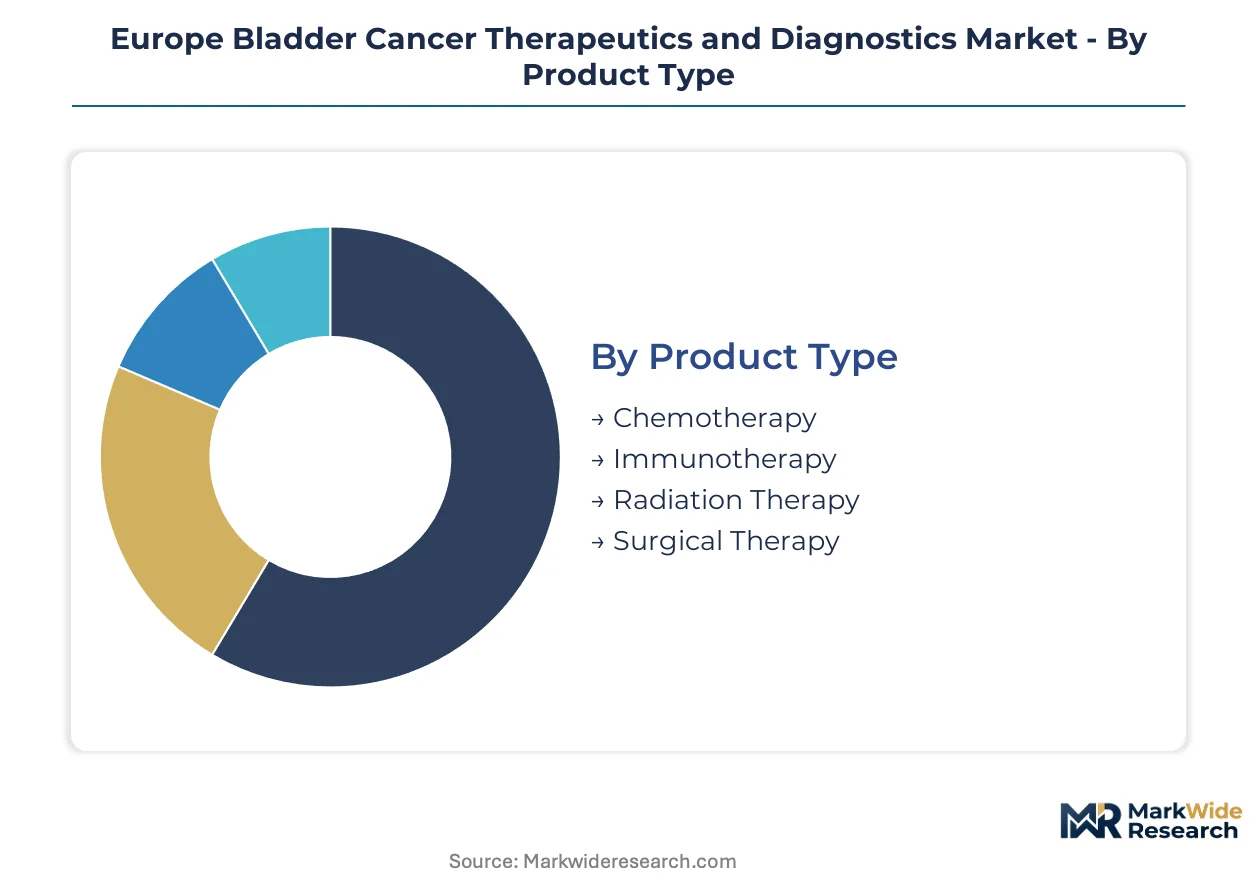
Segmentation in the Europe bladder cancer market reveals how treatment selection diverges across care settings and disease stages. Procurement patterns vary sharply between centralized hospital networks and distributed outpatient facilities, while diagnostic technology adoption clusters in high-volume oncology centers.
Product Type:
Cost tier separates segments, with platinum-based regimens occupying lower price bands and biologics commanding premium positioning.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and PD-L1 pathways now dominate first-line protocols for cisplatin-ineligible muscle-invasive patients. German and French academic medical centers are scaling automated immunohistochemistry platforms to handle rising biomarker testing volumes for patient eligibility.
- Chemotherapy:Platinum-based cytotoxic formulations remain foundational for neoadjuvant and adjuvant protocols, though carboplatin and cisplatin manufacturers face raw material volatility from concentrated South African and Russian supply sources.
- Radiation Therapy:External beam and brachytherapy approaches serve localized disease and palliative symptom management in regional oncology networks.
- Surgical Therapy:Transurethral resection and radical cystectomy procedures anchor staging and curative intent across European urology departments.
Volume sits with chemotherapy; growth tilts toward immunotherapy.
Application:
Maturity distinguishes segments, with established protocols in early-stage disease contrasting against evolving combination approaches in advanced settings.
- Early-stage:Ta through T1 disease management relies on transurethral resection with intravesical therapy, where fluorescence cystoscopy systems enhance visualization though photosensitizer shortages constrain adoption outside tertiary centers in Italy and Spain.
- Advanced-stage:Muscle-invasive and metastatic protocols are restructuring around immunotherapy-chemotherapy combinations, with EMA accelerated assessment pathways compressing marketing authorization timelines for novel agents.
- Maintenance Therapy:Post-induction avelumab and pembrolizumab protocols extend progression-free intervals in responding patients across United Kingdom cancer alliance networks.
- Palliative Care:Symptom-focused interventions address bladder preservation and quality-of-life endpoints in elderly populations concentrated in Western European demographics.
Patient volume concentrates in early-stage; steepest expansion trajectory appears in advanced-stage combination protocols.
End User:
Customer type governs procurement complexity, with consolidated purchasing power in hospital networks diverging from fragmented clinic decision-making.
- Hospitals:Centralized oncology networks in Germany, France, and the United Kingdom drive standardized care pathways and aggregated antibody-drug conjugate procurement under multi-year framework agreements.
- Clinics:Community urology practices handle initial diagnosis and surveillance cystoscopy, referring complex cases to academic centers.
- Outpatient Facilities:Ambulatory infusion centers are expanding capacity for checkpoint inhibitor administration as treatment shifts away from inpatient settings.
- Research Laboratories:Academic and commercial labs validate companion diagnostic assays under tightening EU IVDR clinical evidence requirements.
Revenue pools favor hospitals; fastest volume gains emerge in outpatient facilities.
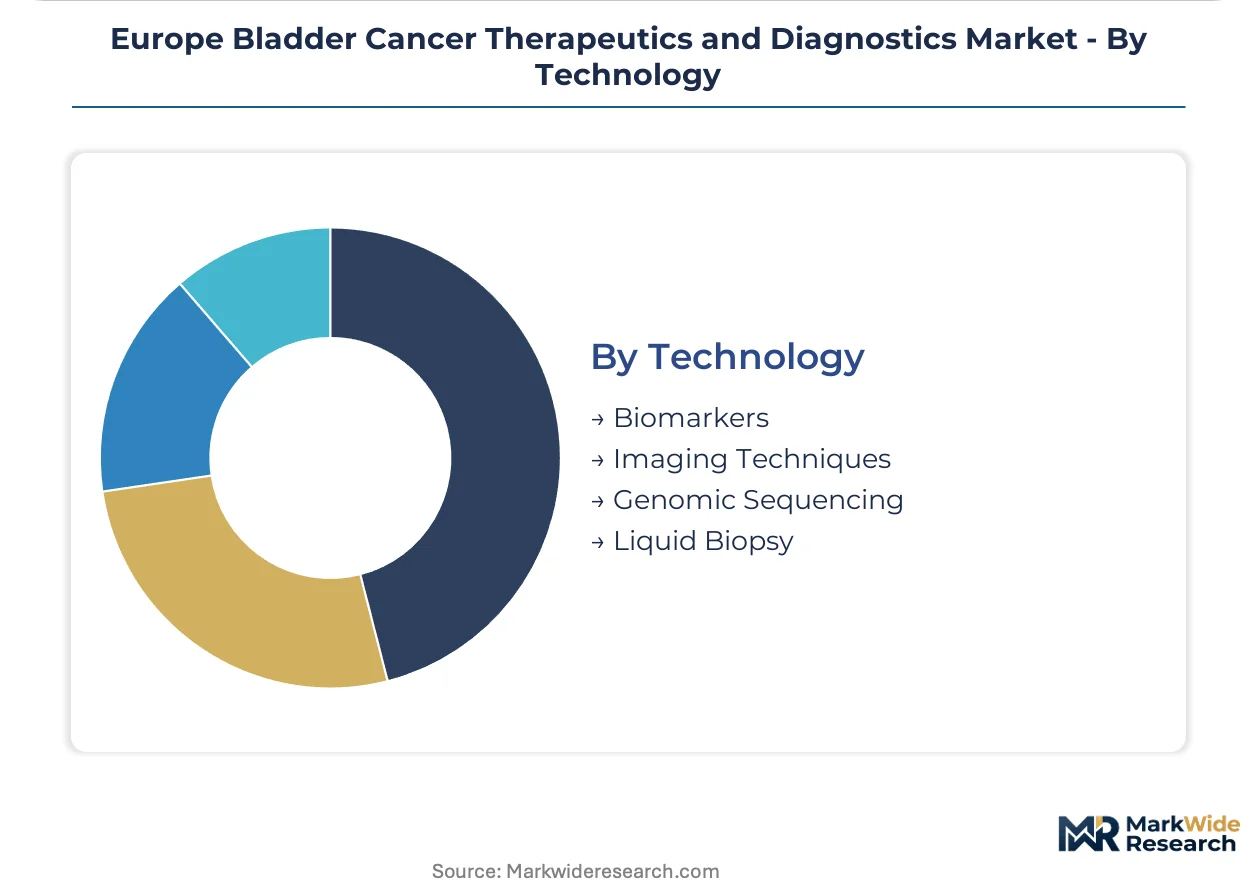
Technology:
Supply concentration differentiates segments, with diagnostic platform development controlled by a narrow set of notified body-certified manufacturers.
- Liquid Biopsy:PCR-based circulating tumor DNA platforms are expanding most quickly for recurrence monitoring, with Dutch and Swedish pathology departments deploying automated systems to manage rising test volumes without proportional staffing expansion.
- Imaging Techniques:Fluorescence cystoscopy and advanced MRI protocols retain the deepest margin pools due to reimbursement security and established clinical utility across European urology departments.
- Biomarkers:PD-L1 immunohistochemistry and urinary protein panels guide checkpoint inhibitor eligibility, with EMA and national health technology assessments synchronizing on validation requirements.
- Genomic Sequencing:Comprehensive genomic profiling identifies actionable alterations in advanced disease, though coverage variability persists across member state reimbursement schemes.
Margin security rests with imaging; innovation velocity concentrates in liquid biopsy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum group metal supply chains from South African and Russian mining districts anchor formulation economics across European oncology networks. Hospital procurement committees in Western Europe now weight raw material provenance heavily in multi-year framework negotiations.
Germany
Automated immunohistochemistry platforms in Heidelberg and Munich pathology laboratories handle rising PD-L1 testing volumes for checkpoint inhibitor eligibility. The Federal Joint Committee (G-BA) synchronizes reimbursement decisions with EMA marketing authorizations through early benefit assessment pathways. The Rhine-Main biotech corridor concentrates antibody-drug conjugate manufacturing investments from Basel-based pharmaceutical developers.
France
Academic medical centers in Paris and Lyon scale fluorescence cystoscopy capacity despite photosensitizer agent shortages constraining Italian and Spanish adoption. The National Authority for Health (HAS) evaluates companion diagnostic clinical utility through parallel therapeutic assessment procedures. The Lyon-Saint-Étienne oncology cluster coordinates multicenter biomarker validation studies under EU IVDR performance study requirements.
United Kingdom
NHS England's specialized commissioning function aggregates checkpoint inhibitor demand across cancer alliance networks, displacing single-product contracts with bundled pathway pricing. The National Institute for Health and Care Excellence (NICE) maintains distinct health technology assessment methodologies from continental counterparts, creating access timeline divergence. The Cambridge-London life sciences corridor anchors liquid biopsy development programs targeting circulating tumor DNA detection.
Italy
Tertiary referral centers in Milan and Rome concentrate fluorescence cystoscopy adoption while regional hospitals face equipment procurement delays. The Italian Medicines Agency (AIFA) negotiates price-volume agreements separately from EMA authorization timelines, fragmenting commercial launch sequencing. The Lombardy oncology network standardizes muscle-invasive disease protocols across provincial hospital consortia.
Poland
Centralized oncology networks in Warsaw and Kraków consolidate diagnostic and therapeutic procurement under single-contract frameworks, presenting expansion opportunities for Western European manufacturers. The Polish Office for Registration of Medicinal Products aligns national reimbursement lists with EMA decisions through accelerated parallel procedures. The Mazovia region attracts clinical trial investments from multinational sponsors seeking Eastern European patient access.
Europe Bladder Cancer Therapeutics and Diagnostics Market Competitive Landscape
Global majors compete with regional champions across regulatory submission density and biomarker co-development timelines. The vendor base clusters around three concentration points: integrated theranostic developers controlling companion diagnostic pathways, pure-play immunotherapy specialists scaling manufacturing networks, and diversified pharmaceutical conglomerates leveraging oncology portfolio breadth. Strategic archetypes include checkpoint inhibitor originators, antibody-drug conjugate engineering platforms, and fluorescence imaging system manufacturers. Dominant competitive moves encompass M&A activity targeting biomarker assay capabilities and capacity expansion for platinum-based cytotoxic formulations.
Within the integrated theranostic tier, F. Hoffmann-La Roche Ltd and Bristol-Myers Squibb Company exemplify divergent approaches to diagnostic-therapeutic synchronization. Roche's Basel-based structure anchors companion diagnostic development through controlled regulatory submission pathways for co-approved pairs. Bristol-Myers Squibb leverages its European development network to sustain clinical trial density across multiple member states. AstraZeneca PLC occupies a position emphasizing PD-L1 directed specialization within the checkpoint inhibitor segment.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Johnson & Johnson |
| Endo International plc |
| Merck KGaA |
| Novartis AG |
| Pfizer Inc. |
| Sanofi SA |
| Others |
Supply & Pricing Matrix
Captive manufacturing of antibody-drug conjugates and immune checkpoint inhibitors by Basel-based pharmaceutical developers anchors both supply security and premium pricing power across European oncology networks. This integration choice insulates against raw material volatility while enabling bundled theranostic contracting that commands price premiums from hospital purchasing consortia.
Pricing Analysis
Warranty and service bundling separates premium antibody-drug conjugate contracts from unbundled chemotherapy procurement across German and French hospital networks. Three-tier pricing structure across premium, standard, and economy levels reflects biomarker validation status, CE-IVD certification tier, and volume commitment scale. Cost compression in platinum-based regimens is intensifying because of concentrated South African and Russian supply sources. Community urology clinics in Italy and Spain exhibit highest price sensitivity due to fragmented procurement authority, while NHS England cancer alliances demonstrate lowest sensitivity through aggregated demand pools.
Supply Chain Analysis
Freight cost escalation for temperature-controlled biologics distribution from Swiss and German manufacturing hubs to Eastern European oncology centers is reshaping regional fulfillment strategies. Active pharmaceutical ingredient production concentrates in Switzerland, Germany, and Ireland for monoclonal antibodies, while platinum group metal refining rests on South African and Russian outputs. Supply chain risk centers on single-source vulnerability for photosensitizer agents used in fluorescence cystoscopy systems. Distribution runs through specialized pharmaceutical wholesalers with cold-chain certification, bypassing general medical device distributors for high-value biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe bladder cancer market sits in a technology-transition phase as liquid biopsy platforms displace repeat cystoscopy for recurrence monitoring. PCR-based circulating tumor DNA detection is replacing legacy fluorescence-guided surveillance in Dutch and Swedish pathology departments.
For Market Incumbents: Acquire automated immunohistochemistry platform capabilities to secure companion diagnostic synchronization with checkpoint inhibitor pipelines. Consolidate manufacturing capacity in the Rhine-Main biotech corridor to capture scale economies against emerging biosimilar threats. Deepen backward integration into platinum group metal sourcing to buffer formulation cost volatility from geopolitical supply disruptions.
For New Entrants and Emerging Players: Enter via underpenetrated Polish and Romanian centralized oncology networks where single-contract procurement frameworks reduce access barriers. Target ambulatory infusion center expansion for outpatient checkpoint inhibitor administration, bypassing entrenched hospital formulary committees. Pursue EU Cancer Plan grant funding to de-risk antibody-drug conjugate development programs before commercial negotiations.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified pharmaceutical conglomerates seeking oncology portfolio breadth. Five-to-ten year viability hinges on biomarker-validated therapeutic positioning rather than commodity chemotherapy exposure. Watch EMA accelerated assessment pathway utilization rates as the inflection signal for pipeline quality and commercial timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-development | Synchronizing PD-L1 assay validation with pembrolizumab timelines secures pathway contracting in German academic centers. |
| EMA Accelerated Assessment Pursuit | Compressing marketing authorization timelines enables earlier patient access across EU member state reimbursement schemes. |
| Liquid Biopsy Platform Launch | PCR-based circulating tumor DNA detection opens ambulatory care channels beyond tertiary hospital networks. |
| Eastern European Network Expansion | Polish and Romanian centralized procurement frameworks offer protected commercial windows for compliant entrants. |
| Manufacturing Scale-Up | Antibody-drug conjugate capacity additions in the Basel region capture demand from NHS England bundled contracts. |
Research Methodology
Independent corroboration across hospital procurement managers, pathology laboratory directors, and regulatory affairs leads underwrites the qualitative findings on companion diagnostic adoption patterns. Primary interviews with formulary directors at German university hospitals, payer access specialists in France, and biomedical engineers in Dutch digital pathology departments combined with secondary validation from EMA submission databases, ClinicalTrials.gov records, and NHS England specialized commissioning frameworks. Bottom-up test volume modeling and top-down therapeutic revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across the analysis window separated volume drivers from price mix effects in immunotherapy displacement of chemotherapy. Segmentation dimensions modeled include treatment line, biomarker status, administration setting, and regional regulatory cluster. CAGRs derived from patient population projections, protocol penetration curves, and reimbursement trajectory assumptions. Forecast inputs incorporated EMA approval probability weightings and health technology assessment timeline distributions across NICE, HAS, and G-BA methodologies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IVDR enforcement disruption or platinum supply chain fragmentation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market