
 Global Clinical Oncology NGS Market | 2026-2036
Global Clinical Oncology NGS Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Oncology NGS Market Foresight
Consolidation among hospital-based molecular pathology programs is repositioning procurement power toward integrated health networks. Illumina leverages its installed base of sequencing systems to sustain recurring consumables revenue across major oncology centers. Thermo Fisher Scientific anchors its position through end-to-end workflow solutions spanning sample preparation to data interpretation. Guardant Health competes in the liquid biopsy segment with specialized assays designed for minimal residual disease monitoring.
Clinical oncology next-generation sequencing encompasses massively parallel DNA sequencing technologies that detect somatic mutations, copy number alterations, and microsatellite instability in tumor specimens with analytical sensitivity reaching variant allele frequencies below one percent. The primary commercial purpose centers on guiding targeted therapy selection, predicting immunotherapy response, and identifying hereditary cancer syndromes in patient care. Sequencing platforms occupy the largest value share given high instrument costs and multi-year service contracts, while bioinformatics software represents the fastest-expanding margin pool as laboratories outsource variant interpretation complexity. Somatic mutation profiling dominates application volume due to broad reimbursement for solid tumor comprehensive genomic testing.
The FDA regulates clinical NGS assays as in vitro diagnostics or laboratory-developed tests depending on commercial distribution model, while the EU In Vitro Diagnostic Regulation imposes stricter conformity assessment for class C devices including oncology companion diagnostics. ISO 15189 accreditation and CAP proficiency testing requirements shape laboratory operational standards across multiple jurisdictions. Stakeholders must monitor evolving payer coverage policies for whole exome sequencing versus targeted gene panels to anticipate revenue mix shifts in clinical testing portfolios.
Market Dynamics
Centralized molecular pathology networks in the United States, Germany, and China are consolidating procurement authority into integrated health systems, compressing vendor negotiation cycles and favoring end-to-end workflow providers over point-solution suppliers.
Growth Catalysts
- FDA companion diagnostic guidelines:The framework accelerates approval pathways for NGS-based tumor profiling assays, reducing time-to-market for precision oncology tests and expanding reimbursable indications.
- Liquid biopsy adoption in academic medical centers:Minimal residual disease monitoring protocols are driving repeat testing volumes and creating recurring revenue streams for specialized assay providers.
- EU In Vitro Diagnostic Regulation:Stricter conformity assessment requirements for class C devices are elevating barriers for low-quality entrants and rewarding manufacturers with robust quality management systems.
Market Restraints
- Sequencing reagent cost volatility:Proprietary consumables from dominant platform vendors lock laboratories into multi-year contracts with limited price transparency or alternative sourcing.
- Bioinformatics talent scarcity:Variant interpretation complexity requires specialized computational biologists and clinical geneticists, constraining laboratory expansion timelines.
- Reimbursement fragmentation:Payer policies for whole exome sequencing versus targeted gene panels vary across Medicare administrative contractors and commercial insurers, creating revenue unpredictability.
Strategic Opportunities
- China's centralized cancer hospital network:The national push for tiered diagnosis and treatment systems creates demand for standardized NGS platforms across provincial oncology centers.
- Artificial intelligence-variant calling convergence:Machine learning algorithms trained on large somatic mutation databases are reducing false positive rates and accelerating report turnaround times.
- Pharmaceutical companion diagnostic partnerships:Co-development agreements for targeted therapy trials provide upfront funding and guaranteed volume commitments for assay developers.
Industry Challenges
- ISO 15189 accreditation timelines:Multi-jurisdictional laboratory certification requirements delay operational launch by 12-18 months for international expansion efforts.
- Legacy LIMS integration complexity:Hospital information systems require custom middleware development to connect NGS data pipelines with electronic health records.
- Variant classification standardization gaps:Inconsistent application of ACMG guidelines across laboratories generates discordant clinical interpretations for identical genomic findings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Oncology NGS Market |
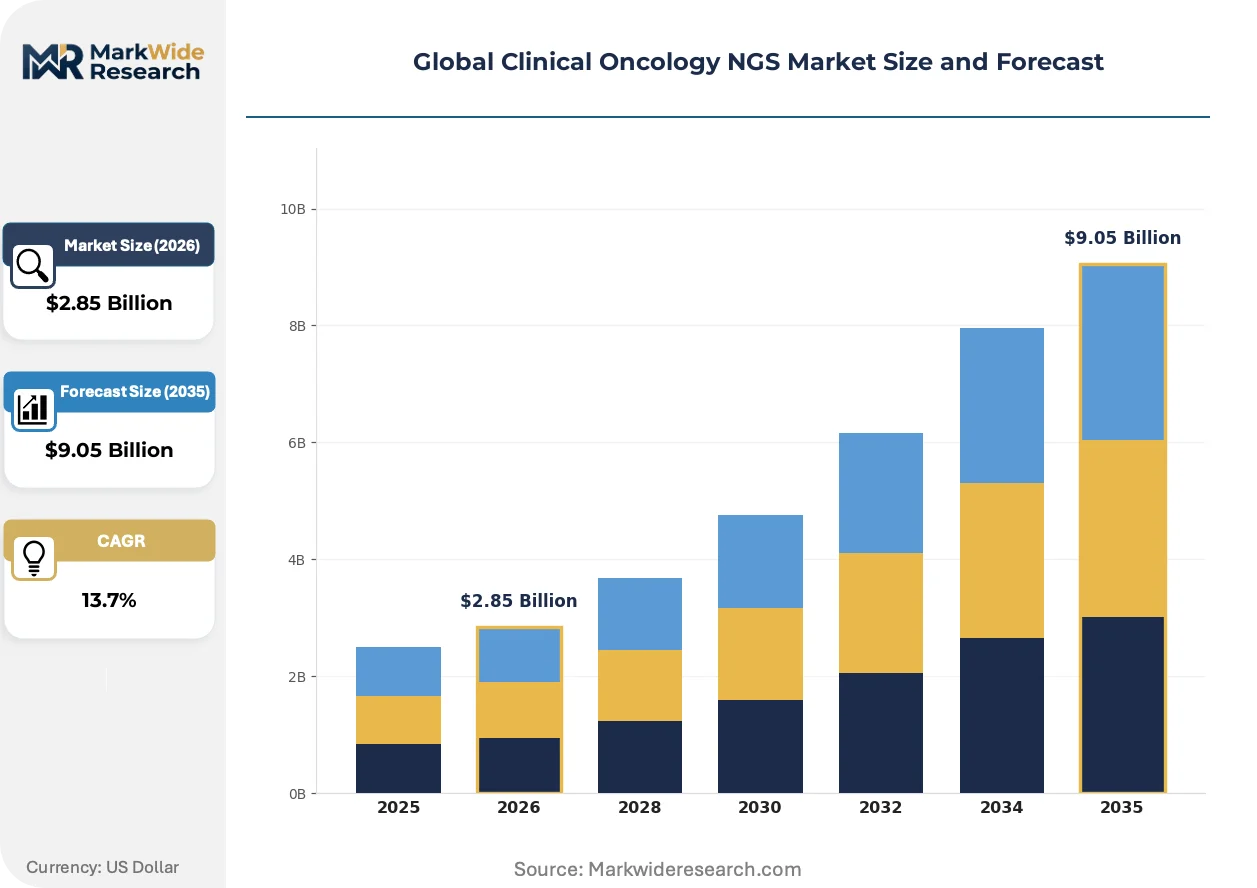
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $9.05 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequencing Platforms, Library Preparation Kits, Bioinformatics Software, Consumables Application: Somatic Mutation Profiling, Germline Mutation Identification, Tumor Mutation Burden Analysis, Minimal Residual Disease Detection, Pharmacogenomics End User: Diagnostic Laboratories, Research Institutes, Contract Research Organizations, Academic Centers Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Managed Services |
| Companies Covered | Illumina, Thermo Fisher Scientific, Guardant Health, Foundation Medicine, QIAGEN, Roche Diagnostics, Agilent Technologies, Pacific Biosciences, ArcherDX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Oncology NGS Market Shifts & Advancements
Platform architecture and regulatory frameworks are converging to reshape how clinical laboratories deploy, validate, and monetize sequencing capacity. Three developments dominate strategic planning.
Amplicon-based targeted panels is modularizing assay design for solid tumor profiling. Community oncology practices and regional reference laboratories are adopting configurable gene content modules that swap biomarker targets without revalidating entire workflows. This architecture is compressing development timelines for indication-specific tests and enabling rapid response to emerging therapeutic targets.
EU In Vitro Diagnostic Regulation's class C device requirements are forcing manufacturers to restructure quality management systems and clinical evidence packages. Oncology companion diagnostics face notified body bottlenecks as conformity assessment capacity concentrates in fewer designated organizations. German and French regulators are prioritizing submissions from vendors with established post-market surveillance infrastructures.
Integrated health networks in the United States are consolidating sequencing procurement through centralized contracting offices. Independent community laboratories face exclusion from preferred vendor lists as health systems standardize on single-platform deployments. This concentration is most visible in Texas and Florida, where large hospital chains have consolidated molecular pathology services into regional hubs.
Global Clinical Oncology NGS Market Segmentation
Segmentation in clinical oncology NGS reveals how procurement authority concentrates around workflow integration, reimbursement eligibility, and regulatory compliance requirements. Laboratories prioritize segments that compress turnaround times while satisfying payer coverage policies and accreditation standards.
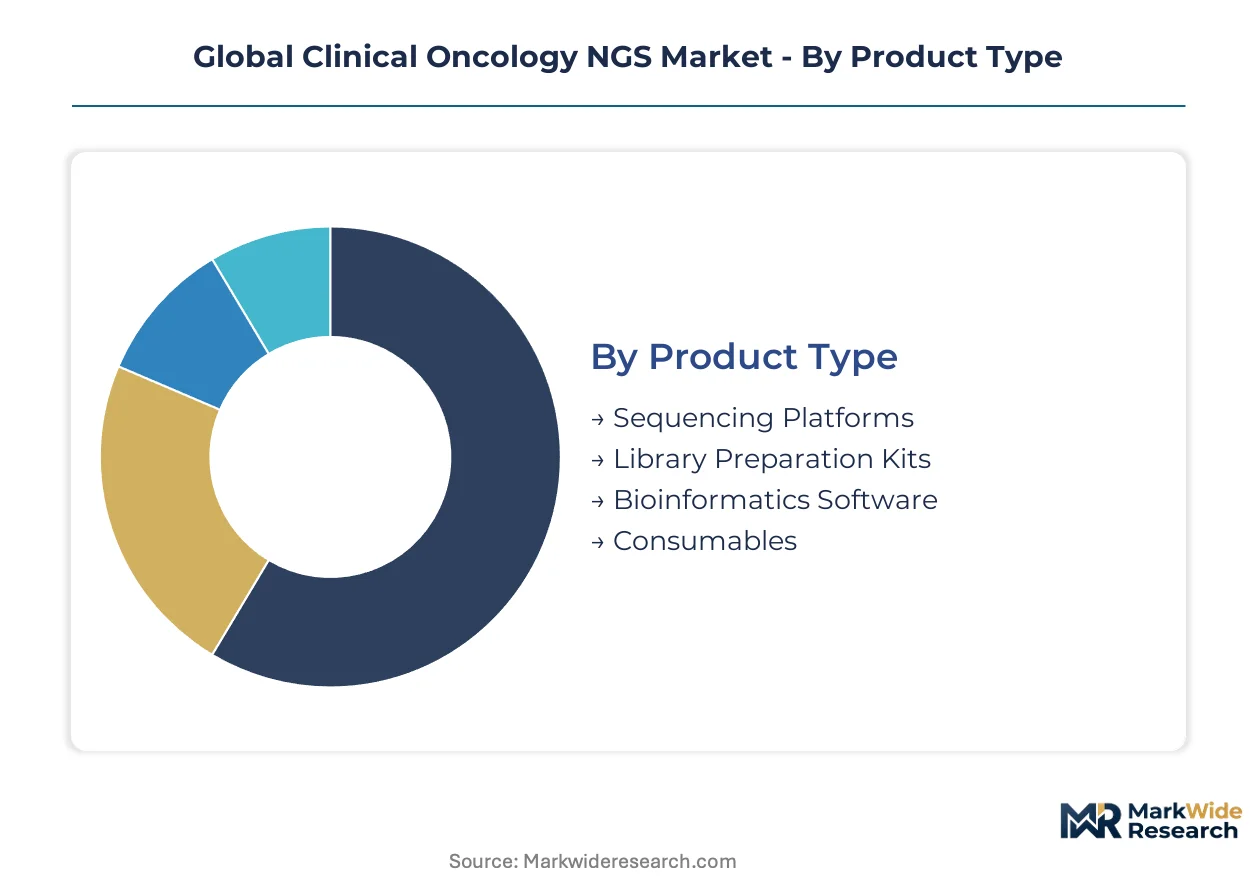
Product Type:
Customization versus standardization tension runs deepest here, with integrated workflow providers locking laboratories into proprietary ecosystems while modular suppliers fight for point-solution niches.
- Sequencing Platforms:Capital-intensive instruments with multi-year service contracts dominate procurement budgets. United States academic medical centers concentrate demand for high-throughput systems supporting comprehensive genomic profiling at scale.
- Library Preparation Kits:Standardized reagent sets enable consistent input processing across specimen types. German reference laboratories drive kit standardization to satisfy ISO 15189 traceability requirements for regulatory submissions.
- Bioinformatics Software:Cloud-deployed variant interpretation tools reduce in-house computational infrastructure. Outsourcing complexity accelerates as laboratories face bioinformatics talent scarcity.
- Consumables:Flow cells, reagents, and quality control materials generate recurring revenue locked to specific instrument footprints. China's provincial cancer centers represent expanding procurement volume as molecular pathology networks centralize.
Leading the category by volume: Sequencing Platforms. Expanding most quickly: Bioinformatics Software.
Application:
Cost tier stratification separates reimbursable solid tumor testing from emerging applications still navigating coverage determination processes.
- Somatic Mutation Profiling:Comprehensive genomic testing of tumor specimens guides FDA-approved targeted therapy selection. Broad Medicare coverage across United States administrative contractors sustains test volume concentration.
- Minimal Residual Disease Detection:Liquid biopsy protocols tracking circulating tumor DNA enable therapy response monitoring. Repeat testing cadences at academic medical centers create recurring revenue streams for specialized assay providers.
- Germline Mutation Identification:Hereditary cancer syndrome detection requires distinct consent and counseling workflows. Clinical utility evidence gaps constrain reimbursement outside high-risk patient populations.
- Tumor Mutation Burden Analysis:Quantifying mutational load predicts immunotherapy response in specific indications. Companion diagnostic co-development partnerships with pharmaceutical sponsors accelerate adoption.
- Pharmacogenomics:Germline variants affecting drug metabolism guide dosing decisions. Integration into electronic health records remains technically fragmented across hospital information systems.
Reimbursement concentration favors: Somatic Mutation Profiling. Steepest expansion trajectory: Minimal Residual Disease Detection.
End User:
Customer type determines procurement sophistication, with integrated health networks extracting volume discounts unavailable to independent operators.
- Diagnostic Laboratories:CAP-accredited facilities process the majority of reimbursed oncology testing. Centralized molecular pathology programs in Texas and Florida hospital chains consolidate purchasing authority.
- Academic Centers:Research-clinical hybrid operations validate novel biomarkers alongside routine diagnostic workflows. NIH funding cycles influence capital equipment refresh timelines.
- Contract Research Organizations:Pharmaceutical trial support demands rapid assay validation for investigational protocols. Companion diagnostic partnerships provide guaranteed volume commitments.
- Research Institutes:Discovery-focused sequencing operates outside clinical regulatory frameworks. Publication pressure drives adoption of cutting-edge platform generations.
Procurement volume concentrates with: Diagnostic Laboratories. Fastest customer segment growth: Contract Research Organizations.
Deployment:
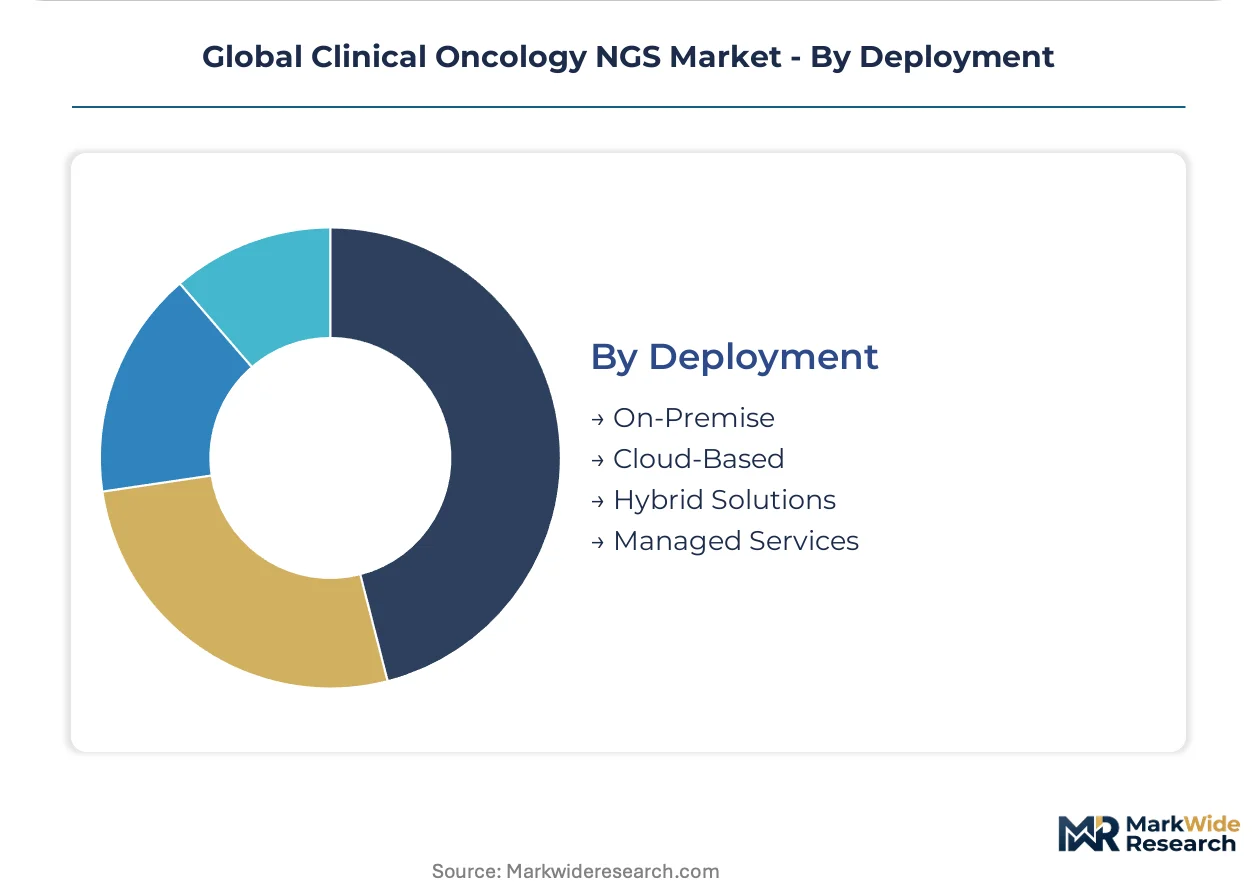
Margin structure varies dramatically across infrastructure models, with cloud solutions capturing software-like economics while on-premise deployments require sustained field service investment.
- On-Premise:Local servers and storage maintain data sovereignty for privacy-sensitive genomic information. German and French regulators prioritize submissions from vendors with established post-market surveillance infrastructures.
- Cloud-Based:Scalable compute resources eliminate capital expenditure for variant interpretation pipelines. China's national push for tiered diagnosis systems creates demand for standardized platform access.
- Hybrid Solutions:Mixed architectures balance local primary analysis with cloud secondary interpretation. Security-conscious laboratories in United States health systems favor this architecture for protected health information segmentation.
- Managed Services:Outsourced end-to-end operations reduce bioinformatics staffing requirements. Small community oncology practices adopt this model to access comprehensive testing without internal expertise investment.
Current infrastructure dominance: On-Premise. Gaining share fastest: Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reagent manufacturing clusters in San Diego, Massachusetts, and the Basel region anchor supply-side capacity for clinical oncology NGS consumables. Procurement gravity concentrates where integrated health networks and national cancer hospital systems centralize molecular pathology infrastructure.
United States
Academic medical centers in Texas and Florida drive demand for high-throughput comprehensive genomic profiling platforms. FDA companion diagnostic guidelines accelerate approval pathways for tumor profiling assays, compressing time-to-market for precision oncology tests. The MD Anderson and Memorial Sloan Kettering networks consolidate purchasing authority through centralized contracting offices.
Germany
Reference laboratories in North Rhine-Westphalia and Bavaria standardize kit validation to satisfy ISO 15189 traceability requirements. The EU In Vitro Diagnostic Regulation imposes stricter conformity assessment for class C oncology companion diagnostics, elevating barriers for low-quality entrants. Berlin and Munich host notified bodies prioritizing submissions from vendors with established post-market surveillance infrastructures.
China
Provincial cancer centers in the Yangtze River Delta and Pearl River Delta expand procurement of standardized NGS platforms under national tiered diagnosis systems. NMPA regulatory pathways for innovative medical devices streamline approval for somatic mutation profiling assays. Beijing and Shanghai anchor molecular pathology networks consolidating testing authority into regional oncology hubs.
Japan
PMDA reimbursement approvals for comprehensive genomic testing sustain test volume at National Cancer Center hospitals in Tokyo and Osaka. METI industrial policy supports domestic sequencing platform development to reduce import dependency for critical diagnostic infrastructure. The Kanto region concentrates bioinformatics talent pools serving clinical variant interpretation pipelines.
United Kingdom
NHS England's Genomic Medicine Service consolidates somatic testing procurement through seven genomic laboratory hubs spanning London, Manchester, and Birmingham. MHRA recognition of FDA-approved companion diagnostics accelerates patient access to targeted therapy selection assays. The Cambridge-Oxford-London triangle anchors pharmaceutical co-development partnerships for trial-enabling NGS assays.
Global Clinical Oncology NGS Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized liquid biopsy and minimal residual disease monitoring applications. Platform vendors with multi-year instrument service contracts lock laboratories into proprietary consumable ecosystems, compressing point-solution supplier margins. Three archetypes dominate: integrated workflow providers spanning sample preparation to data interpretation; modular assay designers offering configurable gene content modules; and cloud-native bioinformatics specialists outsourcing variant interpretation complexity. Competitive moves center on pharmaceutical companion diagnostic co-development agreements and centralized health network procurement consolidation.
Within the integrated workflow tier, Illumina and Thermo Fisher Scientific exemplify platform-centric strategies anchored by installed base expansion and recurring consumables revenue. Guardant Health occupies a specialized position representing the liquid biopsy archetype focused on circulating tumor DNA applications. These three companies span sequencing platform manufacturing, end-to-end clinical workflow solutions, and cancer-specific assay development respectively, illustrating how vendor positioning fragments across technology layers rather than consolidating horizontally.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| Guardant Health |
| Foundation Medicine |
| QIAGEN |
| Roche Diagnostics |
| Agilent Technologies |
| Pacific Biosciences |
| ArcherDX |
| Others |
Supply & Pricing Matrix
Illumina consumables price indices cascade through molecular pathology networks into three distinct procurement tiers, compressing margins for independent laboratories while locking integrated health systems into multi-year service contracts with proprietary reagent ecosystems.
Pricing Analysis
Extended warranty and field service bundling separate premium instrument deployments from unbundled capital purchases, with comprehensive service agreements commanding substantial premiums over break-fix arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15189 accreditation status, throughput scale, and bioinformatics support depth. Cost compression in the economy tier intensifies as Chinese provincial cancer centers negotiate volume discounts for standardized NGS platforms. Academic medical centers exhibit lowest price sensitivity given NIH funding insulation, while community oncology practices face acute budget constraints.
Supply Chain Analysis
Direct-to-hospital sales channels handle high-throughput platform demand from United States academic medical centers, while distributor networks serve smaller European reference laboratories. Manufacturing concentrates in San Diego, Massachusetts, and the Basel region for sequencing reagents and flow cell production. Supply chains draw from semiconductor fabrication for imaging sensors, specialty chemicals for sequencing biochemistry, and precision optics for detection systems. Single-source vulnerability around Illumina's proprietary flow cell technology creates procurement risk for laboratories locked into installed bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical oncology NGS sits at a technology-transition inflection where cloud-native bioinformatics platforms displace on-premise variant interpretation pipelines, compressing timelines from raw data to clinical report.
For Market Incumbents: To counter liquid biopsy specialists eroding solid tumor testing volumes, deepen instrument-locked consumable ecosystems through multi-year service contracts with integrated health networks. Prioritize backward integration into sequencing reagent manufacturing to reduce third-party chemical dependency and defend margin structure against modular assay competitors. For New Entrants and Emerging Players: Artificial intelligence-variant calling convergence offers entry into bioinformatics software segments where talent scarcity constrains incumbent expansion. Target China's provincial cancer centers for cloud-based deployment partnerships under national tiered diagnosis systems. Lead with regulatory-compliant SaaS pricing to bypass capital-intensive platform competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular assay designers with FDA breakthrough device designations in liquid biopsy minimal residual disease monitoring. Long-term viability hinges on pharmaceutical companion diagnostic co-development pipelines guaranteeing volume commitments. Watch NMPA approval timelines for somatic mutation profiling assays as inflection signals for China market access windows.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Companion Diagnostic Partnership | Co-development agreements with Roche and AstraZeneca secure guaranteed assay volumes for targeted therapy trials. |
| Cloud-Native Bioinformatics Platform Launch | Scalable variant interpretation reduces laboratory computational infrastructure requirements across China's tiered diagnosis network. |
| EU IVDR Class C Device Certification | Notified body approval from Berlin and Munich regulators unlocks oncology companion diagnostic commercialization. |
| Integrated Health Network Consolidation | Centralized contracting with Texas and Florida hospital chains compresses vendor negotiation cycles toward end-to-end providers. |
| Artificial Intelligence Variant Calling Investment | Machine learning algorithms trained on MSK-IMPACT data reduce false positive rates and accelerate report turnaround. |
Research Methodology
Multi-period observation of FDA PMA approval timelines, CMS coverage determination patterns, and NMPA innovative device registrations anchored the trend analysis, supplemented by interviews with molecular pathology laboratory directors, hospital procurement committee chairs, bioinformatics pipeline engineers, and pharmaceutical companion diagnostic alliance managers. Secondary validation drew from FDA 510(k) and PMA databases, EMA scientific advice letters, ClinicalTrials.gov protocol registries, and CMS Medicare coverage database extracts. Bottom-up laboratory capacity modeling triangulated against top-down health system expenditure tracking.
Input-output matrices mapped sequencing platform installed bases through reagent consumption rates into revenue pool estimates across the projection horizon. Segmentation dimensions included product type, application workflow, end-user facility category, and deployment architecture. CAGRs derived from logistic diffusion curves fitted to technology adoption S-cycles, with sensitivity testing around reimbursement policy shifts and regulatory approval velocity. Forecast inputs incorporated pharmaceutical pipeline biomarker targets and health system consolidation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA enforcement discretion changes or EU IVDR notified body capacity constraints. Practitioners should monitor CMS national coverage determination updates for whole exome sequencing and NMPA approval velocity for innovative medical devices as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market