
 US Pancreatic Cancer Diagnostics Market | 2026-2036
US Pancreatic Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
US Pancreatic Cancer Diagnostics Market Analytics
Consolidation among hospital procurement networks is realigning vendor selection criteria toward integrated diagnostic platforms. Thermo Fisher Scientific sustains broad reagent and instrument portfolios that span histopathology through next-generation sequencing. Myriad Genetics specializes in hereditary cancer risk assessment, anchoring its position in germline testing for pancreatic cancer susceptibility syndromes. Illumina dominates sequencing infrastructure deployment, controlling the analytical backbone that most molecular diagnostic laboratories operate upon.
Pancreatic cancer diagnostics encompasses imaging modalities, tissue and liquid biopsy analysis, and molecular profiling technologies used to detect, stage, and characterize pancreatic ductal adenocarcinoma and its precursors. CT scanning with multiphase pancreatic protocol delivers spatial resolution of 2-3 millimeters for lesion detection, while endoscopic ultrasound enables fine-needle aspiration with real-time tissue acquisition. Genetic testing segments leverage circulating tumor DNA platforms that compete with tissue-based assays for treatment-naïve patient stratification. Imaging maintains the largest volume footprint due to established reimbursement and clinical workflow integration, though blood test segments attract disproportionate R&D investment.
FDA breakthrough device designations accelerate market access for novel diagnostics, while CMS national coverage determinations govern Medicare reimbursement for molecular profiling tests. CLIA laboratory certification requirements shape quality standards for high-complexity testing performed at Laboratory Corporation of America Holdings and competing reference laboratories. Stakeholders must monitor evolving FDA guidance on companion diagnostic co-development requirements and state-level laboratory licensing harmonization.
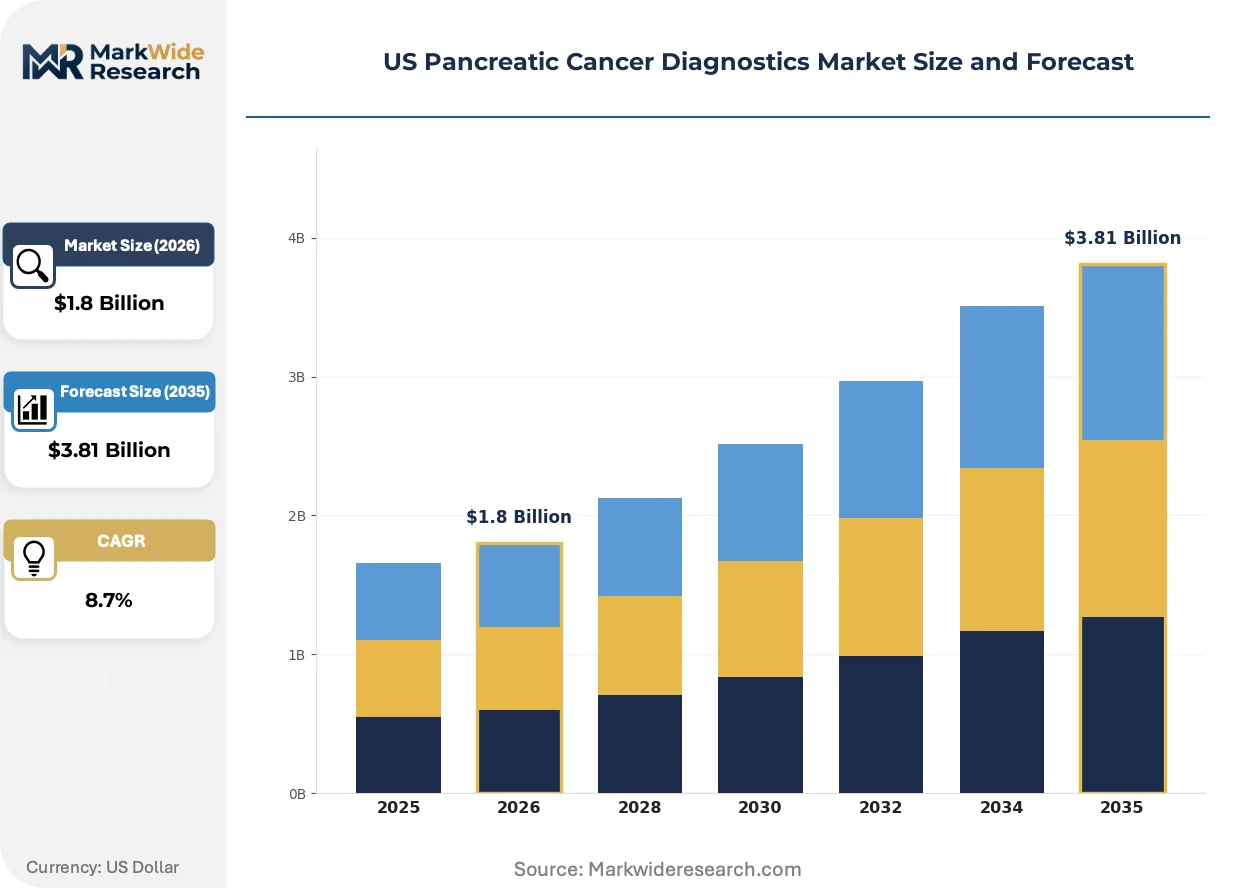
Market Dynamics
Hospital procurement consolidation is compressing vendor selection timelines and favoring integrated platform providers over point-solution specialists across the US pancreatic cancer diagnostics landscape.
Growth Catalysts
- Medicare Coverage Expansion:CMS national coverage determinations for liquid biopsy assays are unlocking reimbursement pathways for treatment-naïve patient stratification.
- Massachusetts Biotech Clusters:Concentrated R&D investment in the Northeast corridor accelerates FDA breakthrough device designations and commercialization timelines.
- Next-Generation Sequencing Infrastructure:Declining per-run costs for molecular profiling are expanding access to comprehensive genomic testing beyond academic medical centers.
Market Restraints
- Reagent Supply Concentration:Critical enzymatic reagents for PCR-based assays originate from a limited supplier base, creating vulnerability to batch-to-batch variability.
- CLIA Laboratory Certification Friction:State-level licensing harmonization gaps delay high-complexity test validation and interstate specimen transport compliance.
- Imaging Modality Lock-in:Established CT and MRI reimbursement codes create substitution resistance against emerging blood-based screening platforms.
Strategic Opportunities
- Community Hospital Penetration:Underserved metropolitan health systems in the Southeast and Southwest present whitespace for decentralized molecular testing deployment.
- FDA Companion Diagnostic Co-Development:Parallel therapeutic-diagnostic approval pathways offer regulatory tailwinds for precision oncology assay developers.
- Artificial Intelligence-Enabled Pathology:Convergence of digital slide imaging with machine learning algorithms creates automated diagnostic interpretation capabilities.
Industry Challenges
- Computational Pathology Talent Scarcity:Shortage of bioinformaticians trained in somatic variant interpretation limits laboratory expansion capacity.
- Specimen Preanalytics Standardization:Circulating tumor DNA collection protocols vary across health systems, introducing preanalytical variability that complicates assay validation.
- Electronic Health Record Integration Complexity:Molecular test results require structured data formatting that legacy hospital IT infrastructure struggles to accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pancreatic Cancer Diagnostics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging, Blood Tests, Biopsy, Endoscopic Ultrasound Technology: CT Scans, MRI, PET Scans, Genetic Testing End User: Hospitals, Diagnostic Laboratories, Cancer Treatment Centers, Academic Research Institutes Delivery Mode: In-Hospital Testing, At-Home Testing, Remote Monitoring, Point-of-Care Testing |
| Companies Covered | F. Hoffmann-La Roche Ltd., Abbott, Thermo Fisher Scientific, Inc., Myriad Genetics, Inc., BD, QIAGEN, Agilent Technologies, Inc., Laboratory Corporation of America Holdings, Illumina, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pancreatic Cancer Diagnostics Market Evolving Landscape
Liquid biopsy platforms are compressing diagnostic timelines and enabling serial monitoring capabilities that tissue-based assays cannot match. Three interconnected developments are restructuring competitive positioning.
Multi-cancer early detection panels are decentralizing screening access from specialized oncology centers to primary care workflows. Community health systems in Texas and Florida are piloting blood-draw collection protocols that feed into centralized CLIA laboratories. This shift is compressing the geographic radius between specimen collection and molecular analysis.
FDA breakthrough device designations for pancreatic cancer-specific assays are accelerating premarket review timelines while CMS parallel coverage determinations lock in reimbursement codes. The industrial consequence is a compressed path from clinical validation to commercial deployment. Academic medical centers in New York and California are responding by restructuring their technology assessment committees to evaluate designated devices on accelerated schedules.
Health system procurement committees are consolidating molecular diagnostics spend under single-source agreements with integrated platform vendors. Group purchasing organizations are displacing individual hospital laboratory directors as the primary decision-makers for instrument acquisition. This concentration is most visible in the Northeast corridor, where Massachusetts-based hospital networks are negotiating enterprise-wide sequencing contracts.
US Pancreatic Cancer Diagnostics Market Segmentation
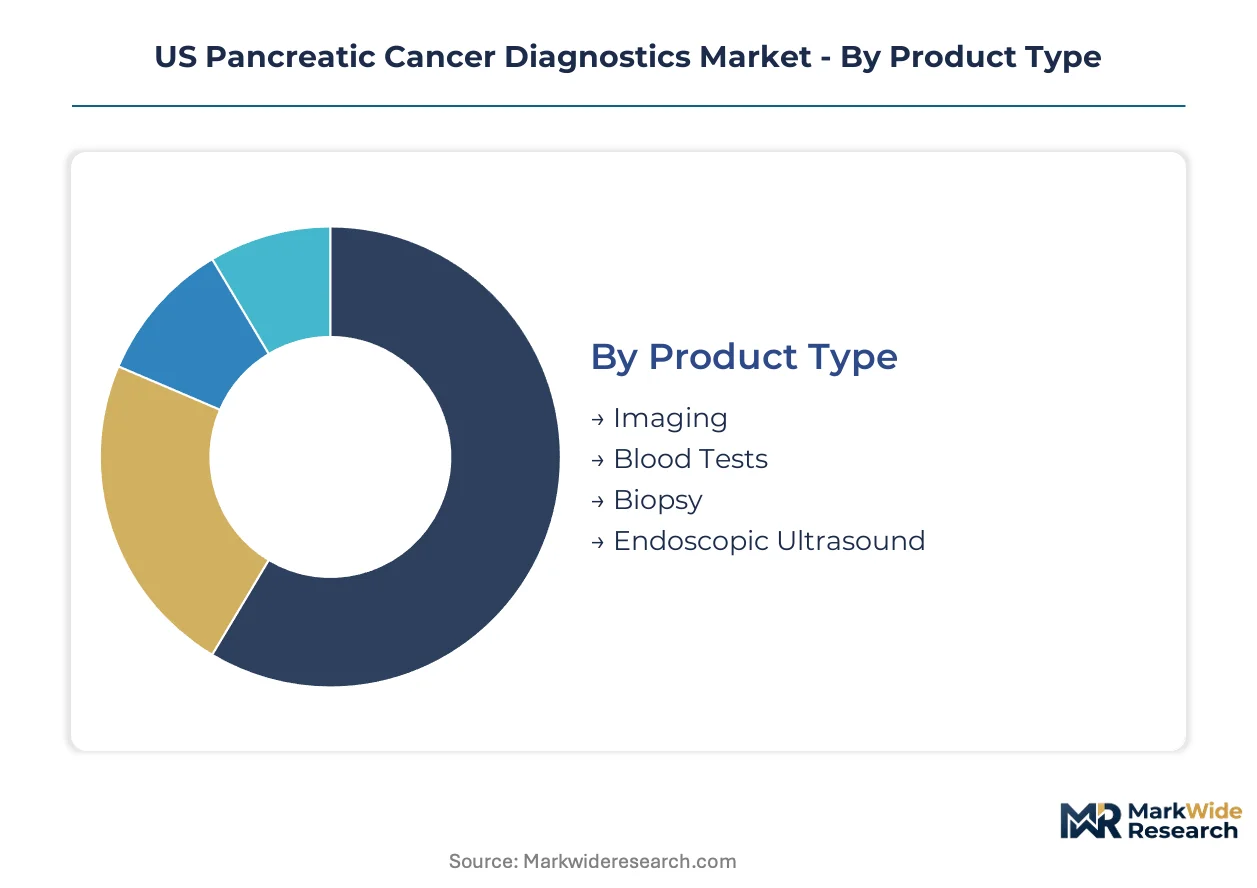
Diagnostic modality selection in pancreatic cancer hinges on reimbursement codes, CLIA certification requirements, and FDA breakthrough device pathways. Procurement committees weight capital expenditure against per-test economics when segmenting spend across imaging infrastructure and molecular platforms.
Product Type:
FDA 510(k) clearance and CMS national coverage determinations create divergent certification burdens across these four segments. Imaging modalities carry established reimbursement codes, while blood-based assays navigate parallel FDA-CMS approval timelines.
- Imaging:Multiphase CT protocols with 2-3 millimeter spatial resolution anchor initial lesion detection workflows at Massachusetts General Hospital and Memorial Sloan Kettering. Northeast corridor health systems concentrate procurement for these capital-intensive systems under enterprise-wide radiology contracts.
- Blood Tests:Circulating tumor DNA platforms enable serial monitoring without repeated tissue acquisition, compressing diagnostic timelines for treatment-naïve patient stratification. FDA breakthrough designations for pancreatic-specific liquid biopsies are accelerating Medicare coverage determinations at academic medical centers in California and New York.
- Biopsy:Tissue-based molecular profiling requires CLIA high-complexity laboratory certification and specialized pathologist interpretation.
- Endoscopic Ultrasound:Real-time fine-needle aspiration demands gastroenterologist training programs and dedicated endoscopy suite infrastructure.
Imaging sits at the top of the volume ranking, with blood tests climbing the fastest.
Technology:
Per-scan economics and throughput capacity segment these modalities across community hospital versus academic medical center deployment. Cost tiers separate high-volume CT screening from premium-priced PET-based metabolic assessment.
- CT Scans:Pancreatic protocol CT delivers sub-millimeter slice thickness with dual-energy capabilities for iodine quantification. Texas and Florida community health systems are expanding CT capacity to reduce referral leakage to tertiary centers.
- MRI:Magnetic resonance cholangiopancreatography enables non-invasive ductal assessment without ionizing radiation, capturing demand from younger patient cohorts and serial monitoring protocols at Stanford and Cedars-Sinai.
- PET Scans:FDG-avid lesion characterization supports staging decisions with metabolic activity mapping.
- Genetic Testing:Germline and somatic profiling requires next-generation sequencing infrastructure and bioinformatics pipelines.
CT scans command the highest procedure volume, with genetic testing expanding most quickly as NGS costs decline.
End User:
Customer type determines procurement authority, with group purchasing organizations displacing individual laboratory directors at consolidated hospital networks. Specimen volume and case complexity shape vendor selection criteria.
- Hospitals:Integrated delivery networks in the Northeast corridor consolidate molecular diagnostics spend under single-source agreements with Thermo Fisher and Illumina, compressing vendor selection timelines for sequencing infrastructure.
- Diagnostic Laboratories:Laboratory Corporation of America Holdings and Quest Diagnostics operate CLIA-certified high-complexity testing facilities that process specimens from community health systems lacking in-house molecular capabilities.
- Cancer Treatment Centers:Specialized oncology centers demand rapid turnaround times for treatment-naïve patient stratification.
- Academic Research Institutes:Dana-Farber and MD Anderson drive assay development through investigator-initiated trials and FDA breakthrough device co-development partnerships.
Hospitals anchor the volume base, with cancer treatment centers gaining share fastest through vertical integration of diagnostic and therapeutic services.
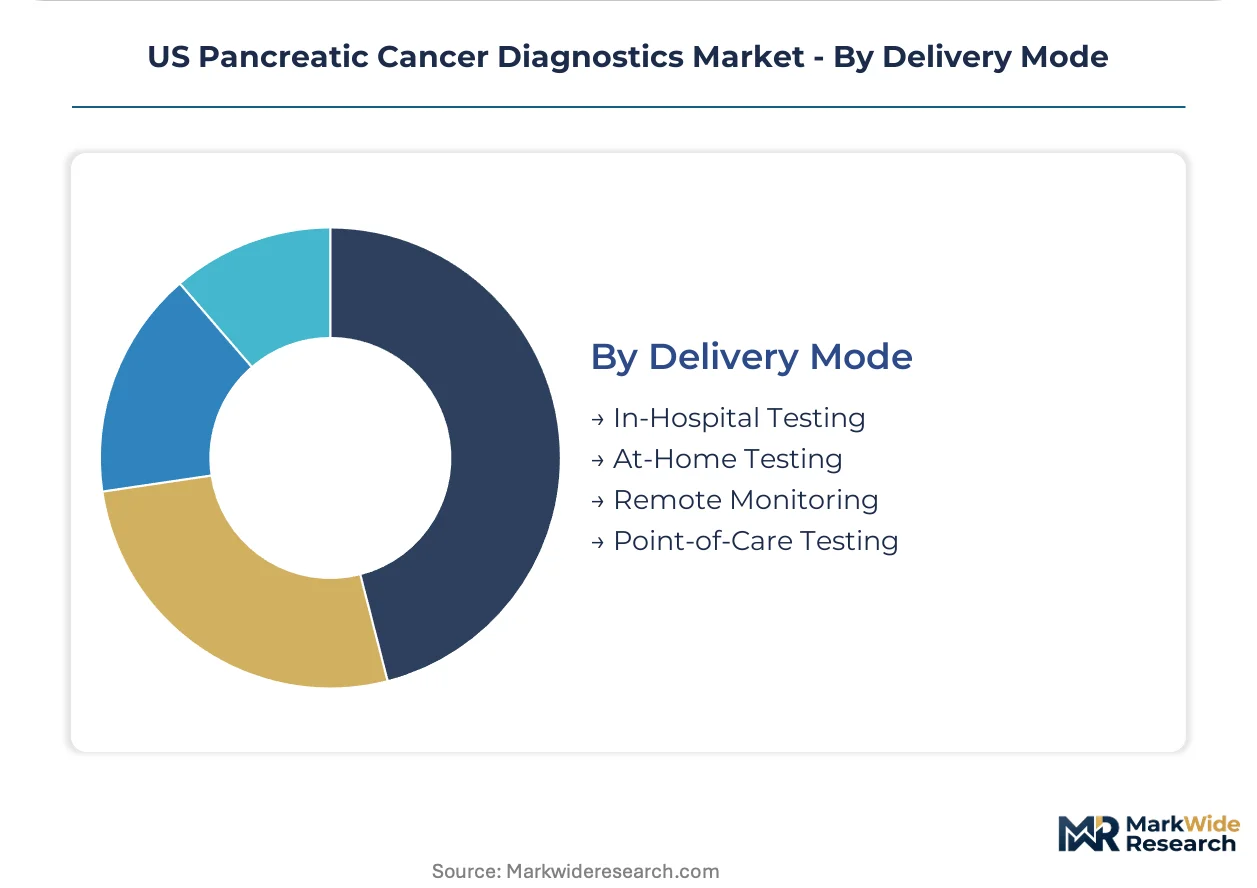
Delivery Mode:
Geographic penetration separates centralized laboratory models from decentralized point-of-care deployment. Rural access gaps and urban health system density create divergent infrastructure requirements.
- In-Hospital Testing:On-site histopathology and molecular diagnostics laboratories at Johns Hopkins and Mayo Clinic deliver sub-48-hour turnaround times for urgent treatment decisions, justifying capital investment through case volume concentration.
- At-Home Testing:Blood-draw collection kits for circulating tumor DNA analysis are piloting in Texas and Florida community health systems, extending screening access beyond metropolitan oncology centers.
- Remote Monitoring:Digital pathology platforms enable specialist consultation across state lines.
- Point-of-Care Testing:Rapid biomarker assays in emergency department settings support acute pancreatitis differential diagnosis.
In-hospital testing dominates procedure volume, with at-home testing showing the steepest expansion trajectory as collection logistics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts biotech clusters and Texas medical centers anchor workforce concentration for pancreatic cancer diagnostics development and deployment across distinct US sub-regions.
Northeast Corridor
Massachusetts General Hospital and Memorial Sloan Kettering drive demand for multiphase CT protocols and molecular profiling platforms. FDA breakthrough device designations accelerate through Boston-based regulatory consulting networks. The Massachusetts biotech cluster concentrates liquid biopsy R&D along Route 128 corridor.
Southeast
Florida community health systems and Georgia hospital networks present whitespace for decentralized molecular testing deployment. State-level CLIA laboratory licensing harmonization gaps create compliance friction for interstate specimen transport. The MD Anderson satellite network in Houston anchors precision oncology infrastructure across Texas Gulf Coast.
California
Stanford and Cedars-Sinai capture demand for MRI-based serial monitoring protocols among younger patient cohorts. CMS national coverage determinations for liquid biopsy assays unlock reimbursement at academic medical centers in Los Angeles and San Francisco. The Bay Area biotech corridor feeds computational pathology talent into diagnostic laboratories.
Southwest
Texas community health systems pilot at-home blood-draw collection kits for circulating tumor DNA analysis. Group purchasing organizations consolidate molecular diagnostics spend across Dallas-Fort Worth and Houston metropolitan networks. The Texas Medical Center anchors high-complexity testing capacity for the broader region.
Midwest
Mayo Clinic and Johns Hopkins regional affiliates concentrate case volume for urgent sub-48-hour turnaround diagnostics. Hospital procurement consolidation compresses vendor selection timelines across Illinois and Ohio integrated delivery networks. The Cleveland Clinic anchors histopathology and molecular diagnostics laboratory infrastructure.
US Pancreatic Cancer Diagnostics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument, reagent, and service segments. Thermo Fisher Scientific and Illumina occupy integrated platform positions spanning sequencing infrastructure through consumables. Three archetypes structure competitive positioning: full-stack instrumentation vendors, specialized assay developers, and reference laboratory service providers. Consolidation among hospital procurement networks favors enterprise-wide contracting over point-solution procurement.
Among diversified life science conglomerates, F. Hoffmann-La Roche Ltd. and Abbott occupy positions spanning diagnostics through therapeutics. Thermo Fisher Scientific, Inc. anchors the instrumentation-reagent integrated tier. Laboratory Corporation of America Holdings and Quest Diagnostics exemplify the reference laboratory service archetype processing specimens from community health systems lacking in-house molecular capabilities.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Abbott |
| Thermo Fisher Scientific, Inc. |
| Myriad Genetics, Inc. |
| BD |
| QIAGEN |
| Agilent Technologies, Inc. |
| Laboratory Corporation of America Holdings |
| Illumina, Inc. |
| Others |
Value Network & Pricing Analysis
Bioinformatician workforce concentration in the Boston-Cambridge corridor widens pricing-tier spreads between academic medical centers and community hospitals, as labor-cost differentials for somatic variant interpretation compress margins at lower-volume sites while premium-tier institutions absorb specialized talent premiums.
Pricing Analysis
Bundled enterprise-wide sequencing contracts dominate procurement at consolidated hospital networks, while unbundled per-test pricing persists at standalone community laboratories. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with sub-48-hour turnaround guarantees from regional hospitals with 5-7 day standard service and reference laboratories with economy batch processing. Price differentiation stems from CLIA high-complexity certification tier and bioinformatics pipeline sophistication. Pricing pressure intensifies as group purchasing organizations consolidate molecular diagnostics spend and squeeze reagent margins. Community health systems exhibit highest price sensitivity, while specialized cancer treatment centers prioritize turnaround speed over per-test economics.
Supply Chain Analysis
Critical enzymatic reagents for PCR-based assays rest on concentrated specialty chemical production in Germany, Japan, and the United States, with thermostable DNA polymerases and fluorescent probe chemistries sourced from limited qualified suppliers. Next-generation sequencing flow cells, nucleotide reagents, and library preparation kits draw from Illumina's San Diego manufacturing base and Thermo Fisher's Massachusetts production network. Single-source vulnerability for sequencing instrument consumables creates exposure to batch-to-batch variability and allocated supply during demand surges. Distribution runs through direct vendor-to-laboratory contracts for high-volume academic centers, with regional distributors serving fragmented community hospital demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand shifting toward FDA breakthrough device-designated assays that command premium reimbursement and lock in preferred vendor status at consolidated procurement committees.
For Market Incumbents: Lock in long-term reagent supply agreements with enzymatic component manufacturers to insulate against batch variability that disrupts CLIA laboratory certification timelines. Deepen backward integration into bioinformatics pipeline development to offset computational pathology talent scarcity that constrains laboratory expansion capacity. Defend against point-of-care testing substitution by embedding sequencing infrastructure within hospital IT systems through structured data formatting integration. For New Entrants and Emerging Players: Underserved community health systems in Texas and Florida present whitespace for decentralized molecular testing deployment with at-home blood-draw collection logistics. Target FDA companion diagnostic co-development partnerships with oncology therapeutic developers to accelerate premarket review timelines and secure parallel CMS coverage determinations. Pursue group purchasing organization vendor qualification as the fastest path to enterprise-wide contracting at consolidated hospital networks. For Investors and Strategic Acquirers: Integrated diagnostics conglomerates with sequencing-through-service capabilities are the most active acquirers in this space, seeking specialized liquid biopsy assay developers to fill portfolio gaps. Acquisition target archetype: CLIA-certified laboratories with established Medicare reimbursement codes and validated circulating tumor DNA platforms. Watch FDA breakthrough device designation velocity as the inflection indicator for reimbursement pathway clarity and commercial deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated premarket review compresses path from clinical validation to Medicare coverage determination at academic medical centers. |
| CMS National Coverage Determination | Locks in reimbursement codes for liquid biopsy assays, unlocking treatment-naïve patient stratification economics. |
| Hospital System Partnership | Enterprise-wide sequencing contracts with Massachusetts General Hospital displace point-solution procurement. |
| Software Companion Development | Structured data formatting integration with Epic and Cerner EHR systems reduces IT infrastructure friction. |
| Reimbursement Strategy | Parallel FDA-CMS approval timelines for companion diagnostics capture precision oncology assay premiums. |
Research Methodology
Coverage spans the Northeast corridor, California, Texas, and the Midwest, with primary inputs from each region combining structured interviews with hospital procurement managers, CLIA laboratory directors, GPO contracts specialists, and FDA regulatory consultants with secondary validation against CMS Medicare reimbursement databases, FDA 510(k) and breakthrough device filings, and hospital procurement system records. Bottom-up testing volume estimates triangulate against top-down market sizing derived from instrument installed base and per-run economics.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon, with segmentation modeling across imaging modality, molecular platform technology, end-user type, and delivery mode dimensions. CAGRs derive from weighted average of historical reimbursement trend analysis and forward-looking regulatory pathway assessments. Forecast inputs include FDA breakthrough device designation velocity, CMS national coverage determination timelines, and hospital network consolidation trajectories.
Underlying measurement precision varies by segment; imaging modality volumes carry tighter precision than emerging blood-based assay projections due to established reimbursement code history. Forecasts reflect documented assumptions regarding regulatory approval timelines and procurement consolidation velocity. Material deviation in FDA guidance on companion diagnostic co-development requirements or state-level CLIA laboratory licensing harmonization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Global Clinical Oncology NGS Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Cancer Diagnostics Market