
 Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market | 2026-2036
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market Outlook
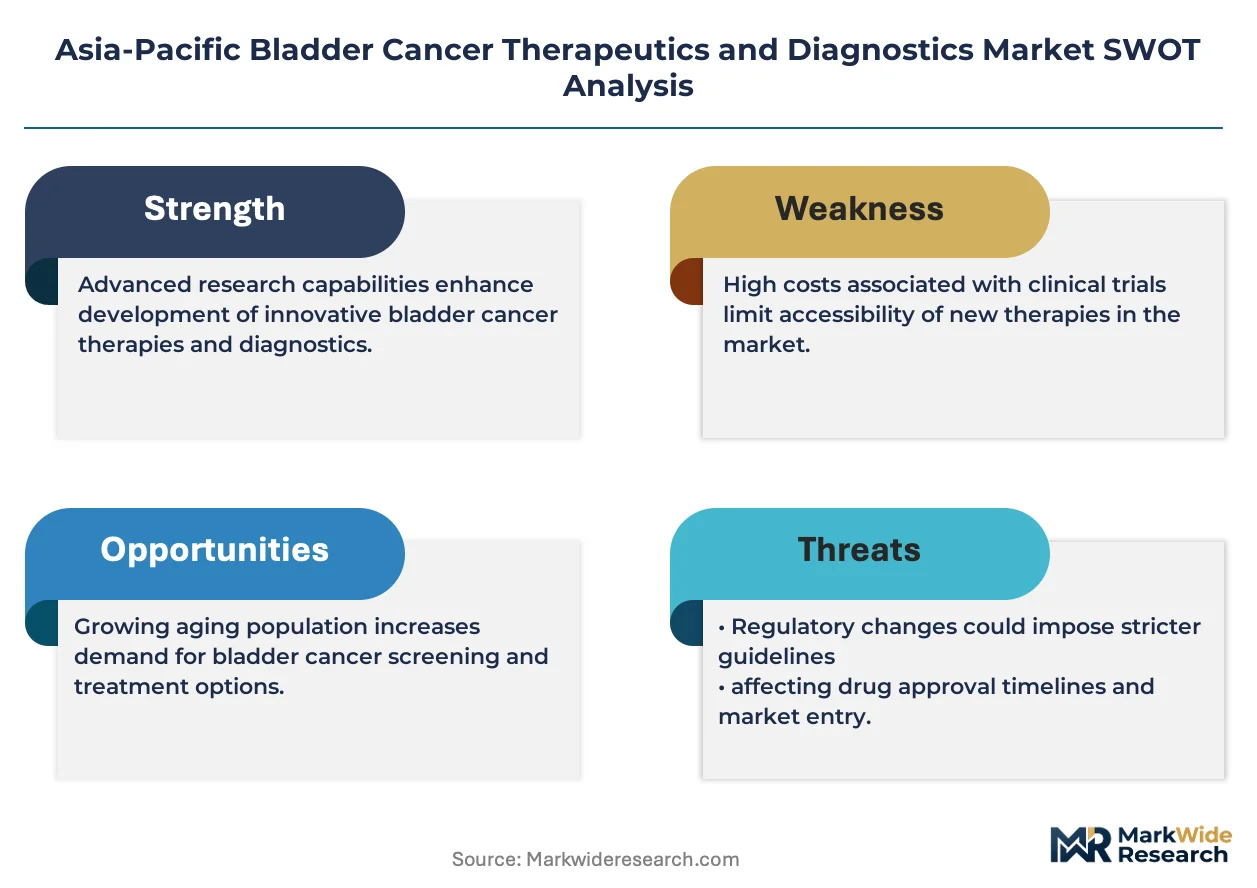
A transition from single-source antibody supply to multi-source biologics procurement is shifting procurement dynamics across Asia-Pacific oncology networks. Bristol-Myers Squibb leverages its immuno-oncology manufacturing footprint to sustain regional supply commitments for checkpoint inhibitors. Astellas Pharma anchors its position through deep urology specialization and established clinician relationships across Japanese and Korean hospital systems. Pfizer competes via broad portfolio coverage spanning both branded and biosimilar chemotherapy agents.
Asia-Pacific bladder cancer therapeutics and diagnostics encompasses pharmaceutical interventions, medical devices, and laboratory services targeting malignant neoplasms of the urinary bladder wall, with diagnostic protocols requiring cystoscopic visualization combined with urine cytology and emerging biomarker panels for recurrence monitoring. The primary commercial purpose centers on extending progression-free survival in non-muscle-invasive cases while improving early detection rates to reduce cystectomy incidence. Immunotherapy commands premium positioning within the product type dimension as PD-1/PD-L1 inhibitors displace BCG in high-risk patient strata. Intravesical delivery mode retains structural importance for localized disease management, though systemic administration expands as muscle-invasive presentations grow in detected prevalence across aging populations in Australia and South Korea.
Japan's PMDA, Australia's TGA, and China's NMPA each maintain distinct clinical evidence requirements that fragment trial design and registration timelines for multinational sponsors seeking broad Asia-Pacific labeling. PMDA's sakigake designation and NMPA's breakthrough therapy pathways create accelerated access corridors that reshape competitive sequencing across the region. Stakeholders must monitor evolving reimbursement negotiations between national health insurance schemes and manufacturers, as pricing agreements in Japan and South Korea typically establish reference benchmarks that cascade through adjacent markets.
Market Dynamics
The transition from BCG-based intravesical therapy to checkpoint inhibitor protocols is restructuring treatment hierarchies across Asia-Pacific oncology networks, with reimbursement negotiations now preceding clinical adoption curves.
Growth Catalysts
- PMDA Sakigake Pathway:Japan's breakthrough therapy designation compresses regulatory review timelines for novel immuno-oncology agents, accelerating commercial launch sequencing ahead of regional competitors.
- Molecular Diagnostic Platforms:Hospital-based pathology departments in Chinese tier-one cities are integrating next-generation sequencing panels for recurrence monitoring, expanding addressable testing volumes.
- Aging Demographics:South Korea and Australia report rising muscle-invasive bladder cancer detection rates as population screening protocols expand to cover adults over sixty-five.
Market Restraints
- BCG Supply Concentration:Global production of bacillus Calmette-Guérin concentrates among two manufacturers, creating vulnerability for Asia-Pacific clinics dependent on intravesical immunotherapy protocols.
- Biomarker Validation Gaps:Urine-based diagnostic assays lack standardized regulatory acceptance criteria across NMPA, TGA, and PMDA jurisdictions, fragmenting clinical evidence requirements.
- Specialist Workforce Constraints:Urological oncology fellowship programs in India and Southeast Asia produce insufficient trained cystoscopists to match expanding screening program targets.
Strategic Opportunities
- Biosimilar Infusion:China's NMPA accelerated approval framework for oncology biosimilars creates entry corridors for domestic manufacturers to capture BCG-replacement demand.
- Telepathology Networks:Cloud-based diagnostic image sharing between Australian regional hospitals and centralized pathology hubs reduces specialist consultation turnaround times.
- Liquid Biopsy Integration:Convergence of circulating tumor DNA detection with cystoscopic surveillance protocols enables non-invasive recurrence monitoring for high-risk patient strata.
Industry Challenges
- Multi-Jurisdictional Trial Design:Sponsors must reconcile divergent primary endpoint requirements between PMDA, TGA, and NMPA, inflating clinical development costs for Asia-Pacific labeling.
- Cold Chain Infrastructure:Temperature-controlled distribution for biologic therapeutics remains underdeveloped in Indonesian and Philippine hospital networks, constraining addressable geography.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market |
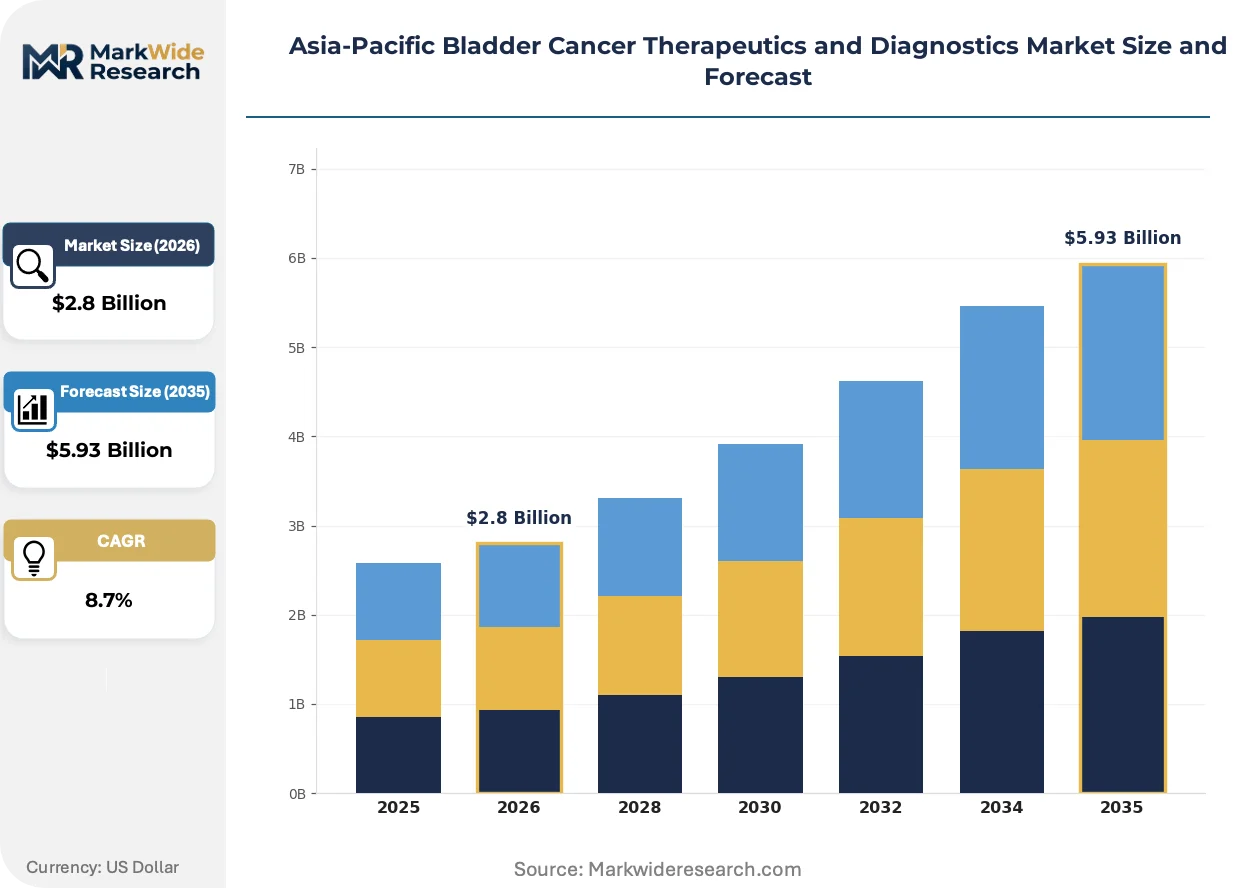
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Radiation Therapy, Diagnostics Therapy Area: Early-stage, Muscle-invasive, Non-muscle-invasive, Advanced disease End User: Hospitals, Specialty Clinics, Research Laboratories, Home Care Delivery Mode: Intravesical, Systemic, Oral, Injectable |
| Companies Covered | Bristol-Myers Squibb Company, Astellas Pharma Inc., F. Hoffmann-La Roche Ltd, Pfizer, Eisai Co., Ltd., Johnson & Johnson, Endo Pharmaceuticals Inc., Merck & Co., AstraZeneca Plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market Strategic Shifts
Digital pathology platforms and AI-assisted cytology screening are compressing diagnostic timelines while restructuring labor allocation across Asia-Pacific hospital laboratories.
Multiplexed immunohistochemistry staining panels for PD-L1 and FGFR3 biomarker detection are modularizing diagnostic workflows in Japanese and Korean reference laboratories. Pathologists now integrate automated scoring algorithms with traditional morphological assessment, reducing inter-observer variability in treatment eligibility determination. This modularization enables smaller regional hospitals to outsource complex molecular characterization to centralized hubs.
Australia's TGA has implemented parallel evaluation pathways for companion diagnostics paired with breakthrough oncology therapies, synchronizing device and drug approval timelines. Manufacturers now submit coordinated evidentiary packages rather than sequential applications, compressing total time-to-reimbursement by eight to twelve months. Korean MFDS is observing this model for potential adoption in its own oncology review procedures.
Chinese cancer centers are consolidating procurement authority at the provincial level, displacing hospital-level purchasing autonomy for high-cost therapeutics. Pharmaceutical manufacturers now negotiate directly with provincial health security bureaus rather than individual institutions, compressing price realization but expanding volume commitments. This concentration is most advanced in Guangdong and Jiangsu provinces, where centralized tendering covers over eighty percent of bladder cancer drug expenditure.
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market Segmentation
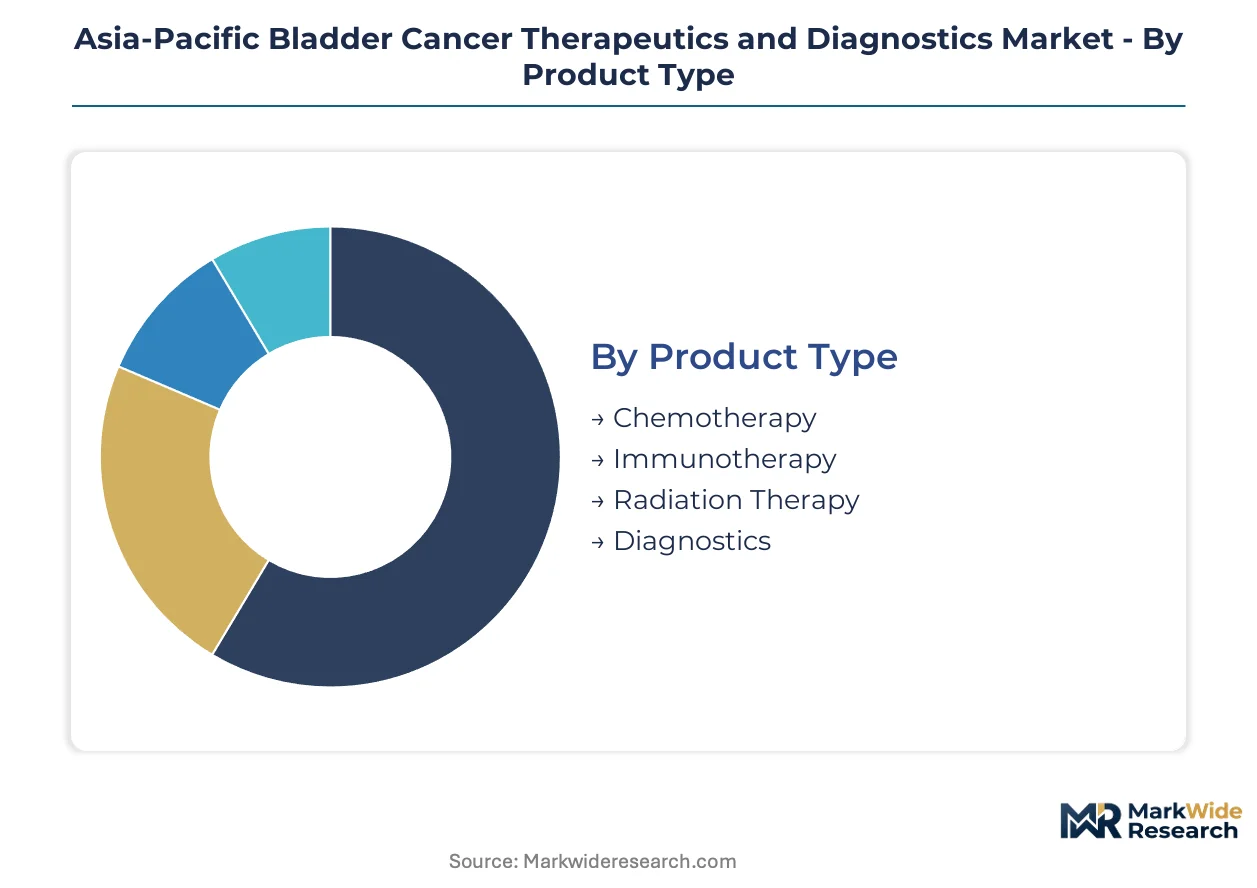
Bladder cancer therapeutics and diagnostics in the Asia-Pacific region fragment across therapeutic modality, disease staging, care setting, and administration route. Each axis carries distinct procurement logic, regulatory pathway requirements, and reimbursement negotiation dynamics that shape commercial strategy.
Product Type:
Technology sophistication and manufacturing complexity differentiate competitive positioning across therapeutic categories.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors target programmed cell death pathways with intravenous administration protocols. Demand concentrates in Japanese university hospitals where PMDA's sakigake pathway accelerates access, though cold chain requirements constrain distribution into Indonesian and Philippine networks.
- Chemotherapy:Platinum-based agents and taxanes remain foundational for neoadjuvant and metastatic protocols. China's NMPA accelerated biosimilar approvals are reshaping procurement in Guangdong and Jiangsu provincial tenders, compressing price realization while expanding volume access.
- Radiation Therapy:External beam and brachytherapy modalities target localized disease with curative intent.
- Diagnostics:Cystoscopic visualization, urine cytology, and molecular biomarker panels enable staging and recurrence monitoring.
Mature deployment sits with chemotherapy. Newer deployment is concentrated in immunotherapy.
Therapy Area:
Disease progression stage determines treatment intensity, duration, and total cost of care.
- Non-muscle-invasive:Superficial bladder wall tumors require intravesical BCG or chemotherapy with intensive surveillance protocols. Australian cancer centers are integrating liquid biopsy monitoring to reduce cystoscopy frequency, though validation gaps persist across TGA and NMPA jurisdictions.
- Muscle-invasive:Transmural disease penetration necessitates multimodal therapy combining neoadjuvant chemotherapy with radical cystectomy or bladder preservation. South Korea's aging demographics are expanding detected prevalence, straining urological oncology fellowship capacity.
- Early-stage:Ta-T1 tumors with favorable histology qualify for endoscopic resection alone.
- Advanced disease:Metastatic presentations require systemic immunotherapy or chemotherapy with palliative intent.
Volume concentration rests with non-muscle-invasive cases. Steepest expansion trajectory belongs to muscle-invasive detection as screening protocols mature.
End User:
Care setting determines equipment investment requirements, specialist availability, and reimbursement pathway.
- Hospitals:Tertiary oncology departments in Chinese tier-one cities aggregate cystectomy volumes and clinical trial access. Provincial procurement consolidation in Guangdong and Jiangsu is displacing hospital-level purchasing autonomy for high-cost therapeutics.
- Specialty Clinics:Urological ambulatory centers concentrate surveillance cystoscopy and intravesical administration. Korean hospital systems leverage Astellas Pharma's established clinician relationships to anchor outpatient protocol adoption.
- Research Laboratories:Academic medical centers conduct biomarker validation and companion diagnostic development.
- Home Care:Oral chemotherapy and supportive care medications enable treatment continuation outside institutional settings.
Procedure complexity anchors activity in hospitals. Patient convenience pressures are expanding specialty clinic capacity.
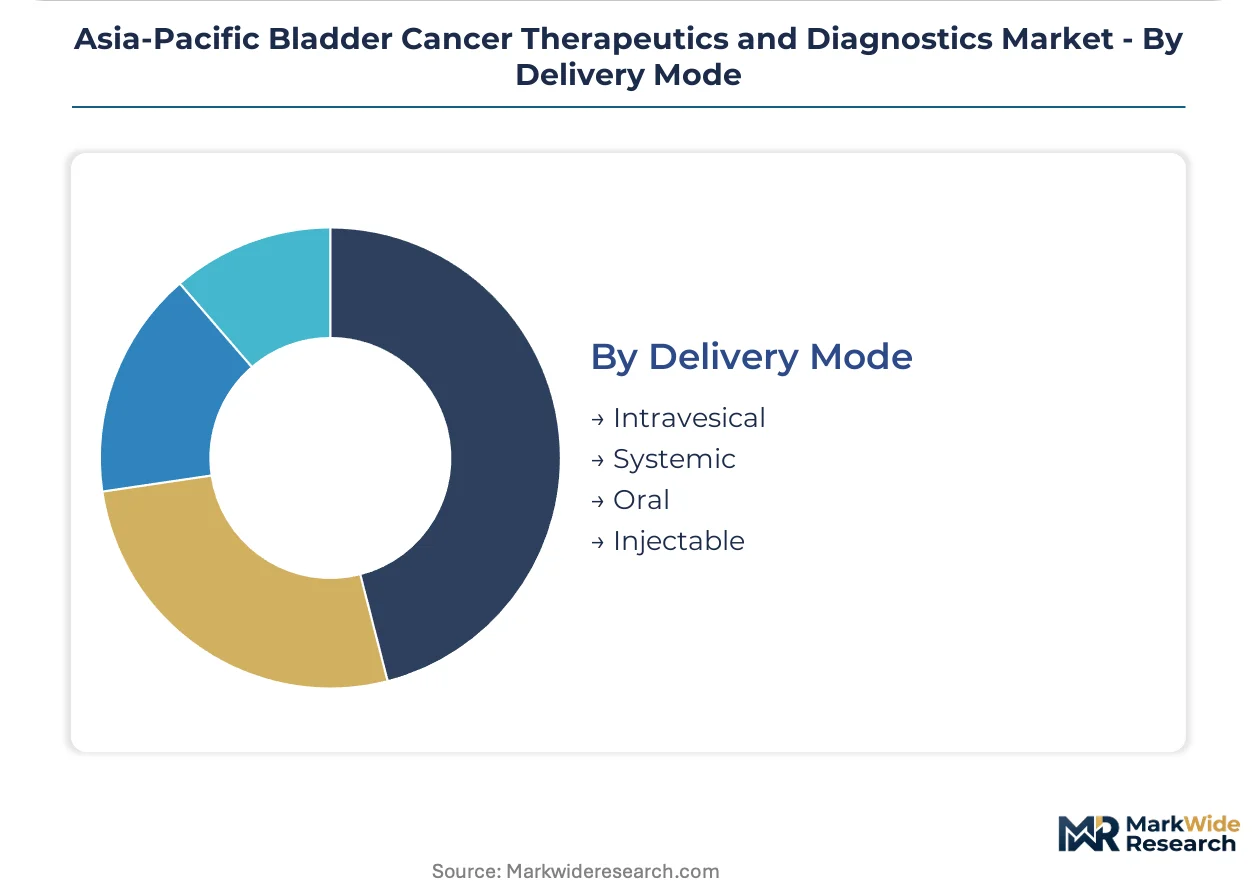
Delivery Mode:
Administration route shapes manufacturing requirements, distribution infrastructure, and patient compliance.
- Intravesical:Direct bladder instillation of BCG or chemotherapy agents requires sterile compounding and catheterization protocols. Global BCG supply concentration between two manufacturers creates vulnerability for Asia-Pacific clinics dependent on this localized immunotherapy approach.
- Systemic:Intravenous infusion of checkpoint inhibitors or chemotherapy demands oncology nursing infrastructure and adverse event monitoring capabilities. Bristol-Myers Squibb leverages regional immuno-oncology manufacturing to sustain supply commitments.
- Oral:Tablet formulations enable outpatient continuation of targeted therapy.
- Injectable:Subcutaneous administration supports supportive care and some chemotherapy protocols.
Established practice favors intravesical delivery for localized disease. Systemic administration is gaining share fastest as muscle-invasive presentations grow and immunotherapy protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Chinese tier-one cities where centralized cancer centers aggregate patient volumes and specialist expertise. Japan's PMDA accelerated review pathways compress time-to-market for novel agents. Hospital-based oncology departments across China and India are expanding adoption of molecular diagnostic platforms.
China
Provincial procurement consolidation in Guangdong and Jiangsu provinces now covers over eighty percent of bladder cancer drug expenditure. NMPA's breakthrough therapy pathway creates accelerated access corridors for domestic and multinational sponsors. Beijing and Shanghai cancer centers anchor clinical trial access and cystectomy volumes.
Japan
PMDA's sakigake designation compresses regulatory review timelines for novel immuno-oncology agents. University hospitals in Tokyo and Osaka concentrate checkpoint inhibitor demand. Japanese and Korean hospital systems leverage established clinician relationships to anchor outpatient protocol adoption.
India
Urological oncology fellowship programs produce insufficient trained cystoscopists to match expanding screening program targets. The national pharmaceutical regulator maintains distinct clinical evidence requirements that fragment trial design. Mumbai and Delhi cancer centers drive molecular diagnostic platform integration.
South Korea
Aging demographics are expanding detected prevalence of muscle-invasive presentations. MFDS is observing Australia's parallel evaluation pathway model for potential adoption. Seoul university hospitals aggregate specialist expertise and clinical trial participation.
Australia
TGA has implemented parallel evaluation pathways for companion diagnostics paired with breakthrough oncology therapies. Population screening protocols now cover adults over sixty-five. Sydney and Melbourne reference laboratories integrate automated scoring algorithms with traditional morphological assessment.
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers expand across branded and biosimilar chemotherapy agents. The vendor base organizes around three strategic archetypes: immuno-oncology specialists leveraging regional manufacturing footprints, urology-focused pharmaceutical companies with deep hospital system relationships, and broad-portfolio competitors spanning multiple therapeutic modalities. M&A activity and strategic partnerships represent the dominant competitive moves as companies seek to secure BCG-replacement demand and molecular diagnostic capabilities.
Within the immuno-oncology tier, Bristol-Myers Squibb Company occupies a position exemplifying supply chain commitment through regional manufacturing infrastructure. Astellas Pharma Inc. represents the urology specialization archetype with established presence across Japanese and Korean hospital networks. Pfizer sits within the broad-portfolio category, spanning both branded and biosimilar chemotherapy agents.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Astellas Pharma Inc. |
| F. Hoffmann-La Roche Ltd |
| Pfizer |
| Eisai Co., Ltd. |
| Johnson & Johnson |
| Endo Pharmaceuticals Inc. |
| Merck & Co. |
| AstraZeneca Plc |
| Others |
Value Chain & Pricing Dynamics
Multinational pharmaceutical conglomerates with regional manufacturing footprints anchor supply-side discipline, translating production scale into pricing leverage across Asia-Pacific oncology procurement networks. Their integrated cost structures compress margin pressure points while enabling volume-based contracting with provincial health authorities.
Pricing Analysis
Volume concentration in China's provincial tenders compresses margin realization while expanding access corridors for checkpoint inhibitors and biosimilar chemotherapy agents. Price differentiation hinges on regulatory pathway acceleration—PMDA sakigake designation commands premium positioning against standard NMPA review timelines—and cold chain infrastructure depth that constrains distribution economics. Pricing pressure stems from Guangdong and Jiangsu provincial consolidation covering over eighty percent of bladder cancer drug expenditure. Hospital procurement committees exhibit highest price sensitivity, whereas Japanese university hospitals prioritize clinical evidence quality over unit cost.
Supply Chain Analysis
China's domestic-content mandates for biologics manufacturing reshape sourcing patterns, compelling multinational sponsors to establish regional fill-finish capacity or partner with local CDMOs. Active pharmaceutical ingredient production concentrates in China and India, with fill-finish operations anchored in Singapore and South Korea. Supply chain risk centers on single-source vulnerability for BCG immunotherapy, where global production concentrates between two manufacturers. Distribution runs through temperature-controlled logistics networks terminating at hospital-based oncology pharmacies, with provincial procurement hubs consolidating last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific bladder cancer therapeutics represents a consolidation play as provincial procurement consolidation and biosimilar penetration force sub-scale manufacturers toward exit or acquisition.
For Market Incumbents: Hedge against BCG supply disruption by securing multi-source biologics manufacturing partnerships or backward integration into regional fill-finish capacity. Deepen urology specialist relationships across Japanese and Korean hospital systems to anchor protocol adoption ahead of checkpoint inhibitor displacement. Prioritize PMDA sakigake pathway investment to compress time-to-reimbursement against NMPA-standard competitors. For New Entrants and Emerging Players: Launch via provincial tender participation in Guangdong and Jiangsu, where centralized procurement creates volume access without hospital-by-hospital sales infrastructure. Target liquid biopsy and companion diagnostic white space, where biomarker validation gaps across NMPA, TGA, and PMDA jurisdictions delay incumbent lock-in. Emphasize telepathology network partnerships to bypass specialist workforce constraints in Indian and Southeast Asian markets. For Investors and Strategic Acquirers: NMPA accelerated biosimilar approvals are the leading indicator that domestic manufacturing capacity will command premium valuations over pure licensing plays. Frame long-term viability around five-to-ten year provincial procurement consolidation trajectories, with acquisition focus on urology-focused specialists possessing established clinician relationships and regional cold chain infrastructure. Monitor PMDA-MFDS regulatory harmonization signals as inflection points for cross-border portfolio rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | PMDA sakigake designation compresses review timelines for novel immuno-oncology agents in Japanese university hospitals. |
| Manufacturing Scale-Up | Regional fill-finish capacity in Singapore and South Korea secures supply commitments for temperature-sensitive biologics. |
| Regulatory Approval Pathway | NMPA breakthrough therapy corridors create accelerated access for domestic and multinational sponsors in Chinese tier-one cities. |
| Strategic Partnership | Telepathology networks between Australian regional hospitals and centralized pathology hubs reduce specialist consultation delays. |
| Reimbursement Strategy | Provincial health security bureau negotiations in Guangdong establish price benchmarks cascading through adjacent markets. |
Study Parameters
Multi-period observation of regulatory submission timelines, provincial tender outcomes, and biomarker adoption rates anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from PMDA and NMPA submission databases, ClinicalTrials.gov oncology trial records, hospital procurement databases, and GPO contract filings. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure analysis were triangulated against manufacturer-reported regional sales data.
Segment-weighting across therapeutic modality, disease staging, care setting, and administration route shaped the analytical framework, with regional regulatory clusters and patient population demographics as cross-cutting dimensions. CAGRs were derived from trend extrapolation anchored in historical approval-to-adoption intervals and reimbursement negotiation patterns. Forecast inputs incorporated aging demographic trajectories in South Korea and Australia, plus BCG supply concentration risk scenarios.
Regulatory pathway delays, biomarker validation failures, and provincial procurement policy reversals are the dominant revision risks to modeled adoption curves. Forecasts reflect assumptions regarding PMDA-NMPA harmonization progress and cold chain infrastructure expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Global Clinical Oncology NGS Market