
 Asia-Pacific Lung Cancer Diagnostics Market | 2026-2036
Asia-Pacific Lung Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lung Cancer Diagnostics Market Outlook
Japan's PMDA reclassification of liquid biopsy assays is pivoting the cost-of-entry calculus for multinational manufacturers seeking reimbursement parity. F. Hoffmann-La Roche Ltd leverages its centralized diagnostics infrastructure across East Asian markets to sustain premium positioning in molecular testing. Thermo Fisher Scientific Inc anchors its regional presence through localized manufacturing of PCR-based oncology panels in Singapore. Abbott competes on point-of-care lung cancer biomarker platforms designed for outpatient clinic deployment.
Asia-Pacific lung cancer diagnostics encompasses molecular, imaging, and tissue-based modalities for detecting and subtyping pulmonary malignancies, employing techniques ranging from next-generation sequencing of circulating tumor DNA to low-dose computed tomography with AI-enhanced nodule characterization. These systems enable clinicians to distinguish adenocarcinoma from squamous cell carcinoma and identify actionable mutations such as EGFR and ALK rearrangements for targeted therapy selection. Molecular tests command the deepest margin pools as companion diagnostic requirements expand, while liquid biopsy segments attract the fastest investment as blood-based monitoring reduces repeat tissue sampling burdens. Imaging modalities, particularly CT scan technology, retain volume leadership across screening programs in China and Japan but face reimbursement compression as low-dose protocols commoditize.
China's NMPA and Japan's PMDA enforce divergent clinical evidence standards for novel diagnostic platforms, creating parallel development tracks that inflate regulatory costs for manufacturers serving both markets. India's CDSCO and Australia's TGA introduce additional compliance layers for IVD registration and post-market surveillance, further fragmenting market access pathways. Stakeholders must calibrate portfolio investments across biomarker-driven precision diagnostics and scalable imaging infrastructure as health systems balance cost containment with mortality reduction targets.
Market Dynamics
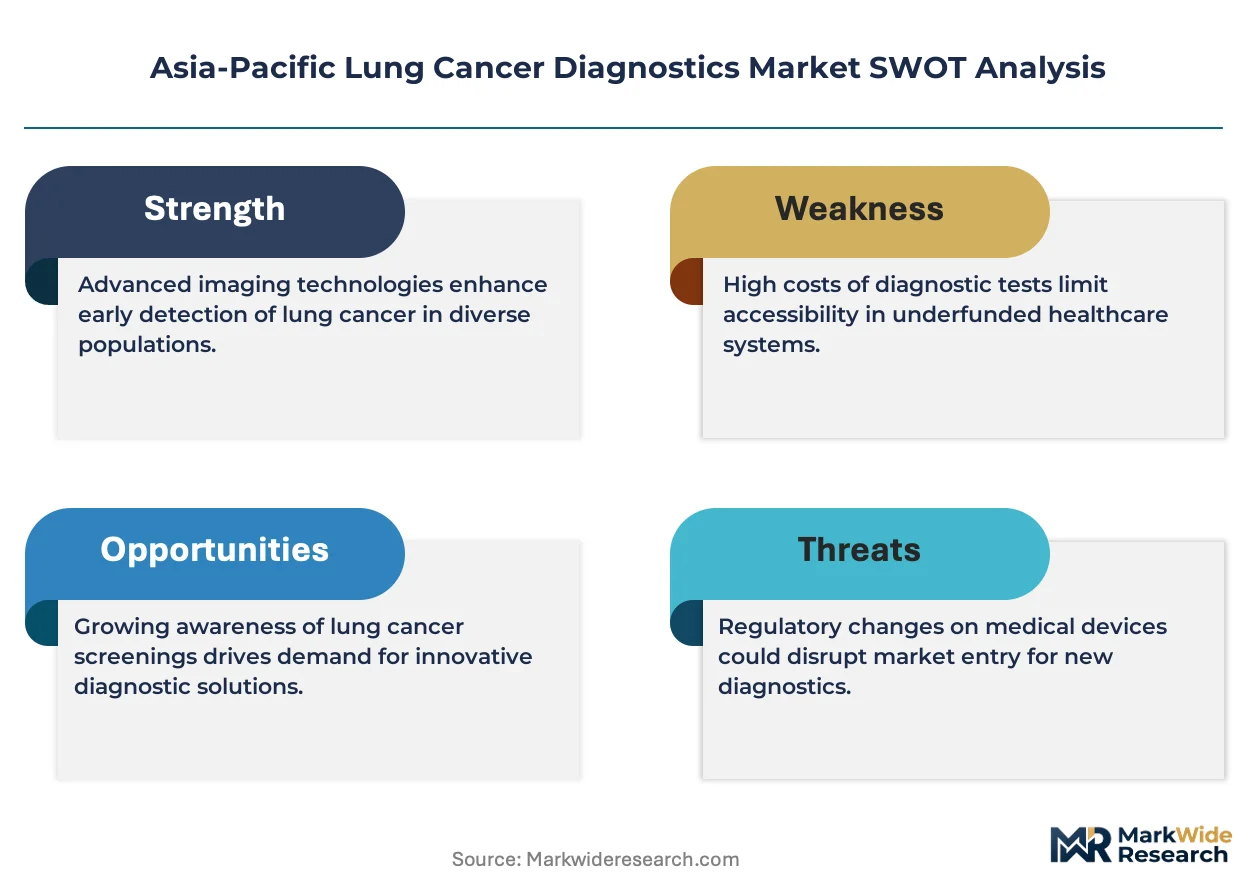
China's NMPA accelerated review pathways for companion diagnostics are compressing commercialization timelines and forcing multinational manufacturers to restructure their Asia-Pacific regulatory submissions around parallel-track development.
Growth Catalysts
- Liquid biopsy assay adoption:Japan's PMDA reclassification of blood-based testing is expanding reimbursement eligibility for circulating tumor DNA analysis in metropolitan hospital networks.
- Screening program mandates:Low-dose CT protocols in China's tier-one cities are institutionalizing early detection infrastructure that feeds downstream molecular testing demand.
- Companion diagnostic requirements:Targeted therapy pipelines from Shanghai and Osaka oncology centers are mandating biomarker confirmation prior to EGFR and ALK inhibitor administration.
Market Restraints
- Reimbursement compression:Japan's Ministry of Health, Labour and Welfare biennial fee schedule revisions are constraining margins for imaging-based screening modalities.
- Regulatory fragmentation:Divergent clinical evidence standards between China's NMPA and Japan's PMDA inflate development costs for assays seeking dual-market approval.
- Tissue sampling limitations:Inadequate biopsy yields from peripheral lung lesions in Indian tertiary care centers restrict molecular test completion rates.
Strategic Opportunities
- Point-of-care biomarker platforms:Outpatient clinic deployment in Australia's regional health networks is creating demand for rapid, decentralized EGFR mutation detection.
- AI-enhanced nodule characterization:Integration of machine learning with low-dose CT workflows in South Korea's National Cancer Screening Program is reducing radiologist interpretation burdens.
- Post-treatment monitoring:Minimal residual disease testing via liquid biopsy is penetrating Japan's private oncology practices as a recurrence surveillance tool.
Industry Challenges
- Molecular pathologist scarcity:Interpretation of complex next-generation sequencing reports requires specialized training that outpaces supply in India's diagnostic laboratory sector.
- Sample logistics integrity:Cold chain maintenance for circulating tumor DNA specimens across Indonesia's archipelago geography degrades analyte stability before centralized processing.
- Interoperability with legacy systems:Integration of AI-enabled CT analysis tools with existing PACS infrastructure in Chinese provincial hospitals demands costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lung Cancer Diagnostics Market |
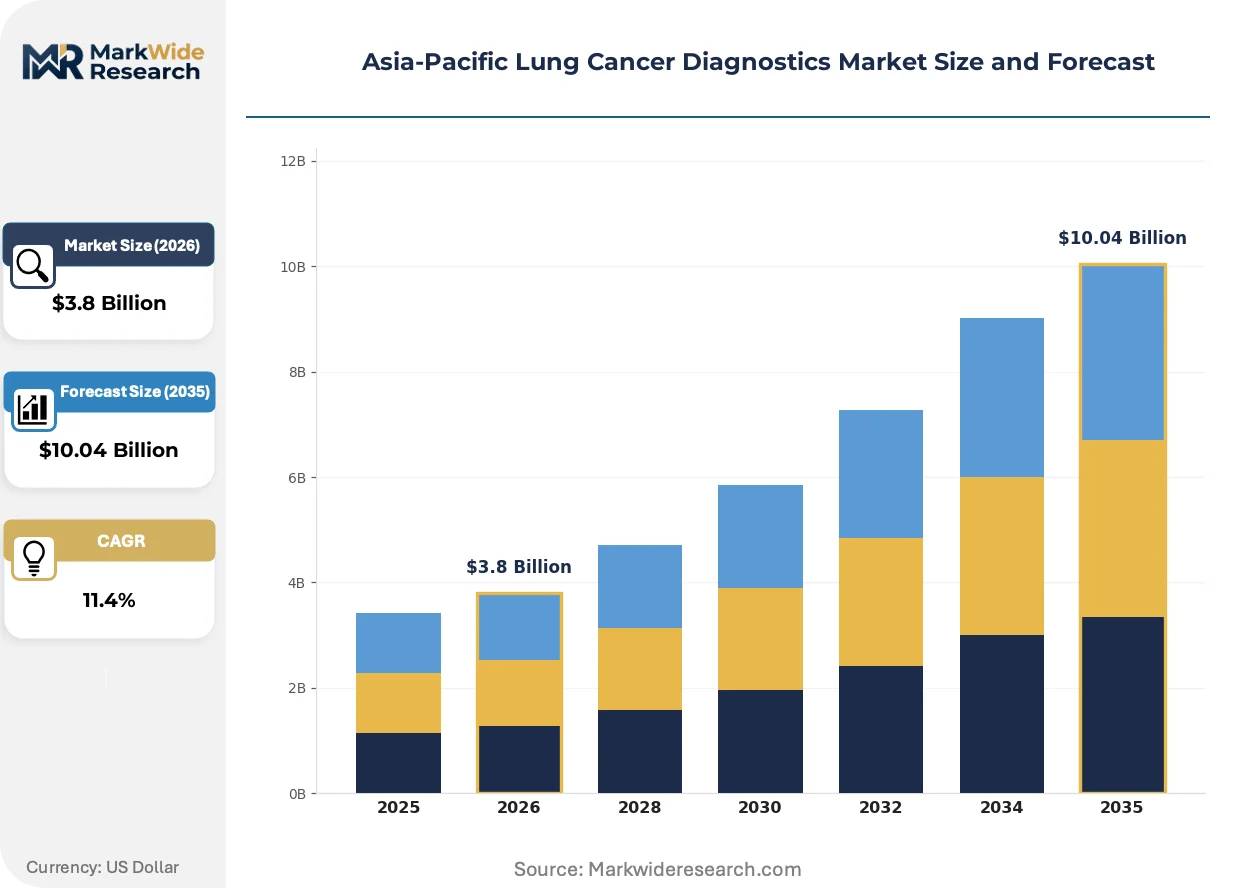
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Imaging, Biopsy, Molecular Tests Technology: CT Scan, MRI, PET Scan, Liquid Biopsy End User: Hospitals, Diagnostic Laboratories, Research Institutes, Outpatient Clinics Delivery Mode: In-Person, Home Testing, Telehealth, Mobile Testing Units |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc, Abbott, Quest Diagnostics Incorporated, Amoy Diagnostics Co., Ltd., Biodesix, Bio-Rad Laboratories, Inc., Boditech Med Inc., Sysmex Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lung Cancer Diagnostics Market Strategic Shifts
Multiplexed molecular platforms are consolidating previously discrete biomarker tests into single-workflow solutions, compressing laboratory operational footprints while expanding actionable mutation coverage for Asia-Pacific oncologists.
Next-generation sequencing panels are unifying EGFR, ALK, ROS1, and emerging biomarker detection into single-sample workflows. Hospital-based pathology departments in Tokyo and Seoul are adopting these consolidated platforms to replace sequential single-gene testing. This unification is compressing diagnostic turnaround times from weeks to days and reducing tissue consumption for patients with limited biopsy material.
China's NMPA breakthrough device designation pathway is prioritizing review resources for companion diagnostics linked to novel targeted therapies. Domestic manufacturers in Suzhou and Shenzhen are leveraging this framework to secure market access ahead of multinational competitors. The policy is most actively reshaping the competitive landscape for PD-L1 expression assays in non-small cell lung cancer.
Centralized procurement consortia in Australia's state health systems are consolidating diagnostic test purchasing across multiple hospital networks. Traditional distributor relationships with individual pathology laboratories are yielding to direct manufacturer negotiations with regional purchasing authorities. This concentration is most visible in Victoria and New South Wales, where standardized EGFR testing menus are displacing hospital-specific assay selections.
Asia-Pacific Lung Cancer Diagnostics Market Segmentation
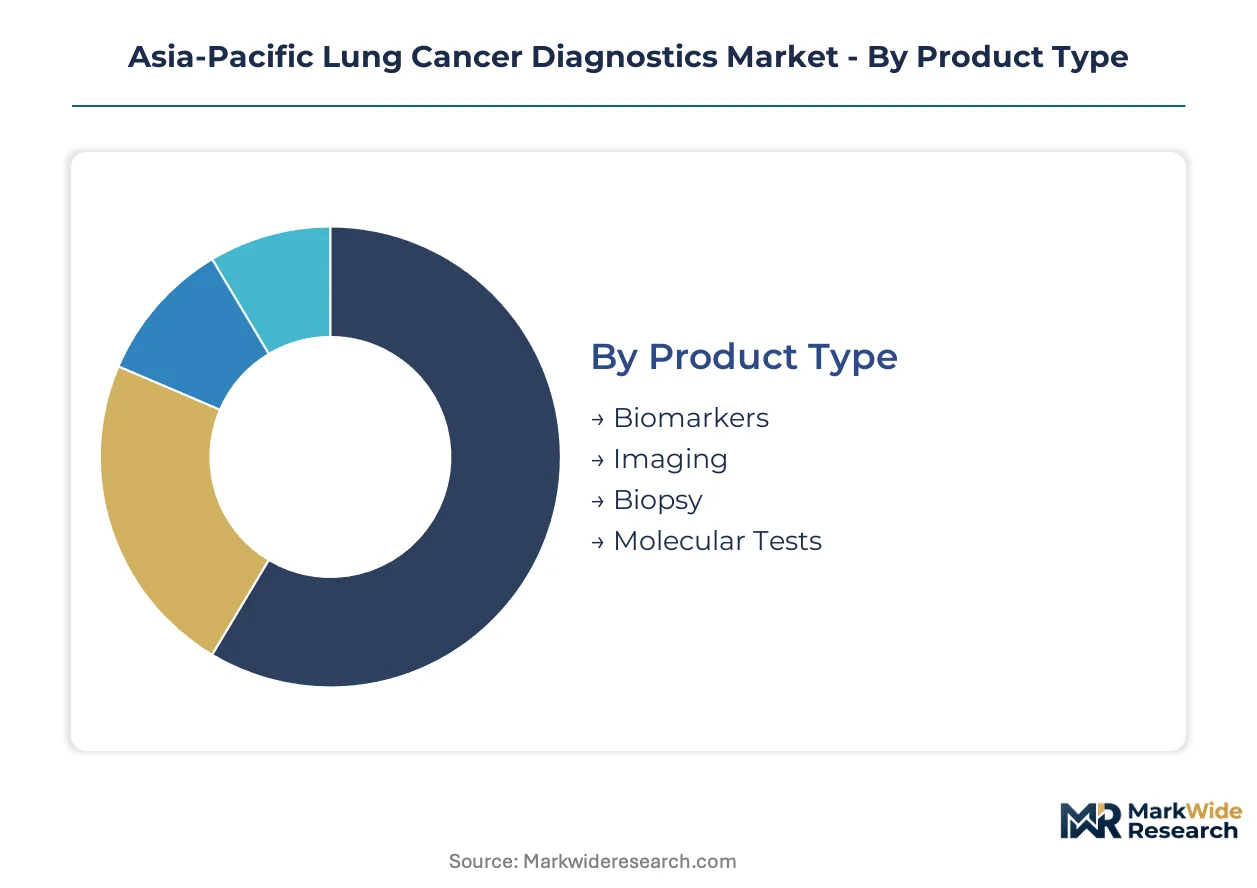
Segmentation in Asia-Pacific lung cancer diagnostics reveals how technology choices, care settings, and delivery models allocate value across molecular precision and scalable screening infrastructure. Understanding these divisions illuminates where margin pools concentrate and where volume expansion reshapes competitive positioning.
Product Type:
Product architecture separates high-margin molecular platforms from capital-intensive imaging systems and tissue-based procedures.
- Biomarkers:Circulating proteins and genetic signatures enable non-invasive risk stratification and treatment monitoring. Shanghai and Osaka oncology centers are expanding biomarker panels for EGFR and ALK detection, though reimbursement inconsistency across China's provincial health bureaus constrains uniform adoption.
- Imaging:Low-dose CT with AI-enhanced nodule characterization dominates screening volumes in Japan's National Cancer Screening Program and China's tier-one city health initiatives. Radiologist workforce shortages in India's tertiary hospitals limit interpretation capacity despite equipment availability.
- Biopsy:Tissue acquisition via bronchoscopy or CT-guided percutaneous sampling provides definitive histological diagnosis. Peripheral lesion accessibility challenges in Indonesian archipelago hospitals reduce diagnostic yield for molecular downstream testing.
- Molecular Tests:Next-generation sequencing and PCR-based mutation analysis command premium pricing as companion diagnostic requirements expand. Singapore's centralized molecular pathology infrastructure supports regional referral networks for complex case resolution.
Imaging leads on scale; molecular tests lead on momentum.
Technology:
Diagnostic modality selection reflects trade-offs between anatomical resolution, functional assessment, and minimally invasive monitoring.
- CT Scan:Low-dose protocols with computer-aided detection software form the backbone of population screening programs. South Korea's National Cancer Screening Program processes millions of annual scans, creating downstream demand for confirmatory molecular testing of detected nodules.
- MRI:Magnetic resonance imaging provides superior soft-tissue contrast for mediastinal staging and brain metastasis evaluation. Australia's state hospital networks deploy MRI for surgical planning in complex resectable cases where CT characterization proves indeterminate.
- PET Scan:Positron emission tomography with FDG tracer enables metabolic assessment of nodal involvement and distant metastasis. Japan's PMDA reimbursement frameworks prioritize PET-CT for staging decisions in locally advanced non-small cell lung cancer.
- Liquid Biopsy:Circulating tumor DNA analysis from peripheral blood reduces repeat tissue sampling burdens. China's NMPA breakthrough device pathway is accelerating approvals for blood-based EGFR monitoring assays in Beijing and Guangzhou hospital networks.
CT scan anchors volume; liquid biopsy climbs fastest.
End User:
Care setting determines test complexity, turnaround requirements, and reimbursement pathways across the diagnostic journey.
- Hospitals:Acute care institutions integrate imaging, biopsy, and molecular testing through centralized pathology departments. Tokyo's metropolitan hospital networks are consolidating previously distributed testing into single-site molecular diagnostics hubs.
- Diagnostic Laboratories:Independent and hospital-affiliated labs process high-throughput screening and confirmatory testing. India's diagnostic laboratory sector faces molecular pathologist scarcity that outpaces training program output for complex NGS report interpretation.
- Research Institutes:Academic medical centers drive biomarker discovery and clinical trial assay development. Seoul's national cancer center coordinates multi-site validation studies for novel companion diagnostic platforms.
- Outpatient Clinics:Community-based settings demand rapid, decentralized testing for initial suspicion and post-treatment surveillance. Australia's regional health networks are piloting point-of-care EGFR mutation detection to reduce urban referral burdens.
Hospitals concentrate value; outpatient clinics expand access most rapidly.
Delivery Mode:
Patient interface models reshape geographic reach and sample integrity requirements across archipelago and continental geographies.
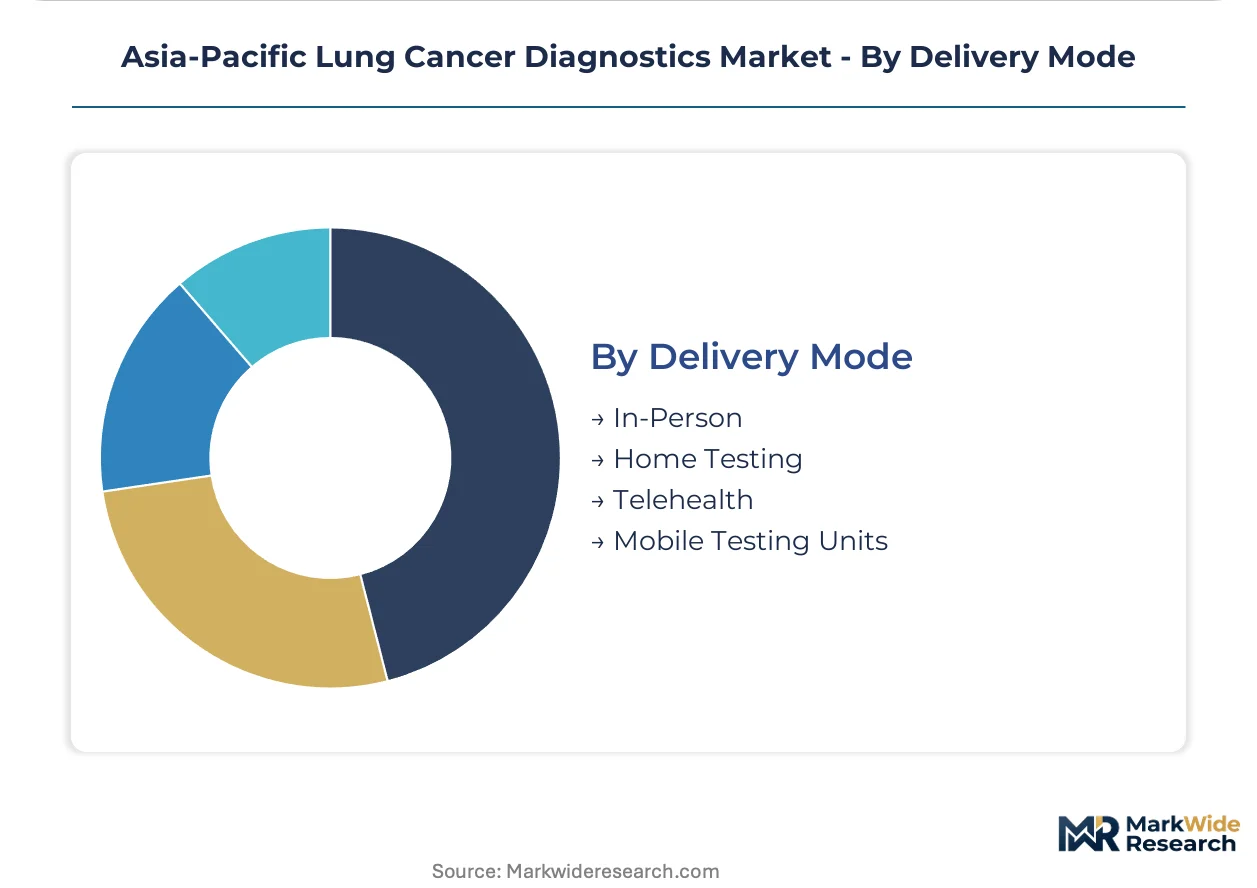
- In-Person:Traditional facility-based testing maintains diagnostic accuracy through controlled specimen handling. China's tier-one city hospital networks rely on in-person workflows for complex biopsy procedures requiring real-time imaging guidance.
- Home Testing:Self-collected specimens for circulating biomarker analysis extend screening to remote populations. Regulatory frameworks for home-based lung cancer diagnostics remain underdeveloped across most Asia-Pacific jurisdictions.
- Telehealth:Remote consultation with digital image transmission enables specialist interpretation in underserved regions. Victoria's state health system in Australia integrates tele-radiology for CT nodule assessment across rural hospital networks.
- Mobile Testing Units:Deployable screening vehicles bring low-dose CT to high-risk populations outside metropolitan centers. Indonesia's archipelago geography drives interest in mobile units, though cold chain maintenance for molecular specimens degrades analyte stability before centralized processing.
In-person delivery dominates current volume; mobile testing units show steepest expansion trajectory for screening access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molecular pathologists cluster in Tokyo, Shanghai, and Singapore, anchoring diagnostic interpretation capacity across East Asia while regional screening programs scale imaging infrastructure elsewhere.
China
Beijing and Guangzhou hospital networks drive liquid biopsy volume for EGFR-mutant non-small cell lung cancer monitoring. NMPA breakthrough device designation accelerates review timelines for companion diagnostics linked to domestic targeted therapies. Suzhou and Shenzhen manufacturing clusters supply PCR-based oncology panels to tier-one city pathology departments.
Japan
Osaka and Nagoya oncology centers mandate biomarker confirmation before EGFR and ALK inhibitor administration, standardizing molecular testing protocols. PMDA reclassification of liquid biopsy assays expands reimbursement eligibility for circulating tumor DNA analysis in metropolitan hospital networks. Tokyo's consolidated molecular diagnostics hubs replace previously distributed testing across metropolitan hospital networks.
South Korea
Seoul's national cancer center coordinates multi-site validation studies for novel companion diagnostic platforms, bridging academic research and clinical deployment. The National Cancer Screening Program processes millions of annual low-dose CT scans, creating downstream demand for confirmatory molecular testing. Daegu-Gyeongbuk medical device manufacturers supply AI-enhanced nodule characterization software to screening workflows.
Australia
Victoria and New South Wales state health systems consolidate diagnostic test purchasing across hospital networks, displacing hospital-specific assay selections with standardized EGFR testing menus. TGA registration requirements introduce compliance layers for IVD market access. Regional health networks pilot point-of-care EGFR mutation detection to reduce urban referral burdens for outpatient clinics.
India
Maharashtra and Karnataka diagnostic laboratories face molecular pathologist scarcity that outpaces training program output for complex NGS report interpretation. CDSCO post-market surveillance requirements add compliance layers for IVD registration. Mumbai and Bangalore tertiary care centers struggle with inadequate biopsy yields from peripheral lung lesions, restricting molecular test completion rates.
Asia-Pacific Lung Cancer Diagnostics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across molecular, imaging, and tissue-based diagnostic modalities. The vendor base organizes around three strategic archetypes: multinational life sciences conglomerates with centralized diagnostics infrastructure, regional manufacturers with localized production capabilities, and emerging domestic players leveraging accelerated regulatory pathways. Consolidation pressures intensify as hospital procurement centralization favors scale. Competitive moves concentrate on portfolio diversification into companion diagnostics and geographic expansion through distributor network restructuring.
Among Swiss and American conglomerates, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific Inc exemplify the diversified infrastructure archetype, while Abbott occupies a position bridging point-of-care deployment with molecular platform breadth. Chinese specialists Amoy Diagnostics Co., Ltd. and Boditech Med Inc. represent the domestic acceleration archetype, leveraging NMPA priority review frameworks. These named entities anchor competitive positioning without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc |
| Abbott |
| Quest Diagnostics Incorporated |
| Amoy Diagnostics Co., Ltd. |
| Biodesix |
| Bio-Rad Laboratories, Inc. |
| Boditech Med Inc. |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed hospital procurement consortia in Australia and centralized diagnostics infrastructure in Singapore anchor supply concentration while enforcing pricing discipline across molecular testing and imaging modalities. NMPA breakthrough device pathways in China compress manufacturer margins for domestic entrants, whereas PMDA reimbursement reclassifications in Japan sustain premium positioning for multinational assay providers.
Pricing Analysis
Bundled service contracts for comprehensive molecular diagnostics—combining NGS panels with pathologist interpretation—command premium positioning against unbundled per-test transactional models. Pricing stratifies across premium, standard, and economy tiers based on assay complexity and PMDA reimbursement tier eligibility. Cost compression in imaging-based screening stems from Japan's biennial fee schedule revisions constraining CT scan margins. Diagnostic laboratories in India's tertiary centers exhibit highest price sensitivity due to reimbursement inconsistency across state health bureaus, while Japan's metropolitan hospital networks maintain lowest sensitivity given standardized national pricing.
Supply Chain Analysis
Reverse-logistics flows for circulating tumor DNA specimens—requiring temperature-controlled return transport from peripheral collection sites to centralized processing hubs—degrade analyte stability across Indonesia's archipelago geography. Manufacturing concentration centers on Singapore for PCR-based oncology panels, Suzhou and Shenzhen for domestic Chinese assays, and Tokyo for PMDA-registered companion diagnostics. Raw material dependencies include fluorophores for PCR detection, sequencing reagents for NGS workflows, and AI training datasets for nodule characterization software. Single-source vulnerability in cold chain logistics creates supply risk for liquid biopsy networks. Distribution runs through hospital-based pathology departments and regional diagnostic laboratory consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where demand tilts toward multiplexed molecular platforms consolidating previously discrete biomarker tests into unified workflows with superior turnaround and tissue efficiency.
For Market Incumbents: Hedge against PMDA reimbursement compression by diversifying into companion diagnostic partnerships with Osaka and Shanghai oncology centers developing novel targeted therapies. Deepen backward integration into sequencing reagent production to offset supply volatility from single-source fluorophore dependencies. Prioritize certification investment for NMPA breakthrough device designation to defend position against domestic Chinese manufacturers accelerating through priority review pathways.
For New Entrants and Emerging Players: Regional diagnostic laboratory networks in Australia's Victoria and New South Wales present the most penetrable channel partner type for point-of-care EGFR mutation detection platforms. Target outpatient clinic deployment in underserved Indian tertiary centers facing molecular pathologist scarcity. Pursue white-space expansion into minimal residual disease testing for Japan's private oncology practices as a recurrence surveillance entry point.
For Investors and Strategic Acquirers: Valuations sit cheapest among domestic Chinese manufacturers with NMPA breakthrough designations but limited multinational distribution infrastructure. Long-term viability over the projection horizon hinges on regulatory moats in dual-market approval capability spanning PMDA and NMPA pathways. Acquisition focus should center on AI-enhanced nodule characterization software developers with existing integration into South Korea's National Cancer Screening Program. Monitor NMPA approval velocity for blood-based EGFR monitoring assays as the inflection indicator for liquid biopsy segment repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Secures reimbursement eligibility with PMDA and NMPA for novel targeted therapy-linked assays. |
| AI-Enhanced Nodule Characterization | Reduces radiologist interpretation burden in South Korea's National Cancer Screening Program workflows. |
| Liquid Biopsy Assay Expansion | Captures post-treatment monitoring demand in Japan's private oncology practice networks. |
| Point-of-Care Platform Deployment | Addresses regional health network access gaps in Australia's outpatient clinic infrastructure. |
| Centralized Procurement Alignment | Positions for standardized testing menu adoption across Victoria and New South Wales state systems. |
Study Parameters
Bottom-up hospital and diagnostic laboratory modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with molecular pathologists, hospital procurement committee members, biomedical engineers, and GPO contracts managers were cross-validated against secondary sources including NMPA registration databases, PMDA reimbursement bulletins, hospital procurement records, and GPO contract disclosures. Triangulation between demand-side utilization patterns and supply-side production data ensures segment-level precision.
Input-output matrices map assay volume flows across product type, technology modality, end-user setting, and delivery mode dimensions throughout the forecast period. CAGRs were derived from segmented growth trajectory modeling incorporating NMPA approval velocity, PMDA fee schedule revision cycles, and screening program mandate expansion timelines. Industry-specific forecast inputs include liquid biopsy reimbursement reclassification schedules and AI-enhanced imaging adoption curves in national screening programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory pathway divergence between NMPA and PMDA evidence standards and molecular pathologist training pipeline expansion rates. Practitioners should monitor NMPA breakthrough device designation grant rates and PMDA liquid biopsy reimbursement tier adjustments for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market