
 Europe Liver Cancer Diagnostics Market | 2026-2036
Europe Liver Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Liver Cancer Diagnostics Market Foresight
Hospital procurement of non-invasive biomarker panels is broadening across European healthcare systems. Siemens Healthineers AG leverages its installed imaging base to anchor molecular diagnostic workflows in major oncology centers. F. Hoffmann-La Roche Ltd. sustains leadership in blood-based biomarker platforms through continuous R&D investment. Illumina, Inc. competes on next-generation sequencing applications for mutational profiling in hepatocellular carcinoma subtyping.
Europe Liver Cancer Diagnostics encompasses technologies and reagents used to detect, characterize, and monitor malignant hepatic lesions through serum biomarker quantification, cross-sectional imaging, and tissue molecular analysis. CT scan protocols with multiphasic contrast enhancement remain the structural backbone of lesion characterization, while MRI with hepatobiliary contrast agents dominates indeterminate nodule workups. Blood tests for alpha-fetoprotein and des-gamma-carboxy prothrombin capture substantial volume in screening applications, though biomarker multiplexing is displacing single-analyte testing in high-throughput laboratories. Diagnostic laboratories command significant margin pools through centralized processing economies, whereas hospital-based imaging segments face equipment utilization pressures.
EMA's In Vitro Diagnostic Regulation and the EU AI Act impose conformity assessment burdens on algorithm-assisted imaging devices entering European markets. The F-Gas Regulation constrains MRI coolant supply chains, indirectly affecting scanner deployment timelines in liver imaging programs. France's HAS and Germany's G-BA shape reimbursement thresholds that determine biomarker test adoption velocity across national health systems. Stakeholders must monitor evolving HTA convergence between EUnetHTA members and national pricing bodies to anticipate access timelines for novel diagnostic modalities.
Market Dynamics
Hospital procurement committees across Germany, France, and the United Kingdom are consolidating vendor relationships for non-invasive biomarker panels, compressing supplier margins while elevating throughput requirements for centralized hepatology laboratories.
Growth Catalysts
- EMA companion diagnostic guidelines:The evolving framework accelerates co-development pathways for algorithm-assisted imaging interpretation, reducing time-to-market for integrated diagnostic platforms in oncology centers.
- EU AI Act conformity pathways:Standardized assessment procedures for machine learning-enabled lesion characterization tools create predictable regulatory costs, encouraging mid-tier manufacturers to enter European markets.
- Hepatobiliary MRI contrast agents:Enhanced sensitivity for indeterminate nodule characterization drives replacement demand for older CT-first protocols in French and German tertiary referral networks.
Market Restraints
- F-Gas Regulation coolant constraints:Supply chain bottlenecks for helium and specialized refrigerants delay MRI scanner deployment timelines, particularly affecting liver imaging program expansions in Southern Europe.
- Single-analyte biomarker displacement:Laboratory infrastructure sunk costs in AFP-only testing create friction against multiplexed panel adoption in smaller diagnostic facilities.
- Reimbursement fragmentation:Divergent HTA assessments between France's HAS and Germany's G-BA force manufacturers to maintain parallel evidence-generation strategies, elevating commercialization costs.
Strategic Opportunities
- Spain and Italy outpatient networks:Underpenetrated community hepatology settings present first-mover advantages for portable ultrasound elastography combined with blood-based risk scores.
- Next-generation sequencing convergence:Integration of ctDNA profiling with radiomic feature extraction enables molecular subtyping workflows that command premium pricing in academic medical centers.
- EU Green Deal procurement incentives:Sustainability-linked tender criteria favor manufacturers with closed-loop reagent systems, creating differentiation leverage in public hospital purchasing.
Industry Challenges
- Computational pathology talent scarcity:Shortage of dual-trained professionals in hepatology and machine learning impedes validation of AI-assisted diagnostic algorithms for regulatory submission.
- Legacy PACS integration complexity:Hospital information system heterogeneity forces customized middleware development, extending implementation timelines and elevating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Liver Cancer Diagnostics Market |
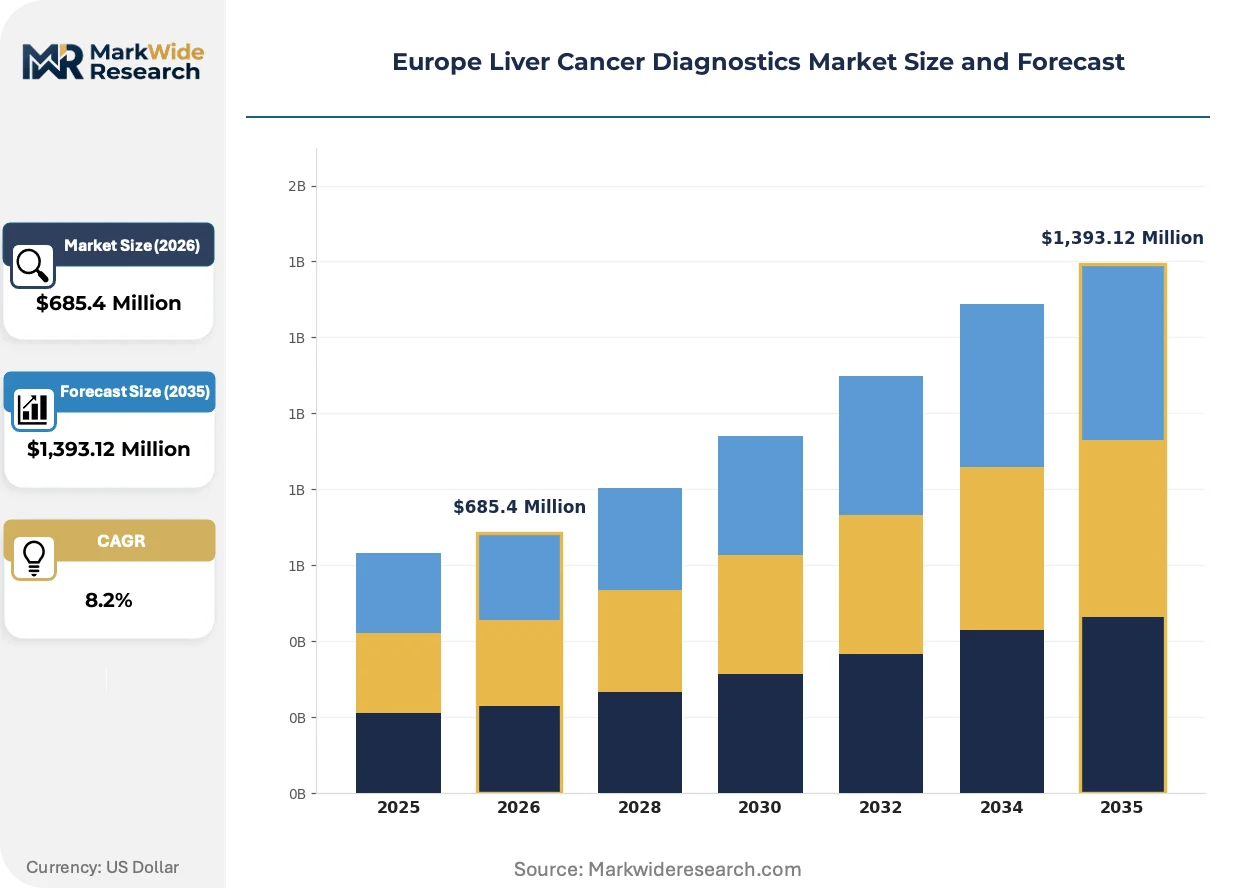
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Imaging Devices, Diagnostic Kits, Biological Assays Technology: CT Scan, MRI, Ultrasound, Blood Tests End User: Hospitals, Diagnostic Laboratories, Research Institutes, Clinics Application: Screening, Diagnosis, Monitoring, Prognosis |
| Companies Covered | Siemens Healthineers AG, Koninklijke Philips N.V., F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., QIAGEN, Illumina, Inc., Abbott, bioMerieux SA, Epigenomics AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Liver Cancer Diagnostics Market Shifts & Advancements
Liquid biopsy technologies and radiomics pipelines are converging to enable longitudinal disease monitoring without repeat tissue acquisition, fundamentally altering the economic structure of hepatocellular carcinoma surveillance programs across European healthcare systems.
Multiplexed serum biomarker platforms combining AFP, DCP, and novel glycosylation markers are decentralizing diagnostic capability from centralized reference laboratories toward hospital-affiliated stat labs. Community oncology centers in the United Kingdom and Netherlands are adopting these workflows to reduce turnaround times for treatment-naive patients. This shift is compressing the addressable market for high-volume commercial diagnostic laboratories while expanding margin capture for integrated health systems with in-house capabilities.
The EU AI Act's risk-classification framework for medical device software imposes enhanced documentation burdens on manufacturers of computer-aided detection tools for liver lesion characterization. Developers must now maintain post-market surveillance systems and algorithm change control protocols that mirror pharmaceutical pharmacovigilance requirements. French and German notified bodies are interpreting these provisions most strictly, creating a two-speed conformity assessment environment across member states.
Hospital purchasing consortia in Scandinavia and the Benelux region are unbundling diagnostic service contracts from equipment procurement, favoring per-test pricing models over capital-heavy scanner acquisitions. This transition elevates working capital requirements for manufacturers while reducing barrier-to-entry for specialized biomarker firms without imaging hardware portfolios. The Netherlands' centralized procurement agency has pioneered this approach, with Belgium's hospital networks now piloting comparable frameworks.
Europe Liver Cancer Diagnostics Market Segmentation
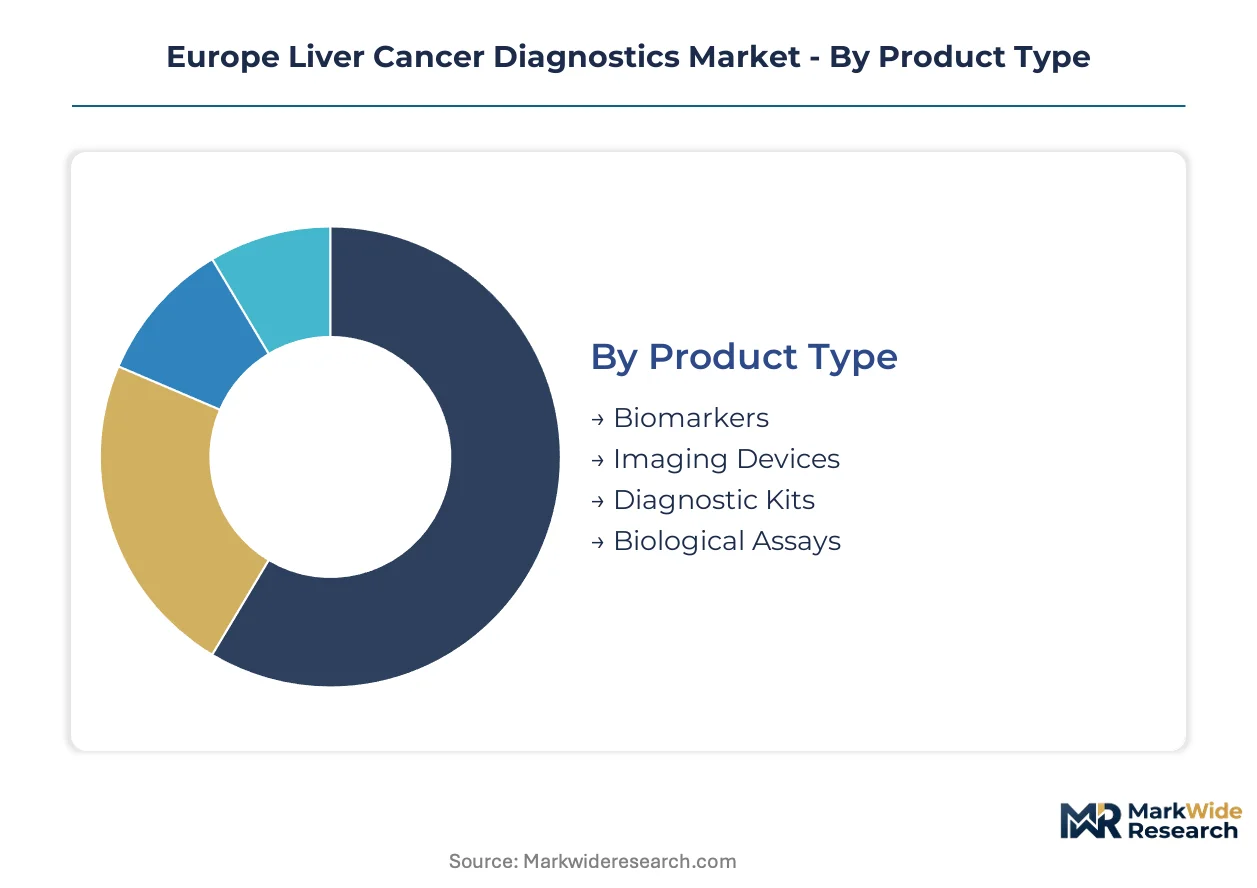
Diagnostic modality selection in European hepatology follows distinct procurement logics across public health systems, with technology choices constrained by HTA reimbursement thresholds and equipment amortization cycles. Segmentation reveals where margin pools concentrate versus where volume expansion occurs.
Product Type:
Volume concentration sits with consumable reagents, while premium capture belongs to integrated platform vendors with locked-in service contracts.
- Biomarkers:Serum protein panels quantifying AFP, DCP, and emerging glycosylation signatures through automated immunoassay platforms. Demand concentrates in German and French centralized hepatology laboratories where high-throughput automation justifies multiplexed panel adoption over single-analyte legacy workflows.
- Imaging Devices:MRI scanners with hepatobiliary contrast capability and CT systems with multiphasic acquisition protocols. Procurement committees in United Kingdom tertiary networks favor equipment with embedded AI lesion characterization to satisfy EU AI Act conformity requirements upfront.
- Diagnostic Kits:Point-of-care and laboratory-based reagent systems for rapid biomarker quantification.
- Biological Assays:Tissue-based molecular profiling including immunohistochemistry and in-situ hybridization for subtyping.
Today's leader: Biomarkers. Tomorrow's challenger: Imaging Devices.
Technology:
Application setting determines technology selection—emergency pathways favor speed while surveillance programs prioritize sensitivity.
- CT Scan:Multiphasic contrast-enhanced protocols remain the structural backbone for initial lesion detection and staging across European oncology networks. Scanner utilization pressures in Spanish and Italian hospital systems create aftermarket service revenue concentration for vendors with dense installed bases.
- MRI:Hepatobiliary contrast agents enable characterization of indeterminate nodules with superior specificity to CT. French HAS reimbursement approvals for enhanced MRI sequences accelerate replacement demand in tertiary referral centers.
- Ultrasound:First-line screening modality with elastography add-ons for fibrosis assessment in community settings.
- Blood Tests:Conventional AFP and emerging liquid biopsy platforms for longitudinal monitoring.
CT Scan holds current volume leadership. MRI represents the steepest expansion trajectory as contrast protocols displace CT-first workups.
End User:
Procurement authority fragmentation shapes vendor access—centralized tenders favor scale while distributed purchasing rewards specialization.
- Hospitals:Integrated health systems with in-house pathology and imaging departments command premium pricing through bundled service contracts. United Kingdom NHS trust consolidation creates procurement leverage that compresses supplier margins while demanding extended warranty terms.
- Diagnostic Laboratories:Centralized reference facilities processing high biomarker volumes for multiple hospital networks. Germany's G-BA reimbursement frameworks determine test menu viability, forcing manufacturers to maintain parallel evidence dossiers for national HTA submissions.
- Research Institutes:Academic medical centers driving validation of novel biomarker signatures and AI algorithms.
- Clinics:Community hepatology settings with limited on-site diagnostics relying on referral networks.
Diagnostic Laboratories dominate current biomarker volume. Hospitals are capturing expanding imaging and integrated platform share.
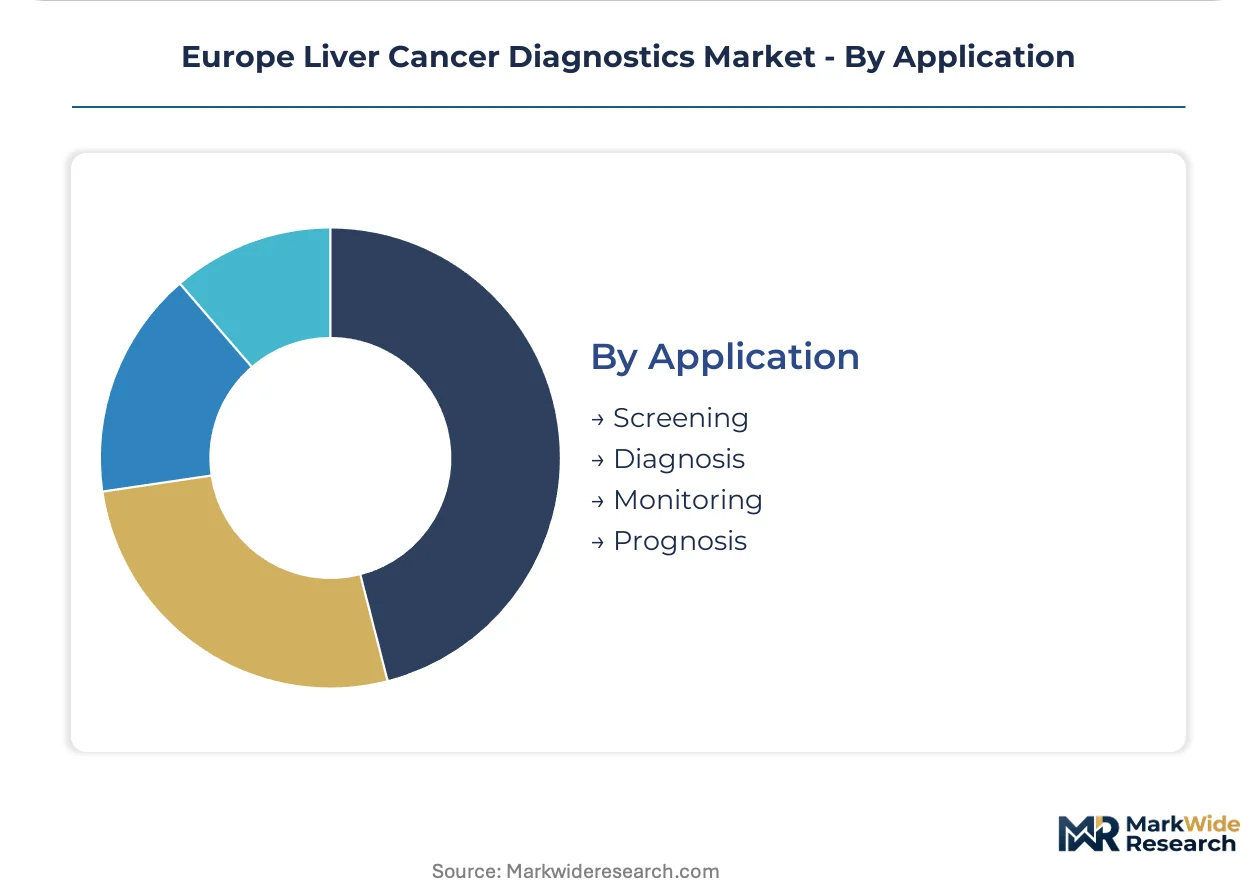
Application:
Clinical utility varies across the care continuum—screening demands cost minimization while prognosis commands premium molecular detail.
- Screening:Population-scale detection programs targeting high-risk cirrhotic populations through ultrasound and serum biomarker surveillance. Netherlands and Belgium pilot decentralized screening models combining portable elastography with blood-based risk scores in community settings.
- Diagnosis:Definitive characterization of suspicious lesions through cross-sectional imaging and tissue confirmation. French and German tertiary networks standardize on MRI-first protocols for indeterminate nodules, elevating contrast agent consumption.
- Monitoring:Serial assessment of treatment response and recurrence detection through imaging and liquid biopsy.
- Prognosis:Molecular subtyping to guide therapeutic selection and survival estimation.
Screening generates the highest test frequency. Diagnosis captures the premium pricing tier per procedure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest biomarker processing volumes while France leads hepatobiliary MRI adoption rates, reflecting divergent national HTA priorities across European hepatology networks.
Germany
Centralized hepatology referral networks in North Rhine-Westphalia and Bavaria drive standardized diagnostic protocols through G-BA reimbursement frameworks. The F-Gas Regulation constrains MRI coolant supply chains, delaying scanner deployments in Southern German hospital systems. Heidelberg and Munich academic medical centers anchor molecular subtyping validation programs for next-generation sequencing platforms.
France
HAS reimbursement approvals for enhanced MRI sequences accelerate contrast agent consumption in Île-de-France tertiary centers. EMA companion diagnostic guidelines reshape co-development pathways for Paris-based algorithm developers. Lyon and Marseille hepatology networks standardize on MRI-first protocols for indeterminate nodule characterization.
United Kingdom
NHS trust consolidation creates procurement leverage that compresses supplier margins while demanding embedded AI lesion characterization in imaging equipment. The EU AI Act conformity requirements drive London and Manchester oncology centers toward standardized assessment procedures. Cambridge and Oxford research institutes validate liquid biopsy integration with radiomic feature extraction.
Spain
Underpenetrated community hepatology settings in Catalonia and Andalusia present first-mover opportunities for portable ultrasound elastography combined with blood-based risk scores. ANSM interpretations of EU AI Act provisions create compliance bottlenecks for algorithm-assisted detection tools. Barcelona and Madrid hospital networks pilot decentralized screening models to reduce referral backlogs.
Netherlands
The centralized procurement agency pioneers unbundled diagnostic service contracts favoring per-test pricing over capital-heavy scanner acquisitions. Rotterdam and Utrecht academic centers drive validation of multiplexed biomarker panels for community adoption. Dutch hepatology networks integrate sustainability-linked tender criteria favoring closed-loop reagent systems.
Europe Liver Cancer Diagnostics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across imaging hardware, reagent platforms, and algorithm-assisted interpretation software. Market structure tilts toward consolidated procurement relationships in German and UK hospital systems while fragmenting across Spanish and Italian regional networks. Three archetypes dominate: integrated imaging-reagent platform vendors, standalone biomarker assay developers, and AI-enabled software specialists. Competitive moves concentrate on strategic partnerships between hardware manufacturers and algorithm developers, plus portfolio diversification into liquid biopsy adjacent categories.
Within the integrated platform tier, Siemens Healthineers AG and Koninklijke Philips N.V. occupy positions anchored by dense installed imaging bases across European oncology centers. F. Hoffmann-La Roche Ltd. exemplifies the biomarker-focused archetype through sustained leadership in blood-based assay platforms. These three entities represent the dominant competitive anchors shaping vendor consolidation dynamics in hepatology procurement committees.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Illumina, Inc. |
| Abbott |
| bioMerieux SA |
| Epigenomics AG |
| Others |
Supply & Pricing Matrix
Multiplexed biomarker panel adoption across German and French centralized laboratories is compressing per-test margins while concentrating procurement leverage in hospital purchasing consortia, simultaneously elevating automation equipment costs and squeezing standalone reagent suppliers without integrated platform offerings.
Pricing Analysis
Capacity additions in the Netherlands and Belgium are reshaping price floors for diagnostic consumables as centralized procurement agencies unbundle service contracts from hardware acquisitions. Three-tier pricing structure across premium, standard, and economy levels differentiates by automation throughput and G-BA reimbursement tier. Pricing pressure stems from NHS trust consolidation demanding extended warranty bundling. Community clinics exhibit highest price sensitivity; academic medical centers prioritize molecular specificity over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the United Kingdom operate hub-and-spoke patterns for hepatobiliary contrast agents and specialized immunoassay reagents. Manufacturing concentrates in Germany, Switzerland, and the United States for MRI components and diagnostic platforms. Supply chains draw from helium reserves for MRI coolant, rare earth elements for contrast chemistry, and polymer substrates for assay cartridges. Single-source vulnerability sits with helium supply under F-Gas Regulation constraints. Distribution runs through GPO-negotiated contracts with hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's evolving companion diagnostic guidelines create faster regulatory pathways in France and Germany than Southern European markets, enabling geographic-arbitrage strategies for algorithm developers seeking earlier revenue recognition.
For Market Incumbents: To counter unbundled procurement contracts in the Benelux region, Siemens Healthineers and Roche must deepen service integration through captive maintenance networks and locked-in reagent supply agreements. Backward integration into hepatobiliary contrast agent production secures margin capture against generic substitution. CE marking investment for AI-embedded imaging platforms preserves access to French HAS reimbursement tiers. For New Entrants and Emerging Players: The EU AI Act in Spain and Italy opens a window for portable ultrasound elastography vendors to establish community hepatology footprints before notified body interpretations harden. Spain's underpenetrated outpatient networks present the most penetrable geography. Blood-based risk score partnerships with regional health authorities offer the clearest go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone biomarker assay developers lacking imaging hardware portfolios. Long-term viability hinges on molecular subtyping convergence with radiomic workflows. Acquisition targets should demonstrate validated ctDNA profiling pipelines. The signal to monitor is HAS reimbursement approvals for enhanced MRI sequences in French tertiary centers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU AI Act conformity accelerates market access for algorithm-assisted lesion detection tools in German oncology centers. |
| Hospital System Partnership | NHS trust consolidation creates procurement leverage demanding embedded AI capabilities in imaging equipment acquisitions. |
| Software Companion Development | EMA companion diagnostic guidelines reshape co-development pathways for Paris-based algorithm developers. |
| Reimbursement Strategy | G-BA evidence dossiers determine biomarker test menu viability across German centralized hepatology laboratories. |
| Reagent System Integration | Closed-loop reagent systems capture EU Green Deal procurement incentives in Dutch hospital purchasing frameworks. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down imaging equipment installation tracking forms the analytical core. Primary interviews with hepatology department heads, GPO contracts managers, biomedical engineers, and EMA regulatory affairs specialists combined with secondary validation against EMA submission databases, hospital procurement registries, G-BA reimbursement listings, and EU AI Act implementation guidance. Triangulation between consumable volume estimates and scanner utilization rates ensures segmentation integrity.
Historical trendline analysis of biomarker test frequencies and imaging procedure volumes established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include diagnostic modality, technology platform, end-user setting, and application point in the care continuum. CAGRs derive from regression analysis of reimbursement trajectory impacts and technology substitution elasticities. Forecast inputs incorporate F-Gas Regulation compliance timelines and HAS HTA convergence patterns.
Revisions become necessary when EMA regulatory interpretations diverge significantly across member states or when helium supply disruptions extend MRI deployment delays beyond modeled scenarios. Forecasts reflect documented assumptions regarding reimbursement stability and AI Act implementation uniformity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market