
 Global Oncology Molecular Diagnostics Market | 2026-2036
Global Oncology Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oncology Molecular Diagnostics Market Foresight
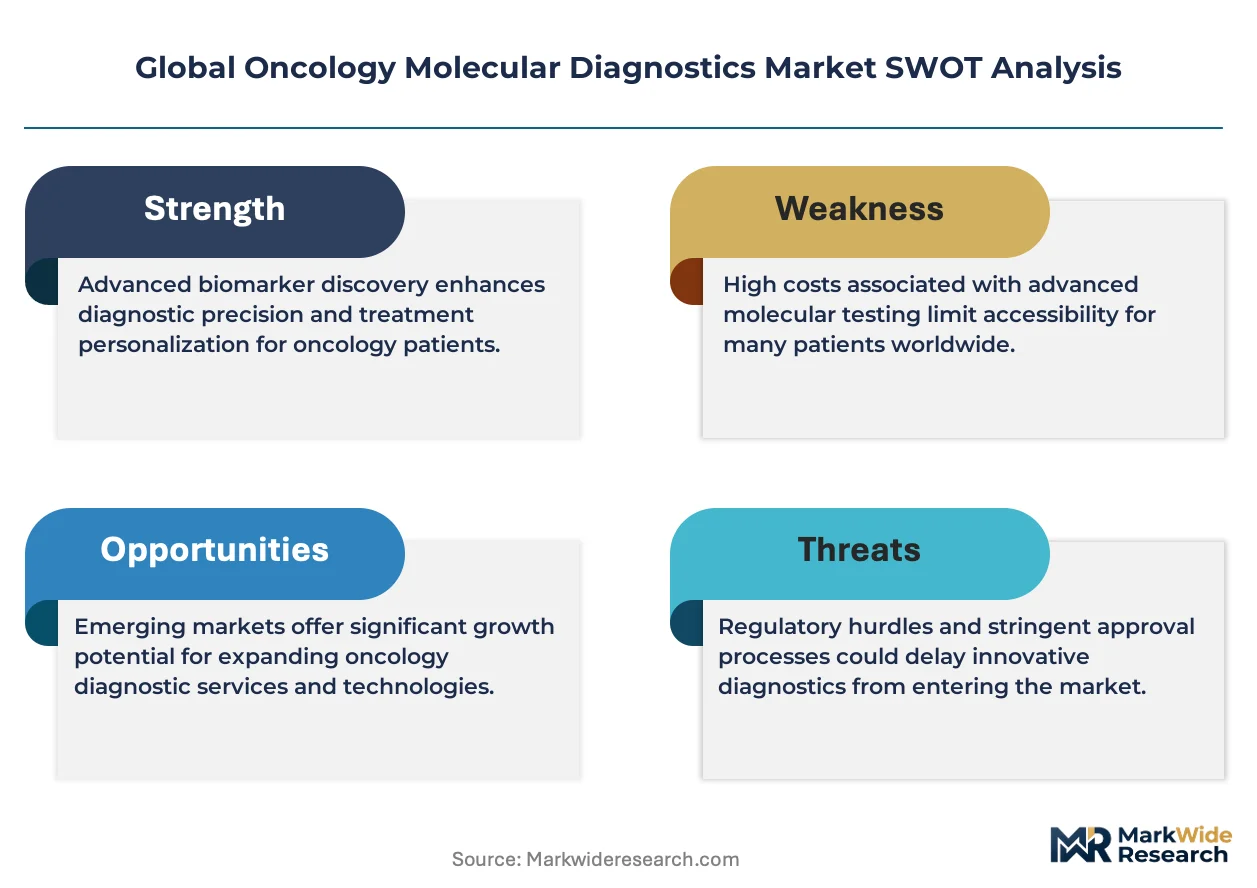
Next-generation sequencing (NGS) is rewriting the competitive architecture of oncology molecular diagnostics by enabling simultaneous multi-gene profiling from minimal tissue samples. Roche Diagnostics leverages its vertically integrated instrument-reagent platform to dominate high-throughput clinical workflows. Illumina anchors the sequencing hardware layer with proprietary flow-cell chemistry that sustains instrument lock-in across major cancer centers. Guardant Health competes through specialized liquid biopsy assays that detect circulating tumor DNA without invasive tissue extraction.
Oncology molecular diagnostics encompasses laboratory techniques that detect cancer-related genetic mutations, gene expression patterns, and epigenetic alterations in DNA or RNA extracted from tumor tissue or blood specimens, typically requiring nucleic acid amplification with sensitivity thresholds reaching single-digit variant allele frequencies. The primary commercial purpose centers on guiding targeted therapy selection, monitoring treatment response, and enabling early cancer detection through biomarker identification. Reagents capture the largest margin pool due to recurring consumable demand tied to installed instrument bases, while NGS technology segments expand fastest as panel sizes grow and turnaround times compress. Diagnostic labs represent the most concentrated end-user channel, though oncology clinics are gaining share through point-of-care testing adoption.
FDA companion diagnostic requirements under the In Vitro Diagnostics Regulation pathway shape product development timelines and clinical trial design for US market entry, while EMA's IVDR enforcement in Europe elevates conformity assessment burdens for multinational manufacturers. China's NMPA accelerates review pathways for innovative oncology diagnostics under its breakthrough device designation, creating divergent regulatory arbitrage opportunities across major markets. Stakeholders must monitor evolving payer coverage policies for multi-cancer early detection tests, as reimbursement decisions will determine whether liquid biopsy platforms achieve population-scale deployment or remain confined to affluent patient segments.
Market Dynamics
Liquid biopsy platforms are restructuring oncology molecular diagnostics by shifting sample collection from surgical suites to outpatient phlebotomy centers, compressing turnaround times and expanding addressable testing volumes beyond tissue-limited patients.
Growth Catalysts
- FDA In Vitro Diagnostics Regulation:The IVDR pathway mandates companion diagnostic co-development with targeted therapies, accelerating biomarker validation investments from pharmaceutical partners seeking accelerated approval.
- NGS panel expansion:Simultaneous multi-gene profiling from minimal tissue samples enables comprehensive genomic characterization that single-gene assays cannot match, driving platform upgrades at academic medical centers.
- China NMPA breakthrough designation:Expedited review timelines for innovative oncology diagnostics attract multinational manufacturers seeking earlier market entry in the world's second-largest pharmaceutical market.
Market Restraints
- Reagent supply concentration:Proprietary sequencing chemistries from Illumina and Thermo Fisher create captive consumable demand that locks diagnostic laboratories into high-margin recurring purchases.
- Variant allele frequency thresholds:Detection sensitivity limitations at sub-1% frequencies in circulating tumor DNA assays generate false-negative risks that restrict clinical utility in minimal residual disease monitoring.
- EMA IVDR conformity assessment:Elevated documentation burdens and notified body bottlenecks extend European market entry timelines by 18-24 months for novel biomarker assays.
Strategic Opportunities
- Multi-cancer early detection:Blood-based screening panels targeting 50+ cancer types simultaneously represent a $15 billion addressable population health opportunity pending payer coverage determinations.
- Point-of-care oncology clinics:Decentralized PCR and isothermal amplification platforms enable same-day treatment decisions at community cancer centers without centralized lab logistics.
- Japan PMDA regenerative medicine pathway:Accelerated approval frameworks for companion diagnostics in immuno-oncology combinations create first-mover advantages in Asia-Pacific's most profitable reimbursed market.
Industry Challenges
- Bioinformatics pipeline standardization:Variant interpretation discordance between laboratories using different annotation databases and filtering algorithms undermines clinical confidence in NGS reports.
- Liquid biopsy assay validation:Analytical and clinical validation requirements for circulating tumor DNA tests demand prospective cohort studies that extend development costs and timelines substantially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oncology Molecular Diagnostics Market |
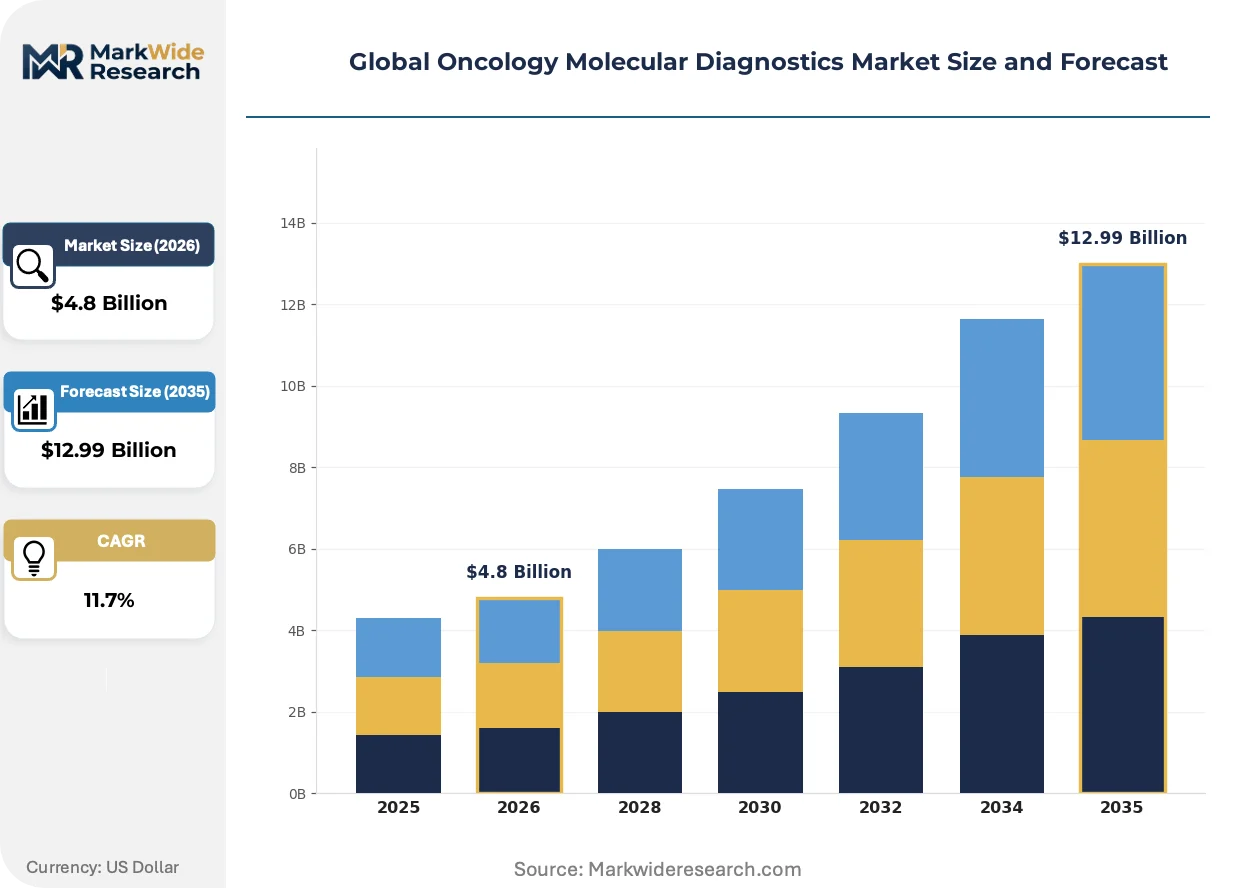
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Services Technology: PCR, NGS, FISH, Immunohistochemistry End User: Hospitals, Diagnostic Labs, Research Institutions, Oncology Clinics Application: Personalized Medicine, Biomarker Discovery, Cancer Screening, Prognostic Testing |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Thermo Fisher Scientific, Illumina, QIAGEN, Danaher, Agilent Technologies, Sysmex Corporation, Guardant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oncology Molecular Diagnostics Market Shifts & Advancements
Digital pathology integration with molecular profiling is compressing diagnostic workflows from days to hours. Artificial intelligence algorithms now automate biomarker scoring that previously required specialized pathologist interpretation.
Next-generation sequencing is virtualizing tissue-based testing by enabling comprehensive genomic profiling from plasma samples alone. Community oncology practices are adopting hybrid capture-based liquid biopsy panels at twice the rate of academic centers. This shift is virtualizing the traditional tissue-archival infrastructure that anchored hospital-based molecular pathology departments.
EMA's In Vitro Diagnostics Regulation enforcement is restructuring European market access pathways. Manufacturers must now engage with 23 notified bodies for conformity assessment rather than self-certifying under the previous directive. Mid-sized diagnostic companies are consolidating regulatory affairs functions in Dublin and Amsterdam to manage centralized technical documentation requirements.
Oncology clinics are unbundling diagnostic service contracts from pharmaceutical distribution agreements. Large US health systems now procure molecular testing through direct laboratory partnerships rather than bundled oncology drug contracts. This pattern is most visible in Texas and Florida, where independent physician associations negotiate standalone testing pricing with reference laboratories.
Global Oncology Molecular Diagnostics Market Segmentation
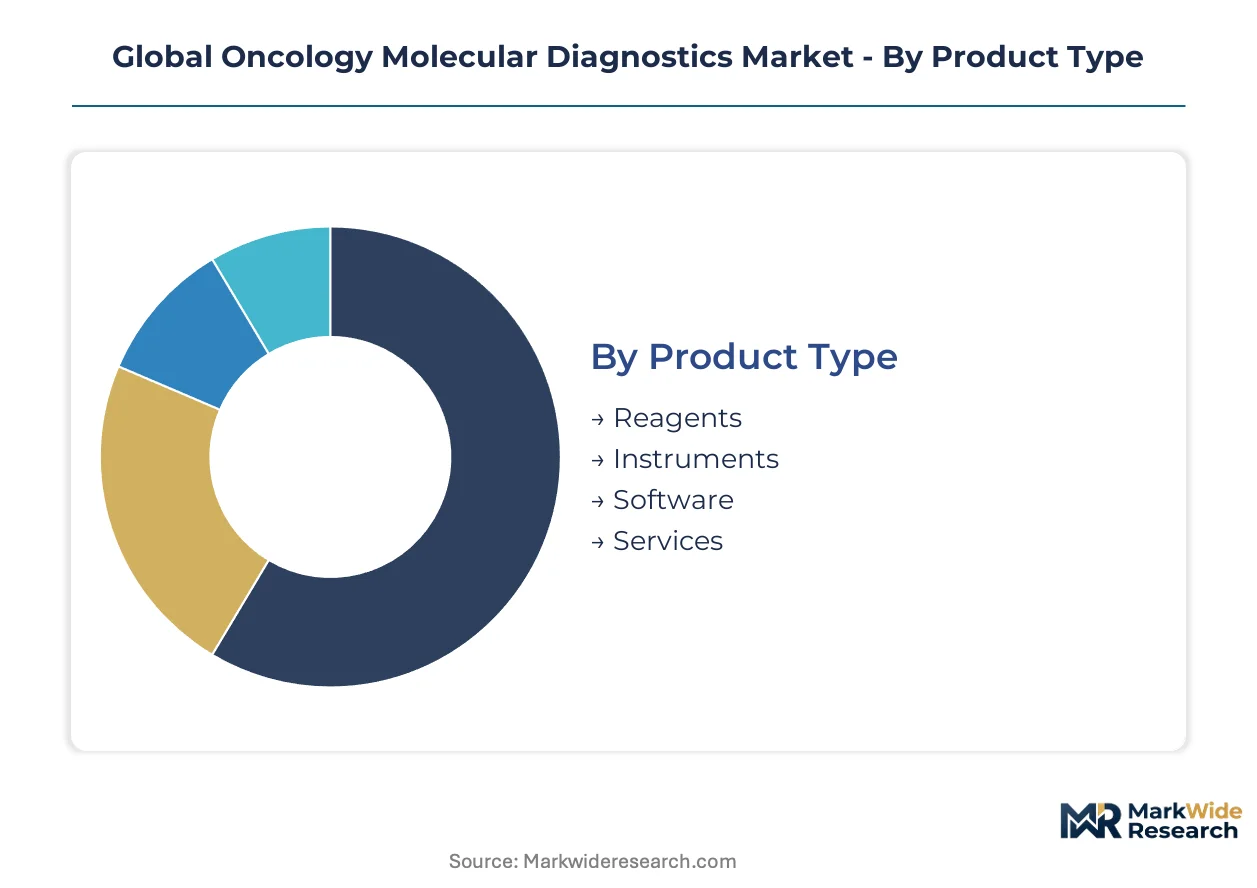
Oncology molecular diagnostics segments by product, technology, end user, and application each carry distinct service intensity profiles and margin structures. Reagent contracts demand continuous technical support and lot-to-lot consistency management. Instrument placements require field engineering networks that reshape competitive economics across geographies.
Product Type:
After-sales service intensity varies dramatically across product categories, with reagent portfolios consuming 60-70% of field application scientist hours due to assay troubleshooting and validation support demands.
- Reagents:Consumable kits for nucleic acid extraction, amplification, and library preparation constitute the recurring revenue foundation. Hospital laboratories in the United States and Germany negotiate multi-year supply agreements with embedded technical support. The FDA's IVDR pathway mandates lot release documentation that elevates quality assurance burdens for manufacturers.
- Instruments:Sequencing platforms, thermal cyclers, and hybridization systems require installation validation and preventive maintenance contracts. China's NMPA breakthrough designation accelerates instrument registration but demands localized service infrastructure in Shanghai and Beijing clusters.
- Software:Bioinformatics pipelines for variant annotation and clinical reporting operate on subscription models with cloud-based updates. Research institutions in Japan prioritize PMDA-compliant security architectures for patient data handling.
- Services:Contract testing and companion diagnostic co-development generate project-based revenue with milestone dependencies. Oncology clinics in Texas and Florida outsource complex NGS interpretation to reference laboratories with CAP accreditation.
By volume, Reagents leads. By growth pace, Services is ahead.
Technology:
Cost tier stratification separates gold-standard clinical workflows from emerging research applications, with reimbursement codes determining viable price points for each modality.
- PCR:Real-time and digital PCR platforms deliver rapid turnaround for single-gene hotspot mutations with established CPT coding. Community oncology practices in the United States deploy point-of-care PCR for same-day EGFR and KRAS results. Reagent rental programs reduce capital barriers for mid-sized diagnostic labs.
- NGS:Targeted gene panels and whole exome sequencing enable comprehensive genomic profiling from minimal tissue. Academic medical centers in Germany and China prioritize NGS for immuno-oncology biomarker discovery. Turnaround time compression to 7-10 days drives competitive differentiation.
- FISH:Fluorescence in situ hybridization retains dominance for gene fusion detection in hematological malignancies. Diagnostic laboratories maintain FISH capability for HER2 and ALK testing with established clinical utility evidence.
- Immunohistochemistry:Protein expression assays for PD-L1 and mismatch repair proteins require pathologist interpretation with quantitative scoring algorithms. EMA's IVDR elevates antibody validation documentation for European market access.
By installed base, PCR dominates. By expansion trajectory, NGS is climbing the fastest.
End User:
Customer type concentration shapes go-to-market economics, with procurement centralization in health systems fragmenting vendor relationships that previously ran through pharmaceutical distributors.
- Hospitals:Integrated delivery networks consolidate molecular pathology into centralized laboratories serving multiple campuses. United States health systems in California and New York negotiate enterprise pricing for NGS platforms with standardized assay menus.
- Diagnostic Labs:Reference laboratories process samples from community oncologists with specialized biomarker expertise. China's independent clinical testing market expands in Guangzhou and Chengdu under NMPA laboratory-developed test frameworks.
- Research Institutions:Academic centers drive technology adoption ahead of clinical validation with grant-funded instrumentation. Germany's Max Planck and Helmholtz networks anchor European research demand for single-cell sequencing.
- Oncology Clinics:Community cancer centers adopt decentralized testing to accelerate treatment decisions. Independent physician associations in Florida procure liquid biopsy panels through direct laboratory partnerships.
By specimen volume, Diagnostic Labs leads. By adoption velocity, Oncology Clinics is gaining share fastest.
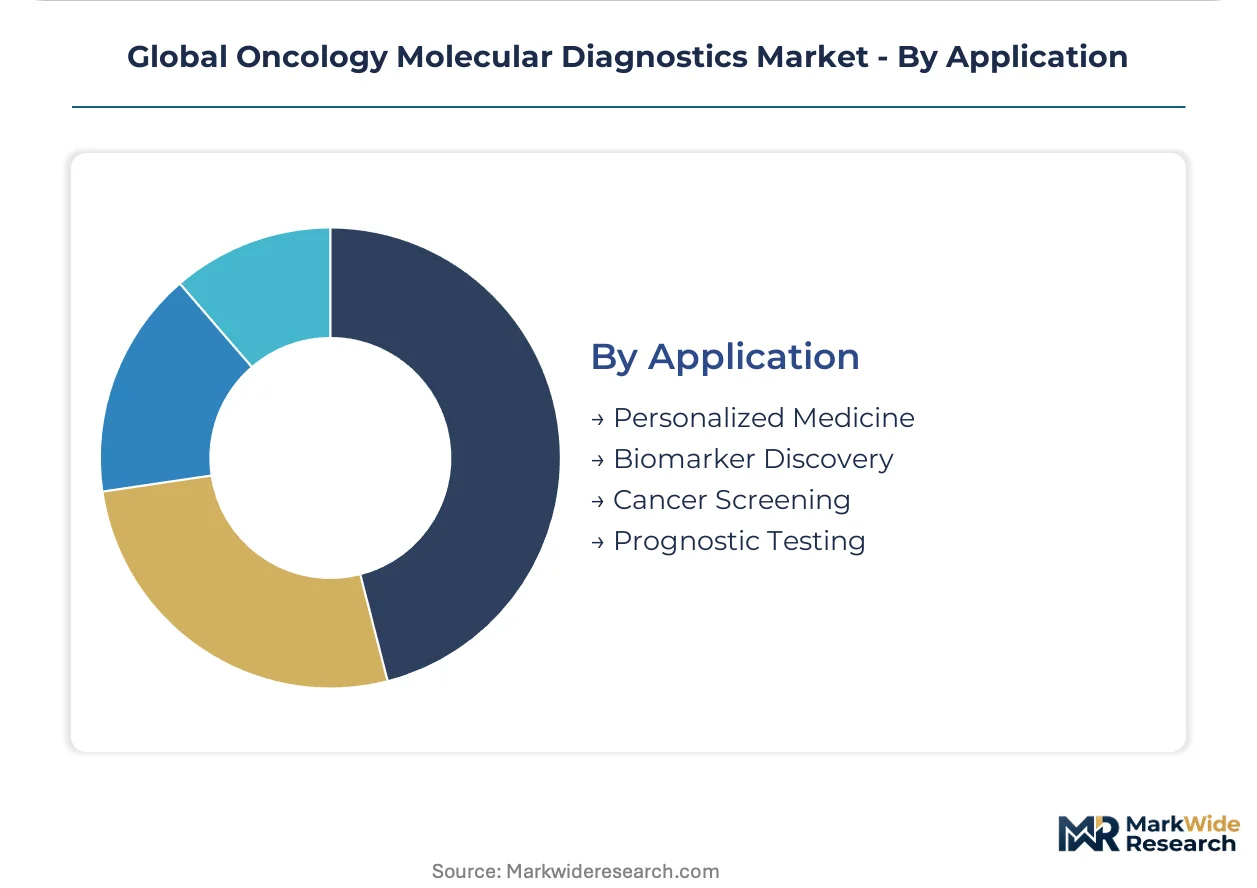
Application:
Maturity differentiation separates reimbursed clinical utilities from investigational use cases, with payer coverage determinations constraining addressable market expansion for emerging applications.
- Personalized Medicine:Companion diagnostic testing matches patients to targeted therapies with FDA-approved indications. United States oncology practices integrate EGFR, ALK, and BRAF testing into standard lung cancer workups. Pharmaceutical sponsors fund assay development to secure accelerated drug approvals.
- Biomarker Discovery:Research-phase genomic profiling identifies novel therapeutic targets and resistance mechanisms. China's biotech clusters in Suzhou and Shanghai contract academic medical centers for prospective cohort sequencing.
- Cancer Screening:Multi-cancer early detection assays analyze circulating tumor DNA for asymptomatic population surveillance. Payer coverage uncertainty in Germany and the United States limits commercial deployment pending prospective validation data.
- Prognostic Testing:Minimal residual disease monitoring tracks treatment response and recurrence risk in hematological malignancies. Sensitivity limitations at sub-1% variant allele frequencies restrict clinical utility in solid tumors.
By revenue concentration, Personalized Medicine leads. By development investment, Cancer Screening shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated health systems and specialized oncology networks concentrate procurement authority in the United States, Germany, China, Japan, and the United Kingdom, with each market exhibiting distinct regulatory pacing and reimbursement frameworks.
United States
Academic medical centers in Boston and Houston drive NGS platform adoption for immuno-oncology biomarker discovery. FDA's IVDR pathway mandates companion diagnostic co-development with targeted therapies, accelerating pharmaceutical partnerships. Texas and Florida health systems negotiate standalone molecular testing contracts through independent physician associations.
Germany
Max Planck and Helmholtz research networks anchor European demand for single-cell sequencing technologies. EMA's IVDR enforcement elevates conformity assessment burdens through 23 notified bodies, extending market entry timelines. Munich and Heidelberg clusters concentrate diagnostic laboratory capacity for hematological malignancy testing.
China
NMPA's breakthrough device designation expedites review timelines for innovative oncology diagnostics in the world's second-largest pharmaceutical market. Suzhou and Shanghai biotech clusters contract academic centers for prospective cohort sequencing. Guangzhou and Chengdu expand independent clinical testing under laboratory-developed test frameworks.
Japan
PMDA's regenerative medicine pathway accelerates companion diagnostic approvals for immuno-oncology combinations in Asia-Pacific's most profitable reimbursed market. Tokyo and Osaka metropolitan areas concentrate precision medicine infrastructure. Research institutions prioritize PMDA-compliant security architectures for patient data handling.
United Kingdom
NHS England's genomic medicine service consolidates molecular pathology into regional laboratory hubs serving multiple hospital trusts. MHRA post-Brexit regulatory divergence creates parallel submission requirements for US and European manufacturers. London and Cambridge clusters concentrate bioinformatics talent for variant interpretation pipeline development.
Global Oncology Molecular Diagnostics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across instrument, reagent, and service layers. The vendor base stratifies into three tiers: vertically integrated platform holders capturing high-throughput clinical workflows, specialized assay developers targeting liquid biopsy niches, and regional service laboratories expanding through reference testing contracts. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and geographic expansion through regulatory arbitrage in breakthrough designation markets.
Within the platform-holder tier, Roche Diagnostics and Illumina occupy positions defined by instrument-reagent integration and sequencing hardware dominance respectively. Thermo Fisher Scientific exemplifies the diversified life sciences conglomerate archetype spanning reagent chemistry and analytical instruments. Guardant Health represents the specialized liquid biopsy developer segment competing through blood-based assay innovation rather than installed instrument bases.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Illumina |
| QIAGEN |
| Danaher |
| Agilent Technologies |
| Sysmex Corporation |
| Guardant Health |
| Others |
Supply & Pricing Matrix
Illumina's proprietary flow-cell chemistry concentration in San Diego and Singapore sequencing consumable production anchors margin capture downstream at diagnostic laboratories locked into high-margin recurring reagent purchases. This upstream chemistry control shapes pricing power across the oncology molecular diagnostics value chain, with proprietary nucleic acid amplification kits capturing the largest profit pools.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate reagent supply agreements between manufacturers and hospital laboratories in the United States and Germany. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated companion diagnostic assays from research-use-only panels and unbundled software subscriptions. Pricing pressure stems from China's NMPA breakthrough designation accelerating domestic competitor entry at lower price points. Community oncology clinics exhibit highest price sensitivity due to direct laboratory procurement without pharmaceutical distributor subsidies, while academic medical centers prioritize turnaround time over per-test cost.
Supply Chain Analysis
Contract manufacturing of sequencing instruments concentrates at Thermo Fisher Scientific facilities in Singapore and Shanghai, with specialized reagent production anchored in Carlsbad, California and Vilnius, Lithuania. Raw material dependencies span semiconductor-grade silicon for flow cells, fluorophore-conjugated nucleotides for PCR chemistries, and recombinant polymerases for amplification enzymes. Single-source vulnerability in proprietary sequencing chemistry patents creates supply chain risk if licensing disputes disrupt reagent availability. Distribution runs through direct field service organizations for instrument placements and third-party logistics for temperature-controlled reagent delivery to diagnostic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oncology molecular diagnostics market is recovering from a cyclical trough driven by post-pandemic laboratory capital expenditure normalization and deferred instrument upgrade cycles. Pharmaceutical companion diagnostic co-development pipelines are restocking after two years of delayed clinical trial initiations.
For Market Incumbents: Pre-empt emerging liquid biopsy platform entrants by accelerating backward integration into circulating tumor DNA enrichment chemistries and locking community oncology clinics into multi-year reagent rental programs. Roche Diagnostics and Illumina should prioritize CAP-accredited reference laboratory partnerships in Texas and Florida to defend against independent physician association procurement fragmentation. FDA IVDR pathway expertise constitutes a defendable moat as European conformity assessment timelines extend market entry barriers for mid-sized competitors. For New Entrants and Emerging Players: Pursue point-of-care oncology clinic segments in China's Guangzhou and Chengdu clusters where NMPA laboratory-developed test frameworks enable faster commercialization than FDA-equivalent pathways. Blood-based minimal residual disease monitoring for hematological malignancies represents the most penetrable white space given established clinical utility evidence and reimbursed CPT coding. A go-to-market angle anchored in same-day turnaround PCR platforms for community cancer centers bypasses Illumina's sequencing hardware lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward specialized liquid biopsy assay developers with proprietary bioinformatics pipelines and prospective clinical validation cohorts rather than undifferentiated instrument manufacturers facing reagent margin compression. Long-term viability across a 5-10 year window hinges on multi-cancer early detection reimbursement decisions by CMS and German statutory health insurers. The signal to watch is payer coverage policy publication for blood-based screening panels, which would trigger population-scale addressable market expansion beyond affluent patient segments.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Pharmaceutical partnerships with FDA IVDR pathway expertise accelerate targeted therapy approval timelines. |
| Liquid Biopsy Assay Validation | Prospective cohort studies for circulating tumor DNA tests establish clinical utility for minimal residual disease monitoring. |
| Point-of-Care Platform Deployment | Decentralized PCR systems in Texas and Florida oncology clinics enable same-day treatment decisions. |
| Bioinformatics Pipeline Standardization | Cloud-based variant interpretation reduces discordance between laboratories using different annotation databases. |
| Multi-Cancer Early Detection Reimbursement Strategy | CMS and German payer coverage determinations will dictate population-scale commercial deployment feasibility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with molecular pathology laboratory directors, companion diagnostic regulatory affairs leads, hospital GPO contracts managers, and pharmaceutical biomarker development executives; and secondary validation against FDA 510(k) filings, EMA IVDR submission databases, ClinicalTrials.gov protocol records, and CMS Medicare reimbursement coding updates. Bottom-up triangulation across instrument placement data, reagent consumption estimates, and service contract values reconciled against top-down pharmaceutical R&D spending on oncology biomarker programs.
Forecast inputs considered technology adoption curves across PCR, NGS, FISH, and immunohistochemistry modalities over the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user channel concentration, and application maturity from personalized medicine through cancer screening. CAGRs were derived from instrument installed base expansion rates, reagent pull-through per system, and services revenue per test interpretation. Industry-specific forecast inputs encompassed NMPA breakthrough designation approval timelines and EMA notified body capacity constraints for IVDR conformity assessments.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, pharmaceutical R&D budget allocations, or biotech venture funding availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and payer coverage expansion timelines. Quarterly review of FDA IVDR submission volumes, NMPA breakthrough designation grants, and CMS preliminary coverage determinations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Global Clinical Oncology NGS Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
US Cancer Biopsy Market