
 Brain Tumor Diagnostics Market | 2026-2036
Brain Tumor Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
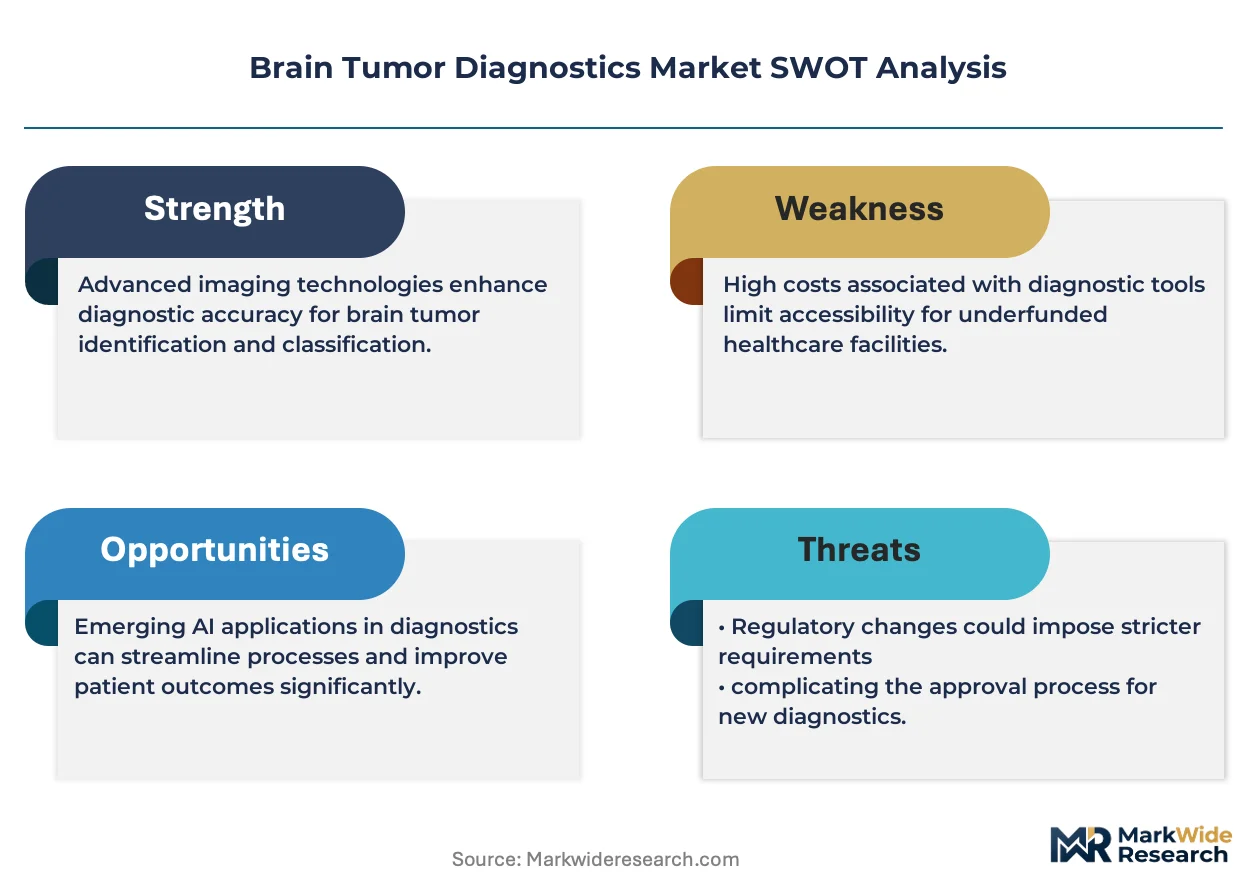
Brain Tumor Diagnostics Market Analysis
Artificial intelligence integration into neuroimaging workflows is rewriting how radiologists detect and characterize gliomas, meningiomas, and metastatic lesions. Siemens Healthineers leverages deep learning algorithms to differentiate tumor grades from multiparametric MRI sequences. Thermo Fisher Scientific anchors its position through genomic testing panels that guide targeted therapy selection for IDH-mutant gliomas. Illumina specializes in next-generation sequencing platforms that enable molecular subtyping of brain tumors at academic medical centers.
Brain tumor diagnostics encompasses imaging modalities, molecular assays, and tissue analysis tools designed to detect primary and secondary central nervous system neoplasms with spatial resolution down to millimeter-scale lesions and genetic sensitivity for single-nucleotide variants. Magnetic resonance imaging dominates clinical workflows due to superior soft-tissue contrast for preoperative tumor boundary delineation, while liquid biopsy represents the fastest-expanding technology segment as blood-based biomarkers circumvent risks of invasive stereotactic biopsy. Genomic testing commands premium pricing within the technology dimension because companion diagnostic linkages to FDA-approved therapies create locked-in referral flows from neuro-oncologists.
The FDA regulates brain tumor diagnostic devices through the Center for Devices and Radiological Health, with Breakthrough Device Designation compressing review timelines for AI-augmented imaging tools. The EU Medical Device Regulation imposes stricter clinical evidence requirements on software-as-a-medical-device products, reshaping how manufacturers validate algorithm performance across diverse patient populations. Stakeholders must monitor evolving reimbursement codes for molecular diagnostics as payors increasingly tie coverage decisions to demonstrated improvement in progression-free survival endpoints.
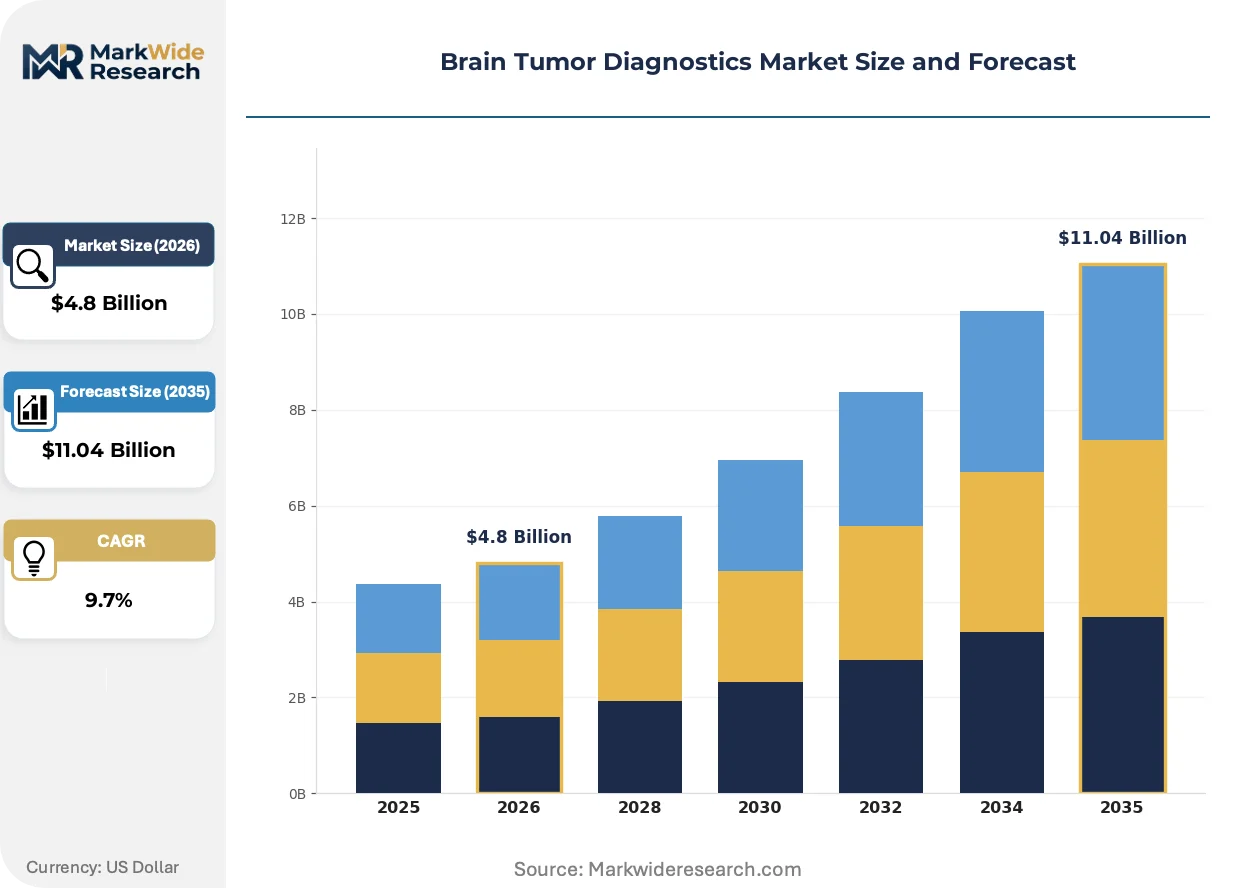
Market Dynamics
AI-augmented neuroimaging is compressing diagnostic timelines from weeks to hours, forcing incumbent manufacturers to restructure R&D budgets toward algorithm validation and regulatory submissions for software-as-a-medical-device products.
Growth Catalysts
- Medicare reimbursement expansion:The Centers for Medicare & Medicaid Services now covers molecular diagnostic testing for IDH-mutant gliomas, directing patient flow toward precision oncology pathways in US academic medical centers.
- EU MDR accelerated pathways:The Medical Device Regulation's fast-track provisions for breakthrough technologies are compressing CE marking timelines for AI-integrated imaging platforms across German and French hospital networks.
- Liquid biopsy biomarker validation:Blood-based detection of circulating tumor DNA is displacing invasive stereotactic biopsy for recurrent glioblastoma monitoring, reducing procedural risk and recovery time.
Market Restraints
- Neodymium supply concentration:Rare earth magnet dependency for MRI systems concentrates in Chinese processing facilities, exposing OEMs to export quota volatility and price spikes.
- Algorithm training data scarcity:AI diagnostic tools require annotated imaging datasets spanning diverse patient demographics, yet multicenter data sharing faces HIPAA and GDPR fragmentation.
- Specialized neuroradiologist shortage:The pipeline of fellowship-trained readers capable of validating AI outputs remains constrained in rural US markets and secondary European hospitals.
Strategic Opportunities
- India diagnostic network expansion:Tier-2 and Tier-3 cities lack access to advanced neuroimaging, creating white space for teleradiology platforms connecting regional hospitals to metropolitan specialist hubs.
- Japan's aging demographic:METI funding for elderly cancer screening programs is expanding reimbursement for MRI-based early detection protocols in prefectural health systems.
- Multi-omics convergence:Integration of radiomics features with genomic profiling is enabling synthetic biomarker discovery, opening companion diagnostic development partnerships between imaging vendors and sequencing firms.
Industry Challenges
- Cross-border data governance:Cloud-based AI diagnostic tools face divergent data localization requirements across US HIPAA, EU GDPR, and China's Cybersecurity Law, complicating single-platform deployment.
- Legacy PACS integration:Hospital information systems built on decade-old DICOM standards require costly middleware development to interface with modern deep learning inference engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Tumor Diagnostics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Resonance Imaging, Computed Tomography, PET Scans, Biopsy Tools Technology: Molecular Imaging, Genomic Testing, Imaging Biomarkers, Liquid Biopsy Application: Diagnostic Imaging, Surgical Planning, Treatment Monitoring, Patient Monitoring End User: Hospitals, Diagnostic Centers, Research Institutions, Cancer Clinics |
| Companies Covered | Canon Medical Systems Corporation, Thermo Fisher Scientific Inc., General Electric Company, Illumina Inc., QIAGEN N.V., Siemens Healthineers AG, F. Hoffmann-La Roche Ltd., Abbott Laboratories, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Tumor Diagnostics Market Emerging Trajectories
Neuroimaging workflows are undergoing algorithmic transformation as regulatory frameworks adapt to software-centric diagnostic modalities and procurement patterns shift toward integrated service contracts.
Multiparametric MRI synthesis is digitizing conventional contrast-enhanced scanning protocols. Academic medical centers in the United States are deploying deep learning models to generate synthetic contrast images from non-contrast sequences, reducing gadolinium exposure in pediatric and renal-impaired populations. This capability is compressing scan duration and reagent costs while maintaining diagnostic accuracy for tumor boundary delineation.
The FDA's Breakthrough Device Designation is restructuring validation requirements for AI-augmented tools. Manufacturers must now demonstrate algorithm performance across demographically diverse patient cohorts rather than single-site studies, elevating clinical evidence costs but accelerating market access for validated platforms. European manufacturers are responding by establishing US-based training datasets to satisfy FDA demographic representativeness standards.
Hospital procurement departments are consolidating diagnostic service contracts under single-vendor frameworks. Large US health systems including Kaiser Permanente and Mayo Clinic are bundling imaging hardware, software licenses, and AI analytics into multi-year agreements, displacing point-solution purchasing. This concentration is most visible in California and Minnesota, where integrated delivery networks command sufficient volume to negotiate outcome-based performance clauses.
Brain Tumor Diagnostics Market Segmentation
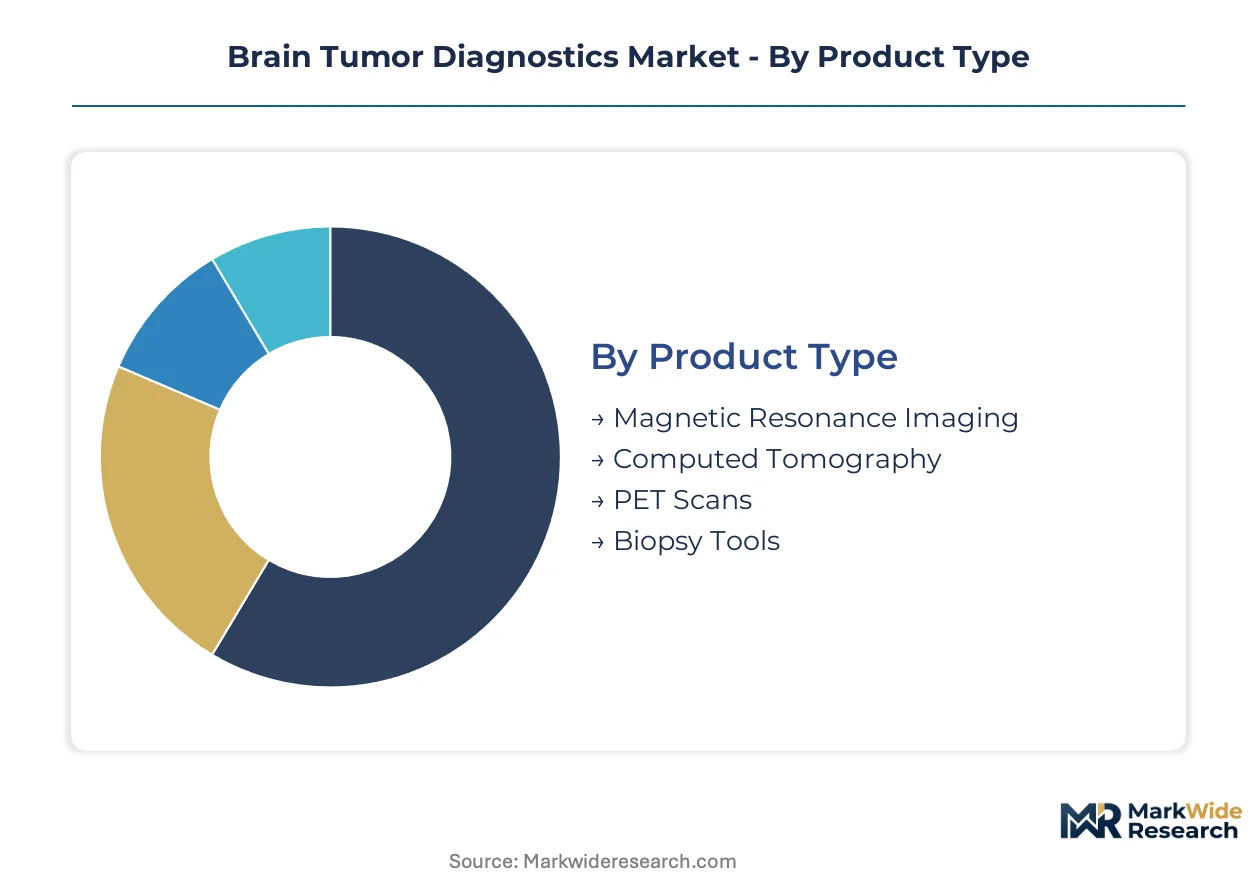
Brain tumor diagnostics segmentation reveals how capital-intensive imaging hardware, consumable molecular assays, and software analytics command fundamentally different procurement cycles and margin structures. Understanding these divisions clarifies where vendors can extract recurring revenue versus one-time equipment sales.
Product Type:
Magnetic Resonance Imaging systems turn over every 7-10 years, while biopsy tools and contrast agents cycle annually, creating divergent cash flow profiles across manufacturer portfolios.
- Magnetic Resonance Imaging:Multiparametric scanners with 3T field strength and advanced diffusion-weighted sequences enable millimeter-scale glioma boundary detection. Siemens Healthineers and GE HealthCare dominate installed base expansion at US academic medical centers seeking FDA Breakthrough Device Designation for AI-integrated platforms.
- Computed Tomography:Emergency departments deploy CT for rapid intracranial hemorrhage exclusion before MRI referral, with 64-slice systems representing the current procurement standard. German hospital networks prioritize photon-counting detector upgrades to reduce radiation dose in pediatric neuro-oncology protocols.
- PET Scans:Radiotracer-dependent metabolic imaging for distinguishing tumor recurrence from radiation necrosis.
- Biopsy Tools:Stereotactic needle systems and navigation frames for tissue acquisition.
Magnetic Resonance Imaging dominates installed base. Biopsy Tools represent where expansion concentrates as minimally invasive techniques displace open surgical sampling.
Technology:
Cost tiers separate capital-heavy imaging platforms from consumable molecular assays, with genomic testing commanding premium pricing through companion diagnostic linkages to FDA-approved therapies.
- Molecular Imaging:Radiolabeled tracers targeting amino acid metabolism and hypoxia markers enable biological characterization beyond anatomical boundaries. US neuro-oncology programs at Mayo Clinic and MD Anderson drive adoption of FET-PET for glioma grading.
- Genomic Testing:Next-generation sequencing panels detect IDH mutations, MGMT methylation, and 1p/19q co-deletions to guide targeted therapy selection. Illumina platforms anchor molecular subtyping workflows at European comprehensive cancer centers navigating EU MDR clinical evidence requirements.
- Imaging Biomarkers:Radiomics feature extraction from standard-of-care scans.
- Liquid Biopsy:Circulating tumor DNA detection from blood samples.
Genomic Testing dominates installed base. Liquid Biopsy is where expansion concentrates as blood-based monitoring displaces repeated stereotactic procedures for recurrent glioblastoma.
Application:
Volume concentration follows the patient journey from initial detection through longitudinal surveillance, with surgical planning representing the highest-value intervention point.
- Diagnostic Imaging:Initial detection and characterization of primary and metastatic central nervous system lesions. US Medicare reimbursement for MRI-based glioma protocols drives patient flow toward precision oncology pathways at concentrated academic medical centers.
- Surgical Planning:Preoperative mapping of eloquent cortex and white matter tracts to maximize resection while preserving neurological function. German neurosurgical departments integrate intraoperative MRI with neuronavigation to update resection boundaries in real time.
- Treatment Monitoring:Response assessment following chemoradiation.
- Patient Monitoring:Longitudinal surveillance for recurrence detection.
Diagnostic Imaging dominates installed base. Surgical Planning is where expansion concentrates as functional mapping capabilities differentiate high-volume neuro-oncology centers.
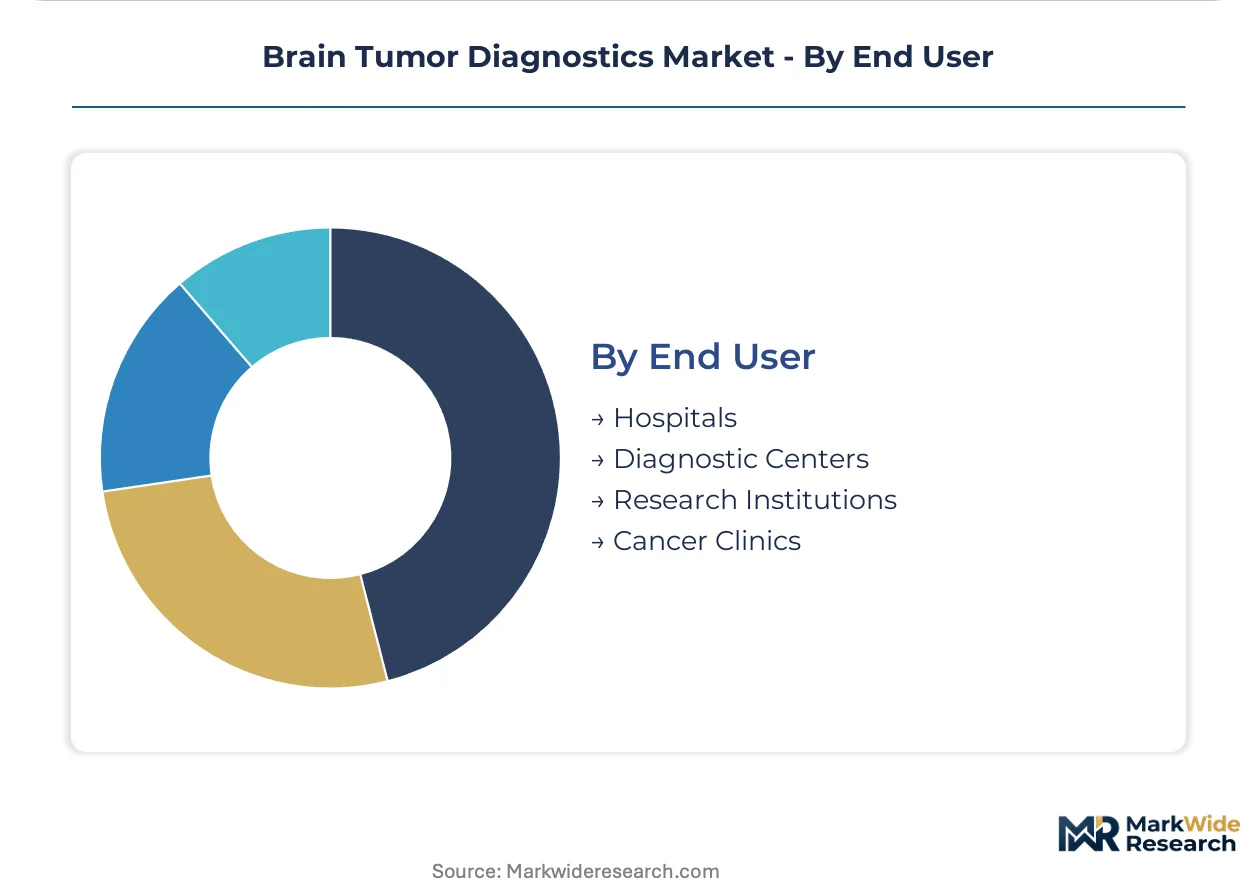
End User:
Customer type determines procurement authority, with integrated delivery networks consolidating purchasing power while research institutions drive early technology validation.
- Hospitals:Tertiary care centers with dedicated neuro-oncology programs and intraoperative imaging suites. Kaiser Permanente and similar US systems negotiate multi-year service contracts bundling hardware, software licenses, and AI analytics under single-vendor frameworks.
- Diagnostic Centers:Independent imaging facilities and outpatient radiology chains. Indian tier-2 cities present white space for teleradiology platforms connecting regional centers to metropolitan neuroradiologist hubs.
- Research Institutions:Academic medical centers conducting clinical trials and algorithm development.
- Cancer Clinics:Community oncology practices with limited neuro-oncology specialization.
Hospitals dominate installed base. Diagnostic Centers represent where expansion concentrates as ambulatory reimbursement policies shift lower-complexity neuroimaging outside inpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese imaging equipment flows into US academic medical centers, while Indian teleradiology platforms export diagnostic interpretation services to underserved markets across Southeast Asia and the Middle East.
United States
Medicare reimbursement policies for precision oncology diagnostics concentrate patient flow at academic medical centers in Boston, Houston, and Rochester. The FDA's Breakthrough Device Designation compresses review timelines for AI-augmented neuroimaging tools. Mayo Clinic in Minnesota anchors integrated service contracts bundling hardware, software licenses, and AI analytics under multi-year frameworks.
Germany
Photon-counting CT detector upgrades and intraoperative MRI neuronavigation systems drive procurement at university hospitals in Munich and Heidelberg. The EU Medical Device Regulation imposes stricter clinical evidence requirements on software-as-a-medical-device products. Siemens Healthineers anchors AI-integrated platform validation across German hospital networks seeking CE marking acceleration.
Japan
METI funding for elderly cancer screening programs expands reimbursement for MRI-based early detection protocols. The Pharmaceuticals and Medical Devices Agency regulates AI diagnostic software through a fast-track approval pathway for breakthrough technologies. Prefectural health systems in Kanto and Kansai regions deploy advanced neuroimaging for aging demographic tumor surveillance.
India
Tier-2 and Tier-3 cities lack access to advanced neuroimaging, creating white space for teleradiology platforms connecting regional hospitals to metropolitan specialist hubs. The Central Drugs Standard Control Organization regulates diagnostic device imports and software validation requirements. Maharashtra and Karnataka host emerging diagnostic networks leveraging cloud-based AI interpretation for glioma detection.
United Kingdom
NHS England's specialized commissioning frameworks concentrate high-complexity neuro-oncology diagnostics at designated cancer centers in London, Manchester, and Birmingham. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR standards while streamlining UK-specific AI validation pathways. Academic medical centers in the Southeast anchor genomic testing partnerships for IDH-mutant glioma subtyping.
Brain Tumor Diagnostics Market Vendor Landscape
On the supply side, the industry is consolidating around integrated diagnostic platforms that bundle imaging hardware, molecular assays, and AI analytics under single-vendor contracts. Tiered competition separates capital-intensive imaging OEMs from consumable-focused molecular testing specialists and emerging software-centric disruptors. Dominant competitive moves include strategic partnerships between imaging vendors and sequencing firms for multi-omics convergence, and geographic expansion into underserved diagnostic networks in India and Southeast Asia.
Within the imaging systems tier, Siemens Healthineers and GE HealthCare exemplify integrated platform providers anchoring US academic medical center procurement. Thermo Fisher Scientific occupies a position representing the molecular diagnostics archetype through genomic testing panels. Among AI-augmented specialists, Philips anchors European hospital network adoption of deep learning inference engines for neuroimaging workflows.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Thermo Fisher Scientific Inc. |
| General Electric Company |
| Illumina Inc. |
| QIAGEN N.V. |
| Siemens Healthineers AG |
| F. Hoffmann-La Roche Ltd. |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| Others |
Supply Flow & Price Mechanics
Chinese rare earth processing clusters in Jiangxi and Inner Mongolia govern neodymium magnet output for MRI systems, translating export quota volatility directly into equipment pricing power for Siemens Healthineers and GE HealthCare contract negotiations with US hospital systems.
Pricing Analysis
Next-generation 3T MRI platforms with integrated AI inference engines command 40-60% premiums over prior-generation 1.5T systems without algorithmic capabilities, while economy-tier refurbished scanners serve price-constrained diagnostic centers in India's tier-3 cities. Three-tier pricing structure across premium AI-integrated, standard conventional, and economy refurbished levels reflects FDA Breakthrough Device Designation status and accompanying reimbursement codes. Pricing pressure stems from Medicare's site-neutral payment policies compressing outpatient imaging margins, with hospital systems exhibiting highest price sensitivity for capital equipment and molecular diagnostic laboratories least sensitive due to companion diagnostic-linked therapy revenues.
Supply Chain Analysis
Upstream feedstock concentration for superconducting wire rests on niobium-titanium alloy production in Germany, Japan, and the United States, while liquid biopsy consumables draw from specialized polymer manufacturing in Singapore and Ireland. Gadolinium-based contrast agents hinge on rare earth separation facilities in China, creating single-source vulnerability for contrast reagent supply. Distribution runs through authorized dealer networks for capital equipment and direct-to-laboratory channels for genomic testing consumables, with hospital GPOs consolidating procurement leverage for high-volume molecular diagnostics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brain tumor diagnostics sits in early-cycle expansion as AI-augmented neuroimaging penetration remains below 15% at US academic medical centers despite FDA Breakthrough Device Designation acceleration, creating runway for algorithm-integrated platform adoption.
For Market Incumbents: Harden installed base retention by embedding AI analytics into existing MRI service contracts at Kaiser Permanente-scale health systems, and accelerate backward integration into neodymium magnet supply through offtake agreements with Chinese processors to offset tariff exposure from export quota volatility.
For New Entrants and Emerging Players: Pursue white-space penetration in India's tier-2 diagnostic center networks through teleradiology platforms connecting regional hospitals to metropolitan neuroradiologist hubs, and target liquid biopsy biomarker development partnerships with European comprehensive cancer centers navigating EU MDR clinical evidence requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors multi-omics convergence plays combining radiomics feature extraction with genomic profiling capabilities, with long-term viability hinging on companion diagnostic lock-in to FDA-approved targeted therapies; watch for inflection signals in Medicare reimbursement expansion for blood-based glioma monitoring protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pathway | Compresses review timelines for AI-integrated neuroimaging platforms at academic medical centers. |
| Hospital System Partnership | Enables multi-year service contracts bundling hardware, software, and AI analytics at integrated delivery networks. |
| CE Marking Pathway | Facilitates EU MDR compliance for software-as-a-medical-device products across German hospital networks. |
| Reimbursement Strategy | Locks in Medicare coverage for molecular diagnostic testing directing patient flow toward precision oncology. |
| Software Companion Development | Creates synthetic biomarker discovery partnerships between imaging vendors and sequencing firms. |
Methodological Framework
The analysis maps neuroimaging hardware, molecular diagnostic assays, and AI-augmented software platforms, each validated through neuroradiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary fieldwork combined with secondary triangulation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body documentation, and hospital procurement records anchored bottom-up and top-down estimates.
Assumptions held regulatory approval pathways and reimbursement codes fixed while varying technology adoption curves and competitive entry timing across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application stage, and end-user procurement authority, with CAGRs derived from installed base turnover rates and consumable utilization patterns per procedure volume. Forecast inputs incorporated MRI system replacement cycles and liquid biopsy biomarker validation timelines.
Sensitivities concentrate around FDA algorithm validation requirements and Medicare reimbursement expansion for precision oncology diagnostics. Cross-checking against CMS Medicare claims data and EU notified body CE marking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market