
 Lung Cancer Diagnostics Market | 2026-2036
Lung Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Cancer Diagnostics Market Intelligence
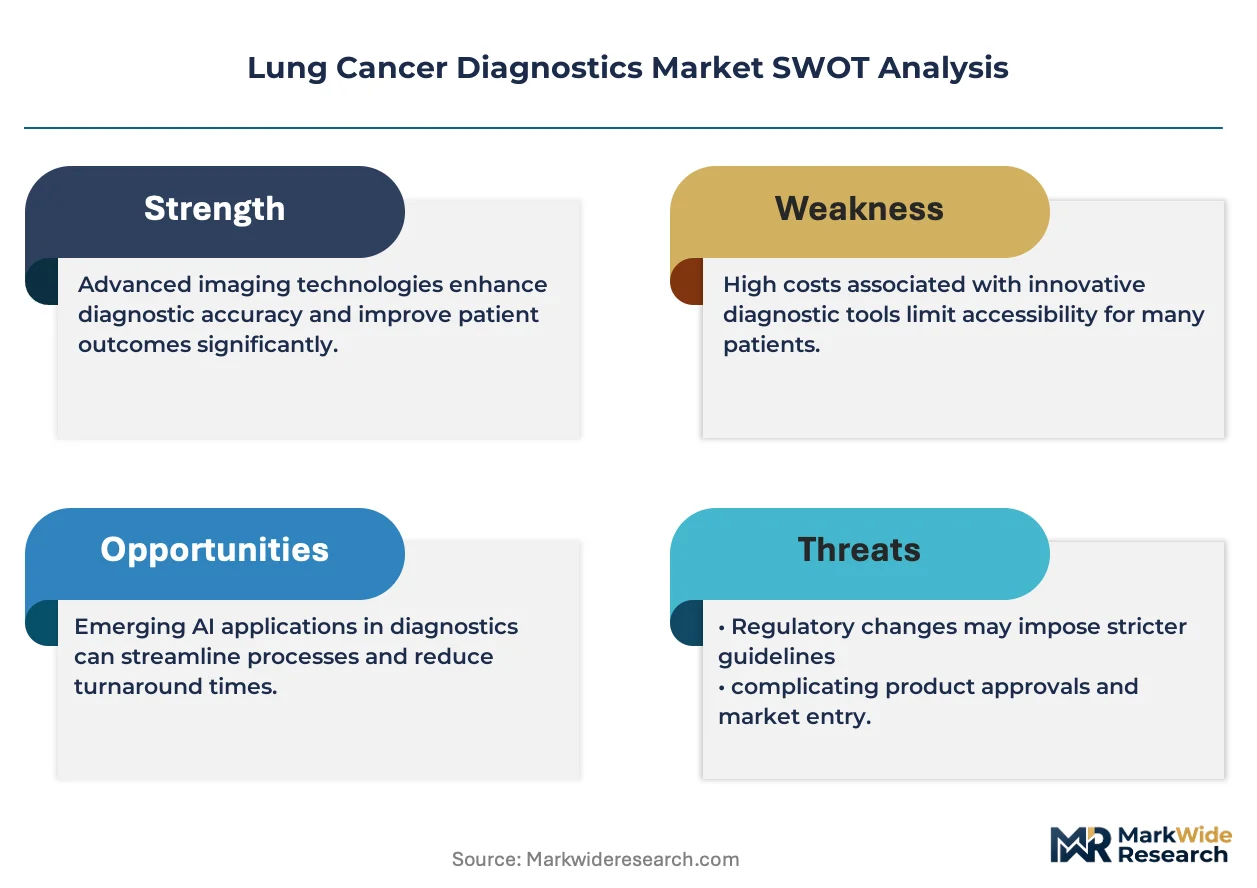
The bundling of diagnostic assays with companion therapeutic guidance is rebalancing procurement decisions for oncology centers. F. Hoffmann-La Roche Ltd leverages its integrated pharma and diagnostics portfolio to offer comprehensive solutions. Illumina Inc. dominates the next-generation sequencing instrument space, critical for genomic profiling. Guardant Health, Inc. specializes in liquid biopsy tests, providing a non-invasive alternative to traditional tissue sampling.
Lung cancer diagnostics encompass a range of methodologies used to identify malignant pulmonary nodules and characterize tumor genetics. These techniques detect specific biomarkers, such as EGFR or ALK mutations, to guide personalized treatment. The primary purpose is to enable early detection, accurate staging, and ongoing monitoring of therapeutic response. Molecular diagnostics and biomarker kits represent the highest-margin product categories, while demand for next-generation sequencing technology is expanding rapidly in diagnostic labs.
Regulatory frameworks, including clearance pathways from the US FDA and CE marking requirements under the EU's MDR, govern market access for new diagnostic tests. In China, the NMPA's stringent approval process influences product localization and clinical trial strategies. Stakeholder success will hinge on navigating disparate reimbursement landscapes and demonstrating clear clinical utility for novel diagnostic platforms.
Market Dynamics
The central force shaping the lung cancer diagnostics market is the clinical transition from tissue-based biopsies to non-invasive liquid biopsies. This shift redefines laboratory workflows, infrastructure investment priorities, and the demand for advanced bioinformatics capabilities for genomic data analysis.
Growth Catalysts
- Liquid Biopsy Adoption:The increasing clinical validation of liquid biopsy for early detection and monitoring provides a non-invasive alternative, accelerating patient screening rates.
- National Screening Programs:Government-led initiatives, particularly in China, are expanding access to low-dose CT scans and subsequent diagnostic testing for high-risk populations.
- Companion Diagnostics:Pharma-diagnostic partnerships are driving demand for tests that identify specific biomarkers, such as EGFR or ALK, to guide targeted therapy selection.
Market Restraints
- Reimbursement Disparity:Inconsistent and often slow reimbursement decisions for novel molecular tests by payers in the US and Europe limit patient access and lab adoption.
- NGS Platform Costs:The high capital expenditure and maintenance costs for next-generation sequencing instruments create a barrier for smaller hospitals and independent laboratories.
- Bioinformatics Bottleneck:A scarcity of trained bioinformaticians to interpret complex genomic data from NGS platforms restricts the scalability of advanced diagnostic services.
Strategic Opportunities
- Minimal Residual Disease Testing:Developing and validating liquid biopsy assays for monitoring minimal residual disease (MRD) post-treatment represents a significant opportunity for longitudinal patient management.
- AI in Pathology:The convergence of artificial intelligence with digital pathology can automate tumor detection and biomarker quantification, improving diagnostic speed and accuracy.
- Emerging Markets Expansion:Expanding diagnostic test availability into Southeast Asian and Latin American markets with rising healthcare investment offers new growth avenues.
Industry Challenges
- Data Interoperability:Integrating genomic data outputs from diverse diagnostic platforms into hospital electronic health record systems creates significant technical and workflow challenges.
- Specialized Talent Scarcity:A global shortage of molecular pathologists and bioinformaticians capable of interpreting complex genomic data limits the operational capacity of diagnostic labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Cancer Diagnostics Market |
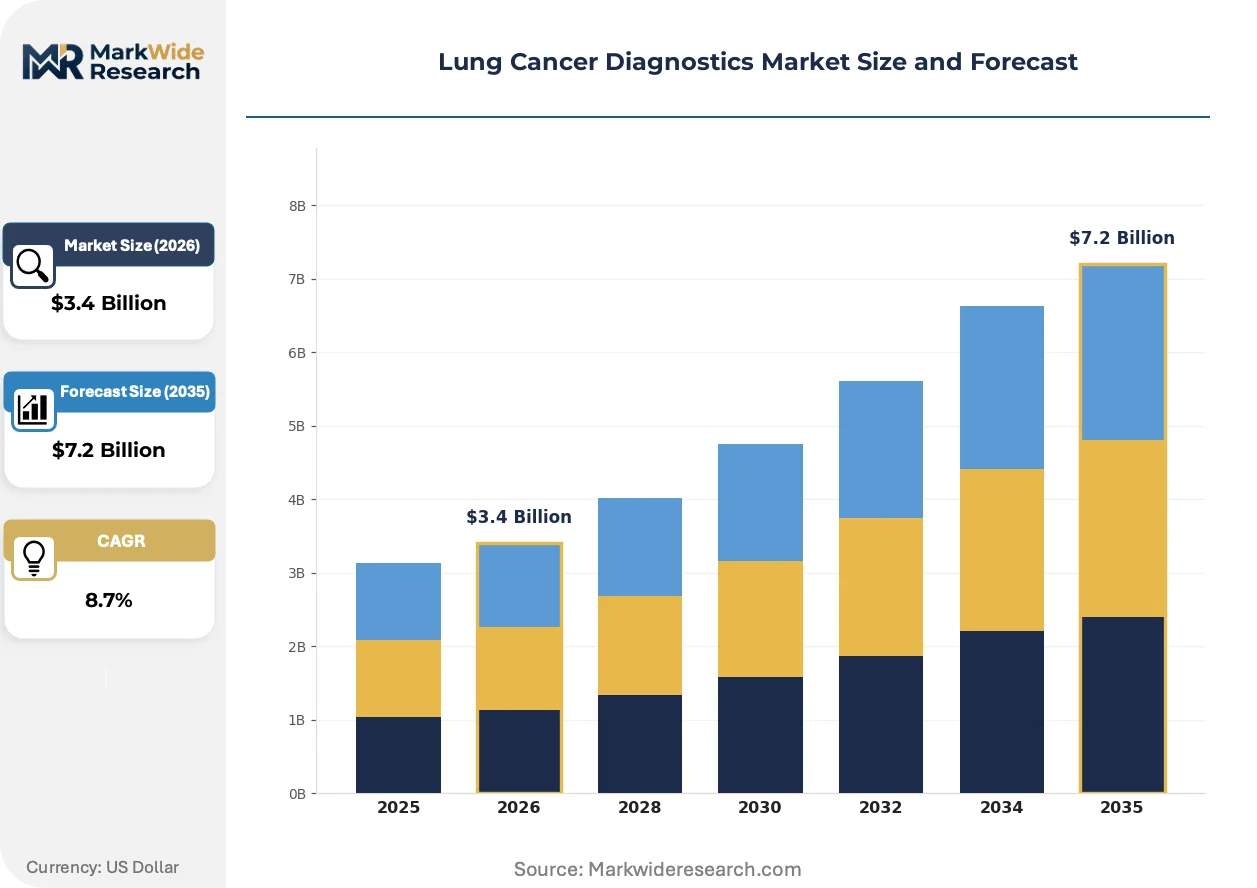
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Biopsy Devices, Molecular Diagnostics, Biomarker Kits Technology: CT Scan, PET Scan, Liquid Biopsy, Immunohistochemistry, Next-Generation Sequencing Application: Early Detection, Staging, Treatment Monitoring, Recurrence Diagnosis, Prognosis End User: Diagnostic Labs, Oncology Centers, Research Institutes, Specialized Clinics |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Illumina Inc, Agilent Technologies, Qiagen, Abbott, Bio-Rad Laboratories, Myriad Genetics, Inc., Guardant Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Cancer Diagnostics Market Strategic Shifts & Innovations
The market is evolving from simple cancer detection towards a model of predictive, data-driven disease management. This evolution is driven by the fusion of molecular biology with advanced computational analysis, fundamentally changing how therapeutic decisions are made.
Artificial intelligence in digital pathology automates the analysis of tissue images, identifying malignant features with high precision. Major academic medical centers and high-volume reference laboratories are rapidly adopting these platforms to enhance diagnostic accuracy and efficiency. This software is integrating directly with laboratory information systems, creating a more seamless and data-rich workflow from slide to report.
Implementation of the European Union's In Vitro Diagnostic Regulation (IVDR) mandates more stringent clinical evidence and post-market surveillance for all diagnostic tests. This significantly elevates the compliance burden and cost for manufacturers seeking CE marking. Laboratory-developed tests (LDTs), particularly in oncology, are most impacted, as many now require formal validation processes previously reserved for commercial kits.
Hospital procurement models are favoring bundled solutions that pair diagnostic assays with analytical software and companion therapeutic guidance. This approach displaces the traditional, transactional purchase of standalone instruments or test kits, favoring vendors with integrated portfolios. The trend is most visible in large US hospital networks and European oncology centers operating under value-based reimbursement schemes.
Lung Cancer Diagnostics Market Segmentation
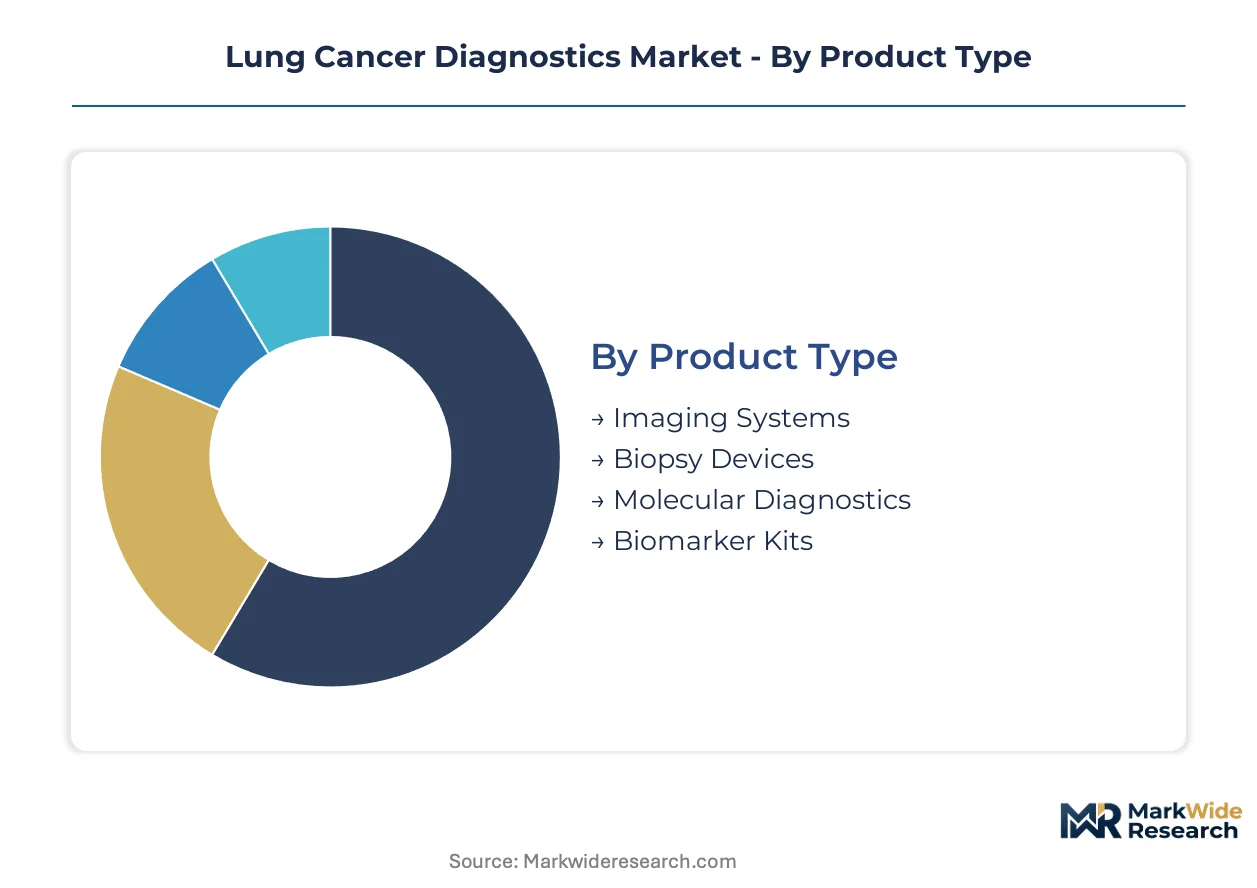
Understanding the varied needs of healthcare providers and diagnostic preferences drives product development in the lung cancer diagnostics market. This segmentation analysis dissects the market by product type, underlying technology, clinical application, and primary end-users. Each category reveals distinct purchasing behaviors and operational requirements.
Product Type:
Buyers in the product type category differentiate based on the invasiveness of the procedure and the specificity of the diagnostic output required.
- Molecular Diagnostics:These assays identify specific genetic mutations or biomarkers, such as EGFR or ALK, critical for guiding targeted therapies. Demand is concentrating in oncology centers in Europe, driven by the increasing availability of personalized medicine.
- Biomarker Kits:These kits provide reagents and protocols for detecting specific biological markers indicative of lung cancer presence or progression. Demand is expanding in specialized clinics in the United States, supporting non-invasive screening initiatives.
- Imaging Systems:These systems include CT scans and PET scans for visual detection of pulmonary nodules.
- Biopsy Devices:These devices facilitate tissue collection for histological examination and genetic profiling.
Volume sits with Imaging Systems; growth tilts toward Molecular Diagnostics.
Technology:
The technological landscape differentiates based on the maturity of the technique and its integration into established clinical workflows.
- Liquid Biopsy:This non-invasive method analyzes circulating tumor DNA or cells from blood samples, offering a less risky alternative to tissue biopsies. Demand is accelerating in diagnostic labs across China, supported by national health initiatives.
- Next-Generation Sequencing:NGS platforms sequence entire genomes or specific gene panels, providing comprehensive genetic profiles for complex tumor characterization. Demand is rapidly expanding in high-volume reference laboratories in Germany, driven by advanced research capabilities.
- CT Scan:This imaging technique uses X-rays to create detailed cross-sectional images of the lungs.
- PET Scan:This nuclear medicine imaging technique detects metabolic activity, helping identify cancerous tissues.
- Immunohistochemistry:This laboratory method uses antibodies to detect specific antigens in tissue samples.
The adoption trajectory for Liquid Biopsy is steeper than for Immunohistochemistry.
Application:
Applications in lung cancer diagnostics are differentiated by the specific stage of disease management they address and the clinical questions they answer.
- Early Detection:These diagnostic efforts aim to identify lung cancer at its nascent stages, significantly improving patient prognosis and treatment outcomes. Demand is concentrated in national screening programs in the United States, leveraging low-dose CT scans.
- Treatment Monitoring:Diagnostics used here track the effectiveness of ongoing therapies, detecting changes in tumor burden or resistance mechanisms. Demand is increasing in oncology centers in France, driven by the need for adaptive treatment strategies.
- Staging:These diagnostics determine the extent of cancer spread within the body.
- Recurrence Diagnosis:This application focuses on identifying cancer return after initial treatment.
- Prognosis:Prognostic tools estimate the likely course and outcome of the disease.
While Staging remains foundational, Early Detection is gaining significant traction.
End User:
End-users are differentiated by their operational scale, patient volume, and the complexity of diagnostic services they provide.
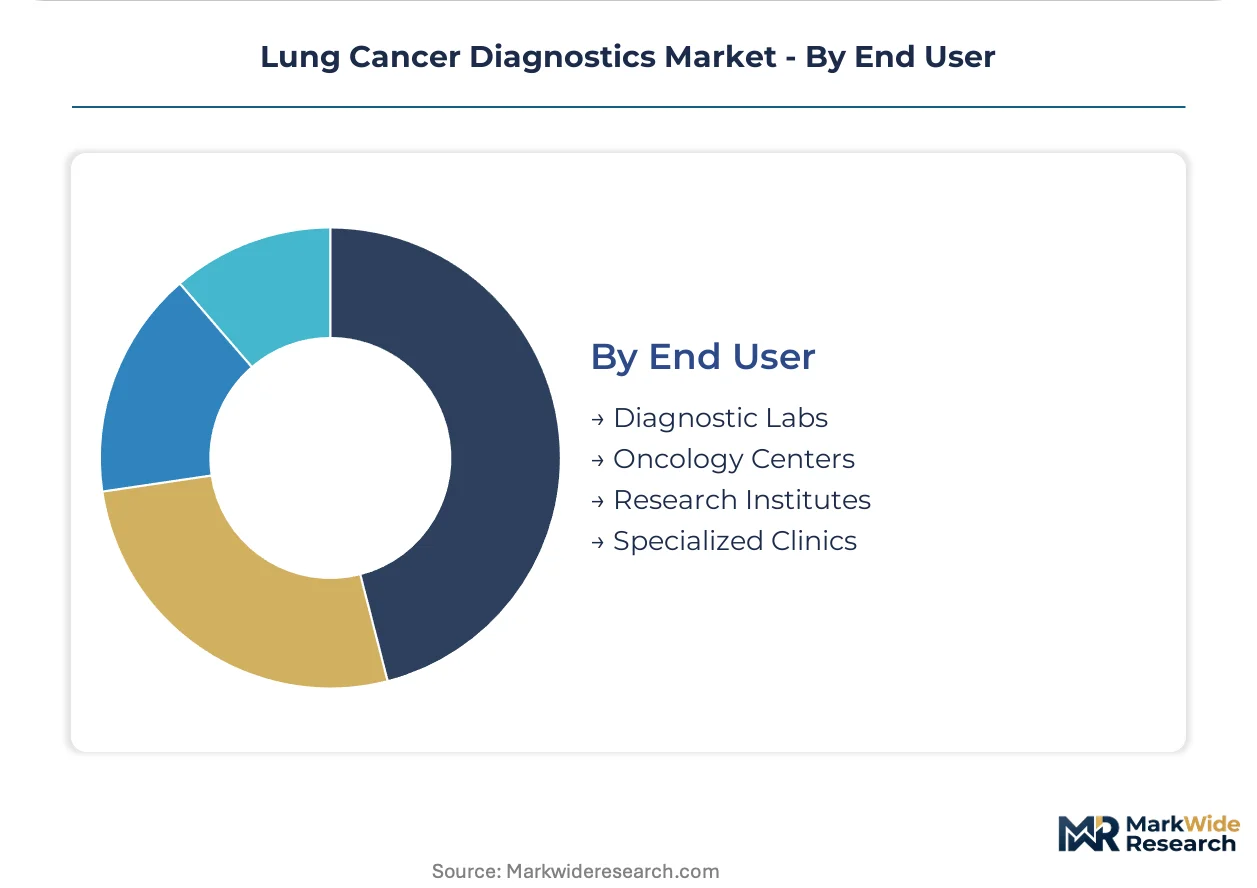
- Diagnostic Labs:These facilities specialize in processing a high volume of samples, often for molecular and genomic testing, serving a broad network of clinicians. Demand is particularly strong in large commercial diagnostic labs in the United Kingdom, driven by outsourcing trends.
- Oncology Centers:These integrated centers provide comprehensive cancer care, including advanced diagnostics, treatment, and patient management. Demand is robust in university-affiliated oncology centers in Japan, integrating research with clinical practice.
- Research Institutes:These institutions focus on developing new diagnostic methods and understanding disease mechanisms.
- Specialized Clinics:These smaller clinics offer targeted diagnostic services, often for specific patient populations.
The largest volume of tests flows through Diagnostic Labs, while Oncology Centers drive innovation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global lung cancer diagnostics market exhibits a clear divide, with significant consumption driven by advanced healthcare systems and national health initiatives. Production and innovation are concentrated in regions with robust research infrastructure and established regulatory frameworks. This dynamic shapes market penetration and the distribution of diagnostic technologies worldwide.
China
National health initiatives and expanding access to specialized cancer care drive demand for lung cancer diagnostics in China. The NMPA's stringent approval process influences product localization and clinical trial strategies. Demand for liquid biopsy accelerates in diagnostic labs across Beijing and Shanghai, supported by these national health programs.
United States
Early detection demand concentrates in national screening programs across the United States, leveraging low-dose CT scans. Inconsistent reimbursement decisions for novel molecular tests by payers limit patient access. Specialized clinics in major metropolitan areas like Boston and San Francisco support non-invasive screening initiatives using biomarker kits.
Germany
Advanced research capabilities in Germany fuel rapid expansion of next-generation sequencing demand within high-volume reference laboratories. CE marking requirements under the EU's MDR govern market access for new diagnostic tests. Diagnostic labs in cities such as Munich and Berlin adopt NGS platforms for comprehensive genetic profiling.
Japan
University-affiliated oncology centers in Japan drive innovation adoption in lung cancer diagnostics, integrating research with clinical practice. The country's national pharmaceutical regulator (PMDA) ensures rigorous evaluation of new diagnostic platforms. Oncology centers in Tokyo and Osaka actively seek advanced diagnostic tools for patient management.
France
Oncology centers in France show increasing demand for treatment monitoring diagnostics, driven by adaptive treatment strategies. European regulatory frameworks, including CE marking requirements, influence test availability and market access. Diagnostic efforts in Paris and Lyon focus on tracking therapeutic effectiveness and detecting resistance mechanisms.
Lung Cancer Diagnostics Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered competitive landscape in lung cancer diagnostics. Large pharmaceutical and diagnostics firms offer integrated solutions, leveraging extensive portfolios across therapeutic and diagnostic areas. Specialized companies concentrate on specific technologies like liquid biopsy or next-generation sequencing. Strategic partnerships and technology licensing are dominant competitive moves, allowing companies to expand their diagnostic offerings.
Within the integrated solutions segment, F. Hoffmann-La Roche Ltd exemplifies a comprehensive approach, leveraging its integrated pharma and diagnostics portfolio to offer bundled solutions for oncology centers. Illumina Inc. occupies a leading position in the next-generation sequencing instrument space, critical for genomic profiling across high-volume diagnostic labs globally. Guardant Health, Inc. represents a pure-play focus on advanced liquid biopsy tests, providing a non-invasive alternative to traditional tissue sampling platforms and anchoring the specialized diagnostics vector for early detection and monitoring.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Illumina Inc |
| Agilent Technologies |
| Qiagen |
| Abbott |
| Bio-Rad Laboratories |
| Myriad Genetics, Inc. |
| Guardant Health, Inc. |
| Others |
Cost & Logistics Intelligence
Specialized enzyme costs, a key input for molecular diagnostics, directly influence the final pricing of advanced genomic profiling tests offered by diagnostic labs. This cost component flows from upstream manufacturers through reagent suppliers and into the final diagnostic service pricing.
Pricing Analysis
Margin compression across routine biomarker kits stems from increasing competition and standardized reimbursement schedules. The dominant pricing model remains per-unit transactional for most diagnostic tests, though value-based agreements are emerging for companion diagnostics tied to specific therapies. Price differentiation traces to the clinical utility of the test and its regulatory clearance status, such as US FDA approval or EU CE marking. Smaller independent laboratories demonstrate higher price sensitivity compared to large university-affiliated oncology centers.
Supply Chain Analysis
Dual-sourcing requirements for critical reagents, such as synthetic oligonucleotides and specialized buffers, are increasingly mandated by large diagnostic labs to mitigate supply disruptions. Geographic supply for these complex components concentrates in the United States, Germany, and China. Raw material dependencies extend to specialized microfluidic chips and high-purity chemicals essential for next-generation sequencing. Intellectual property disputes over proprietary assay designs represent a structural supply chain risk. Distribution runs through a hybrid model combining direct sales channels to major oncology centers and specialized distributor networks for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stringent requirements of the European Union's In Vitro Diagnostic Regulation (IVDR) define a significant cost-of-compliance barrier, effectively creating a moat for established, compliant diagnostic test manufacturers.
For Market Incumbents: Deploy integrated solution bundles that combine diagnostic assays with bioinformatics software and companion therapeutic guidance. This strategy counters emerging pure-play liquid biopsy providers by offering a comprehensive value proposition. Invest heavily in regulatory affairs expertise to navigate disparate global frameworks, mitigating market access risks from novel technologies and reimbursement disparities.
For New Entrants and Emerging Players: A significant price-point gap exists between premium comprehensive genomic profiling and more accessible, targeted molecular tests, presenting an opportunity for focused market entry. Target the underpenetrated minimal residual disease (MRD) testing segment, particularly in emerging markets like Southeast Asia. A go-to-market angle emphasizing cost-effective, non-invasive liquid biopsy for routine monitoring offers a strong differentiation point.
For Investors and Strategic Acquirers: Widespread reimbursement for minimal residual disease (MRD) testing is the leading indicator that validates next-generation diagnostics for long-term patient management. The market offers long-term viability, driven by the shift towards personalized oncology and non-invasive detection. Identify acquisition targets specializing in AI-powered digital pathology or advanced bioinformatics platforms. Expanding national screening programs for liquid biopsy represents a critical inflection signal to monitor.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Integrated Solutions | F. Hoffmann-La Roche Ltd strengthens market position by offering comprehensive diagnostic and therapeutic portfolios. |
| Invest in AI Pathology | Automates tumor detection and biomarker quantification, enhancing diagnostic accuracy and laboratory efficiency. |
| Target Minimal Residual Disease | Guardant Health, Inc. can capture significant value in longitudinal patient management post-treatment. |
| Navigate EU IVDR Compliance | Ensures market access for diagnostic tests in Europe, increasing regulatory burden for manufacturers. |
| Develop Cost-Effective Liquid Biopsy | Accelerates patient screening rates and expands access to non-invasive early detection in China. |
Research Approach
Multi-period observation of biomarker discovery rates and regulatory approval timelines anchored the trend analysis, supplemented by interviews with molecular pathologists, diagnostic lab directors, regulatory affairs leads, and hospital procurement managers. Secondary validation drew from US FDA 510(k) clearances, EU CE marking databases, NMPA approval records, and clinical trial registries. The analysis utilized both bottom-up and top-down triangulation to ensure data consistency and accuracy.
Segment-specific weighting, applied across product type, technology, clinical application, end-user, and regional regulatory environments, informed the quantitative forecast model. Compound annual growth rates were derived by projecting historical growth patterns and anticipated market shifts across the analysis window. Key industry-specific forecast inputs included lung cancer incidence rates and biomarker validation success rates.
Underlying measurement precision varies by segment; established imaging systems carry tighter precision than novel liquid biopsy applications. Forecasts reflect assumptions regarding technological advancements and healthcare infrastructure development. Deviation in national screening program expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market