
 Cancer Biopsy Market | 2026-2036
Cancer Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Biopsy Market Intelligence
Hospital-based oncology departments are consolidating procurement authority for biopsy platforms. Illumina, Inc. leverages sequencing chemistry advances to anchor the molecular diagnostics segment. Thermo Fisher Scientific, Inc. competes across instrument, consumable, and service layers. Guardant Health specializes in circulating tumor DNA assays, positioning it against tissue-based incumbents.
Cancer biopsy encompasses the extraction and histopathological or molecular analysis of tissue or biofluid specimens to characterize malignancy, grade, and therapeutic targets, typically requiring fixation in formalin, paraffin embedding, and sectioning at 4-5 micrometers for microscopic evaluation. Its primary purpose is to enable definitive diagnosis and guide precision oncology treatment selection. Liquid biopsy is displacing repeat surgical procedures in metastatic monitoring, while histopathology sustains the largest revenue pool due to irreplaceable morphological assessment. Molecular diagnostics captures the fastest expansion as next-generation sequencing panels become standard of care in lung and colorectal cancer.
FDA premarket approval and CLIA high-complexity laboratory certification govern test commercialization in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for companion diagnostic claims. EMA centralized procedures increasingly demand co-development evidence linking biopsy biomarkers to approved therapeutics. Stakeholders must monitor reimbursement coding decisions for multi-cancer early detection tests, as coverage determinations will dictate commercial viability faster than technical validation alone.
Market Dynamics
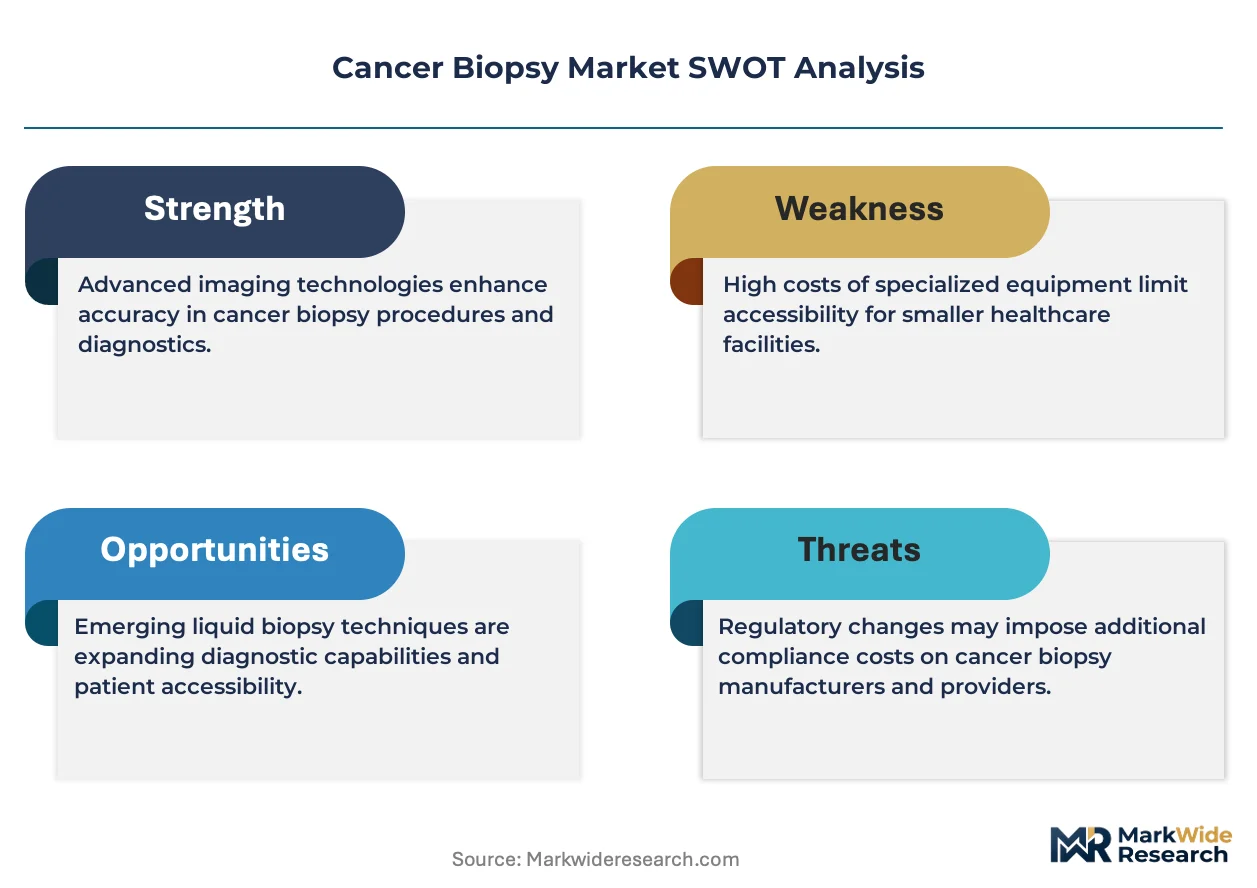
Liquid biopsy workflows are compressing the diagnostic timeline from weeks to days, forcing tissue-based pathology labs to defend their revenue base through platform consolidation and molecular capability expansion.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage determinations for companion diagnostics in the United States accelerate test volume for molecular profiling panels.
- CLIA high-complexity certification:Laboratory-developed test pathways enable rapid commercialization of circulating tumor DNA assays without full FDA premarket approval.
- Next-generation sequencing chemistry:Advances in library preparation and bioinformatics pipelines reduce per-sample costs for comprehensive genomic profiling.
Market Restraints
- FFPE tissue workflow dependency:Formalin fixation and paraffin embedding infrastructure represents sunk capital that slows liquid biopsy substitution in community hospital settings.
- Reimbursement coding lag:CPT code assignment delays for multi-cancer early detection tests compress commercial viability timelines regardless of technical validation status.
- Pathologist workforce constraints:Specialized training requirements for molecular interpretation create bottlenecks at high-volume academic medical centers.
Strategic Opportunities
- Rural and community hospital penetration:Underserved United States markets lack on-site molecular pathology, creating white space for decentralized liquid biopsy service models.
- EMA centralized procedure alignment:Co-development evidence requirements for companion diagnostics create first-mover advantages for biopsy-therapeutic paired submissions.
- Artificial intelligence-enabled image analysis:Digital pathology platforms converge with deep learning algorithms to automate morphological quantification and biomarker scoring.
Industry Challenges
- Cross-platform harmonization:Inter-assay variability in circulating tumor DNA detection limits creates clinical uncertainty when patients switch between reference laboratories.
- Legacy LIS integration:Electronic health record and laboratory information system connectivity requirements delay deployment of cloud-based bioinformatics pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Biopsy Market |
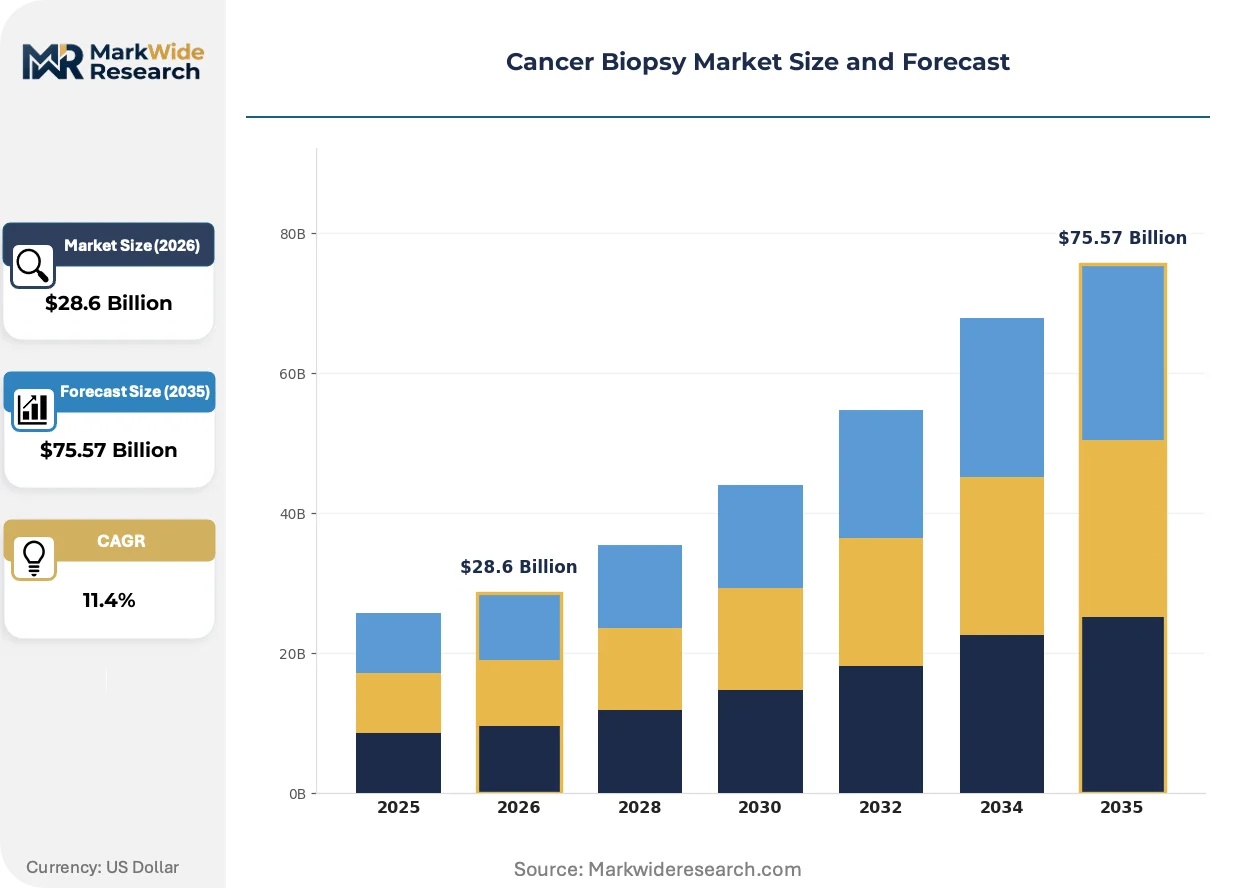
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Needle Biopsy, Endoscopic Biopsy, Surgical Biopsy, Liquid Biopsy Technology: Molecular Diagnostics, Imaging Techniques, Histopathology, Immunohistochemistry End User: Hospitals, Diagnostic Labs, Outpatient Centers, Research Institutes Therapy Area: Breast Cancer, Lung Cancer, Prostate Cancer, Colorectal Cancer |
| Companies Covered | QIAGEN, Illumina, Inc., Hologic, Inc., Danaher Corporation, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific, Inc., Guardant Health, Natera, Inc., Biocept, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Biopsy Market Strategic Shifts & Innovations
Convergence between digital pathology infrastructure and artificial intelligence is compressing diagnostic turnaround times while regulatory frameworks struggle to keep pace with assay complexity.
Multiplex immunohistochemistry panels are electrifying biomarker quantification workflows by enabling simultaneous protein detection across 30-plus targets in single tissue sections. Academic medical centers in the United States are adopting these platforms at accelerated cadences to support immuno-oncology clinical trials. This technology is electrifying the shift from sequential single-marker testing toward comprehensive spatial profiling that informs combination therapy selection.
The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for companion diagnostic claims, extending commercialization timelines for biopsy-therapeutic pairs. Manufacturers must generate prospective validation data linking biomarker status to drug response across intended use populations. Lung and colorectal cancer assay developers face the steepest compliance burdens as notified bodies prioritize high-risk device categories.
Hospital-based oncology departments are consolidating vendor relationships through enterprise-wide platform agreements that bundle instruments, consumables, and bioinformatics subscriptions. Independent reference laboratories face margin compression as health systems internalize high-complexity testing to capture technical component revenue. This concentration is most pronounced in United States metropolitan markets where integrated delivery networks control regional referral patterns.
Cancer Biopsy Market Segmentation
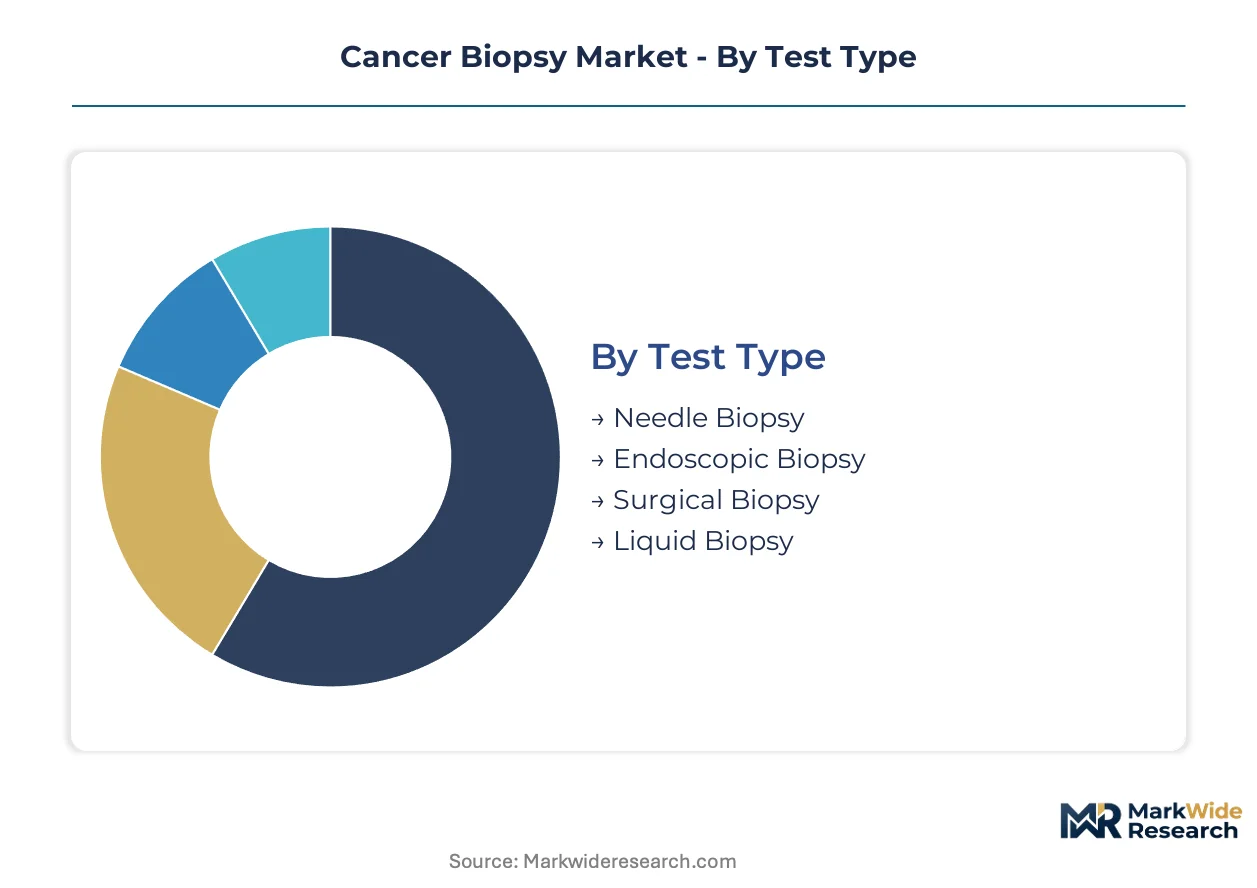
Segmentation in cancer biopsy reveals divergent technology adoption curves across clinical settings. Test type and technology choices determine capital deployment patterns, while end-user concentration shapes go-to-market economics for platform vendors.
Test Type:
Integration depth varies sharply: needle and surgical biopsy demand dedicated procedure suites and pathology integration, while liquid biopsy embeds into existing phlebotomy and laboratory workflows with minimal infrastructure retrofit.
- Liquid Biopsy:Circulating tumor DNA and circulating tumor cell assays extract malignancy signatures from peripheral blood draws without tissue invasion. Demand concentrates in United States metropolitan oncology networks where Medicare reimbursement for companion diagnostics accelerates test volume for metastatic monitoring and therapy response tracking.
- Surgical Biopsy:Open excisional and incisional procedures retrieve intact tissue specimens for definitive histopathological diagnosis. Academic medical centers in the United States sustain placement volume due to irreplaceable morphological assessment requirements for rare cancer subtypes and clinical trial enrollment.
- Needle Biopsy:Core needle and fine-needle aspiration techniques deliver percutaneous tissue sampling under image guidance.
- Endoscopic Biopsy:Forceps and brush sampling through gastrointestinal, bronchial, or urological endoscopy channels.
Volume placements concentrate in surgical biopsy; the faster expansion belongs to liquid biopsy.
Technology:
Cost tier stratification separates capital-intensive instrumentation from consumable-driven reagent workflows, with implications for customer acquisition economics and recurring revenue stability.
- Molecular Diagnostics:Next-generation sequencing panels and PCR-based assays detect actionable mutations, fusions, and microsatellite instability. United States lung and colorectal cancer treatment pathways now mandate comprehensive genomic profiling, concentrating demand in CLIA-certified reference laboratories and hospital-based molecular pathology divisions.
- Histopathology:Formalin-fixed paraffin-embedded tissue processing with hematoxylin-eosin staining remains the diagnostic backbone. Community hospital laboratories across the United States defend this revenue base through platform consolidation and digital pathology adoption despite compressed reimbursement.
- Immunohistochemistry:Antibody-based protein detection on tissue sections enables biomarker quantification for therapy selection.
- Imaging Techniques:CT-guided, ultrasound-guided, and MRI-guided biopsy navigation systems improve targeting precision.
Revenue concentration rests with histopathology; molecular diagnostics is climbing the fastest.
End User:
Customer type determines purchasing authority structure, with integrated delivery networks consolidating procurement decisions away from independent site autonomy.
- Hospitals:Inpatient and outpatient oncology departments command capital budgets for biopsy platforms and internalize high-complexity testing to capture technical component revenue. United States metropolitan markets exhibit pronounced concentration as health systems deploy enterprise-wide agreements bundling instruments, consumables, and bioinformatics subscriptions.
- Diagnostic Labs:Independent reference laboratories and hospital-affiliated outreach operations process specimens on a fee-for-service basis. CLIA high-complexity certification enables rapid commercialization of laboratory-developed tests without full FDA premarket approval, sustaining competitive positioning against vertically integrated hospital systems.
- Outpatient Centers:Ambulatory surgery and imaging centers perform image-guided needle biopsies with rapid specimen transport to reference pathology.
- Research Institutes:Academic and contract research organizations utilize biopsy specimens for biomarker discovery and clinical trial correlative science.
Specimen volume concentrates in hospitals; diagnostic labs are gaining share fastest.
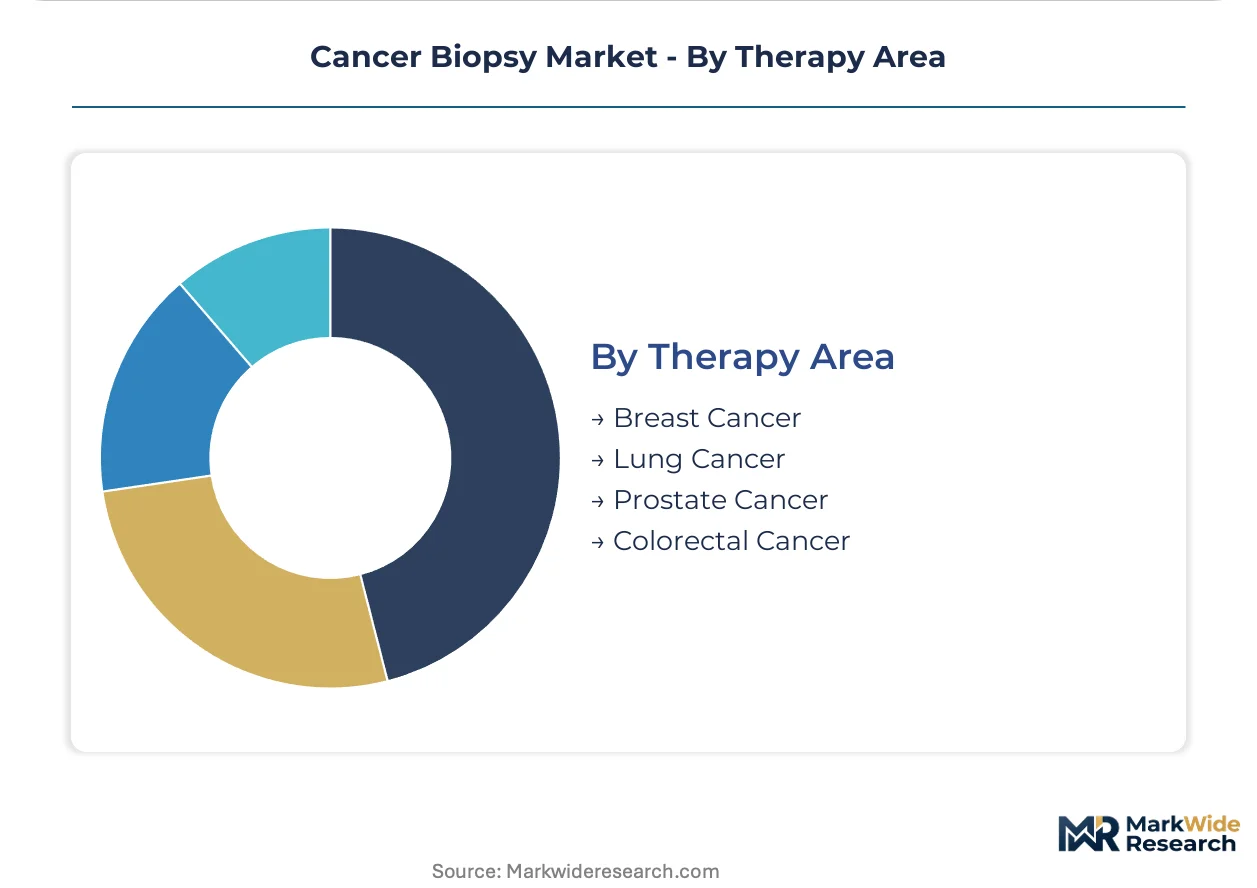
Therapy Area:
Maturity gradients separate well-established screening and diagnostic paradigms from emerging precision oncology applications with evolving reimbursement pathways.
- Lung Cancer:Non-small cell lung carcinoma mandates comprehensive biomarker profiling including EGFR, ALK, ROS1, BRAF, MET, RET, and KRAS alterations. United States treatment guidelines require molecular testing results within specific turnaround windows, compressing diagnostic timelines and favoring integrated molecular pathology workflows.
- Breast Cancer:Estrogen receptor, progesterone receptor, and HER2 status determination guides endocrine and targeted therapy selection. Community pathology laboratories across the United States sustain high test volumes through standardized immunohistochemistry protocols with established CPT reimbursement codes.
- Colorectal Cancer:MSI/MMR deficiency testing and RAS mutation profiling inform immunotherapy and anti-EGFR therapy eligibility.
- Prostate Cancer:Tissue-based and liquid biopsy genomic classifiers stratify active surveillance versus treatment intensification decisions.
Test volume concentrates in breast cancer; the steepest expansion trajectory belongs to lung cancer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotech special economic zones in Massachusetts and California concentrate precision oncology infrastructure, attracting venture capital and FDA-regulated laboratory operations that anchor North American market expansion.
United States
Medicare reimbursement policies for companion diagnostics accelerate liquid biopsy test volume in metropolitan oncology networks. FDA premarket approval pathways and CLIA high-complexity laboratory certification govern commercialization timelines for circulating tumor DNA assays. The Greater Boston corridor hosts Guardant Health and Natera laboratory operations serving integrated delivery networks.
Germany
Hospital-based pathology departments defend revenue through platform consolidation and molecular capability expansion. The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for companion diagnostic claims, extending commercialization timelines. The Rhine-Ruhr metropolitan region concentrates histopathology infrastructure serving community hospital laboratory networks.
China
Domestic NMPA approval pathways enable rapid commercialization of laboratory-developed tests for lung and colorectal cancer profiling. National reimbursement catalog expansion for molecular diagnostics drives test penetration in tier-one city hospital systems. The Yangtze River Delta biotech corridor anchors sequencing platform manufacturing and clinical laboratory scale-up.
Japan
PMDA centralized review procedures demand co-development evidence linking biopsy biomarkers to approved therapeutics. METI industrial policy supports domestic production of next-generation sequencing instrumentation and consumables. The Kanto region around Tokyo concentrates academic medical center molecular pathology divisions and reference laboratory networks.
United Kingdom
NHS England genomic medicine service mandates standardize comprehensive cancer profiling across regional laboratory hubs. MHRA post-Brexit regulatory frameworks align with EU MDR requirements while enabling accelerated access pathways for innovative diagnostics. The Cambridge-London corridor anchors Illumina European operations and contract research organization clinical trial specimen processing.
Cancer Biopsy Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated instrument-consumable-service providers commanding premium positioning against standalone assay developers. The vendor base organizes around three strategic archetypes: sequencing platform incumbents with chemistry lock-in, liquid biopsy pure-plays with CLIA laboratory assets, and diversified life science conglomerates with channel breadth. Consolidation pressures favor enterprise-wide procurement agreements that bundle capital equipment with recurring consumable commitments. Geographic expansion into underserved United States community hospital markets and EMA centralized procedure alignment for companion diagnostic submissions represent dominant competitive moves.
Among sequencing-centric platform providers, Illumina, Inc. and Thermo Fisher Scientific, Inc. occupy positions defined by installed base scale and chemistry roadmap control. Guardant Health exemplifies the liquid biopsy pure-play archetype, anchoring circulating tumor DNA commercialization through CLIA-certified laboratory infrastructure rather than distributed instrument placement. These three entities collectively represent the competitive tension between platform-centric and laboratory-centric business models reshaping molecular diagnostics procurement patterns.
| Leading Market Players |
|---|
| QIAGEN |
| Illumina, Inc. |
| Hologic, Inc. |
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific, Inc. |
| Guardant Health |
| Natera, Inc. |
| Biocept, Inc. |
| Others |
Cost & Logistics Intelligence
Formaldehyde spot pricing volatility cascades through paraffin-embedding consumable tiers, compressing margins for community hospital histopathology workflows while academic medical centers absorb cost spikes through enterprise reagent contracts that lock in multi-year supply commitments.
Pricing Analysis
Short lead-time premiums command pricing separation in liquid biopsy consumables, with same-day shipping reagent kits extracting margin premiums from urgent oncology cases while standard-batch procurement secures volume discounts for routine screening programs. Three-tier pricing structure across premium, standard, and economy levels stratifies by CLIA certification tier and bioinformatics bundling depth. Cost compression in standard-tier molecular panels intensifies because reference laboratories compete for Medicare-reimbursed lung cancer profiling volume. Community hospital laboratories exhibit highest price sensitivity due to fixed technical component capture limits, while integrated delivery networks leverage procurement consolidation for least sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese-manufactured sequencing flow cells and Malaysian rubber-based specimen collection devices, exposing US-based reference laboratories to tariff escalation and logistics disruption. Manufacturing concentration clusters in China, Germany, and the United States for next-generation sequencing instrumentation, with Singapore anchoring regional distribution hubs for Asia-Pacific. Raw material dependencies span semiconductor-grade silicon for microfluidic chips, optical-grade polymers for imaging consumables, and recombinant enzyme biochemistry for library preparation. Tariff exposure on Chinese-sourced reagents constitutes the dominant structural risk. Distribution runs through CLIA-certified laboratory networks and direct-to-hospital instrument leasing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cancer biopsy procurement is accelerating through a technology-transition phase as liquid biopsy workflows displace repeat surgical procedures in metastatic monitoring applications.
For Market Incumbents: Deploy enterprise-wide platform bundling as the primary lever to lock hospital systems into multi-year consumable commitments before CLIA laboratory pure-plays penetrate community oncology networks. Incorporate artificial intelligence-enabled image analysis into digital pathology subscriptions to defend technical component revenue against decentralized liquid biopsy service models. Backward integration into sequencing chemistry manufacturing reduces reagent cost exposure.
For New Entrants and Emerging Players: Rural and community hospital procurement committees represent the most penetrable buyer archetype, as these facilities lack on-site molecular pathology infrastructure and rely on reference laboratory send-outs with extended turnaround times. White-space targets concentrate in underserved United States metropolitan exurbs and tier-two Chinese city hospital systems. A decentralized liquid biopsy service model with rapid specimen logistics and cloud-based bioinformatics reporting captures share from tissue-based incumbents.
For Investors and Strategic Acquirers: The window for entry favors CLIA-certified laboratory assets with companion diagnostic co-development pipelines and established Medicare reimbursement coding. Long-term viability centers on biopsy-therapeutic paired submission capabilities that align with EMA centralized procedure requirements. The signal to watch is FDA premarket authorization velocity for multi-cancer early detection tests, as coverage determination timelines will dictate commercial viability faster than technical validation milestones.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Acquisition | Captures technical component revenue and accelerates LDT commercialization without full FDA premarket timelines. |
| Companion Diagnostic Co-Development | Aligns biopsy biomarker validation with therapeutic approval pathways under EMA centralized procedures. |
| Digital Pathology Platform Integration | Automates morphological quantification through FDA-cleared artificial intelligence algorithms for biomarker scoring. |
| Reimbursement Strategy Investment | Secures Medicare CPT code assignments for multi-cancer early detection tests before competitor technical validation. |
| Enterprise-Wide Procurement Agreement | Bundles instruments, consumables, and bioinformatics subscriptions to lock integrated delivery network volume. |
Research Approach
Independent corroboration across hospital procurement databases, CMS Medicare reimbursement filings, and FDA premarket authorization records underwrites the qualitative findings in this study. Primary interviews with molecular pathology division directors, CLIA laboratory operations managers, oncology department purchasing committees, and companion diagnostic regulatory affairs specialists combined with secondary validation from ClinicalTrials.gov correlative science protocols, SEC 10-K instrument revenue disclosures, and GPO contract award announcements. Bottom-up test volume modeling and top-down market sizing triangulate across analysis windows.
Rate-of-change decomposition separates volume growth from price-mix effects across test type, technology platform, end-user concentration, and therapy area regulatory maturity. Segmentation dimensions span liquid versus tissue-based sampling, next-generation sequencing versus histopathology workflow, hospital versus reference laboratory site of service, and lung versus breast versus colorectal cancer indication. CAGRs derive from logistic diffusion curves fitted to Medicare reimbursement expansion trajectories and companion diagnostic approval velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA premarket authorization delays, CMS coverage determination reversals, and pathologist workforce constraint bottlenecks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Clinical Oncology NGS Market
Oncology Diagnostics
Cancer Diagnostics Market