
 North America Bladder Cancer Therapeutics and Diagnostics Market | 2026-2036
North America Bladder Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bladder Cancer Therapeutics and Diagnostics Market Analytics
Community urology practices is collapsing as the dominant buyer archetype as large integrated hospital networks and specialty oncology centers capture a growing share of high-complexity bladder cancer cases. Bristol-Myers Squibb Company leverages its checkpoint inhibitor portfolio to anchor positions in first-line metastatic settings. AstraZeneca PLC competes through antibody-drug conjugate development programs targeting FGFR-altered tumors. Johnson & Johnson sustains leadership in intravesical delivery systems through its established urology device franchise.
Bladder cancer therapeutics and diagnostics encompasses systemic and localized treatments for urothelial carcinoma alongside molecular and imaging tools for staging, recurrence monitoring, and therapy selection, with primary commercial purpose centered on improving progression-free survival and reducing cystectomy rates through neoadjuvant and adjuvant precision intervention. Immunotherapy now leads the product type landscape as PD-1/PD-L1 inhibitors displace platinum-based chemotherapy in eligible patient populations, while biomarker testing within the technology dimension represents the fastest-expanding segment as FGFR3, TMB, and NTRK companion diagnostics become standard-of-care prerequisites. Intravesical delivery mode retains mature, stable demand for non-muscle-invasive disease management where bacillus Calmette-Guérin remains the reference standard.
FDA breakthrough therapy and device designations, alongside CMS national coverage determinations for next-generation sequencing, shape product development priorities and market access timelines for manufacturers seeking reimbursement at launch. Health Canada and provincial formularies in Ontario and British Columbia introduce parallel regulatory considerations for cross-border commercialization strategies. Stakeholders must monitor evolving FDA guidance on minimal residual disease testing and real-world evidence requirements for label expansion decisions.
Market Dynamics
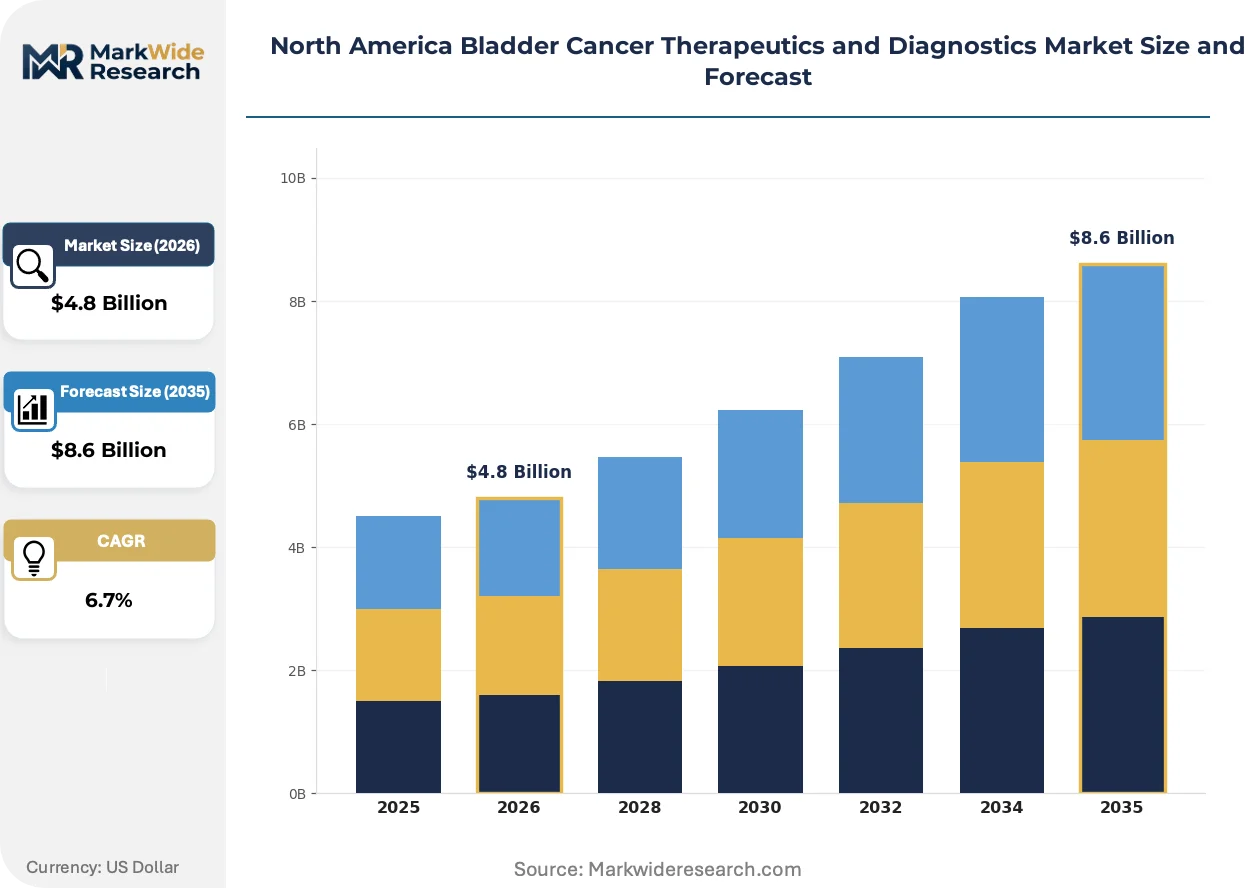
FDA breakthrough device designations for minimal residual disease testing are compressing development timelines and forcing manufacturers to front-load biomarker validation before pivotal trials, while CMS national coverage determinations for next-generation sequencing simultaneously reshape reimbursement pathways across hospital networks.
Growth Catalysts
- CMS National Coverage Determinations:Medicare reimbursement for companion diagnostics removes prior authorization friction, accelerating biomarker-guided therapy adoption across community oncology practices.
- Integrated Hospital Networks:Large health systems in Texas and Florida are consolidating urology services, creating centralized referral pathways for high-complexity bladder cancer cases.
- PD-1/PD-L1 Inhibitors:Checkpoint inhibitors displace platinum-based chemotherapy in first-line metastatic settings, expanding addressable patient populations for precision therapeutics.
Market Restraints
- Biomarker Test Cost Structure:FGFR3 and TMB testing requires specialized molecular pathology infrastructure that smaller community hospitals cannot sustain without network affiliation.
- Supply Concentration Risk:Bacillus Calmette-Guérin production concentrates among two global manufacturers, creating vulnerability to shortage events affecting non-muscle-invasive disease management.
- Technical Limitation:Current urine-based liquid biopsy assays demonstrate insufficient sensitivity for early recurrence detection in low-grade tumors, limiting adoption outside surveillance protocols.
Strategic Opportunities
- Ontario and British Columbia:Provincial formularies are accelerating immunotherapy protocol access, creating parallel commercialization pathways for manufacturers with Health Canada approvals.
- Antibody-Drug Conjugate Convergence:ADC development programs targeting FGFR-altered tumors represent white space where diagnostic-therapeutic pairing can command premium positioning.
- Real-World Evidence Pathways:FDA guidance on minimal residual disease testing creates regulatory tailwind for post-market study designs supporting label expansion.
Industry Challenges
- Molecular Pathology Talent Gap:Interpretation of complex biomarker panels requires specialized training that outpaces current fellowship program output.
- Legacy Electronic Health Record Integration:Precision oncology workflows demand API connectivity that many hospital systems lack, forcing manual data entry for therapy selection algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bladder Cancer Therapeutics and Diagnostics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Biologic Agents End User: Hospitals, Clinics, Research Laboratories, Homecare Settings Delivery Mode: Intravesical, Systemic, Oral, Injectable Technology: Next-Generation Sequencing, Biomarker Testing, Imaging Techniques, Diagnostic Kits |
| Companies Covered | Bristol-Myers Squibb Company, AstraZeneca PLC, Johnson & Johnson, F. Hoffmann-La Roche Ltd, GlaxoSmithKline PLC, Pfizer Inc., Eli Lilly and Company, Novartis AG, Astellas Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bladder Cancer Therapeutics and Diagnostics Market Evolving Landscape
Technology convergence between diagnostic platforms and therapeutic decision engines is redefining competitive moats, while regulatory acceleration mechanisms compress traditional development timelines and buyer consolidation reshapes channel economics.
Minimal residual disease testing is fragmenting the surveillance market for bladder cancer recurrence monitoring. Large integrated hospital networks are adopting multi-cancer early detection platforms at twice the pace of independent urology practices. This technology is fragmenting case volume away from community settings toward centralized molecular pathology hubs with captive clinical trial access.
FDA breakthrough device designation pathways for companion diagnostics are compressing premarket review timelines from 180 to 90 days for qualifying submissions. Manufacturers are front-loading biomarker validation studies to secure simultaneous therapeutic and diagnostic approvals. Muscular-invasive disease staging protocols in California and New York hospital systems are most affected, with pathology departments hiring dedicated regulatory affairs staff to manage parallel FDA and CMS submissions.
Hospital procurement committees are unbundling diagnostic testing from therapeutic purchasing decisions, forcing separate vendor qualification processes. Integrated delivery networks are replacing individual physician preference with centralized formulary committees that mandate biomarker testing before immunotherapy authorization. This pattern concentrates most visibly in the United States, where Medicare Advantage penetration above 50% in Florida and Arizona accelerates utilization management requirements.
North America Bladder Cancer Therapeutics and Diagnostics Market Segmentation
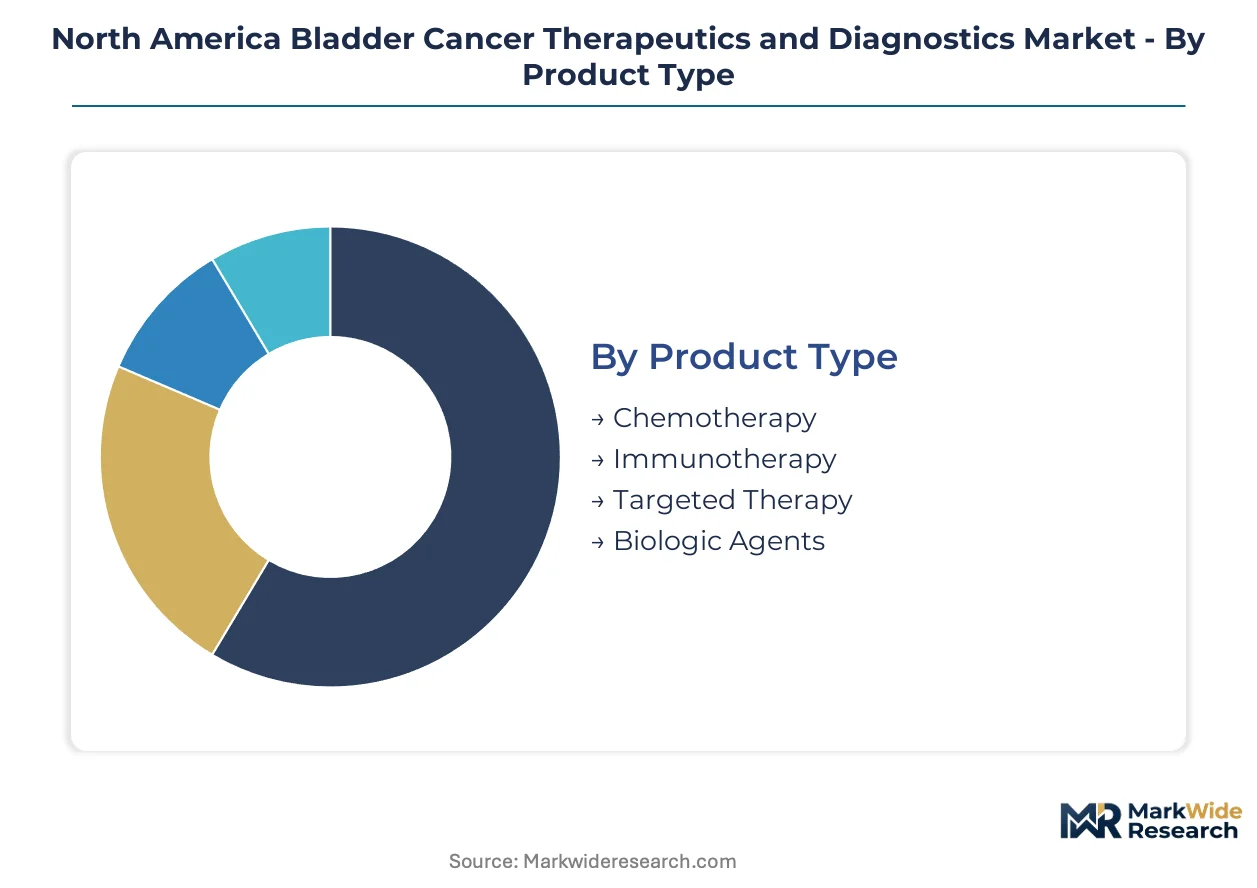
Precision medicine requirements reshape how bladder cancer products cluster commercially. FDA breakthrough designations and CMS coverage decisions create divergent reimbursement trajectories across each segment category, forcing manufacturers to align development priorities with specific regulatory pathways.
Product Type:
FDA approval velocity varies substantially across therapeutic modalities, with breakthrough therapy designation rates highest for immunotherapy and lowest for conventional chemotherapy.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors dominate first-line metastatic protocols through accelerated approval pathways. Hospital networks in Texas and Florida concentrate demand as integrated delivery systems mandate biomarker screening before authorization.
- Targeted Therapy:FGFR inhibitors and antibody-drug conjugates address genomic subpopulations with companion diagnostic requirements. Ontario and British Columbia provincial formularies are expanding access faster than US Medicare Advantage plans in some indications.
- Chemotherapy:Platinum-based regimens retain neoadjuvant positioning despite displacement in metastatic settings.
- Biologic Agents:Bacillus Calmette-Guérin maintains reference standard status for non-muscle-invasive disease with supply concentrated among two global manufacturers.
Established volume favors chemotherapy; emerging adoption favors immunotherapy.
End User:
Buyer consolidation concentrates procurement authority within integrated hospital networks, fragmenting purchasing patterns across facility types.
- Hospitals:Large health systems in California and New York operate centralized molecular pathology hubs with captive clinical trial access. These institutions capture high-complexity cases from collapsing community urology practices through formal referral agreements.
- Clinics:Community oncology settings face prior authorization friction for biomarker-guided therapies without network affiliation. Medicare reimbursement for companion diagnostics removes some barriers, but specialized infrastructure requirements limit independent operation.
- Research Laboratories:Academic medical centers conduct minimal residual disease validation studies supporting FDA label expansion submissions.
- Homecare Settings:Oral targeted therapy administration shifts some monitoring burden outside institutional settings.
Procurement authority concentrates in hospitals; patient access expansion targets clinics.
Delivery Mode:
Route selection determines reimbursement coding complexity and site-of-care economics across Medicare and provincial payment systems.
- Systemic:Intravenous immunotherapy and chemotherapy administration generates hospital outpatient department revenue with established coding. Medicare national coverage determinations for next-generation sequencing reshape which patients qualify for biomarker-guided systemic selection.
- Intravesical:Bladder instillation of Bacillus Calmette-Guérin and chemotherapeutic agents requires specialized urology infrastructure. Supply shortage vulnerability affects non-muscle-invasive disease management when manufacturing disruptions occur.
- Oral:FGFR inhibitor tablets enable community dispensing with pharmacy benefit management complexity.
- Injectable:Subcutaneous and intramuscular formulations occupy limited bladder cancer indications.
Mature infrastructure supports intravesical delivery; pipeline innovation emphasizes systemic routes.
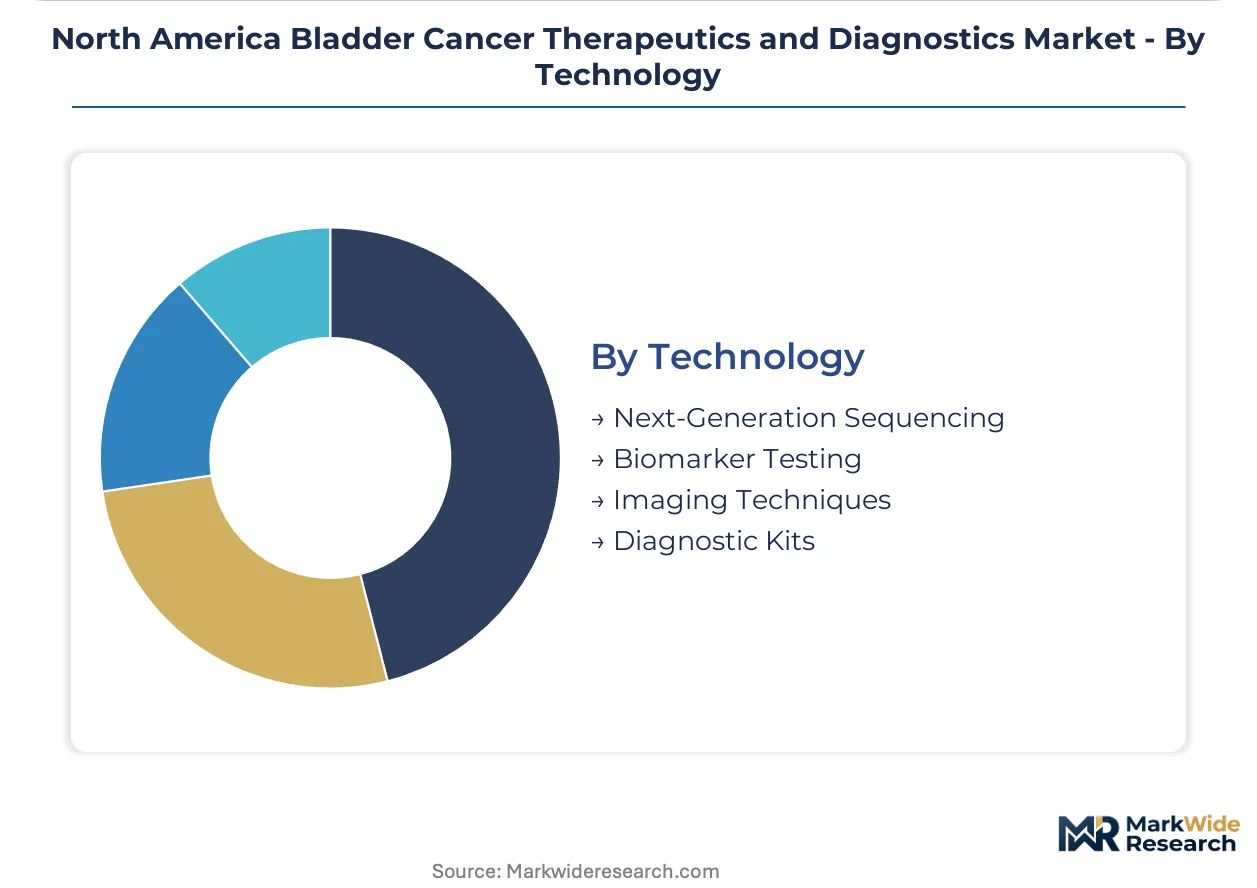
Technology:
Diagnostic platform selection determines therapy eligibility and influences pharmaceutical companion diagnostic partnerships.
- Biomarker Testing:FGFR3, TMB, and NTRK companion diagnostics became standard-of-care prerequisites for targeted therapy authorization. FDA breakthrough device designations compress premarket review timelines from 180 to 90 days for qualifying submissions.
- Next-Generation Sequencing:CMS national coverage determinations enable Medicare reimbursement across hospital networks, accelerating adoption in Florida and Arizona where Medicare Advantage penetration exceeds 50%.
- Imaging Techniques:CT urography and MRI staging protocols guide muscular-invasive disease treatment planning in California and New York hospital systems.
- Diagnostic Kits:Urine-based liquid biopsy assays demonstrate insufficient sensitivity for early recurrence detection in low-grade tumors, limiting adoption outside surveillance protocols.
Installed base anchors imaging; regulatory tailwinds accelerate biomarker testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian biotech exports flow southward into United States hospital procurement networks, while Mexican manufacturing facilities supply device components for intravesical delivery systems across the integrated North American trade corridor.
United States
Texas and Florida health systems consolidate urology services into centralized referral hubs. FDA breakthrough device designations compress premarket review timelines from 180 to 90 days for qualifying companion diagnostic submissions. California and New York hospital systems operate molecular pathology hubs with captive clinical trial access.
Canada
Ontario and British Columbia provincial formularies accelerate immunotherapy protocol access faster than some US Medicare Advantage plans. Health Canada approvals create parallel commercialization pathways for manufacturers seeking cross-border market entry. Toronto and Vancouver academic medical centers conduct minimal residual disease validation studies supporting FDA label expansion submissions.
Mexico
Northern border states concentrate maquiladora manufacturing for urology device components serving US hospital supply chains. The country's national pharmaceutical regulator oversees import licensing for biologic agents including bacillus Calmette-Guérin. Mexico City metro area hospitals participate in multinational clinical trials for antibody-drug conjugate development programs.
North America Bladder Cancer Therapeutics and Diagnostics Market Competitive Landscape
Listed leaders compete with private specialists across checkpoint inhibitor and antibody-drug conjugate development portfolios. The market structure tiers around three archetypes: large-cap pharmaceutical conglomerates with diversified oncology portfolios, mid-cap biotech specialists focused on precision therapeutics, and established urology device manufacturers with intravesical delivery expertise. Dominant competitive moves include strategic partnerships between diagnostic platform developers and therapeutic manufacturers, plus portfolio diversification into companion diagnostic co-development agreements.
Among the large-cap pharmaceutical tier, Bristol-Myers Squibb Company and AstraZeneca PLC occupy positions anchored by immunotherapy and targeted therapy development programs respectively. Johnson & Johnson sits within the device-manufacturing archetype, representing established urology franchise capabilities. These three entities exemplify the competitive positioning that shapes procurement dynamics across hospital networks and integrated delivery systems.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline PLC |
| Pfizer Inc. |
| Eli Lilly and Company |
| Novartis AG |
| Astellas Pharma Inc. |
| Others |
Value Network & Pricing Analysis
Take-or-pay contracts for Bacillus Calmette-Guérin supply lock in multi-year price visibility for hospital networks while exposing buyers to shortage risk if manufacturing disruptions strike the two global producers. These arrangements concentrate procurement leverage among integrated delivery systems with sufficient volume to secure preferred allocation tiers.
Pricing Analysis
Prior-generation platinum-based chemotherapy regimens now trade at steep discounts to PD-1/PD-L1 checkpoint inhibitors commanding premium positioning in first-line metastatic protocols. Three-tier pricing structure across premium immunotherapy, standard targeted therapy, and economy chemotherapy levels reflects FDA breakthrough designation status and companion diagnostic bundling requirements. Cost compression in the chemotherapy tier intensifies because generic erosion and displacement from immunotherapy protocols squeeze margins. Community oncology clinics exhibit highest price sensitivity due to prior authorization friction and infrastructure constraints, while large integrated hospital networks absorb premium pricing through centralized formulary control.
Supply Chain Analysis
Strategic stockpiling of Bacillus Calmette-Guérin dominates inventory strategy given the two-manufacturer concentration and historical shortage events disrupting non-muscle-invasive disease management. Active pharmaceutical ingredient production for FGFR inhibitors and antibody-drug conjugates concentrates in Switzerland, Ireland, and the United States, with fill-finish operations distributed across Puerto Rico and Singapore. Supply chain risk from single-source vulnerability for critical biologics feeds into hospital procurement committee decisions favoring dual-source qualification. Distribution runs through specialty pharmaceutical wholesalers with cold-chain capabilities serving hospital outpatient departments and integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized molecular pathology interpretation capacity trails demand growth across North America, creating bottlenecks that determine which hospital systems can operationalize precision oncology workflows at scale.
For Market Incumbents: Shield market position by deepening companion diagnostic co-development partnerships with emerging antibody-drug conjugate developers before regulatory pathways solidify. Acquire or build captive molecular pathology capacity in Texas and Florida to capture consolidating urology referral volume from collapsing community practices. Vertical integration into biomarker testing infrastructure represents the critical defensive lever against integrated delivery network procurement centralization. For New Entrants and Emerging Players: Differentiate on real-world evidence generation capabilities supporting FDA minimal residual disease testing label expansions, where incumbent diagnostic platforms remain underdeveloped. Target Ontario and British Columbia provincial formulary access as the most penetrable geography given faster immunotherapy protocol adoption than US Medicare Advantage plans. Pursue hospital system partnership models that embed therapy selection algorithms directly into electronic health record workflows. For Investors and Strategic Acquirers: Mid-cap precision therapeutics specialists with Health Canada approvals and parallel FDA submission pathways offer asymmetric upside from cross-border commercialization optionality. Long-term viability hinges on capturing molecular pathology talent and regulatory affairs expertise faster than competitors. Watch Health Canada approval velocity relative to FDA timelines as the signal indicating which development-stage assets merit premium valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA breakthrough device designation compresses premarket review timelines from 180 to 90 days for qualifying submissions. |
| Molecular Pathology Hub Expansion | California and New York hospital systems hire dedicated regulatory affairs staff to manage parallel FDA and CMS submissions. |
| Provincial Formulary Acceleration | Ontario and British Columbia expand immunotherapy protocol access faster than some US Medicare Advantage plans. |
| Real-World Evidence Pathway Investment | FDA guidance on minimal residual disease testing creates regulatory tailwind for post-market study designs. |
| Integrated Delivery Network Partnership | Texas and Florida health systems consolidate urology services into centralized referral hubs with captive clinical trial access. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings against secondary validation from FDA filings, Health Canada submissions, ClinicalTrials.gov records, and CMS national coverage determination databases. Bottom-up patient flow modeling and top-down revenue triangulation across therapeutic modality segments ensure methodological robustness.
Sensitivity analysis around biomarker testing penetration rates and immunotherapy displacement timelines informs the analytical framework across the projection horizon. Segmentation dimensions modeled include treatment line, administration route, patient population risk stratification, and regional regulatory cluster. CAGRs derive from compound growth trajectory analysis applied to therapy adoption curves and diagnostic utilization patterns, with inputs from hospital procurement database trends and GPO contract velocity.
Material uncertainties — FDA guidance revisions on minimal residual disease testing, Health Canada approval timeline shifts, and Bacillus Calmette-Guérin supply disruption events — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding biomarker-guided therapy authorization rates and integrated delivery network consolidation velocity. Revision becomes warranted when Medicare Advantage utilization management requirements cross thresholds that fragment patient access across network-affiliated and independent practice settings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market