
 Asia-Pacific Lung Cancer Screening Software Market | 2026-2036
Asia-Pacific Lung Cancer Screening Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lung Cancer Screening Software Market Outlook
Direct distribution to hospital procurement departments is fragmenting as cloud-based deployment models open alternative channels. Siemens Healthineers leverages its installed base of imaging hardware to bundle screening software across Japanese and Australian health networks. Qure.ai competes on price-performance for teleradiology partnerships in India and Southeast Asia. Infervision anchors its position through deep integration with Chinese hospital information systems.
Asia-Pacific lung cancer screening software comprises algorithmic platforms that analyze low-dose computed tomography (LDCT) scans to detect pulmonary nodules and malignancy risk, typically processing DICOM images through convolutional neural networks trained on annotated thoracic datasets. The primary purpose is to reduce radiologist reading burden while standardizing nodule classification via Lung-RADS or comparable scoring frameworks. Diagnostic software leads current revenue contribution due to mandatory integration with CT workflows, while cloud-based deployment represents the fastest-growing segment as hospitals in Australia and South Korea migrate Picture Archiving and Communication Systems off legacy servers. Risk assessment tools occupy a narrower but higher-margin niche serving specialized oncology centers that require longitudinal patient tracking.
Japan's PMDA, Australia's TGA, and China's NMPA each maintain distinct software-as-medical-device classification rules that determine clinical evidence requirements and market access timelines. PMDA's Sakigake designation accelerates review for AI diagnostics, while NMPA's recent technical guidelines for deep learning medical software have clarified registration pathways for domestic and foreign developers. China's dual carbon goals also influence hospital IT procurement, favoring energy-efficient cloud architectures over on-premise server farms. Stakeholders must monitor evolving reimbursement codes for AI-assisted reads across national health insurance schemes to anticipate which deployment models achieve sustainable payment coverage.
Market Dynamics
Cloud deployment architectures are collapsing traditional hospital IT procurement cycles across Asia-Pacific, compressing vendor selection timelines from eighteen months to under six while forcing legacy on-premise suppliers to restructure pricing and service models.
Growth Catalysts
- Japan's Sakigake designation:PMDA's accelerated review pathway compresses AI diagnostic approval timelines, enabling earlier commercialization for developers targeting Japanese hospital networks.
- LDCT screening protocols:National lung cancer early detection programs in China and South Korea mandate standardized imaging workflows, embedding AI-assisted reads into reimbursement-eligible care pathways.
- Tier-one city hospital clusters:Concentrated procurement budgets in Shanghai, Beijing, and Tokyo create anchor demand that validates software performance for broader regional rollout.
Market Restraints
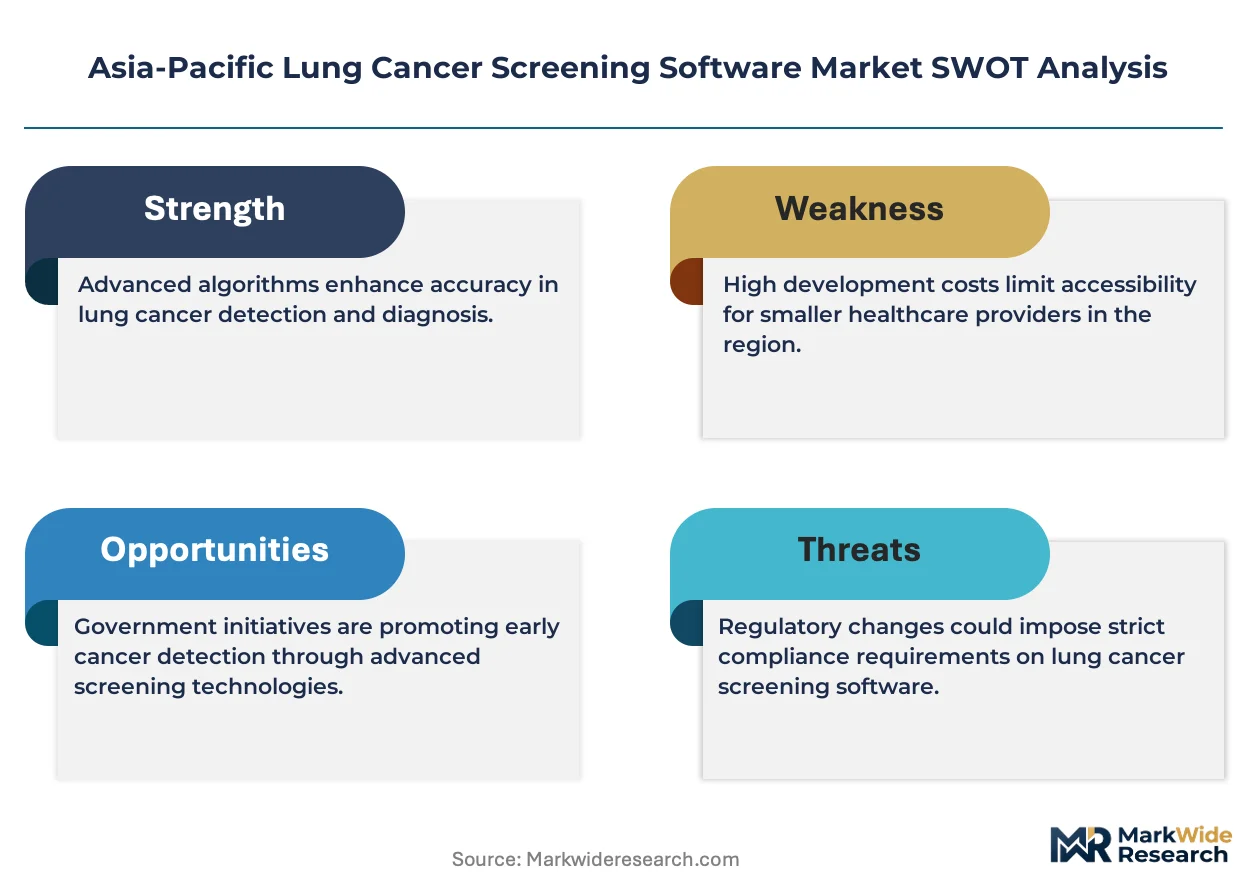
- Annotated dataset scarcity:Curated thoracic CT training libraries remain concentrated among Japanese and Chinese academic medical centers, creating input bottlenecks for algorithm developers outside these institutions.
- Dual carbon compliance costs:China's energy-efficiency mandates for hospital IT infrastructure impose retrofit expenses on institutions maintaining legacy on-premise server farms.
- Interoperability fragmentation:Proprietary DICOM implementation variations across Chinese hospital information systems force redundant integration engineering.
Strategic Opportunities
- Southeast Asia teleradiology networks:Underdeveloped specialist radiologist density in Indonesia, Vietnam, and the Philippines creates demand for AI-assisted remote screening platforms.
- Australia's cloud migration incentives:Federal digital health infrastructure programs subsidize off-premise Picture Archiving and Communication System transitions.
- Federated learning architectures:Privacy-preserving model training across hospital networks without centralizing patient data addresses cross-border data sovereignty constraints.
Industry Challenges
- Clinical validation timelines:Multi-site prospective studies required by NMPA and PMDA for Class III software-as-medical-device registration extend product development cycles.
- Radiologist workflow integration:Custom interface engineering for embedded CT console deployment demands specialized health IT engineering capacity that vendors struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lung Cancer Screening Software Market |
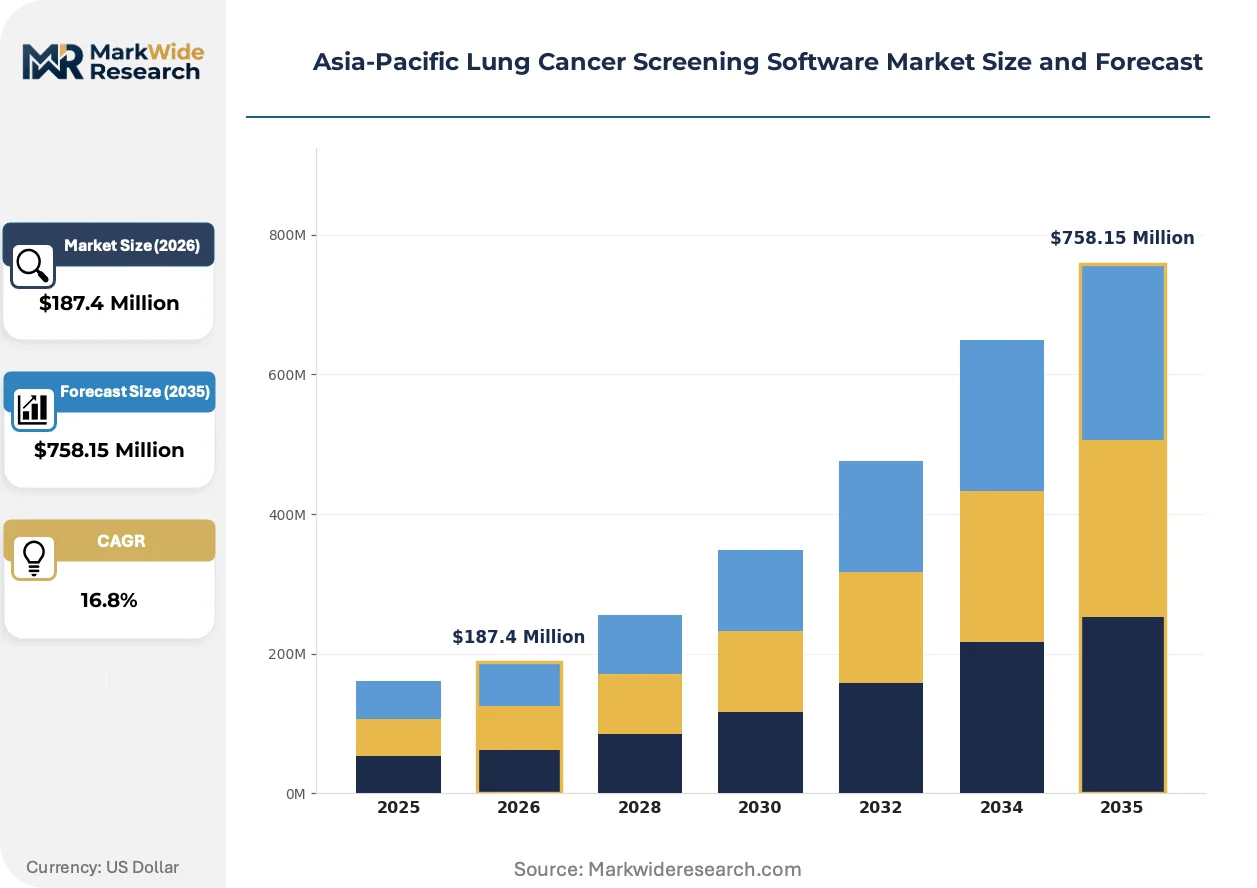
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Software, Risk Assessment Tools, Imaging Solutions, Workflow Management End User: Hospitals, Diagnostic Centers, Research Institutions, Private Clinics Deployment: On-premise, Cloud-based, Hybrid, Local Network Application: Early Detection, Patient Monitoring, Treatment Decision Support, Data Analysis |
| Companies Covered | Coreline Soft, Infervision, Qure.ai, PenRad Technologies, Volpara Health, Optellum, FUJIFILM Holdings Corporation, Philips Healthcare, Siemens Healthineers, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lung Cancer Screening Software Market Strategic Shifts
Edge computing architectures are reshaping how screening algorithms deploy within hospital networks, enabling real-time inference without persistent cloud connectivity while creating new hardware-software bundling opportunities for imaging equipment manufacturers.
Convolutional neural network architectures optimized for low-dose CT reconstruction are collapsing the performance gap between reduced-radiation screening protocols and standard-dose diagnostic quality. Australian and South Korean hospitals are piloting these algorithms in mobile screening units. The compression of radiation exposure requirements expands eligible patient populations while reducing liability exposure for screening program operators.
NMPA's technical guidelines for deep learning medical software have clarified evidentiary standards for algorithm transparency and performance validation. Domestic Chinese developers now face streamlined registration pathways, while foreign entrants must establish local clinical trial infrastructure. The regulation is accelerating consolidation among smaller developers lacking regulatory affairs capacity.
Hospital procurement departments are unbundling AI software from hardware purchase decisions, creating standalone software evaluation committees with radiologist and IT representation. Japanese university hospitals pioneered this separation, and the practice is spreading to Australian public health networks. Vendor sales cycles now require dual-track engagement with clinical and technical stakeholders simultaneously.
Asia-Pacific Lung Cancer Screening Software Market Segmentation
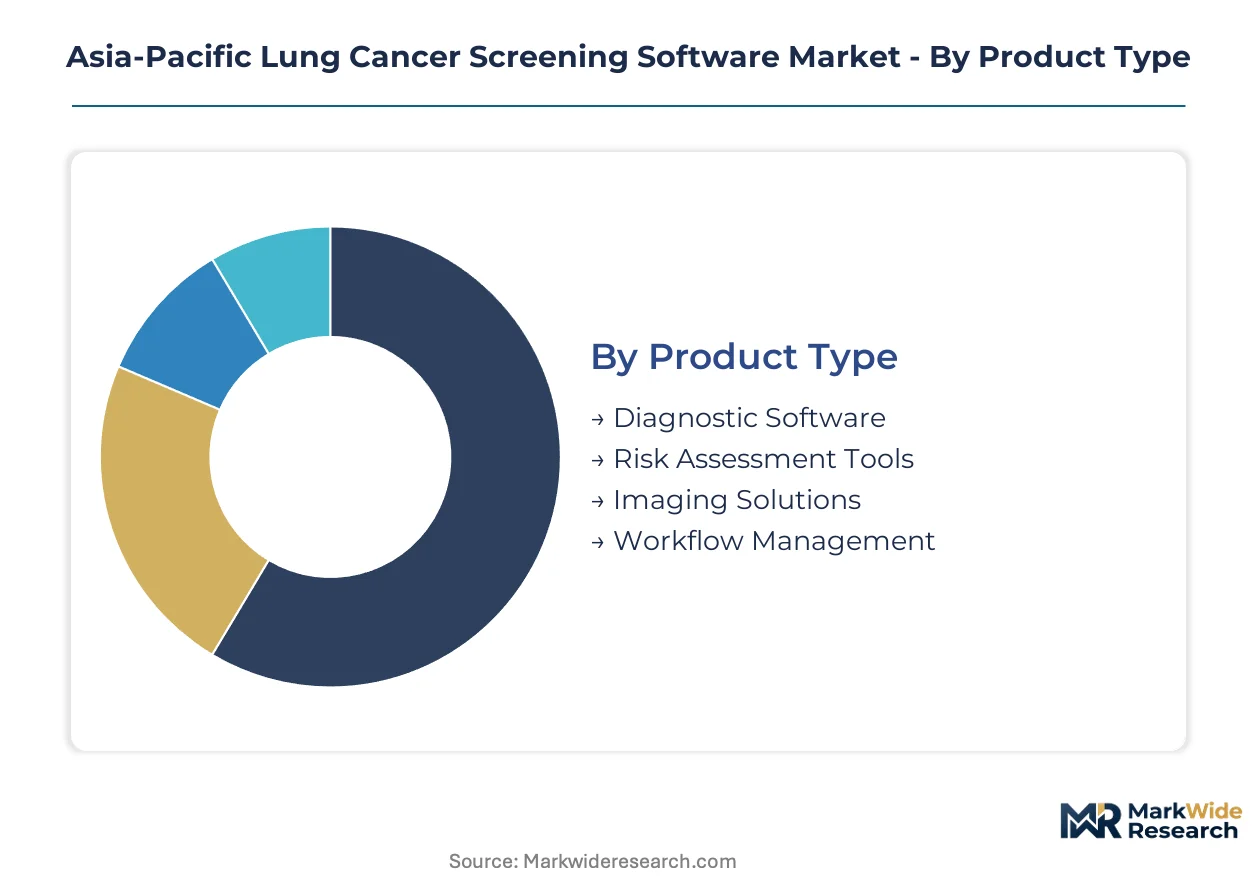
Segmentation in Asia-Pacific lung cancer screening software reveals how procurement priorities diverge across hospital IT maturity levels and regulatory environments. Understanding these divides helps vendors align product architectures with specific buyer capabilities and compliance requirements.
Product Type:
Diagnostic software turns over fastest as hospitals refresh CT-integrated algorithms every 18-24 months, while workflow management platforms persist across decade-long PACS upgrade cycles.
- Diagnostic Software:Algorithmic platforms processing LDCT scans through convolutional neural networks to detect pulmonary nodules and classify malignancy risk via Lung-RADS frameworks. Chinese tier-one hospitals in Shanghai and Beijing drive procurement volume as national screening programs mandate AI-assisted reads into reimbursement pathways.
- Risk Assessment Tools:Longitudinal patient tracking systems serving specialized oncology centers with longitudinal cohort analysis capabilities. Japanese academic medical centers concentrate demand where PMDA's Sakigake designation accelerates validation timelines for predictive algorithms.
- Imaging Solutions:Low-dose CT reconstruction software optimizing radiation exposure parameters.
- Workflow Management:Integration middleware connecting screening outputs to hospital information systems and radiologist worklists.
Diagnostic software anchors the volume base while risk assessment tools gain share at the steepest rate.
End User:
Cost tiers separate institutions by IT infrastructure investment capacity, with public hospital networks prioritizing bundled hardware-software procurement and private buyers favoring standalone software subscriptions.
- Hospitals:Large-scale integrated delivery networks with embedded CT fleets and dedicated radiology departments. Australia's public hospital networks and South Korean regional medical centers concentrate procurement as federal digital health programs subsidize AI-assisted screening infrastructure.
- Diagnostic Centers:Specialized imaging facilities operating high-throughput screening programs without full hospital administrative overhead. India's teleradiology hubs and Southeast Asian standalone imaging chains drive demand for cloud-deployable solutions requiring minimal on-site IT support.
- Research Institutions:Academic medical centers conducting prospective validation studies for regulatory registration.
- Private Clinics:Small-scale practices offering executive health screening packages.
Hospitals dominate absolute spending while diagnostic centers expand most quickly across underpenetrated provincial markets.
Deployment:
Application criticality determines architecture selection, with real-time inference requirements favoring on-premise or edge deployments while retrospective analysis tolerates cloud latency.
- Cloud-based:Scalable infrastructure eliminating capital expenditure for server hardware and enabling rapid algorithm updates without on-site engineering. Australian hospitals lead migration as TGA guidelines clarify software-as-medical-device responsibilities for cloud-hosted diagnostics, with South Korean medical centers following federal cloud-first procurement mandates.
- On-premise:Localized processing architectures maintaining persistent control over patient data and ensuring inference capability during network outages. Chinese hospitals in data-sensitive jurisdictions favor these deployments where NMPA registration requirements emphasize physical data localization.
- Hybrid:Split architectures processing screening inference locally while archiving to cloud PACS.
- Local Network:Hospital intranet-restricted deployments for institutions with limited external connectivity.
On-premise installations retain the largest installed base while cloud-based deployment climbs the fastest as procurement cycles compress below six months.
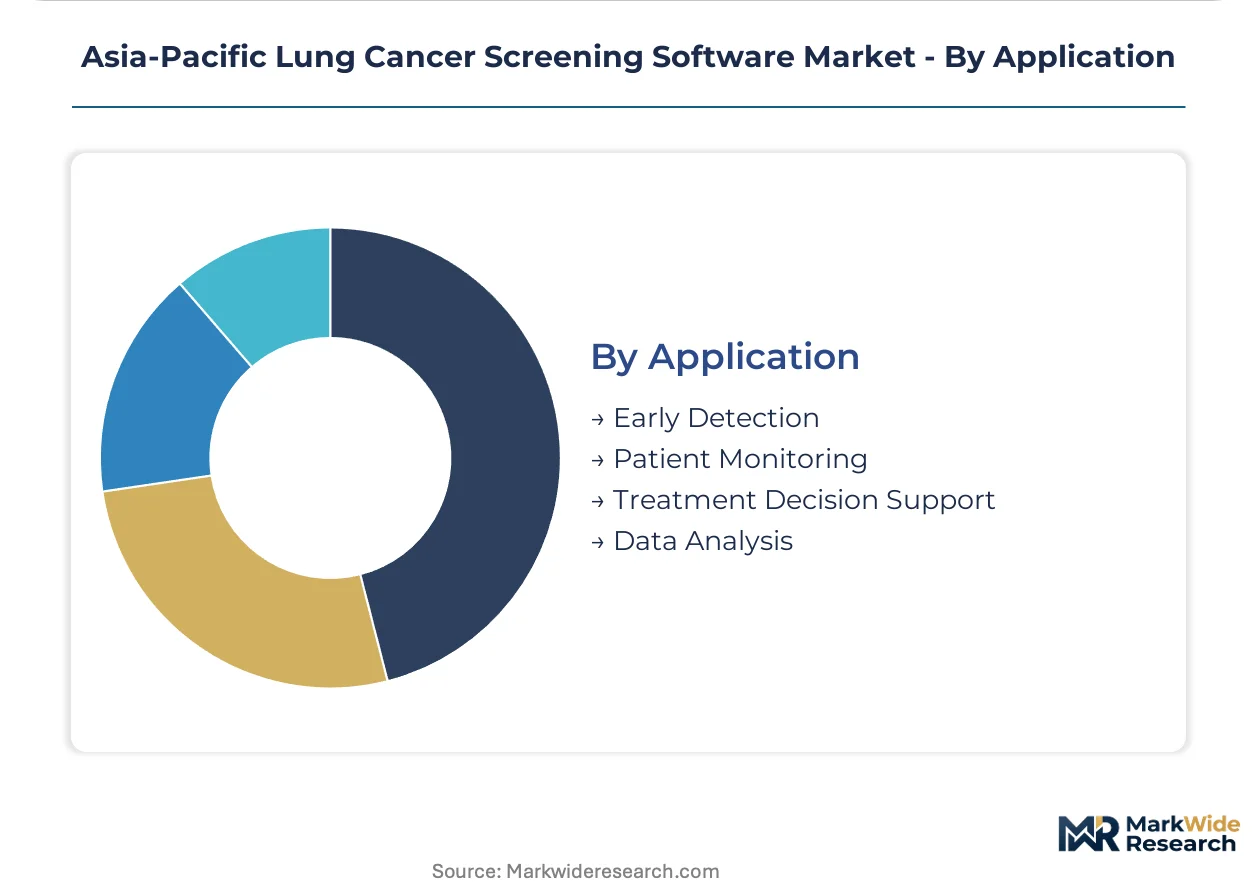
Application:
Customer workflow integration depth varies by application, with early detection requiring seamless CT console embedding while data analysis operates through standalone analytics portals.
- Early Detection:Screening-phase nodule identification and malignancy risk stratification at the point of image acquisition. China's national lung cancer early detection programs embed these applications into standardized care pathways across tier-one city hospital clusters.
- Treatment Decision Support:Post-diagnostic applications integrating screening history with staging and therapy selection workflows. Japanese oncology centers concentrate demand where longitudinal patient tracking supports multidisciplinary tumor board decisions.
- Patient Monitoring:Surveillance applications tracking nodule progression across serial screening rounds.
- Data Analysis:Population-level aggregation tools for screening program quality assurance and outcome reporting.
Early detection commands the dominant revenue share while treatment decision support exhibits the steepest expansion trajectory as precision oncology protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The East-West Economic Corridor and Trans-Asian Railway network underwrite Southeast Asia's emerging role in distributed healthcare delivery, while submarine cable systems connecting Tokyo, Singapore, and Sydney anchor cloud infrastructure for medical AI deployment across the region.
China
Shanghai and Beijing hospital clusters drive procurement volume for AI-assisted LDCT screening as national early detection programs mandate standardized workflows. NMPA's technical guidelines for deep learning medical software clarified registration pathways, accelerating domestic developer consolidation. Yangtze River Delta medical centers lead cloud migration trials under dual carbon compliance mandates.
Japan
Kanto region university hospitals pioneered unbundled AI software procurement committees, separating algorithm evaluation from hardware purchasing decisions. PMDA's Sakigake designation compresses review timelines for AI diagnostics, enabling earlier commercialization for developers targeting Japanese networks. Tokyo metropolitan hospital systems anchor demand validation for broader regional rollout.
Australia
Federal digital health infrastructure programs subsidize cloud-first PACS transitions across New South Wales and Victoria public hospital networks. TGA guidelines clarified software-as-medical-device responsibilities for cloud-hosted diagnostics, reducing procurement uncertainty. Sydney and Melbourne medical centers concentrate pilot deployments of edge-computing screening architectures.
South Korea
Seoul Capital Area regional medical centers drive adoption under federal cloud-first procurement mandates for hospital IT infrastructure. MFDS maintains distinct classification rules for AI-enabled diagnostic software, determining clinical evidence requirements for market access. Daegu-Gyeongbuk hospital clusters specialize in federated learning validation for privacy-preserving model training.
India
Mumbai and Bangalore teleradiology hubs create demand for cloud-deployable screening solutions requiring minimal on-site IT support. CDSCO regulatory frameworks for software-as-medical-device remain in development, creating variable market access timelines across states. Maharashtra diagnostic center chains expand AI-assisted screening into tier-two cities through hub-and-spoke network architectures.
Asia-Pacific Lung Cancer Screening Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying algorithmic modules for embedding. The vendor base separates into imaging equipment manufacturers bundling software with hardware fleets, pure-play AI developers competing on algorithmic performance, and workflow middleware providers bridging hospital information systems. Strategic moves concentrate on cloud deployment partnerships and regulatory registration infrastructure buildout.
Among Asia-Pacific headquartered specialists, Infervision and Qure.ai exemplify contrasting geographic anchoring strategies—one deepening integration with Chinese hospital information systems, the other competing on price-performance for teleradiology partnerships across India and Southeast Asia. Siemens Healthineers represents the integrated equipment manufacturer archetype, leveraging installed imaging hardware bases to bundle screening software across Japanese and Australian health networks.
| Leading Market Players |
|---|
| Coreline Soft |
| Infervision |
| Qure.ai |
| PenRad Technologies |
| Volpara Health |
| Optellum |
| FUJIFILM Holdings Corporation |
| Philips Healthcare |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Chinese hospital information system integrators concentrate control over middleware deployment slots, capturing margin pools that algorithm developers must share through revenue-sharing arrangements for CT console embedding rights.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital networks purchasing site-wide licenses from standalone diagnostic centers acquiring per-study transactional models. Pricing stratifies across premium, standard, and economy tiers based on algorithm validation depth and Lung-RADS classification sophistication. Cost compression in the economy tier intensifies as Indian teleradiology hubs drive per-scan pricing toward marginal cost. Public hospital networks in Australia and South Korea exhibit lowest price sensitivity due to federal subsidy programs, while Southeast Asian standalone imaging chains negotiate aggressively on total cost of ownership.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for GPU hardware sourcing, forcing algorithm developers to qualify alternative compute suppliers from Taiwan and South Korea. The supply chain draws from concentrated GPU manufacturing in Taiwan, specialized DICOM middleware development in Japan, and cloud infrastructure provisioning across Singapore and Australia. Single-source vulnerability persists for NVIDIA data center accelerators used in model training clusters. Distribution runs through direct hospital procurement committees in tier-one cities and regional distributor networks for provincial diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific lung cancer screening software functions as a service-attach opportunity where cloud-based algorithm update subscriptions and radiologist workflow integration services expand faster than perpetual licensing revenue.
For Market Incumbents: Pre-empt cloud-native entrants by acquiring federated learning engineering teams before NMPA and PMDA finalize privacy-preserving validation guidelines. Siemens Healthineers and FUJIFILM Holdings should deepen integration with Chinese hospital information systems to defend against pure-play AI developers. Certification investment in Sakigake-designated pathways anchors pricing power in Japanese academic medical centers. For New Entrants and Emerging Players: Indonesia and Vietnam's underdeveloped specialist radiologist density creates immediate white-space for AI-assisted teleradiology platforms requiring minimal on-site IT support. Target hub-and-spoke network architectures where provincial diagnostic centers feed imaging studies to central reading facilities. A cloud-first go-to-market angle bypasses legacy on-premise procurement cycles that favor established equipment manufacturers. For Investors and Strategic Acquirers: Capital is best deployed toward workflow middleware specialists possessing hospital information system integration depth rather than standalone algorithm developers. Long-term viability across the analysis window hinges on sustainable reimbursement codes for AI-assisted reads across national health insurance schemes. Watch NMPA registration timelines for foreign developers as the inflection indicator for competitive access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Development | Enables privacy-preserving model training across hospital networks without centralizing patient data subject to NMPA localization requirements. |
| Sakigake Designation Pursuit | Accelerates PMDA review timelines for AI diagnostics targeting Japanese university hospital procurement committees. |
| Cloud-First PACS Partnership | Aligns with Australian federal digital health subsidies and South Korean cloud-first procurement mandates. |
| Hospital Information System Integration | Creates switching costs through deep embedding with Chinese HIS vendors like Neusoft and Winning Health. |
| Reimbursement Strategy Development | Secures sustainable payment coverage for AI-assisted LDCT reads across China's national health insurance schemes. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with radiology department heads, hospital procurement managers, biomedical engineers, and GPO contracts managers; and secondary validation against NMPA registration databases, PMDA approval records, hospital procurement disclosures, and CT scanner installation reports. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against national screening program budgets anchored value estimates.
Forecast inputs considered deployment architecture migration rates, regulatory approval velocity across PMDA and NMPA pathways, and cloud infrastructure subsidy program rollouts. Segmentation dimensions modeled include product type, end-user institution scale, deployment model, and application workflow depth. CAGRs derived from algorithmic diffusion curves fitted to historical CT scanner procurement patterns and reimbursement code expansion timelines.
Practitioners should monitor reimbursement code revisions, GPU export control adjustments, and federated learning standardization for early signals requiring forecast recalibration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market