
 Adrenal Cortical Carcinoma Diagnosis and Treatment Market | 2026-2036
Adrenal Cortical Carcinoma Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Adrenal Cortical Carcinoma Diagnosis and Treatment Market Outlook
The capital-intensity divergence between integrated pharmaceutical conglomerates and focused oncology biotechs is redrawing competitive boundaries in adrenal cortical carcinoma care. Pfizer Inc. leverages its global manufacturing scale to secure supply chain resilience for mitotane, the cornerstone ACC therapy. Exelixis, Inc. specializes in kinase inhibitor development, anchoring its position in targeted therapy segments where clinical differentiation commands premium positioning. Bristol-Myers Squibb Company competes through immuno-oncology platforms that extend into rare tumor types via basket trial designs.
Adrenal cortical carcinoma diagnosis and treatment encompasses the clinical detection and therapeutic management of malignant neoplasms arising from the adrenal cortex, typically involving hormonal profiling for cortisol and androgen excess alongside cross-sectional imaging to assess local invasion and metastatic spread. The primary purpose centers on early identification of this rare aggressive malignancy and multimodal intervention combining surgical resection with adjuvant pharmacotherapy. Imaging modalities led by CT Scan dominate initial staging workflows due to superior spatial resolution for retroperitoneal assessment, while Targeted Therapy represents the fastest-expanding treatment category as molecular characterization of ACC tumors enables precision drug selection. End User demand tilts toward Hospitals where multidisciplinary tumor boards coordinate complex case management, though Specialty Clinics capture growing referral volume for hormone-directed surveillance protocols.
The FDA orphan drug program shapes therapeutic development incentives through tax credits and market exclusivity provisions that sustain investment in rare indication pipelines. EMA's centralized marketing authorization procedure governs commercial access across European Union member states, while REACH compliance requirements influence pharmaceutical manufacturing standards for cytotoxic agents used in ACC chemotherapy regimens. Stakeholders must monitor biomarker-driven trial enrollment criteria and evolving health technology assessment methodologies that determine reimbursement for novel ACC therapeutics.
Market Dynamics
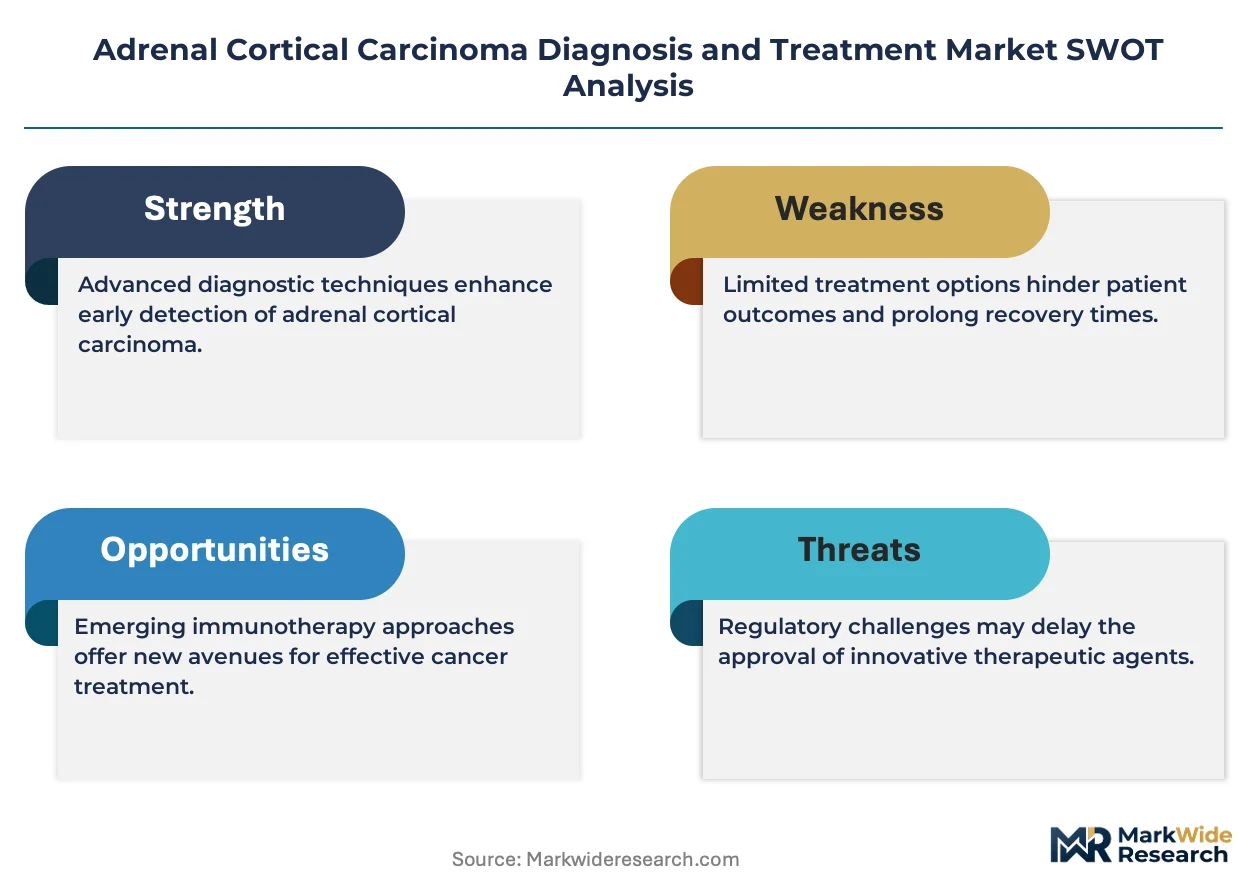
The FDA's orphan drug designation framework is compressing development timelines for adrenal cortical carcinoma therapeutics, creating a structural incentive pull that concentrates R&D investment in rare oncology pipelines and reshapes competitive entry patterns.
Growth Catalysts
- EMA centralized authorization:The European Medicines Agency's unified marketing approval pathway accelerates commercial access across EU member states, reducing regulatory fragmentation for ACC drug sponsors.
- Specialty clinic expansion:Tertiary referral centers in the United States are standardizing hormone-directed surveillance protocols, driving protocol adoption for post-surgical monitoring.
- Mitotane manufacturing scale:Integrated pharmaceutical conglomerates leveraging global production networks are securing supply chain resilience for this cornerstone ACC therapy.
Market Restraints
- REACH compliance burden:The European Chemicals Agency's registration requirements for cytotoxic agents impose manufacturing cost escalation and timeline extension on ACC chemotherapy producers.
- Diagnostic imaging concentration:CT scan dependency for retroperitoneal assessment creates single-modality vulnerability in staging workflows across concentrated tertiary care networks.
- Kinase inhibitor substitution pressure:Targeted therapy development in adjacent oncology indications threatens to divert research capital from ACC-specific molecular targets.
Strategic Opportunities
- Biomarker-driven trial design:Molecular characterization protocols enabling precision drug selection represent untapped segmentation potential for basket trial enrollment expansion.
- Health technology assessment adaptation:Evolving reimbursement methodologies for novel ACC therapeutics in Germany and France create policy windows for value demonstration.
- Multidisciplinary tumor board integration:Hospital-based coordination models in the United States offer channel consolidation opportunities for complex case management services.
Industry Challenges
- Rare oncology talent scarcity:Clinical trial design expertise for ultra-rare malignancies concentrates in limited academic medical centers, constraining sponsor access to qualified investigators.
- Cross-border regulatory harmonization friction:Divergent health technology assessment timelines between FDA breakthrough designation and EMA conditional approval create launch sequencing complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adrenal Cortical Carcinoma Diagnosis and Treatment Market |
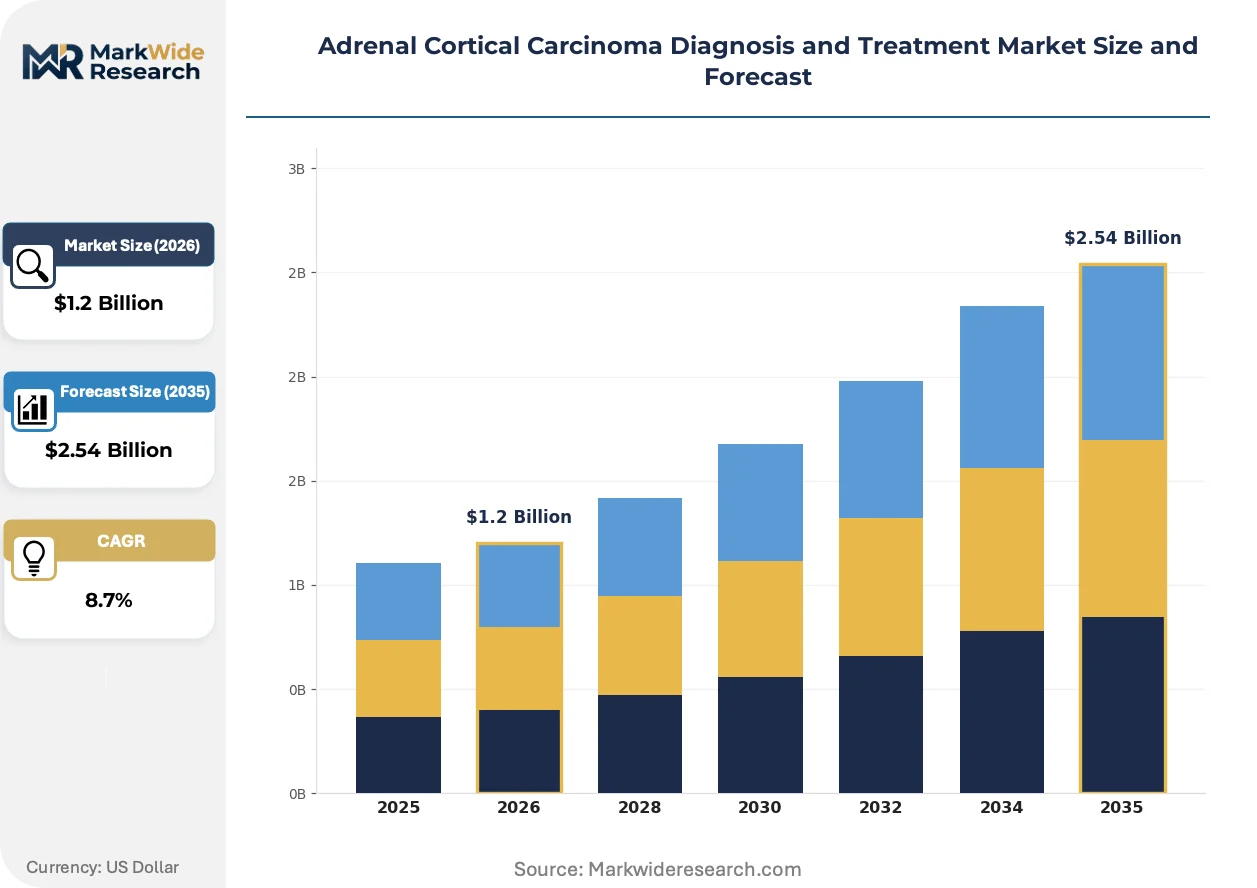
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.54 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Diagnosis Method: CT Scan, MRI, Biopsy, Blood Test Treatment Type: Surgery, Chemotherapy, Radiation Therapy, Targeted Therapy End User: Hospitals, Specialty Clinics, Research Institutes, Diagnostic Centers Stage of Treatment: Initial, Progressive, Advanced, Remission |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Bristol-Myers Squibb Company, Exelixis, Inc., HRA Pharma, Takeda Pharmaceutical Company Limited, Bayer AG, Novartis AG, Ipsen Biopharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adrenal Cortical Carcinoma Diagnosis and Treatment Market Strategic Shifts
Precision oncology platforms are displacing empirical chemotherapy selection in adrenal cortical carcinoma care, with molecular profiling capabilities compressing the gap between diagnostic confirmation and targeted therapeutic intervention.
Liquid biopsy protocols for circulating tumor DNA detection are displacing repeat tissue biopsy requirements in metastatic ACC monitoring. Academic medical centers in the United States are adopting these minimally invasive surveillance methods to track treatment response. This displacement is reducing procedural morbidity while accelerating real-time therapeutic adjustment decisions.
REACH authorization amendments for cytotoxic pharmaceutical intermediates are tightening manufacturing environmental controls across European Union production facilities. ECHA compliance deadlines are forcing reformulation investments for mitotane supply chains serving EU markets. German and French manufacturers are responding with captive synthesis capabilities to isolate regulatory risk.
Specialty clinic referral networks are consolidating hormone-directed surveillance volume away from general oncology practices. Multidisciplinary tumor boards at tertiary centers in the United States are capturing complex ACC case management through dedicated endocrine surgery pathways. This channel concentration is most visible in Boston, Houston, and New York metropolitan clusters where academic medical center density enables protocol standardization.
Adrenal Cortical Carcinoma Diagnosis and Treatment Market Segmentation
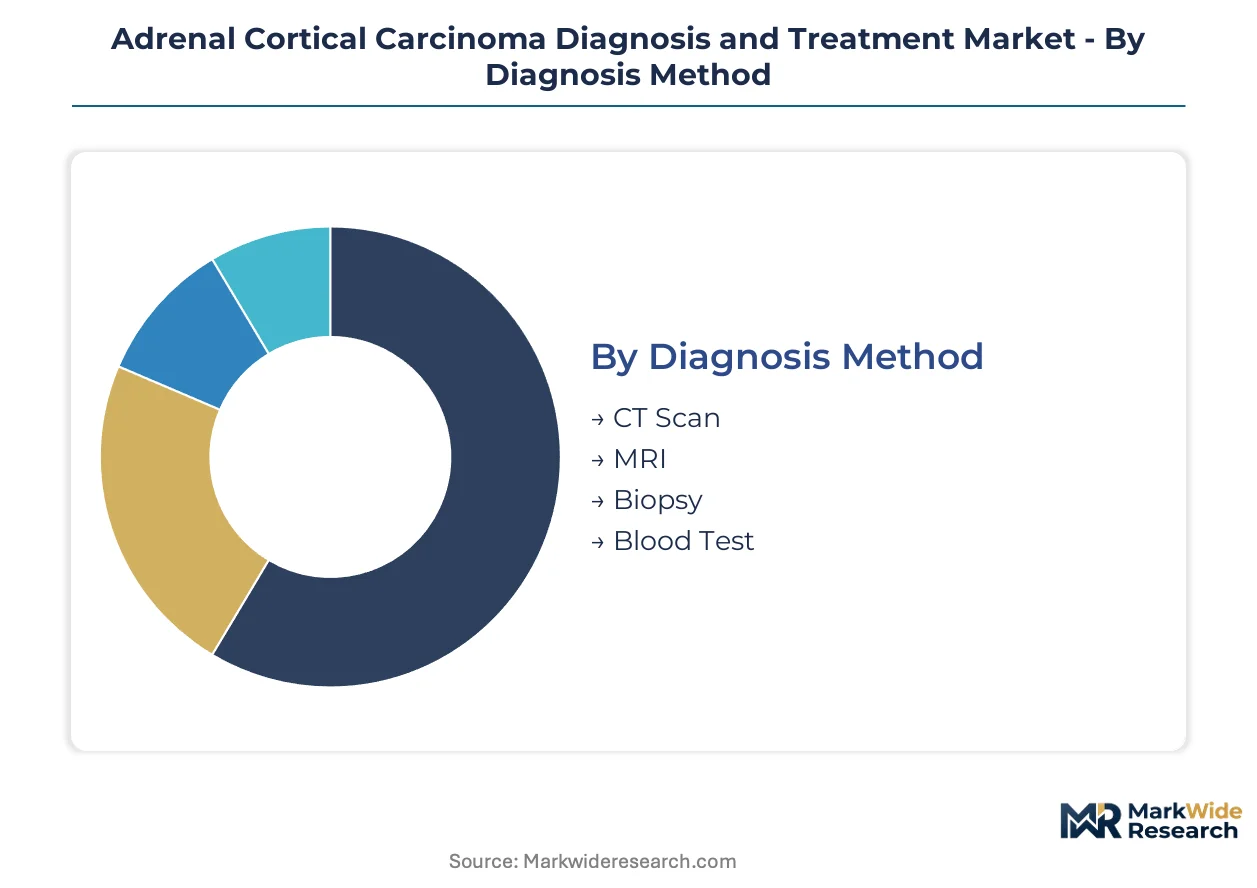
Segmentation in adrenal cortical carcinoma care reflects divergent regulatory pathways for diagnostic imaging versus therapeutic intervention. Each category carries distinct reimbursement logic and clinical workflow requirements that shape vendor positioning and provider procurement priorities.
Diagnosis Method:
FDA device classification tiers and EMA MDR conformity assessment routes create divergent commercialization timelines for imaging modalities versus laboratory assays.
- CT Scan:Cross-sectional imaging with iodinated contrast delivers superior spatial resolution for retroperitoneal mass assessment and local invasion staging. Demand concentrates in United States tertiary care networks where multidisciplinary tumor boards mandate CT-first protocols for surgical planning; EMA MDR technical documentation requirements for Class IIb devices extend EU market entry timelines relative to FDA 510(k) pathways.
- MRI:Magnetic resonance imaging provides tissue characterization without ionizing radiation, particularly valuable for pediatric ACC cases and serial surveillance protocols. Adoption clusters in German academic medical centers leveraging statutory health insurance reimbursement for advanced imaging; superior soft-tissue contrast drives substitution pressure against CT in hormone-secreting tumor evaluation.
- Biopsy:Image-guided tissue acquisition enables histopathological confirmation and molecular profiling.
- Blood Test:Hormonal profiling for cortisol, androgens, and metabolites supports functional tumor characterization.
Established volume favors CT Scan; emerging adoption favors MRI.
Treatment Type:
Cost tier stratification separates curative-intent surgical intervention from chronic pharmacotherapy management.
- Surgery:Adrenalectomy with lymphadenectomy remains the only curative modality for localized ACC, requiring specialized endocrine surgical expertise concentrated in high-volume United States centers. Reimbursement through Medicare DRG-406 classification creates predictable revenue capture for hospitals; EMA centralized authorization for adjuvant protocols influences post-surgical care standardization across France and Italy.
- Targeted Therapy:Kinase inhibitors and mTOR pathway modulators enable precision intervention based on molecular tumor profiling. Steepest expansion trajectory reflects biomarker-driven patient selection protocols; United States specialty clinics capture referral volume for oral agent administration outside traditional infusion center infrastructure.
- Chemotherapy:EDP-M regimen and mitotane monotherapy address metastatic disease progression.
- Radiation Therapy:Adjuvant and palliative applications target local recurrence and symptomatic metastases.
Established volume favors Surgery; emerging adoption favors Targeted Therapy.
End User:
Customer type fragmentation reflects divergent care coordination models across acute inpatient versus ambulatory settings.
- Hospitals:Inpatient facilities with multidisciplinary tumor boards coordinate complex case management combining surgical resection, systemic therapy, and radiation oncology. Volume concentrates in United States academic medical centers with NCI-designated cancer center status; DRG-based reimbursement creates margin pressure offset by high-complexity case mix.
- Specialty Clinics:Tertiary referral centers standardize hormone-directed surveillance protocols and oral therapy monitoring. Fastest volume gains in Boston and Houston metropolitan clusters; streamlined prior authorization pathways for oral oncolytics reduce administrative burden relative to hospital outpatient departments.
- Diagnostic Centers:Independent imaging facilities provide staging and surveillance services.
- Research Institutes:Academic sites conduct basket trials and biomarker validation studies.
Established volume favors Hospitals; emerging adoption favors Specialty Clinics.
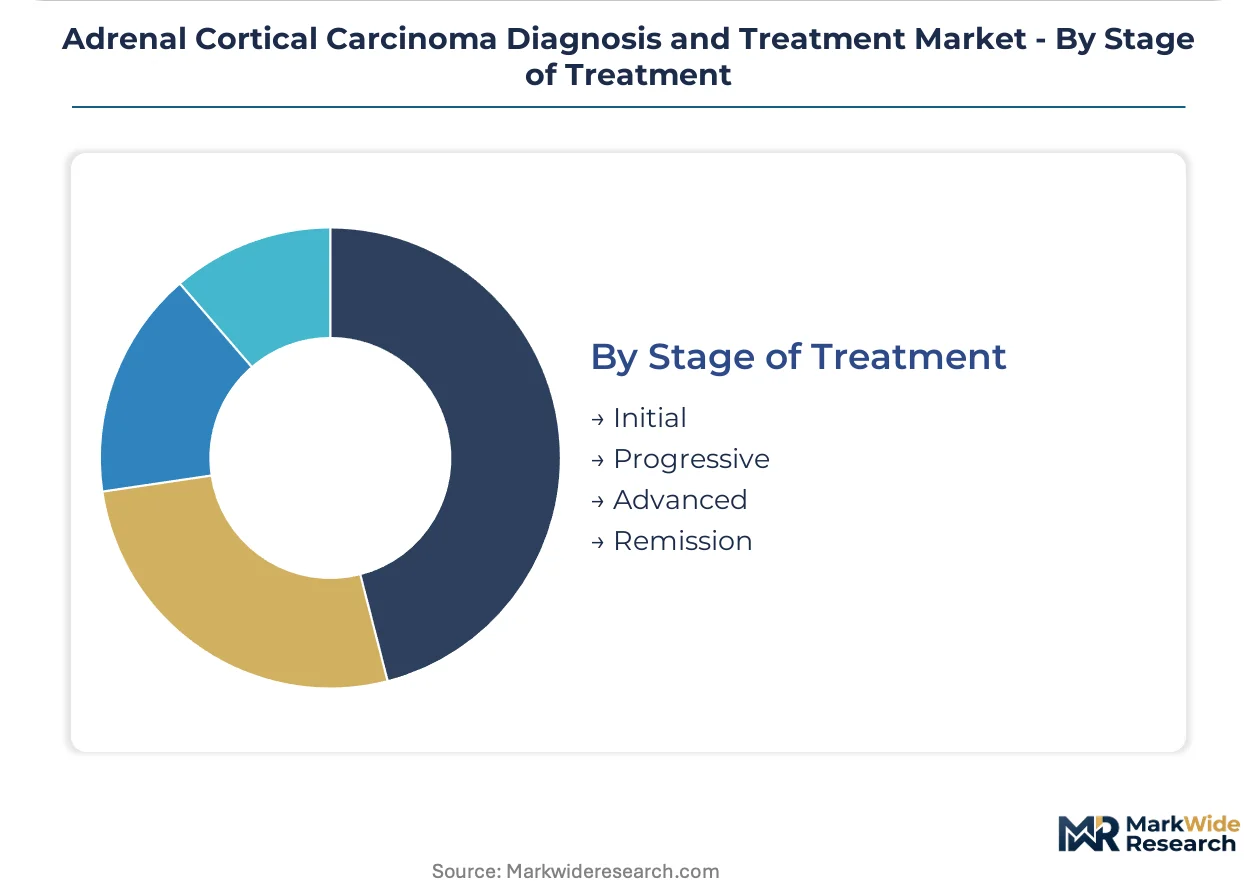
Stage of Treatment:
Maturity differentiation separates well-established initial intervention protocols from evolving remission surveillance standards.
- Initial:Diagnostic confirmation and primary treatment planning encompass imaging staging, surgical consultation, and neoadjuvant therapy consideration. Protocol standardization is most advanced in United States NCCN guideline adoption; EMA-EMA collaboration on rare tumor trial design accelerates evidence generation for first-line therapeutic selection.
- Advanced:Metastatic disease management requires systemic therapy sequencing and palliative intervention coordination. Demand concentrates in French and German comprehensive cancer centers with established sarcoma/ACC referral networks; biomarker-driven trial enrollment creates access to investigational agents outside standard-of-care pathways.
- Progressive:Recurrence detection and salvage therapy initiation follow surveillance protocols.
- Remission:Long-term hormonal monitoring and late-effects management extend care duration.
Established volume favors Initial; emerging adoption favors Advanced.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while Germany enforces cost-containment through health technology assessment, creating a structural asymmetry that shapes commercial strategy across the adrenal cortical carcinoma landscape.
United States
Demand clusters in Boston, Houston, and New York metropolitan areas where NCI-designated cancer centers coordinate multidisciplinary tumor boards. FDA orphan drug tax credits sustain R&D investment in rare oncology pipelines. Tertiary referral networks in these clusters standardize hormone-directed surveillance protocols that drive post-surgical monitoring volume.
Germany
Comprehensive cancer centers in Munich and Heidelberg capture metastatic ACC referral volume through established sarcoma networks. EMA centralized authorization procedures govern commercial access, while statutory health insurance reimbursement frameworks enforce cost-effectiveness thresholds for novel therapeutics. Bavarian manufacturers are developing captive synthesis capabilities to isolate REACH compliance risk for mitotane supply chains.
France
Paris and Lyon academic medical centers lead biomarker-driven trial enrollment for basket study designs. ANSM oversight of clinical trial authorization creates distinct timelines from FDA breakthrough pathways. Île-de-France hospital networks are consolidating complex case management through dedicated endocrine surgery pathways that reduce referral leakage.
United Kingdom
London and Manchester tertiary centers specialize in pediatric ACC cases where MRI substitutes for CT to minimize ionizing radiation exposure. NICE health technology assessment methodologies determine reimbursement access for targeted therapies. The NHS England specialized commissioning framework concentrates rare cancer expertise in designated supra-regional centers.
Japan
Tokyo and Osaka metropolitan areas host PMDA-accredited clinical trial sites for kinase inhibitor development in rare tumors. National health insurance pricing negotiations create predictable but compressed margins for oral oncolytics. Japanese pharmaceutical conglomerates are leveraging domestic manufacturing scale to secure regional supply chain resilience for cytotoxic agents.
Adrenal Cortical Carcinoma Diagnosis and Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated pharmaceutical conglomerates leveraging global manufacturing scale while focused oncology biotechs concentrate on clinical differentiation through targeted therapy development. The market structure reflects this bifurcation: large-cap diversified players secure supply chain resilience for cornerstone therapies, while mid-cap specialists command premium positioning in molecularly defined segments. Three archetypes dominate—scale-driven manufacturers, precision oncology developers, and rare disease specialists. Competitive moves concentrate on strategic partnerships for biomarker validation and geographic expansion through centralized regulatory pathways.
Within the scale-driven tier, Pfizer Inc. and Novartis AG occupy positions anchored by global production networks and orphan drug portfolio breadth. Exelixis, Inc. exemplifies the precision oncology archetype, sitting within the kinase inhibitor specialization segment where molecular characterization drives patient selection protocols. Bristol-Myers Squibb Company represents the immuno-oncology extension strategy, leveraging basket trial designs to access rare tumor indications.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Exelixis, Inc. |
| HRA Pharma |
| Takeda Pharmaceutical Company Limited |
| Bayer AG |
| Novartis AG |
| Ipsen Biopharmaceuticals, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for mitotane API lock in supply access and price visibility for integrated pharmaceutical conglomerates serving United States and European Union markets, insulating procurement costs from spot market volatility in cytotoxic agent feedstocks.
Pricing Analysis
The customization-premium spread between standard mitotane formulations and patient-specific dosing protocols runs wide in adrenal cortical carcinoma care. Contract-based long-term offtake dominates procurement for cornerstone therapies, with price differentiation driven by FDA orphan drug exclusivity premiums and REACH compliance certification tiers. Pricing pressure stems from health technology assessment methodologies tightening reimbursement thresholds in Germany and France. Hospital procurement committees exhibit highest price sensitivity due to DRG-based margin compression, while specialty clinics demonstrate lower sensitivity given streamlined prior authorization pathways for oral oncolytics.
Supply Chain Analysis
Inventory buffers for mitotane API stretch across twelve to eighteen month cycles due to complex synthesis requirements and ECHA environmental control mandates. Manufacturing concentrates in the United States, Germany, and Switzerland for finished dose forms, with active pharmaceutical ingredient production anchored in India and Italy. Raw material dependencies include chlorinated aromatic precursors and specialized solvent systems. Single-source vulnerability pervades the API tier where qualified suppliers number fewer than five globally. Distribution runs through hospital central pharmacies and specialty clinic direct-to-site channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adrenal cortical carcinoma care operates as a service-attach opportunity where hormone-directed surveillance protocols and biomarker monitoring services expand faster than diagnostic hardware sales.
For Market Incumbents: Compound defensive positioning through backward integration into mitotane API synthesis and captive manufacturing of kinase inhibitor intermediates. Kinase inhibitor substitution pressure from adjacent oncology indications threatens to erode molecular-target R&D budgets. Capacity addition in Bavarian production corridors isolates REACH compliance risk while securing EU market access. For New Entrants and Emerging Players: Differentiate on liquid biopsy protocol development for circulating tumor DNA surveillance in metastatic ACC monitoring. The most penetrable white space sits in ambulatory specialty clinic networks in Houston and Boston metropolitan clusters. A go-to-market angle anchored to oral oncolytic prior authorization automation bypasses hospital outpatient department administrative burdens. For Investors and Strategic Acquirers: Capital is best deployed toward precision oncology developers with validated biomarker platforms and basket trial enrollment capabilities across rare tumor indications. Long-term viability over a five-to-ten year window favors molecular characterization tools enabling therapeutic selection protocols. The signal to watch is EMA conditional approval velocity relative to FDA breakthrough designation timelines as an inflection indicator for European market access risk.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Basket trial designs extend immuno-oncology platforms into rare tumor types. |
| Regulatory Approval Pathway | EMA centralized authorization reduces fragmentation across EU member states. |
| Manufacturing Scale-Up | Captive synthesis capabilities isolate REACH compliance risk for mitotane supply. |
| Pipeline Diversification | Kinase inhibitor specialization commands premium positioning in targeted therapy segments. |
| Strategic Partnership | Multidisciplinary tumor board integration consolidates complex case management channels. |
Study Parameters
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation reconcile segmentation outputs across diagnosis method, treatment type, end user, and stage of treatment dimensions.
Sensitivity analysis frameworks test forecast robustness across alternative regulatory approval scenarios and reimbursement policy shifts throughout the projection horizon. Segmentation dimensions modeled include treatment line, patient population, regional regulatory cluster, and molecular characterization protocol adoption. CAGRs derive from fitted growth curves applied to orphan drug market evolution patterns and health technology assessment timeline assumptions.
Decision-makers should treat outputs as directional under stable FDA orphan drug incentive structures and EMA centralized authorization continuity; material deviation in health technology assessment methodologies would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market