
 America Cancer Immunotherapy Market | 2026-2036
America Cancer Immunotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
America Cancer Immunotherapy Market Insights
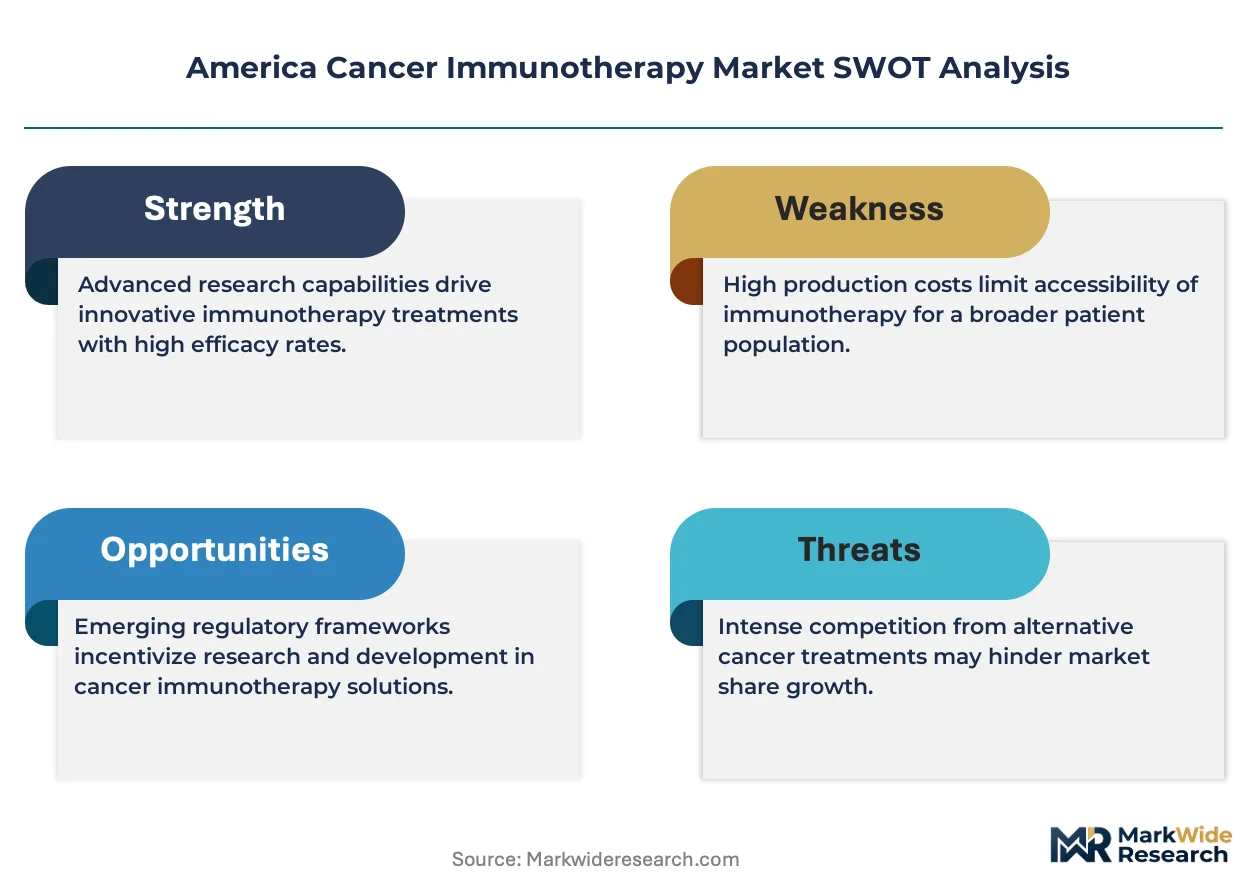
Biologics manufacturing capacity across North and Latin America is realigning toward cell-line expansion and cold-chain infrastructure for immune-oncology biologics. Merck & Co., Inc. leverages its pembrolizumab franchise to dominate PD-1 checkpoint inhibition across solid tumor indications. Bristol-Myers Squibb sustains competitive intensity through dual immunotherapy combinations and manufacturing scale in biologics. Roche anchors its position through diagnostic-therapeutic pairing and companion test integration.
Cancer immunotherapy encompasses therapeutic modalities that harness or modulate the immune system to recognize and eliminate malignant cells, including monoclonal antibodies, checkpoint inhibitors, cytokines, and therapeutic vaccines administered via intravenous, subcutaneous, or oral routes. These agents function by blocking immune evasion mechanisms, enhancing T-cell activation, or stimulating antigen-presenting cell activity to achieve durable anti-tumor responses. Checkpoint inhibitors command the largest revenue share within product type segmentation due to established efficacy in melanoma and non-small cell lung cancer, while cytokines and therapeutic vaccines represent faster-expanding categories driven by combination protocol development. Hospitals retain the dominant end-user position by patient volume, though oncology clinics capture margin concentration through specialized infusion center operations and protocol expertise.
FDA oversees biologics licensing and breakthrough therapy designation pathways that compress development timelines and shape clinical trial investment priorities. The National Institutes of Health funding directives and CMS reimbursement policies for CAR-T and bispecific antibody therapies determine commercial accessibility and provider adoption thresholds. Stakeholders must monitor evolving FDA guidance on real-world evidence requirements and biosimilar interchangeability standards as these frameworks determine competitive entry dynamics and portfolio prioritization decisions.
Market Dynamics
Checkpoint inhibitor manufacturing scale and companion diagnostic co-development requirements are compressing development timelines while concentrating revenue among integrated biologics-diagnostics platforms across the Americas.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Compressed approval pathways accelerate commercialization timelines for novel immunotherapy modalities, reducing time-to-market for first-in-class agents.
- CAR-T cell therapy infrastructure:Dedicated manufacturing facilities and cold-chain networks across the United States enable scalable autologous cell therapy administration.
- Oncology clinic expansion:Specialized infusion centers in Brazil and Mexico extend access to checkpoint inhibitor protocols beyond hospital settings.
Market Restraints
- Biologics manufacturing concentration:Cell-line development and viral vector production capacity concentrates among limited contract manufacturing organizations, creating supply bottlenecks.
- CMS reimbursement complexity:National Coverage Determination processes for novel immunotherapy combinations create payment uncertainty and provider adoption delays.
- High cold-chain logistics costs:Temperature-controlled distribution requirements for mRNA-based therapeutic vaccines inflate per-dose logistics expenditure.
Strategic Opportunities
- Mexico regulatory harmonization:COFEPRIS alignment with FDA standards accelerates parallel approval pathways for immunotherapy agents.
- Subcutaneous formulation development:Self-administration protocols reduce infusion center burden and expand community oncology access.
- Real-world evidence frameworks:FDA guidance on post-approval efficacy monitoring enables label expansion through observational data collection.
Industry Challenges
- Cell therapy manufacturing workforce scarcity:Shortage of aseptic processing technicians and quality control specialists constrains autologous production scale-up.
- Biosimilar interchangeability standards:Evolving FDA guidance on switching studies creates portfolio planning uncertainty for follow-on biologics developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America Cancer Immunotherapy Market |
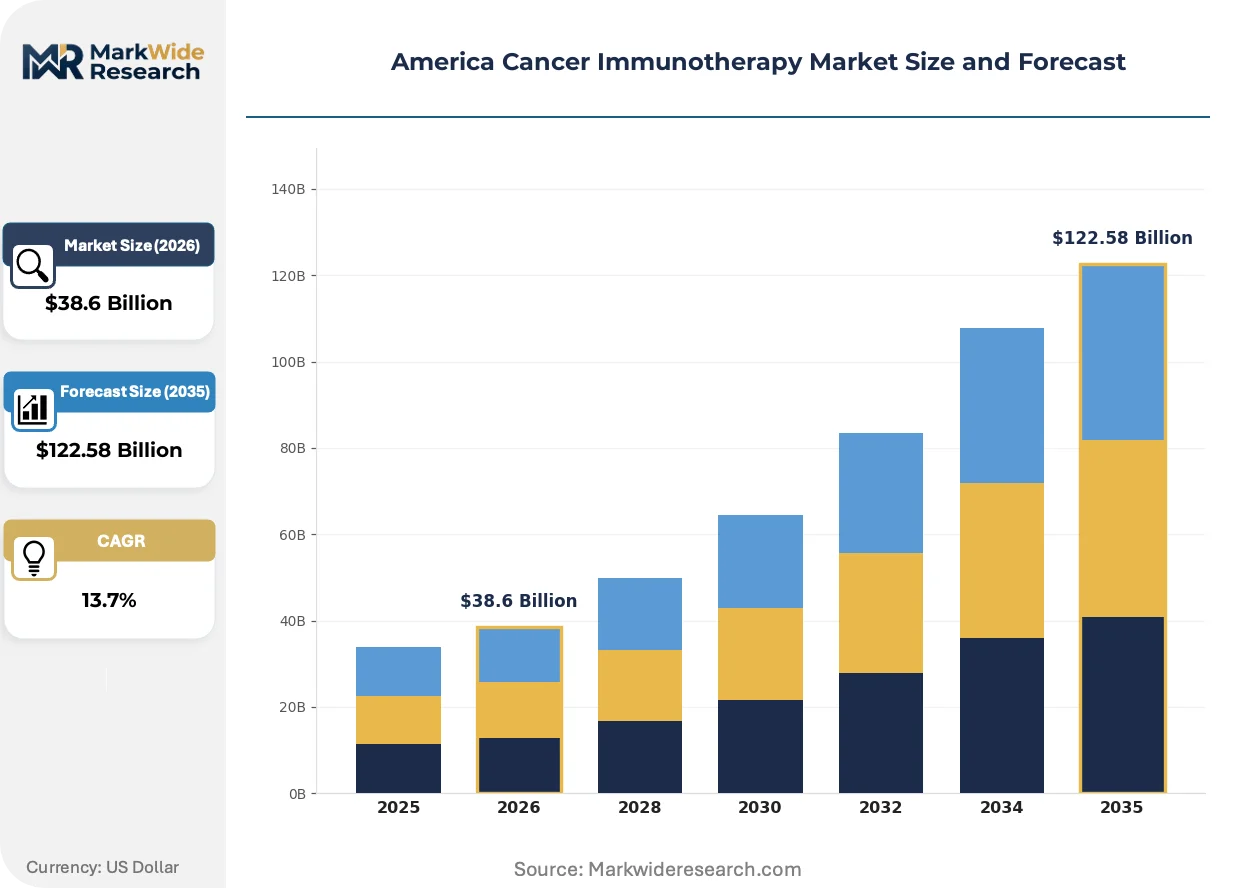
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $122.58 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Checkpoint Inhibitors, Cytokines, Vaccines End User: Hospitals, Oncology Clinics, Research Laboratories, Homecare Settings Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular Therapeutic Area: Hematologic Malignancies, Solid Tumors, Skin Cancer, Lung Cancer |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb, Roche (F. Hoffmann-La Roche Ltd), AstraZeneca, Amgen Inc., Eli Lilly and Company, Pfizer Inc., Johnson & Johnson, Novartis AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America Cancer Immunotherapy Market Trends and Innovations
Bispecific antibody engineering and AI-driven biomarker discovery are compressing clinical development cycles while redirecting competitive investment toward combination protocol design.
Bispecific T-cell engagers are consolidating their position in hematologic malignancy treatment through dual-targeting mechanisms that bypass resistance pathways. Community oncology practices in the United States are adopting these agents at accelerating pace following outpatient administration protocol approvals. The technology is consolidating manufacturing investment toward single-platform multi-specific architectures that reduce per-dose production complexity.
FDA accelerated approval pathway revisions are tightening confirmatory trial requirements for immunotherapy agents granted conditional marketing authorization. Sponsors must now complete randomized controlled studies within compressed timelines or face withdrawal proceedings. Oncology drug developers are restructuring phase III programs to incorporate overall survival endpoints earlier, with solid tumor indications experiencing the most significant protocol redesign activity.
Integrated diagnostic-therapeutic purchasing is reshaping procurement relationships between hospital systems and biopharmaceutical manufacturers. Oncology clinics are consolidating vendor relationships around companion diagnostic-inclusive contracts that bundle testing with therapeutic access. This pattern is most pronounced in the United States, where integrated delivery networks leverage patient volume to negotiate performance-based reimbursement arrangements.
America Cancer Immunotherapy Market Segmentation
Immunotherapy market segmentation reveals distinct commercial trajectories across technology platforms, care delivery settings, and disease indications. Each dimension carries unique regulatory, reimbursement, and operational requirements that shape stakeholder investment priorities across the Americas.
Product Type:
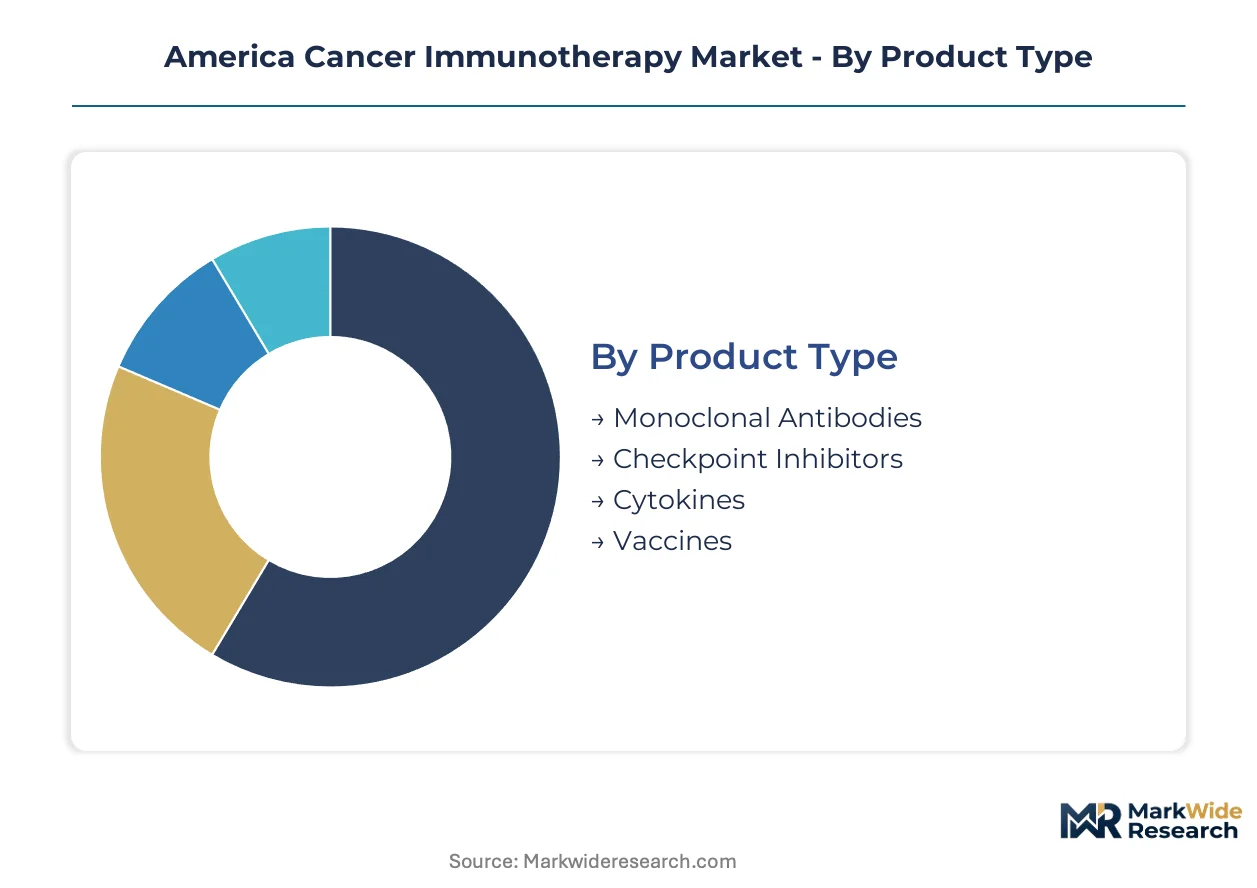
Checkpoint inhibitors and monoclonal antibodies anchor current revenue concentration, while cytokines and therapeutic vaccines are gaining share through combination protocol expansion.
- Checkpoint Inhibitors:PD-1 and PD-L1 blockade agents interrupt tumor immune evasion through T-cell activation restoration. Demand concentrates in United States oncology clinics for melanoma and non-small cell lung cancer, driven by durable response rates and outpatient administration protocols.
- Monoclonal Antibodies:Targeted cytotoxic and antibody-drug conjugate platforms deliver precision oncology through antigen-directed cell killing. United States hospital systems dominate procurement volume, constrained by companion diagnostic co-development requirements and FDA accelerated approval timelines.
- Cytokines:Interleukin and interferon-based immune modulators stimulate anti-tumor responses through innate immune activation. Brazil and Mexico infusion centers are expanding access as combination partners for checkpoint protocols.
- Vaccines:Therapeutic cancer vaccines prime antigen-specific T-cell responses against tumor-associated antigens. Cold-chain infrastructure investments across North America are enabling mRNA-based platform scale-up.
Mature deployment sits with checkpoint inhibitors. Newer deployment is concentrated in therapeutic vaccines.
End User:
Care delivery fragmentation across hospital systems, specialized clinics, and emerging homecare channels is reshaping distribution and reimbursement pathways.
- Hospitals:Academic medical centers and integrated delivery networks manage complex immunotherapy protocols requiring intensive monitoring. United States hospital systems capture the highest patient volumes for CAR-T and bispecific antibody administration.
- Oncology Clinics:Dedicated infusion centers specialize in checkpoint inhibitor protocols with streamlined operational workflows. Brazil and Mexico clinic networks are expanding capacity fastest, driven by private payer reimbursement expansion.
- Research Laboratories:Clinical trial sites and translational research facilities conduct biomarker-driven patient selection and protocol development. United States NIH-funded centers anchor investigator-initiated combination studies.
- Homecare Settings:Subcutaneous formulation administration is shifting select maintenance therapies outside traditional facilities. United States home infusion providers are building cold-chain capabilities for limited immunotherapy categories.
Volume leadership belongs to hospitals. Margin expansion is concentrating in oncology clinics.
Administration Route:
Formulation innovation is redirecting competitive investment toward patient convenience and care setting flexibility.
- Intravenous:Infusion-based delivery remains standard for checkpoint inhibitors and cell therapies requiring controlled administration. United States hospital outpatient departments retain infrastructure dominance for this route.
- Subcutaneous:Self-injection protocols reduce infusion center burden and enable community oncology expansion. FDA approvals for subcutaneous checkpoint inhibitor formulations are accelerating United States adoption.
- Oral:Small-molecule immunomodulators offer patient convenience but face bioavailability challenges for large biologics. Development pipelines concentrate on kinase inhibitors with immune-modulatory properties.
- Intramuscular:Therapeutic vaccine administration leverages depot formation for sustained antigen presentation. Cold-chain requirements for mRNA platforms limit current deployment scale.
Established protocols favor intravenous delivery. Fastest route expansion is occurring in subcutaneous formulations.
Therapeutic Area:
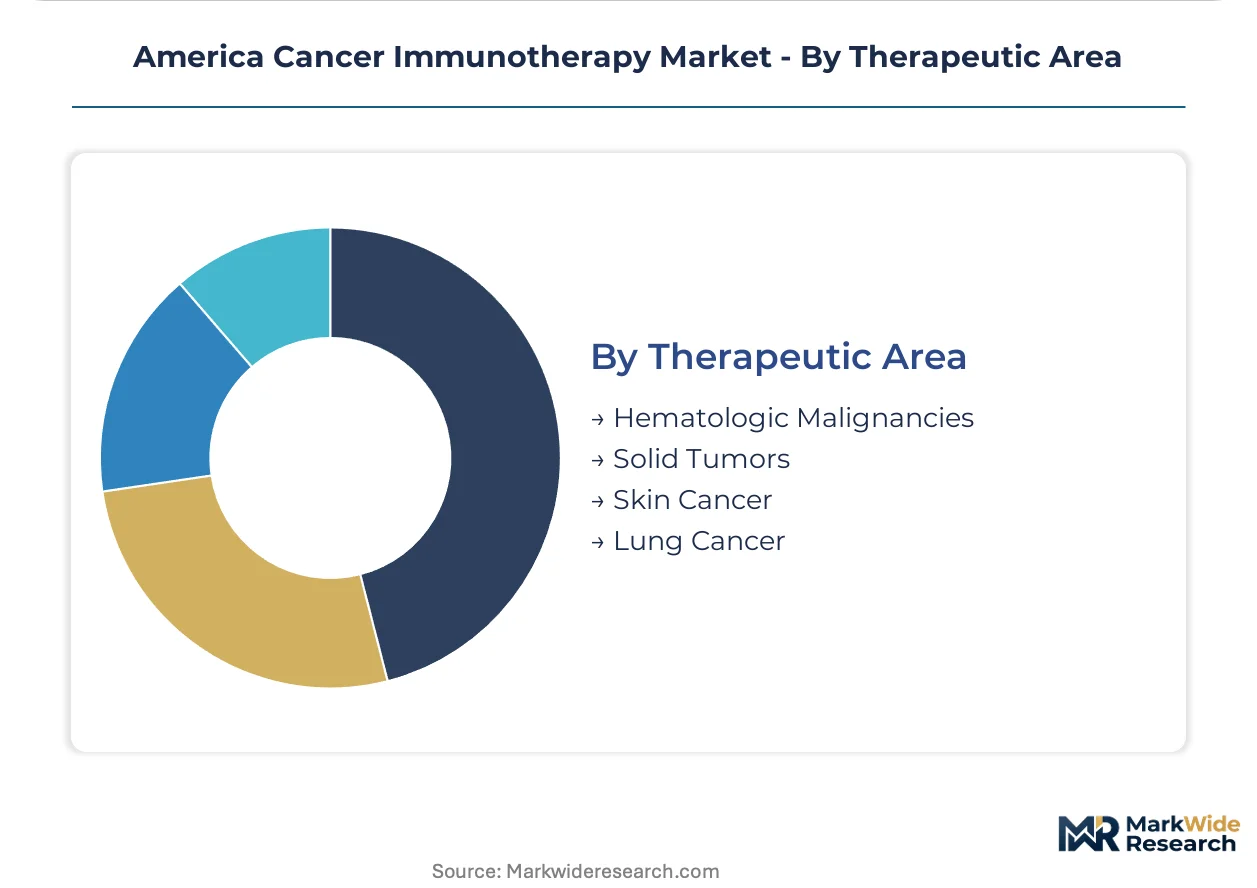
Disease-specific indication strategies determine clinical trial investment, regulatory pathway selection, and reimbursement negotiation positioning.
- Solid Tumors:Non-small cell lung cancer, colorectal, and renal cell carcinoma indications command the largest checkpoint inhibitor prescription volumes. United States Medicare reimbursement policies shape commercial accessibility for these indications.
- Hematologic Malignancies:CAR-T cell therapies and bispecific T-cell engagers achieve highest response rates in B-cell malignancies. Dedicated manufacturing facilities across the United States enable scalable autologous production.
- Lung Cancer:First-line PD-1 combination protocols have transformed standard of care for advanced disease. FDA breakthrough therapy designations have compressed development timelines for novel agents in this indication.
- Skin Cancer:Melanoma served as the initial proving ground for checkpoint inhibitor efficacy and maintains high immunotherapy penetration. United States dermatology-oncology crossover practices drive continued protocol innovation.
Commercial maturity centers on solid tumors. Steepest expansion trajectory is appearing in hematologic malignancies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing clusters in Massachusetts and California anchor the America Cancer Immunotherapy Market's supply-side infrastructure, with viral vector production capacity concentrating around established pharmaceutical corridors.
United States
Academic medical centers in Boston and Houston drive demand for CAR-T cell therapies and bispecific antibodies. FDA breakthrough therapy designations compress development timelines for novel checkpoint inhibitors. The Research Triangle Park in North Carolina anchors contract manufacturing organization concentration for viral vector production.
Brazil
Private oncology clinic networks in São Paulo and Rio de Janeiro expand infusion center capacity for PD-1 inhibitor administration. ANVISA regulatory harmonization with FDA standards accelerates parallel approval pathways for immunotherapy agents. The São Paulo metropolitan corridor anchors diagnostic-therapeutic bundling procurement relationships.
Canada
Provincial health technology assessment bodies in Ontario and Quebec determine reimbursement thresholds for novel immunotherapy combinations. Health Canada biologics licensing pathways align with FDA accelerated approval frameworks. The Toronto-Waterloo biotech corridor anchors immuno-oncology research facility concentration.
Mexico
COFEPRIS regulatory alignment with FDA standards enables faster market entry for subcutaneous checkpoint inhibitor formulations. Private payer expansion in Mexico City and Monterrey drives oncology clinic infrastructure investment. The Mexico City metropolitan area anchors cold-chain distribution network development for temperature-sensitive biologics.
America Cancer Immunotherapy Market Competitive Landscape
Global majors compete with regional champions across integrated diagnostic-therapeutic platforms and manufacturing scale. The market structure concentrates revenue among vertically integrated biopharmaceutical conglomerates with companion diagnostic capabilities. Three archetypes dominate: checkpoint inhibitor specialists with established PD-1 franchises, cell therapy developers with captive manufacturing infrastructure, and diagnostic-therapeutic integrators leveraging testing networks. Competitive intensity manifests through manufacturing capacity expansion and strategic partnerships for biomarker co-development.
Among established pharmaceutical conglomerates, Merck & Co., Inc. and Bristol-Myers Squibb occupy positions exemplifying checkpoint inhibitor market concentration through PD-1 blockade franchises. Roche represents the diagnostic-therapeutic integration archetype, anchoring competitive positioning through companion test bundling. These three entities exemplify the scale-driven tier where manufacturing infrastructure and regulatory expertise create defensive positioning against biosimilar entry.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb |
| Roche (F. Hoffmann-La Roche Ltd) |
| AstraZeneca |
| Amgen Inc. |
| Eli Lilly and Company |
| Pfizer Inc. |
| Johnson & Johnson |
| Novartis AG |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery networks in the United States concentrate procurement volume for checkpoint inhibitors, anchoring a value-based pricing model where outcomes data determines contract tier placement and rebate structures. This buyer concentration enables manufacturers to bundle companion diagnostics with therapeutic access, while Brazil's private oncology clinic networks negotiate separate price-volume arrangements without diagnostic bundling requirements.
Pricing Analysis
Companion diagnostic bundling distinguishes premium-tier contracts from unbundled standard arrangements where testing costs fall to separate laboratory budgets. Price differentiation hinges on FDA breakthrough therapy designation status and volume commitments from integrated delivery networks. Cost compression in the cytokine segment intensifies as Brazilian and Mexican infusion centers expand, eroding historical hospital premiums. Oncology clinics demonstrate highest price sensitivity due to thin operating margins, while academic medical centers prioritize clinical efficacy over per-dose expenditure.
Supply Chain Analysis
Aseptic processing technician shortages in Massachusetts and North Carolina constrain viral vector production scale-up for CAR-T therapies. Cell-line development capacity concentrates in the United States, Switzerland, and Singapore, with plasmid DNA and lentiviral vector production drawing from specialized contract manufacturing organizations. Single-source vulnerability pervades cold-chain logistics for mRNA-based therapeutic vaccines, where temperature excursion risks invalidate entire production lots. Distribution runs through hospital-owned specialty pharmacies and third-party logistics providers with validated cold-chain credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The America Cancer Immunotherapy Market sits in a modality-transition phase, with bispecific T-cell engagers and subcutaneous checkpoint inhibitor formulations displacing intravenous monoclonal antibody protocols that dominated prior treatment paradigms.
For Market Incumbents: Hedge manufacturing concentration risk by diversifying aseptic processing capacity across multiple North American contract manufacturing organization sites, insulating against workforce scarcity disruptions. Secure companion diagnostic co-development partnerships to defend formulary positioning against biosimilar entry, leveraging FDA accelerated approval pathway expertise as a regulatory moat.
For New Entrants and Emerging Players: COFEPRIS alignment with FDA standards in Mexico opens a window for subcutaneous formulation market entry before established players complete local registration. Target private oncology clinic networks in São Paulo and Monterrey with outpatient administration protocols, bypassing hospital procurement complexity through direct specialist engagement.
For Investors and Strategic Acquirers: The window for entry favors cell therapy developers with captive manufacturing infrastructure and validated cold-chain distribution partnerships. Monitor FDA guidance on biosimilar interchangeability standards as the inflection indicator for follow-on biologics portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA breakthrough therapy designation compresses timelines when paired with validated biomarker platforms. |
| Subcutaneous Formulation Development | Outpatient administration protocols expand community oncology access beyond hospital infusion centers. |
| Cold-Chain Infrastructure Investment | Temperature-controlled distribution networks enable mRNA-based therapeutic vaccine commercial scale-up. |
| Regulatory Harmonization Pursuit | COFEPRIS alignment with FDA standards accelerates parallel approval pathways in Mexico. |
| Real-World Evidence Framework Adoption | FDA post-approval efficacy guidance enables label expansion through observational data collection. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings in this study. Primary interviews with payer access specialists and oncology clinic administrators combined with secondary validation from FDA filings, ClinicalTrials.gov records, CMS Medicare reimbursement databases, and hospital procurement systems. Bottom-up patient-volume modeling and top-down revenue triangulation anchored segmentation outputs across treatment line, administration route, and regional regulatory clusters.
Comparable-period anchoring to historical checkpoint inhibitor adoption curves informed the projection horizon, with analytical frameworks modeling technology platform, care delivery setting, and disease indication dimensions. CAGRs derived from patient population growth, protocol penetration rates, and pricing trajectory assumptions, incorporating CAR-T manufacturing capacity expansion and biosimilar entry timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for bispecific antibody engineering would alter the outlook. Forecasts reflect assumptions about FDA accelerated approval pathway stability and CMS reimbursement policy continuity. Material deviation in regulatory guidance timelines or manufacturing workforce availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Thymus Cancer Market
Oncology
Esophageal Cancer Market
Oncology
Outpatient Oncology Infusion Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
North America Veterinary Oncology Market
Oncology
AI in Oncology Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Global Proton Therapy Market
Oncology
Global Non-Small Cell Lung Cancer (NSCLC) Market
Oncology
Oncology Devices Market
Oncology
US Veterinary Oncology Market
Oncology
Solid Tumor Market
Oncology
Stomach Cancer Treatment Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Osteosarcoma Market