
 South America Ovarian Cancer Diagnostics and Therapeutics Market | 2026-2036
South America Ovarian Cancer Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Ovarian Cancer Diagnostics and Therapeutics Market Analytics
The capital-intensity divergence between molecular diagnostics platforms and conventional imaging is rotating competitive investment toward next-generation sequencing capabilities in the region. F. Hoffmann-La Roche Ltd leverages its established immunoassay infrastructure to sustain laboratory partnerships across Brazilian diagnostic networks. AstraZeneca plc anchors its position through targeted therapy portfolios aligned with PARP inhibitor expansion in South American oncology protocols. Bristol-Myers Squibb Company competes via immunotherapy development programs addressing platinum-resistant patient populations.
South America ovarian cancer diagnostics and therapeutics encompasses CA-125 blood testing, transvaginal ultrasound imaging, CT/MRI staging protocols, platinum-based chemotherapy regimens, PARP inhibitor maintenance therapy, and immune checkpoint blockade for epithelial ovarian malignancies, with functional parameters centered on early-stage detection sensitivity and progression-free survival intervals. Diagnostic kits and imaging systems constitute the established revenue base, while targeted therapies represent the fastest-expanding margin pool driven by biomarker-guided patient stratification. Molecular diagnostics technology leads investment allocation as laboratories adopt next-generation sequencing for BRCA mutation profiling and homologous recombination deficiency assessment.
ANVISA governs oncology drug registration and clinical trial conduct in Brazil, while Argentina's national pharmaceutical regulator oversees import licensing and bioequivalence requirements for diagnostic reagents. ANVISA's accelerated review pathway for orphan oncology indications compresses time-to-market for novel therapeutics, directly shaping manufacturer prioritization of South American regulatory submissions. Stakeholders must monitor evolving reimbursement negotiations between national health systems and targeted therapy manufacturers, as access expansion depends on risk-sharing agreements and outcome-based contracting frameworks.
Market Dynamics
ANVISA's accelerated orphan drug pathway is compressing registration timelines and redirecting R&D investment toward Brazil, while hospital consolidation across the southeastern corridor concentrates purchasing power among fewer oncology departments.
Growth Catalysts
- ANVISA Accelerated Review:The regulatory pathway compresses time-to-market for novel therapeutics, incentivizing manufacturers to prioritize Brazilian submissions over other regional markets.
- Next-Generation Sequencing Adoption:Laboratory networks in São Paulo and Rio de Janeiro are integrating BRCA mutation profiling and homologous recombination deficiency assessment into standard diagnostic protocols.
- Hospital Consolidation:Southeastern Brazil's oncology departments are merging procurement functions, creating centralized demand pools for molecular diagnostics platforms.
Market Restraints
- Reagent Import Dependency:Argentina's national pharmaceutical regulator imposes extended bioequivalence requirements on diagnostic kits, creating supply bottlenecks for transvaginal ultrasound contrast agents.
- Specialized Pathologist Shortage:Brazil's southeastern corridor lacks sufficient trained personnel to interpret homologous recombination deficiency assays at scale.
- Platinum Supply Concentration:Chemotherapy regimen costs fluctuate with concentrated global platinum refining capacity, squeezing margin pools for first-line treatment protocols.
Strategic Opportunities
- Argentina's Underserved Interior:Provincial hospital networks outside Buenos Aires remain underpenetrated for PARP inhibitor maintenance therapy, presenting expansion corridors for risk-sharing agreements.
- Telepathology Integration:Remote diagnostic consultation platforms are converging with cloud-based imaging archives, enabling centralized BRCA interpretation across dispersed laboratory networks.
- Outcome-Based Contracting:Brazilian national health system negotiations are piloting progression-free survival guarantees for targeted therapy reimbursement, opening novel pricing frameworks.
Industry Challenges
- Molecular Diagnostics Certification:ANVISA's evolving validation requirements for next-generation sequencing platforms create unpredictable compliance timelines for laboratory accreditation.
- Immunohistochemistry Standardization:Discordant PD-L1 scoring protocols across Brazilian reference laboratories complicate patient stratification for immune checkpoint blockade enrollment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Ovarian Cancer Diagnostics and Therapeutics Market |
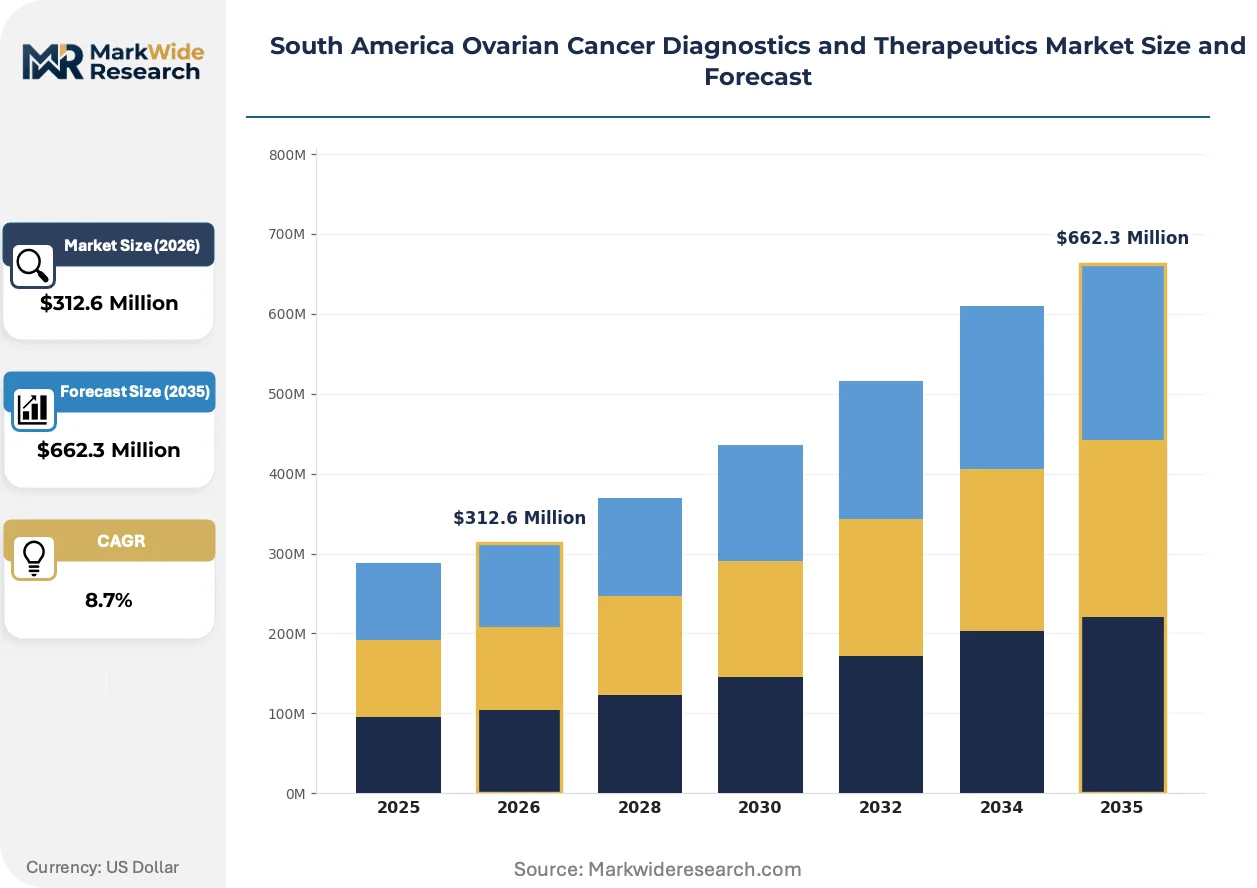
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Imaging Systems, Chemotherapy Drugs, Targeted Therapies Technology: Molecular Diagnostics, Imaging Techniques, Immunotherapy, Biomarker Analysis End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Delivery Mode: Intravenous, Oral, Parenteral, Intraperitoneal |
| Companies Covered | Eli Lilly and Company, Siemens AG, AstraZeneca plc, F. Hoffmann-La Roche Ltd, Boehringer Ingelheim GmbH, GlaxoSmithKline plc, Johnson & Johnson, Bristol-Myers Squibb Company, Siemens Healthineers, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Ovarian Cancer Diagnostics and Therapeutics Market Evolving Landscape
Liquid biopsy platforms are disrupting tissue-based mutation profiling workflows, while regulatory harmonization pressures and shifting hospital procurement authority reshape competitive positioning across the region.
Next-generation sequencing-based circulating tumor DNA analysis is supplanting surgical tissue biopsy as the primary modality for BRCA mutation detection in platinum-resistant patient populations. Hospital-based oncology departments in São Paulo's metropolitan network are adopting these platforms at accelerated cadence. The technology is compressing diagnostic turnaround times from weeks to days, enabling faster treatment initiation and expanding addressable patient pools for PARP inhibitor therapy.
ANVISA's orphan oncology designation framework is streamlining clinical trial conduct requirements for targeted therapeutics addressing epithelial ovarian malignancies. Manufacturers are restructuring regulatory submission strategies to exploit compressed review windows. The accelerated pathway most directly affects PARP inhibitor and immune checkpoint blockade categories, where sponsors are front-loading Brazilian dossiers ahead of other Latin American markets.
Hospital procurement authority is migrating from individual department heads to centralized pharmacy and therapeutics committees across Brazil's southeastern corridor. Academic medical centers in Rio de Janeiro are consolidating molecular diagnostics purchasing through shared service organizations, displacing direct manufacturer-laboratory relationships. This concentration is most visible in São Paulo state's public hospital network, where committee-driven tender processes now govern next-generation sequencing platform selection.
South America Ovarian Cancer Diagnostics and Therapeutics Market Segmentation
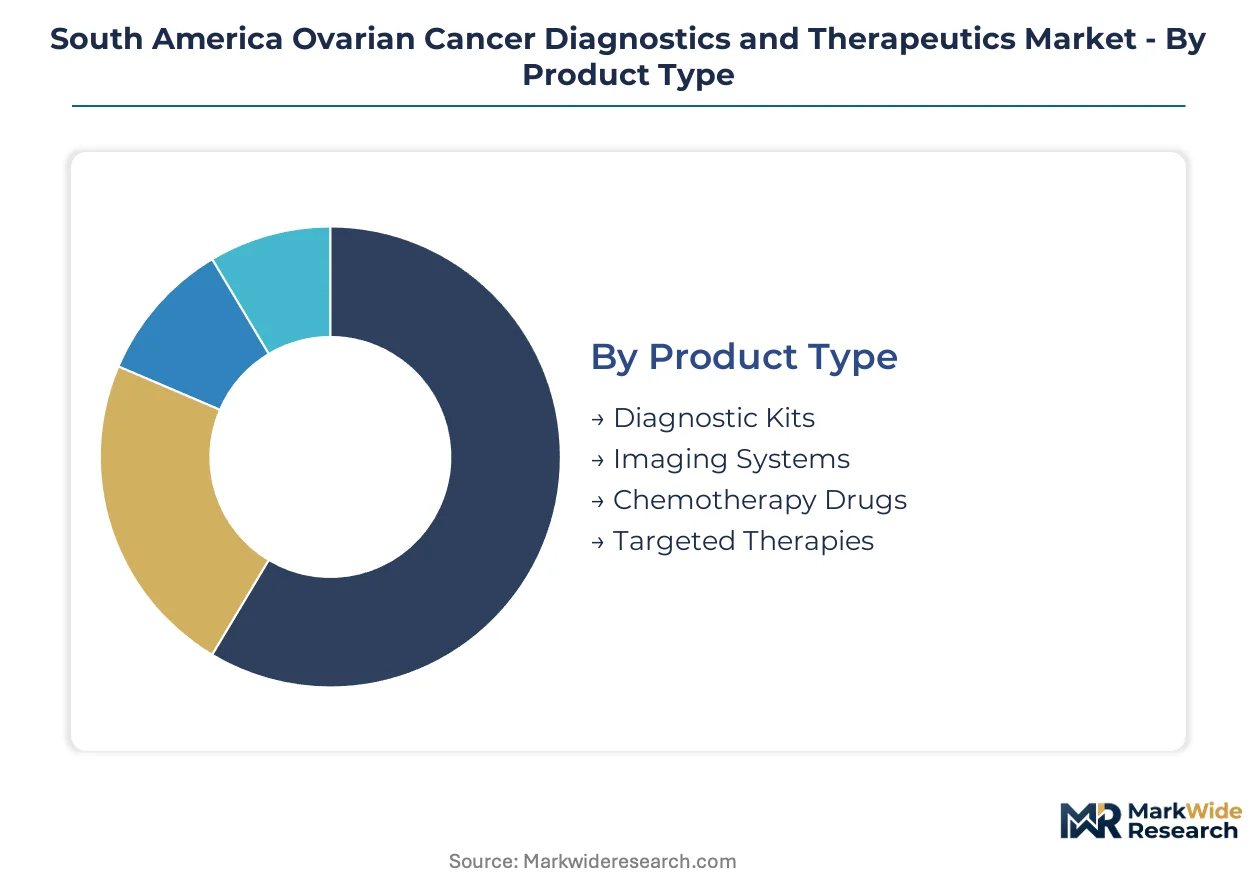
Segmentation in South America ovarian cancer care reflects divergent investment priorities across diagnostic and therapeutic modalities. Hospital procurement committees in Brazil's southeastern corridor are reshaping demand patterns through centralized purchasing authority.
Product Type:
Imaging Systems face acute substitution pressure from liquid biopsy platforms and next-generation sequencing workflows that compress diagnostic timelines.
- Diagnostic Kits:Encompass CA-125 immunoassays, HE4 biomarker panels, and BRCA mutation profiling reagents. São Paulo's consolidated laboratory networks are standardizing kit procurement through multi-year supply agreements with centralized quality validation.
- Targeted Therapies:PARP inhibitors and angiogenesis inhibitors command premium reimbursement positioning. ANVISA's accelerated orphan drug pathway is compressing registration timelines for these agents, redirecting manufacturer prioritization toward Brazilian submissions.
- Imaging Systems:Transvaginal ultrasound and CT/MRI staging platforms anchor hospital capital budgets across Argentina's metropolitan centers.
- Chemotherapy Drugs:Platinum-based regimens and taxane combinations constitute first-line protocol standards throughout the region's public health systems.
Diagnostic Kits anchors the volume base while Targeted Therapies gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive platform investments from consumable-driven recurring revenue models.
- Molecular Diagnostics:Next-generation sequencing and circulating tumor DNA analysis enable BRCA mutation detection and homologous recombination deficiency assessment. Rio de Janeiro's academic medical centers are consolidating platform procurement through shared service organizations, displacing direct manufacturer relationships.
- Biomarker Analysis:PD-L1 scoring and tumor mutational burden quantification guide patient stratification for immune checkpoint blockade enrollment. Discordant interpretation protocols across Brazilian reference laboratories complicate standardized clinical adoption.
- Imaging Techniques:Contrast-enhanced ultrasound and functional MRI protocols support surgical planning and treatment response monitoring.
- Immunotherapy:Checkpoint inhibitors addressing platinum-resistant populations require specialized cold-chain logistics and infusion infrastructure.
Imaging Techniques commands the installed base while Molecular Diagnostics expands most quickly.
End User:
Customer type concentration is rotating purchasing authority from individual department heads toward centralized pharmacy and therapeutics committees.
- Hospitals:Oncology departments in Brazil's southeastern corridor—spanning São Paulo and Rio de Janeiro—concentrate demand for both diagnostic platforms and infused therapeutics. Hospital consolidation is merging procurement functions, creating volume pools that reshape vendor negotiation dynamics.
- Diagnostic Laboratories:Independent and hospital-affiliated labs process biomarker assays and molecular profiling requests. Argentina's national pharmaceutical regulator imposes extended bioequivalence requirements on imported reagents, creating supply bottlenecks for specialized testing menus.
- Clinics:Outpatient oncology centers in Buenos Aires and Santiago manage maintenance therapy administration and surveillance monitoring.
- Research Institutions:Academic centers conduct clinical trials for novel therapeutics under ANVISA's streamlined oncology framework.
Hospitals dominate absolute spending while Diagnostic Laboratories capture the steepest expansion trajectory.
Delivery Mode:
Application requirements dictate route selection based on pharmacokinetic profiles and treatment setting infrastructure.
- Intravenous:Platinum agents and taxanes require infusion center capacity with nursing specialization. Brazil's public hospital network maintains extensive IV chemotherapy infrastructure across state-level health systems.
- Oral:PARP inhibitor maintenance therapy enables outpatient administration, expanding addressable patient pools beyond infusion-capable centers. Argentina's provincial hospital networks outside Buenos Aires remain underpenetrated for these agents.
- Parenteral:Subcutaneous formulations reduce infusion chair time and nursing resource requirements.
- Intraperitoneal:Regional chemotherapy delivery demands surgical oncology expertise concentrated in tertiary referral centers.
Intravenous maintains protocol dominance while Oral delivery climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across South America's ovarian cancer market. Brazil's southeastern hospital corridor absorbs premium-priced targeted therapies with minimal price resistance, while Argentina's provincial networks and Chile's public health system exhibit acute sensitivity to out-of-pocket costs for PARP inhibitor maintenance protocols.
Brazil
ANVISA's accelerated orphan drug pathway compresses registration timelines for novel therapeutics, redirecting manufacturer prioritization toward Brazilian submissions ahead of other regional markets. São Paulo's consolidated laboratory networks standardize kit procurement through multi-year supply agreements with centralized quality validation. Rio de Janeiro's academic medical centers are consolidating molecular diagnostics purchasing through shared service organizations, displacing direct manufacturer-laboratory relationships.
Argentina
The national pharmaceutical regulator imposes extended bioequivalence requirements on imported diagnostic reagents, creating supply bottlenecks for transvaginal ultrasound contrast agents and specialized testing menus. Provincial hospital networks outside Buenos Aires remain underpenetrated for PARP inhibitor maintenance therapy, presenting expansion corridors for risk-sharing agreements and outcome-based contracting frameworks.
Chile
Public health system reimbursement negotiations for targeted therapies concentrate purchasing authority within centralized pharmacy and therapeutics committees. Santiago's tertiary referral centers anchor demand for platinum-based chemotherapy regimens and immune checkpoint blockade protocols. The metropolitan oncology network is piloting telepathology integration with cloud-based imaging archives to enable centralized BRCA interpretation.
Colombia
Bogotá's hospital-based oncology departments are expanding screening programs for high-risk patient cohorts, driving demand for CA-125 immunoassays and HE4 biomarker panels. The national health system is negotiating risk-sharing agreements with targeted therapy manufacturers to expand access expansion beyond infusion-capable centers. Regional laboratories face certification delays under evolving validation requirements for next-generation sequencing platforms.
South America Ovarian Cancer Diagnostics and Therapeutics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in South America's ovarian cancer diagnostics and therapeutics market. The upper tier comprises multinational pharmaceutical and diagnostics conglomerates with established immunoassay infrastructure and targeted therapy portfolios. Mid-tier specialists concentrate on molecular diagnostics platforms and biomarker analysis reagents. The dominant competitive moves involve strategic partnerships with consolidated hospital procurement committees and technology licensing agreements for next-generation sequencing capabilities.
Among the integrated pharmaceutical leaders, AstraZeneca plc and Bristol-Myers Squibb Company occupy positions anchored in targeted therapy and immunotherapy development respectively. F. Hoffmann-La Roche Ltd exemplifies the diagnostics-dominant archetype through its sustained laboratory partnerships across Brazilian diagnostic networks. These three entities represent the competitive core around which regional market dynamics organize.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Siemens AG |
| AstraZeneca plc |
| F. Hoffmann-La Roche Ltd |
| Boehringer Ingelheim GmbH |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
Liquid biopsy reagent substitution for tissue-based BRCA mutation profiling is redrawing procurement geography across Brazil's southeastern laboratory corridor while compressing per-test economics for molecular diagnostics platforms. ANVISA's evolving validation requirements for next-generation sequencing workflows simultaneously extend supplier certification timelines and concentrate purchasing leverage among consolidated hospital networks in São Paulo and Rio de Janeiro.
Pricing Analysis
Service contract extensions and preventive maintenance agreements for sequencing platforms anchor lifetime value capture for molecular diagnostics vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies based on assay throughput commitments and bioinformatics support tiers. Pricing pressure stems from centralized pharmacy committee negotiations in Brazil's public hospital network, which are piloting progression-free survival guarantees. Academic medical centers exhibit lowest price sensitivity due to research funding offsets, while provincial diagnostic laboratories in Argentina's interior face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of platinum-based chemotherapy agents dominates inventory posture given concentrated global refining capacity and treatment protocol inflexibility. Active pharmaceutical ingredient sourcing draws from India, China, and Switzerland for PARP inhibitor synthesis, while diagnostic reagent manufacturing concentrates in Germany, the United States, and Singapore. Single-source vulnerability sits with specialized oligonucleotide suppliers for BRCA probe synthesis. Distribution runs through cold-chain logistics providers with oncology infusion center partnerships across Brazil's state-level health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent molecular diagnostics platforms face substitution pressure from cloud-based telepathology networks that centralize BRCA interpretation and displace distributed laboratory relationships. Defense requires anchoring around workflow integration depth rather than hardware installed base alone.
For Market Incumbents: Compound defensive positioning through backward integration into bioinformatics software development and captive supply of homologous recombination deficiency assay reagents. Secure multi-year exclusive service contracts with São Paulo's consolidated laboratory networks before centralized procurement committees complete vendor rationalization. Threat vector: cloud-native diagnostic platforms with AI-assisted pathology scoring. For New Entrants and Emerging Players: Lead with telepathology-enabled BRCA interpretation services targeting Argentina's provincial hospital networks outside Buenos Aires, where specialized pathologist shortage creates immediate workflow gaps. White-space opportunity concentrates in oral PARP inhibitor maintenance therapy distribution to outpatient oncology centers lacking infusion infrastructure. Go-to-market angle: risk-sharing agreements with provincial health systems tied to treatment response metrics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed molecular diagnostics platform providers with established ANVISA certification but limited geographic expansion beyond Brazil's southeastern corridor. Five-to-ten year viability hinges on successful integration of liquid biopsy capabilities and telepathology service layers. Acquisition signal: ANVISA approval of cloud-based diagnostic interpretation platforms enabling cross-border laboratory consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Accelerated Pathway Submission | Compresses time-to-market for PARP inhibitors ahead of regional competitors. |
| Hospital System Partnership | Locks in multi-year supply agreements with São Paulo's consolidated procurement committees. |
| Telepathology Platform Integration | Enables centralized BRCA interpretation across Argentina's dispersed provincial networks. |
| Reimbursement Strategy Development | Structures progression-free survival guarantees with Brazilian national health system negotiators. |
| Pipeline Diversification | Expands homologous recombination deficiency assay menu beyond BRCA mutation profiling. |
Research Methodology
Desk research of ANVISA regulatory filings, ClinicalTrials.gov oncology trial registries, and Brazilian national health system procurement databases preceded structured interviews with hospital pharmacy directors, molecular diagnostics laboratory managers, regulatory affairs specialists at orphan drug sponsors, and provincial health system administrators across Argentina and Chile. Bottom-up sizing of diagnostic kit volumes and therapeutic patient flows triangulated against top-down health expenditure allocations by oncology indication.
Variance decomposition across product type, technology platform, end-user facility tier, and delivery mode segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from treatment protocol adoption curves, biomarker-guided patient stratification penetration rates, and regulatory approval timeline assumptions. Forecast inputs incorporated ANVISA review pathway throughput estimates and hospital consolidation trajectory modeling for Brazil's southeastern corridor.
Underlying assumptions cover stable ANVISA orphan oncology pathway processing capacity and sustained platinum supply chain continuity, with deviation risk concentrated in molecular diagnostics certification timeline extensions and Argentina's import licensing volatility for specialized reagents. Practitioners should keep alternative scenarios live as telepathology reimbursement frameworks and outcome-based contracting pilot results evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market