
 Personalized Medicine Biomarkers Market | 2026-2036
Personalized Medicine Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized Medicine Biomarkers Market Intelligence
Hospital-based precision oncology programs is bifurcating demand away from traditional reference laboratory models. Abbott Laboratories leverages its point-of-care infrastructure to anchor clinical biomarker testing in decentralized settings. Thermo Fisher Scientific sustains R&D intensity across next-generation sequencing platforms and companion diagnostic development. Illumina dominates the sequencing instrument installed base, which shapes how laboratories adopt biomarker workflows.
Personalized medicine biomarkers are molecular indicators—encompassing genomic variants, protein expression profiles, and metabolite signatures—measured through validated analytical platforms to predict drug response, stratify patient risk, or diagnose disease subtypes. Their commercial purpose centers on enabling targeted therapeutic selection and reducing adverse drug reactions in clinical practice. Oncology applications command the deepest investment pools given companion diagnostic mandates for approved oncolytics, while neurology biomarker development is gaining velocity as blood-based assays for neurodegeneration advance toward regulatory submission. Reagents and consumables capture recurring revenue streams tied to platform utilization, whereas instruments require capital commitment cycles that concentrate purchasing decisions among large health systems and contract research organizations.
FDA's in vitro companion diagnostic guidance and EMA's biomarker qualification program collectively establish the evidentiary threshold for clinical adoption across major markets. ISO 13485 quality management standards and the EU In Vitro Diagnostic Regulation shape manufacturing compliance and market access pathways for assay developers. Stakeholders must monitor evolving payer coverage policies for liquid biopsy tests and anticipate how decentralized manufacturing requirements will reshape supply chain configurations for time-sensitive specimen processing.
Market Dynamics
FDA's in vitro companion diagnostic guidance compresses biomarker validation timelines, forcing assay developers to front-load clinical evidence generation before therapeutic approval submissions. This regulatory acceleration redistributes competitive advantage toward platforms with integrated CDx development capabilities.
Growth Catalysts
- Companion diagnostic mandates:FDA requirements for approved oncolytics create automatic demand pull for co-developed biomarker assays, embedding testing into standard-of-care protocols.
- Liquid biopsy advancement:Blood-based cfDNA and CTC detection technologies expand addressable patient populations beyond tissue biopsy limitations in metastatic disease monitoring.
- EMA biomarker qualification:The European pathway accelerates cross-border assay adoption by establishing evidentiary standards recognized across EU member states.
Market Restraints
- Capital intensity of NGS infrastructure:High-throughput sequencing platforms require seven-figure instrument investments that concentrate purchasing power among academic medical centers and large health systems.
- Reimbursement uncertainty:CMS coverage determinations for liquid biopsy tests lag FDA approvals, creating payment gaps that delay community laboratory adoption.
- Sample degradation logistics:Time-sensitive specimen processing requirements limit geographic reach of centralized reference laboratories, constraining rural market penetration.
Strategic Opportunities
- Neurology biomarker expansion:Blood-based assays for neurodegeneration advance toward regulatory submission, opening therapeutic areas beyond oncology with substantial unmet diagnostic need.
- Point-of-care decentralization:Abbott's point-of-care infrastructure anchors clinical biomarker testing in physician offices and community settings, bypassing hospital laboratory bottlenecks.
- ISO 13485 manufacturing compliance:Quality management certification opens EU market access pathways for assay developers seeking CE marking under IVDR requirements.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of computational biologists capable of variant interpretation and clinical report generation constrains laboratory scaling.
- IVDR transition complexity:EU regulatory reclassification of companion diagnostics intensifies notified body consultation requirements and extends certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Medicine Biomarkers Market |
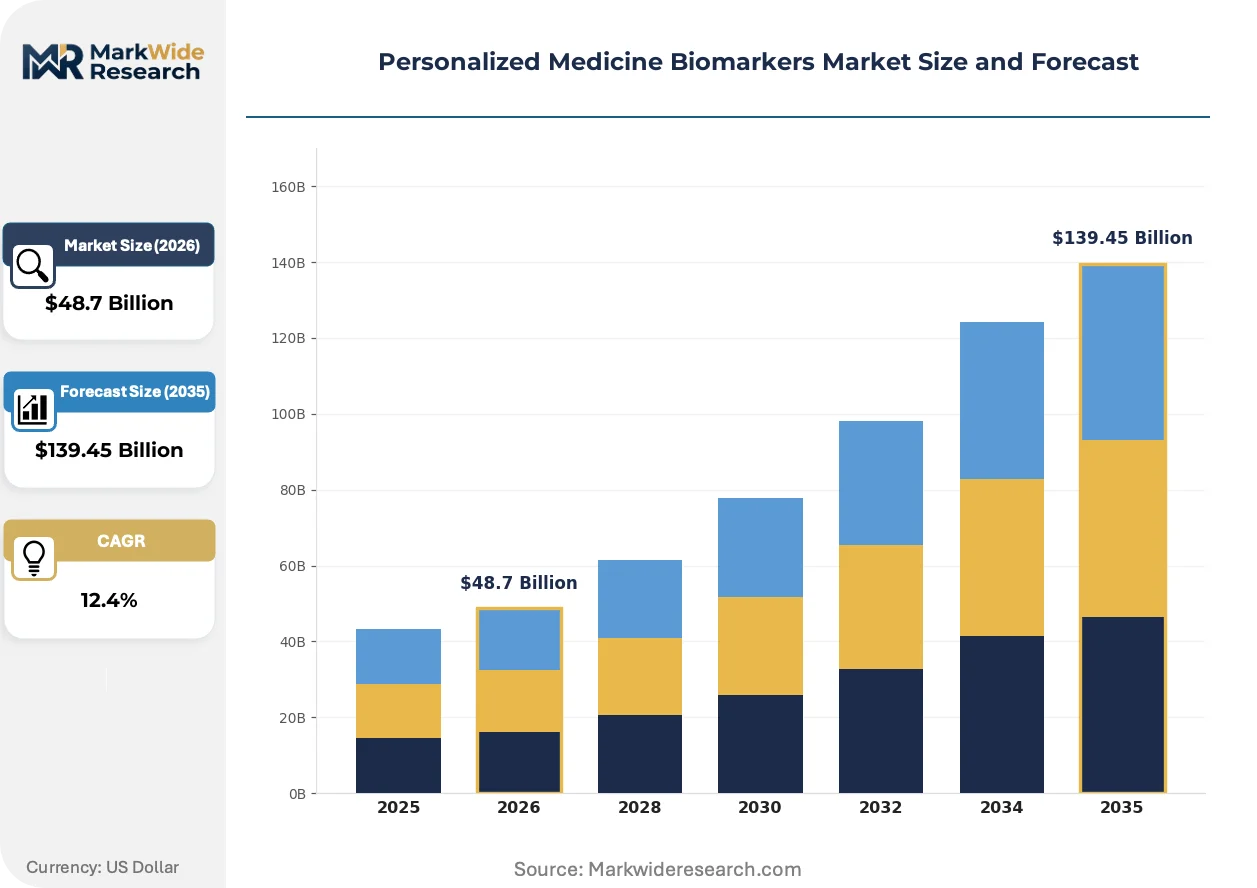
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $139.45 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Oncology, Neurology, Cardiovascular, Infectious Disease Technology: Next-Generation Sequencing, PCR, Mass Spectrometry, Microarrays End User: Pharmaceutical Companies, Diagnostic Laboratories, Research Institutes, Hospitals Product Type: Reagents, Services, Instruments, Software |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, F. Hoffmann-La Roche, Illumina, QIAGEN, Agilent Technologies, Bio-Rad Laboratories, Danaher, Guardant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Medicine Biomarkers Market Strategic Shifts & Innovations
Multi-omics integration and artificial intelligence-driven variant classification are compressing traditional biomarker discovery cycles, while decentralized testing models redistribute where clinical decisions occur.
Multiplexed proteomic profiling platforms simultaneously quantify hundreds of protein biomarkers from minimal sample volumes. Academic medical centers in the Boston-Cambridge corridor deploy these systems for immune-oncology patient stratification. This density of biomarker readouts is displacing single-analyte immunohistochemistry as the frontline diagnostic modality in precision oncology workflows.
EMA's biomarker qualification program establishes evidentiary standards that reduce redundant clinical validation requirements across EU member states. Assay developers leverage qualified biomarkers to streamline CE marking pathways under IVDR. Oncology applications command the deepest regulatory engagement, while neurology biomarker developers anticipate similar framework expansion for neurodegenerative indications.
Hospital-based precision oncology programs are consolidating biomarker testing decisions within integrated delivery networks. Community oncologists increasingly route specimens to in-house molecular pathology laboratories rather than independent reference laboratories. This channel concentration is most visible in United States metropolitan markets where health system mergers have created regional testing monopolies.
Personalized Medicine Biomarkers Market Segmentation
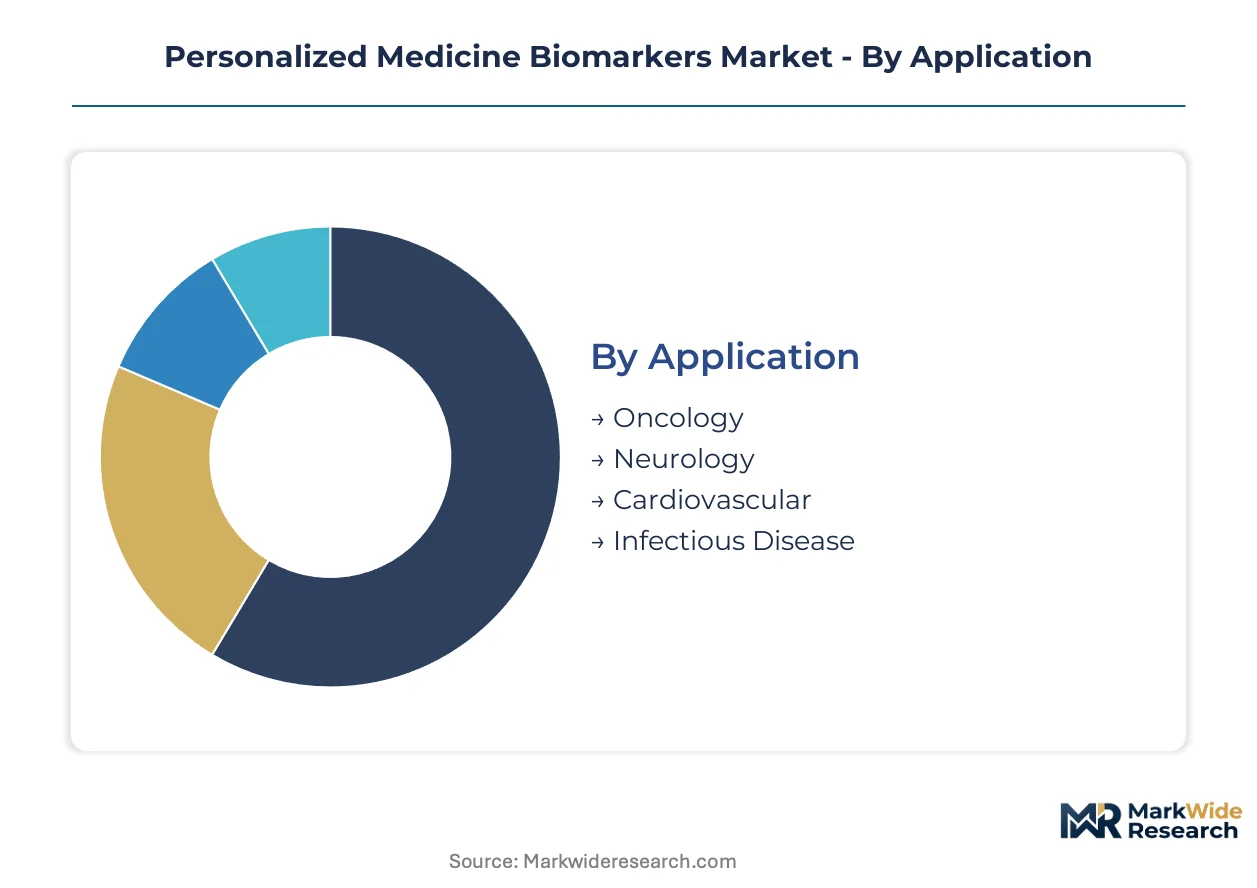
Biomarker market segmentation reveals distinct margin architectures across therapeutic applications and technology platforms. Understanding these divisions exposes where capital concentrates and which customer segments drive platform purchasing decisions.
Application:
Oncology commands the deepest margin pools within this category, driven by companion diagnostic mandates and high-value therapeutic selection decisions.
- Oncology:Companion diagnostic requirements for FDA-approved oncolytics embed biomarker testing into standard-of-care protocols. Academic medical centers in the Boston-Cambridge corridor deploy multiplexed platforms for immune-oncology patient stratification, capturing premium pricing through integrated therapeutic decision workflows.
- Neurology:Blood-based assays for neurodegeneration advance toward regulatory submission, opening therapeutic areas beyond oncology with substantial unmet diagnostic need. Research institutes concentrate demand here as pharmaceutical sponsors fund biomarker discovery for Alzheimer's and Parkinson's drug development pipelines.
- Cardiovascular:Protein biomarker panels stratify patient risk for anticoagulant selection and heart failure management. Diagnostic laboratories process high specimen volumes under established reimbursement codes.
- Infectious Disease:Host response biomarkers distinguish viral from bacterial infections, guiding antibiotic stewardship programs in hospital settings.
The dominant share belongs to Oncology, while Neurology is closing the gap fastest.
Technology:
Platform selection determines capital commitment cycles and recurring revenue durability across laboratory settings.
- Next-Generation Sequencing:High-throughput sequencing instruments require seven-figure investments that concentrate purchasing power among academic medical centers and large health systems. Illumina's installed base shapes how laboratories adopt comprehensive genomic profiling workflows for precision oncology.
- PCR:Established quantitative PCR platforms deliver rapid turnaround for known mutation detection at moderate instrument cost. Community hospital laboratories favor this technology for EGFR and KRAS testing where reimbursement pathways are mature.
- Mass Spectrometry:Proteomic and metabolomic profiling platforms quantify hundreds of analytes from minimal sample volumes. Research institutes deploy these systems for biomarker discovery rather than clinical diagnostics.
- Microarrays:Targeted genotyping arrays retain utility for pharmacogenomic screening in centralized reference laboratories processing high specimen volumes.
Oncology applications concentrate NGS demand, while PCR maintains volume leadership across broader testing menus.
End User:
Customer type dictates procurement scale and integration depth with therapeutic decision workflows.
- Pharmaceutical Companies:Drug sponsors co-develop companion diagnostics with assay developers, front-loading clinical evidence generation before therapeutic approval submissions. This segment drives R&D intensity across next-generation sequencing platforms and companion diagnostic development.
- Diagnostic Laboratories:Reference laboratories and hospital-based molecular pathology units process routine clinical specimens under established reimbursement frameworks. Contract research organizations supplement capacity for pharmaceutical-sponsored trials.
- Research Institutes:Academic laboratories advance biomarker discovery through grant-funded investigations, generating intellectual property rather than clinical revenue.
- Hospitals:Integrated delivery networks consolidate biomarker testing decisions within in-house molecular pathology laboratories, displacing independent reference laboratory routing.
Pharmaceutical companies anchor premium platform sales, while hospitals are consolidating testing volume fastest through vertical integration.
Product Type:
Revenue model durability varies sharply between consumable recurring streams and capital equipment cycles.
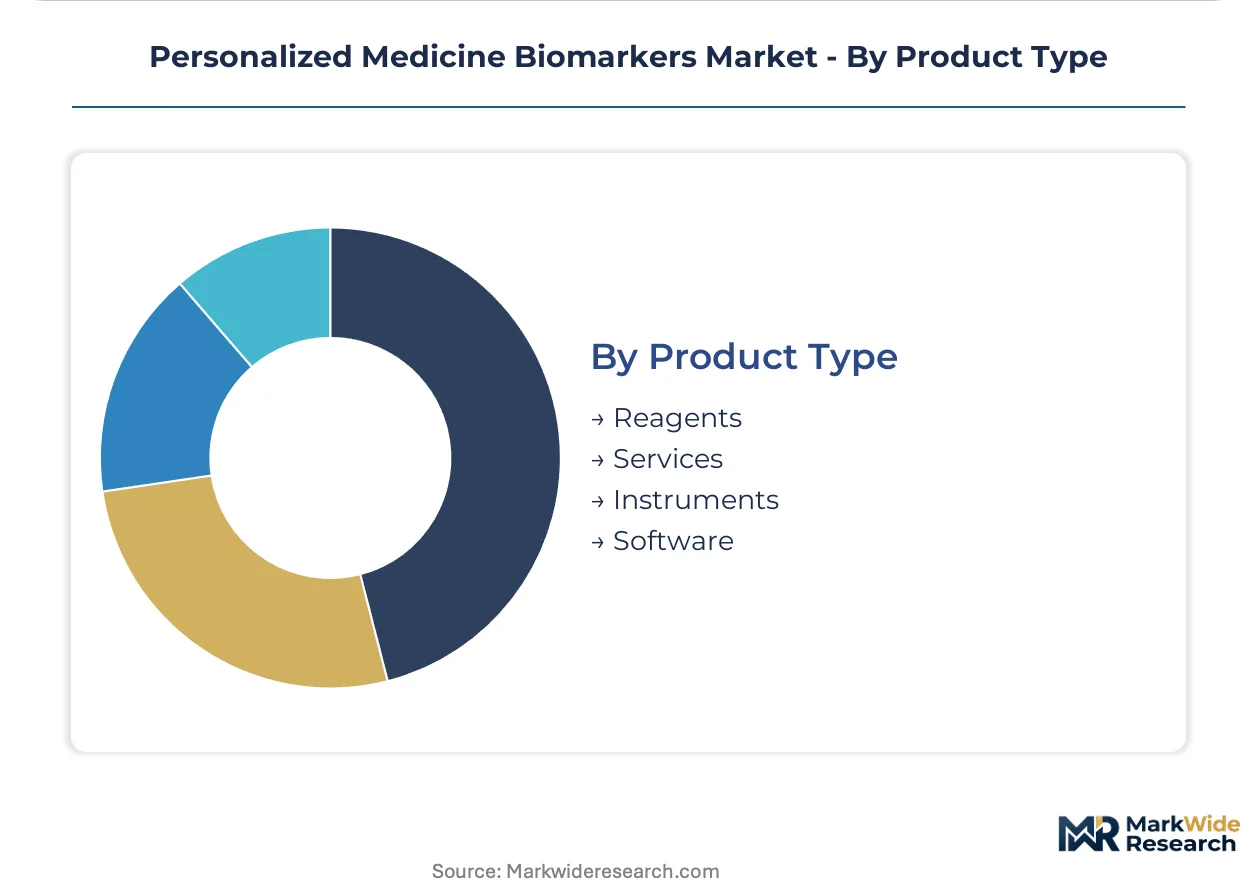
- Reagents:Consumables capture recurring revenue streams tied to platform utilization, with pull-through economics favoring integrated system vendors. ISO 13485 quality management certification opens EU market access pathways under IVDR requirements.
- Services:Contract testing and biomarker validation support pharmaceutical sponsors through regulatory submission timelines. Bioinformatics talent scarcity constrains laboratory scaling for variant interpretation and clinical report generation.
- Instruments:Capital equipment requires extended sales cycles and concentrated purchasing decisions among large health systems. Point-of-care decentralization is anchoring clinical biomarker testing in physician offices and community settings.
- Software:Bioinformatics pipelines and clinical decision support tools integrate variant classification with therapeutic recommendation engines.
Reagents command the dominant revenue share, while Services are expanding most quickly through pharmaceutical outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors United States biomarker infrastructure through its dense concentration of academic medical centers and sequencing instrument deployment. FDA companion diagnostic guidance accelerates validation timelines across this corridor. Venture capital flows concentrate in Massachusetts and California.
United States
FDA in vitro companion diagnostic mandates create automatic demand pull for co-developed biomarker assays across academic medical centers. The agency's guidance compresses validation timelines, forcing front-loaded clinical evidence generation. The Boston-Cambridge corridor deploys multiplexed proteomic platforms for immune-oncology stratification, displacing single-analyte workflows.
Germany
EMA biomarker qualification establishes evidentiary standards recognized across EU member states, streamlining assay adoption. ISO 13485 quality management certification opens market access under IVDR requirements. The Munich and Heidelberg clusters concentrate pharmaceutical-sponsored companion diagnostic development with integrated sequencing infrastructure.
China
NMPA regulatory pathways for innovative diagnostics expand domestic biomarker assay approval capacity. The country's national pharmaceutical regulator accelerates review timelines for oncology companion diagnostics. Shanghai and Beijing biotech parks attract multinational sequencing platform deployments for clinical trial support.
United Kingdom
NHS England coverage determinations for liquid biopsy tests shape community laboratory adoption patterns. The Medicines and Healthcare products Regulatory Agency aligns with EMA qualification pathways post-Brexit. The Cambridge-London corridor concentrates CRISPR-based diagnostic development with pharmaceutical partnership density.
Japan
PMDA biomarker qualification programs accelerate regulatory convergence with FDA and EMA standards. METI funding for precision medicine infrastructure expands sequencing capacity in university hospitals. The Tokyo-Osaka corridor concentrates companion diagnostic co-development with domestic pharmaceutical sponsors.
Personalized Medicine Biomarkers Market Key Industry Players
Concentration sits with diversified life science conglomerates and specialized sequencing platform vendors. The vendor base spans three tiers: integrated diagnostic systems providers, pure-play sequencing instrument manufacturers, and emerging liquid biopsy specialists. Strategic moves center on companion diagnostic co-development partnerships and point-of-care decentralization to bypass hospital laboratory bottlenecks.
Among diversified diagnostic systems providers, Abbott Laboratories and F. Hoffmann-La Roche occupy positions anchoring clinical biomarker testing in decentralized settings through point-of-care infrastructure. Thermo Fisher Scientific exemplifies the integrated platform archetype, sustaining R&D intensity across sequencing and companion diagnostic development. Illumina represents the sequencing-dominated specialist tier, with instrument installed base concentration shaping laboratory workflow adoption patterns across major health systems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Illumina |
| QIAGEN |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Danaher |
| Guardant Health |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day reagent lead times concentrate purchasing power among large health systems that can absorb inventory carrying costs, while smaller laboratories face spot-market premiums that erode margin capture on routine biomarker testing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification status and companion diagnostic co-development depth. Academic medical centers with integrated delivery networks command volume discounts exceeding forty percent off list for NGS consumables, while community hospital laboratories pay elevated per-test rates due to fragmented procurement. Price differentiation hinges on FDA premarket approval tier and after-sales bioinformatics support bundling. Cost compression in the standard tier is intensifying because reference laboratories are consolidating purchasing through group purchasing organizations. Pharmaceutical sponsors exhibit the lowest price sensitivity due to regulatory timeline imperatives, whereas independent diagnostic laboratories face acute margin pressure from reimbursement lag.
Supply Chain Analysis
The United States and Germany anchor sequencing instrument manufacturing and companion diagnostic kit production, while China supplies oligonucleotide synthesis and plastic consumable molding at scale. Critical dependencies include fluorophore chemistries from Japanese specialty chemical producers, semiconductor components for flow cell fabrication from Taiwanese foundries, and stabilized enzyme formulations from Danish biotechnology suppliers. Single-source vulnerability concentrates in Illumina's proprietary sequencing reagent ecosystem, where locked consumable contracts tether laboratories to sole-source supply. Distribution runs through authorized distributor networks for capital equipment, with direct-to-laboratory fulfillment dominating high-velocity reagent replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid biopsy platforms threaten tissue-based companion diagnostic incumbents with sample-type substitution that could disintermediate centralized pathology workflows within the next decade.
For Market Incumbents: Compound defensive moats through backward integration into stabilized reagent manufacturing and captive bioinformatics talent pipelines. Thermo Fisher Scientific's integrated platform architecture demonstrates how controlling consumable supply insulates margin capture from spot-market volatility. Defensive patent thickets around variant interpretation algorithms raise switching costs for hospital laboratory customers. Priority investment in point-of-care decentralization bypasses emerging liquid biopsy specialists before they establish physician-office channel control. For New Entrants and Emerging Players: Differentiate on neurology biomarker assay menus where regulatory pathways remain uncongested and pharmaceutical sponsor funding concentrates. Blood-based neurodegeneration diagnostics represent the most penetrable application segment, with Alzheimer's drug development pipelines creating automatic demand pull. Target research institute channels for initial revenue traction before pursuing clinical laboratory certification. Go-to-market execution should emphasize grant-funded discovery collaborations that generate intellectual property without immediate reimbursement dependency. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core diagnostic assets amid portfolio rationalization pressures. Mid-cap assay developers with EMA biomarker qualification progress and ISO 13485 certification offer near-term EU market access without full IVDR transition burden. Long-term viability rests on companion diagnostic co-development pipeline depth rather than standalone test menu breadth. The signal to watch is CMS national coverage determination timing for multi-cancer early detection assays, which would validate liquid biopsy economics at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA submission timelines for oncology therapeutics embed assay validation into drug approval pathways. |
| Point-of-Care Decentralization Investment | Abbott's infrastructure anchors testing in physician offices, bypassing hospital laboratory bottlenecks. |
| ISO 13485 Manufacturing Certification | Quality management certification opens EU market access under IVDR reagent import requirements. |
| Liquid Biopsy Regulatory Submission | cfDNA assay approvals expand addressable populations beyond tissue biopsy limitations. |
| Multi-Omics Platform Integration | Proteomic-genomic convergence compresses biomarker discovery cycles for immune-oncology stratification. |
Research Approach
Initial hypotheses were tested against primary input from companion diagnostic development executives, hospital molecular pathology directors, regulatory affairs specialists at sequencing platform vendors, and payer coverage policy leads, then refined against FDA 510(k) and PMA filing databases, EMA qualification procedure records, ClinicalTrials.gov biomarker endpoint registrations, and CMS national coverage determination documents. Bottom-up triangulation across laboratory instrument installed base estimates and top-down reconciliation against pharmaceutical R&D expenditure allocations validated segment-level demand projections.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each biomarker application segment. The analytical framework models therapeutic area penetration, technology platform substitution curves, end-user procurement consolidation patterns, and product-type revenue mix shifts. CAGRs were derived from instrument placement run-rates and consumable pull-through economics calibrated to reimbursement pathway maturity. Forecast inputs include companion diagnostic approval velocity, liquid biopsy coverage expansion trajectories, and IVDR implementation compliance costs.
Decision-makers should treat outputs as directional under assumptions of stable FDA-EMA regulatory convergence and sustained pharmaceutical sponsor R&D intensity; material deviation in reimbursement policy or diagnostic regulatory reclassification would warrant model refresh. Recalibration cycles align with material shifts in CMS coverage determinations, companion diagnostic approval milestones, and sequencing platform technology transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market