
 Retroperitoneal Fibrosis Treatment Market | 2026-2036
Retroperitoneal Fibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Retroperitoneal Fibrosis Treatment Market Analytics
Consolidation among tertiary hospital systems is repositioning procurement leverage toward integrated delivery networks. Novartis leverages its transplant immunology portfolio to anchor contract positioning with these consolidated buyers. Bristol-Myers Squibb competes through its established autoimmune franchise, while Roche specializes in diagnostic-guided patient stratification for therapy selection.
Retroperitoneal fibrosis treatment encompasses pharmacological and surgical management of inflammatory tissue proliferation encasing the abdominal aorta and ureters, with corticosteroid taper protocols and ureterolysis procedures representing the standard therapeutic continuum. The primary purpose centers on ureteral decompression and renal function preservation. Corticosteroids dominate current prescribing patterns as the established first-line pharmacologic intervention, while immunotherapy segments capture accelerating interest from payers seeking durable remission with reduced steroid exposure. Surgical intervention retains concentrated margin pools in complex bilateral obstruction cases managed at academic medical centers.
FDA orphan drug incentives and EMA's priority medicines framework shape development incentives for novel biologics targeting idiopathic retroperitoneal fibrosis. The FDA's breakthrough therapy designation pathway compresses review timelines for agents demonstrating superior ureteral patency outcomes. Stakeholders must monitor real-world evidence requirements from CMS and NICE as these agencies tighten reimbursement linkages to renal function preservation endpoints rather than radiographic response alone.
Market Dynamics
Consolidation among tertiary hospital systems is compressing vendor margins while amplifying purchasing leverage for immunotherapy protocols. Integrated delivery networks now command preferential contracting terms that reshape competitive positioning across corticosteroid-sparing regimens.
Growth Catalysts
- Orphan Drug Designation:The FDA's accelerated approval pathway compresses development timelines for novel biologics targeting idiopathic retroperitoneal fibrosis. This incentive structure attracts venture funding toward rare disease indications.
- Medicare Reimbursement Expansion:Surgical decompression procedures carry favorable reimbursement codes that drive volume concentration at academic medical centers. This payment structure incentivizes infrastructure investment in complex ureterolysis capabilities.
- Diagnostic-Guided Stratification:PET-CT and biomarker panels enable precise patient selection for corticosteroid taper protocols. Radiology departments at tertiary centers integrate these tools into standardized care pathways.
Market Restraints
- Specialized Surgical Workforce Scarcity:Ureterolysis requires fellowship-trained urologic oncologists concentrated at academic centers. This geographic limitation restricts procedural access outside major metropolitan clusters.
- Biologic Manufacturing Complexity:Cell culture production of monoclonal antibodies creates supply vulnerability to single-source contract manufacturers. Batch failures at CMO facilities trigger therapy interruption.
- Long-Term Steroid Toxicity:Corticosteroid-sparing alternatives face elevated evidence thresholds from payers skeptical of durable remission claims. This reimbursement friction delays adoption of immunotherapy-first protocols.
Strategic Opportunities
- Real-World Evidence Infrastructure:CMS and NICE tightening of renal function preservation endpoints creates demand for post-market surveillance platforms. Registry-based studies offer competitive differentiation for manufacturers.
- Ambulatory Infusion Expansion:Community oncology networks seek to capture immunotherapy administration outside hospital outpatient departments. This channel shift reduces cost burden for integrated delivery networks.
- EMA Priority Medicines Framework:Accelerated assessment pathways for biologics demonstrating superior ureteral patency outcomes compress time-to-market in European jurisdictions. This regulatory tailwind attracts pipeline investment.
Industry Challenges
- Cross-Functional Trial Design:Nephrology-urology-rheumatology coordination demands specialized clinical operations expertise. Multi-specialty enrollment slows patient accrual for pivotal studies.
- Radiographic-Renal Endpoint Misalignment:Discordance between CT-based response criteria and creatinine clearance trajectories complicates label negotiations with regulators. This evidentiary gap requires prospective biomarker validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retroperitoneal Fibrosis Treatment Market |
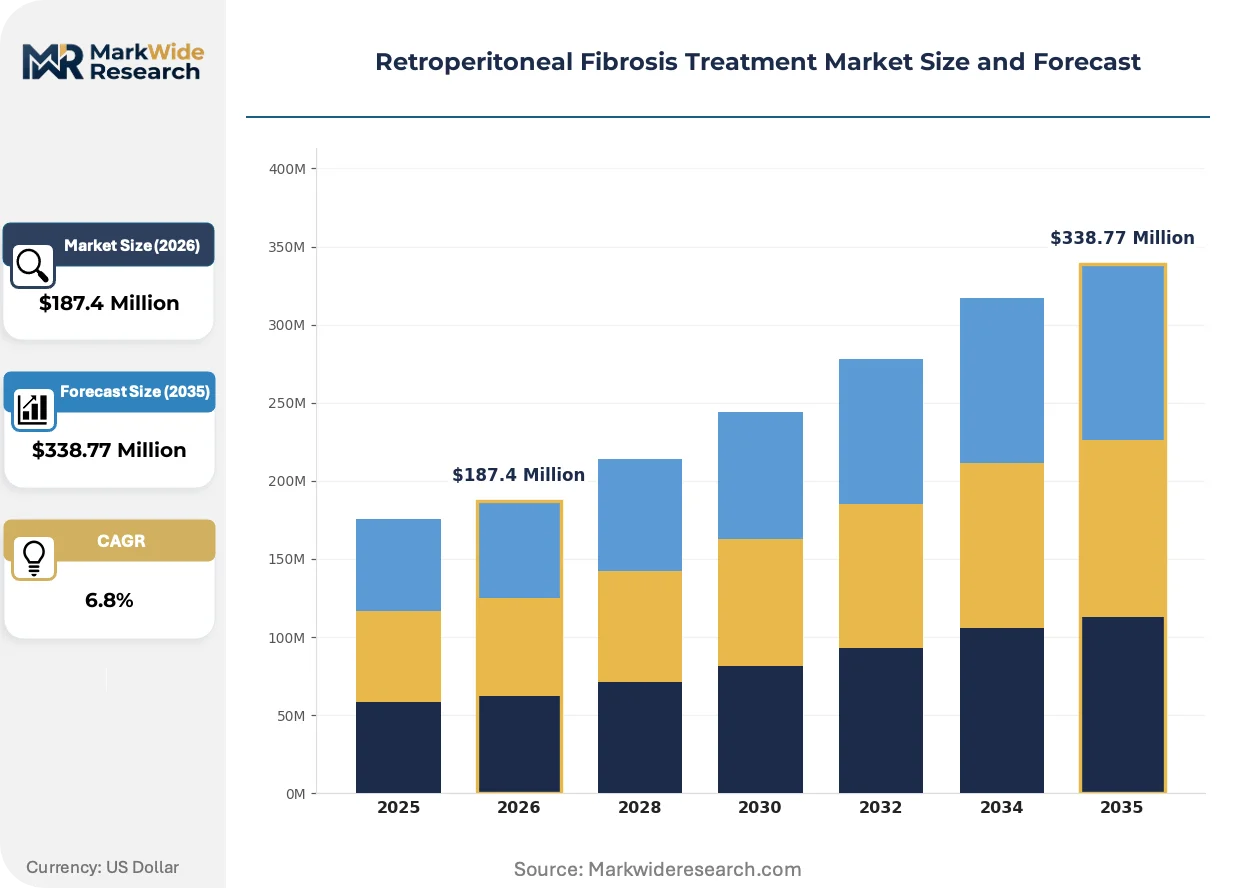
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Corticosteroids, Surgical Intervention, Immunotherapy, Chemotherapy Patient Type: Adult Patients, Pediatric Patients, Geriatric Patients, Surgical Candidates Diagnosis Method: CT Scan, MRI, Ultrasound, Biopsy Care Setting: Outpatient Clinics, Hospitals, Specialty Centers, Home Care |
| Companies Covered | Sanofi, AstraZeneca, GlaxoSmithKline, Bristol-Myers Squibb, Johnson & Johnson, Teva Pharmaceutical Industries, Novartis, Roche, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retroperitoneal Fibrosis Treatment Market Evolving Landscape
Novel biomarker platforms and decentralized care models are compressing the traditional hospital-centric treatment paradigm. These shifts enable earlier intervention while redistributing economic value across the care continuum.
Positron emission tomography with fibroblast activation protein inhibitors is decentralizing diagnostic staging from academic radiology departments into regional imaging networks. Community-based nuclear medicine facilities in Germany and the United States are adopting standardized uptake value protocols for therapy monitoring. This geographic expansion of diagnostic access is compressing referral bottlenecks that previously centralized patient flow.
The FDA's breakthrough therapy designation pathway for agents demonstrating superior ureteral patency outcomes is compressing review timelines from ten to six months. This regulatory acceleration incentivizes manufacturers to prioritize renal function preservation endpoints in Phase II trial designs. Biologics targeting the IL-6 pathway are most affected, with sponsors restructuring development programs to capture this designation.
Integrated delivery networks are unbundling after-sales clinical support from pharmaceutical contracts. Hospital systems in the United States now separately negotiate patient education programs, adherence monitoring, and registry participation. This procurement fragmentation creates openings for specialized service vendors while pressuring traditional full-service contracting models.
Retroperitoneal Fibrosis Treatment Market Segmentation
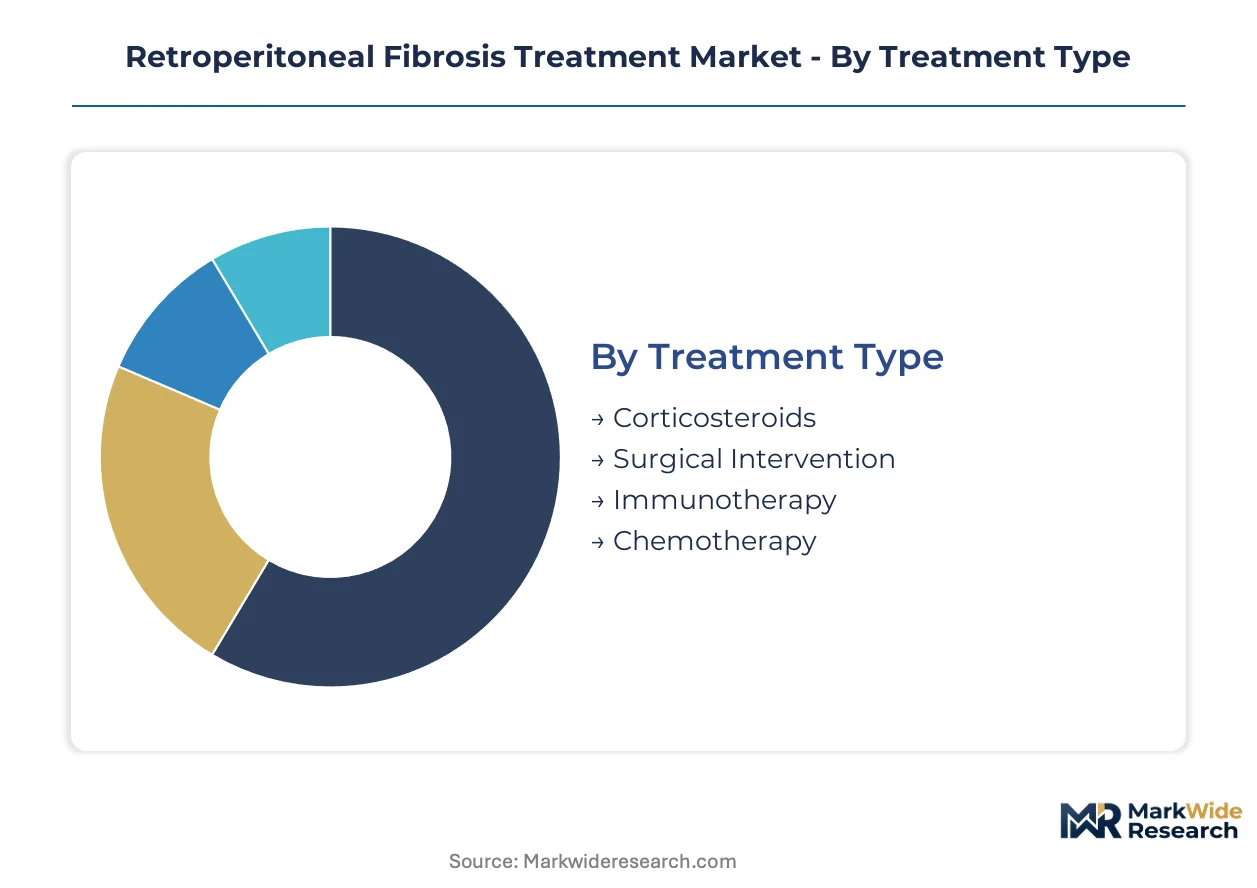
Retroperitoneal fibrosis treatment stratifies across therapeutic modality, patient physiology, diagnostic technology, and care delivery infrastructure. Each segmentation axis reflects distinct procurement patterns, reimbursement codes, and clinical workflow integration requirements that shape vendor commercial strategy.
Treatment Type:
Pharmacologic mechanism and invasiveness level define the primary technology axis for therapeutic selection.
- Corticosteroids:Prednisone and methylprednisolone protocols remain the established first-line intervention, with taper regimens standardized across academic medical centers. Demand concentrates in the United States where Medicare Part D covers oral formulations, though steroid-sparing pressure from integrated delivery networks is accelerating.
- Immunotherapy:Biologics targeting IL-6 and B-cell pathways are displacing prolonged steroid exposure in tertiary referral patterns. Tertiary centers in Germany and the United States are piloting rituximab-first protocols for idiopathic cases, driven by EMA priority medicines incentives and FDA orphan drug designations.
- Surgical Intervention:Ureterolysis and omental wrap procedures address bilateral obstruction refractory to medical management.
- Chemotherapy:Cyclophosphamide and tamoxifen regimens retain niche application in IgG4-related disease subtypes.
Mature deployment sits with corticosteroid protocols. Newer deployment is concentrated in immunotherapy segments at consolidated academic centers.
Patient Type:
Physiologic reserve and comorbidity burden determine treatment intensity tolerance and surgical candidacy thresholds.
- Adult Patients:Patients aged 18-64 represent the core volume pool, with diagnostic delays averaging 8-12 months from symptom onset. Outpatient immunotherapy administration is expanding fastest in this cohort as ambulatory infusion networks mature.
- Geriatric Patients:Age-related renal function decline and polypharmacy constraints favor corticosteroid-sparing approaches. Japan's aging demographic and Germany's statutory health insurance system are driving protocol adaptations for this segment.
- Pediatric Patients:Congenital and secondary fibrosis forms require specialized pediatric urology-nephrology coordination.
- Surgical Candidates:Anatomic complexity and comorbidity screening identify patients eligible for ureterolysis.
Volume concentration rests with adult patients. Steepest expansion trajectory belongs to geriatric segments as population aging intensifies across developed markets.
Diagnosis Method:
Imaging modality selection balances tissue characterization depth against cost and geographic accessibility.
- CT Scan:Contrast-enhanced computed tomography delivers rapid ureteral visualization and periaortic tissue assessment. Community hospital systems in the United States rely on CT for initial diagnosis, though iodinated contrast nephrotoxicity limits application in pre-existing renal impairment.
- MRI:Magnetic resonance urography eliminates radiation exposure and enables soft tissue characterization without contrast. German and Swiss university hospitals are standardizing MRI protocols for therapy monitoring, supported by superior fibrotic tissue delineation.
- Ultrasound:Point-of-care hydronephrosis detection supports emergency department triage.
- Biopsy:Tissue confirmation differentiates idiopathic from secondary fibrosis etiologies.
CT deployment dominates initial diagnosis. MRI adoption is climbing fastest at tertiary centers with integrated PET-MRI capabilities.
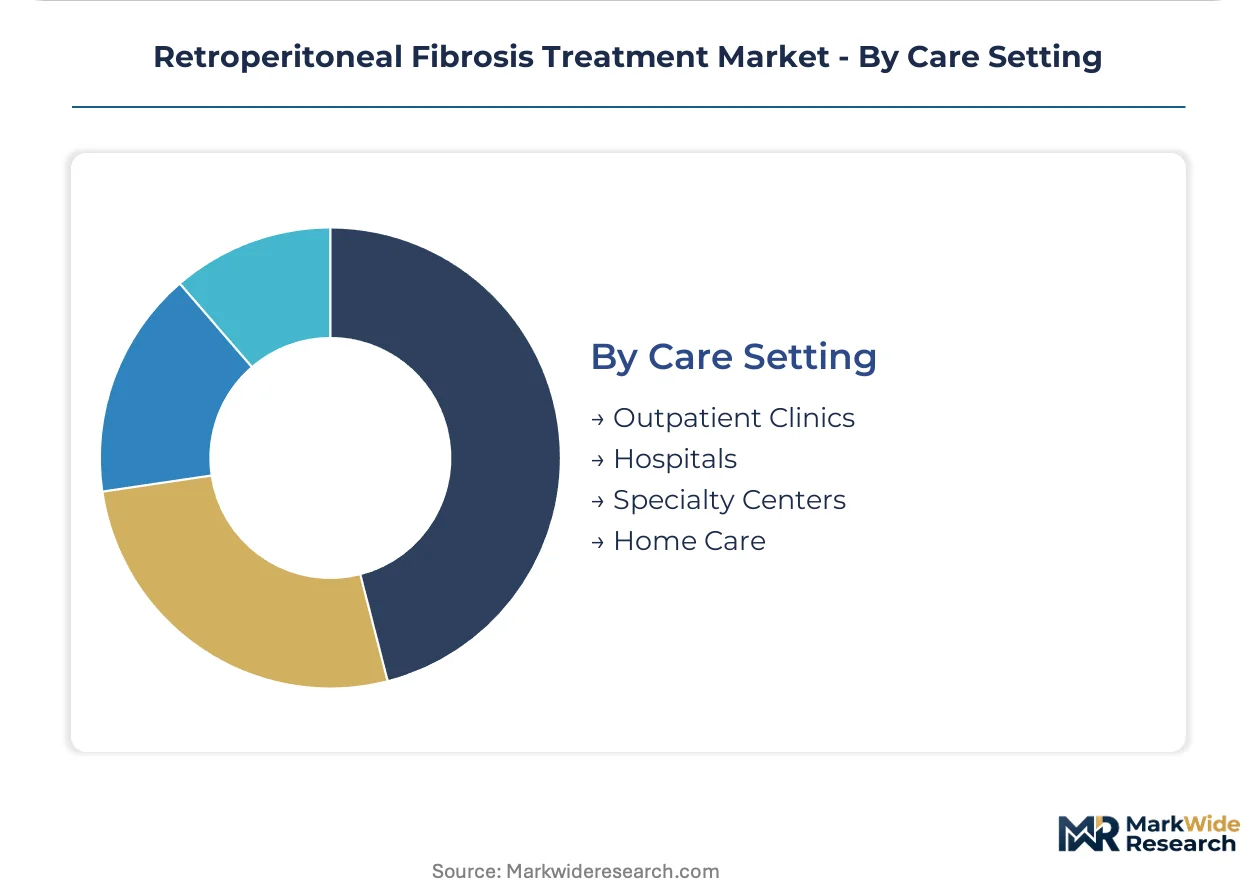
Care Setting:
Acuity level and procedural complexity determine site-of-service economics and reimbursement differentials.
- Hospitals:Inpatient admission supports acute ureteral decompression, complex ureterolysis, and immunotherapy induction. Academic medical centers in the United States capture concentrated surgical margin pools through Medicare Severity Diagnosis-Related Group reimbursement for bilateral procedures.
- Specialty Centers:Dedicated urology and nephrology facilities concentrate multidisciplinary care coordination. France's hospital networks and England's specialist commissioning frameworks are consolidating rare disease treatment into designated centers of excellence.
- Outpatient Clinics:Corticosteroid taper monitoring and stable immunotherapy maintenance are shifting to community settings.
- Home Care:Oral medication adherence support and remote renal function monitoring are emerging.
Hospital infrastructure anchors acute intervention. Specialty centers are gaining share fastest as referral consolidation accelerates across European and North American systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prednisone manufacturing clusters in New Jersey and Basel anchor pharmaceutical supply chains for corticosteroid protocols. Tertiary care infrastructure concentrates in metropolitan academic medical centers across North America and Western Europe.
United States
Medicare Severity Diagnosis-Related Group reimbursement for bilateral ureterolysis drives procedural volume concentration. FDA orphan drug designation accelerates biologic development timelines for idiopathic cases. Boston's Longwood Medical Area and Manhattan's Upper East Side hospital clusters pilot rituximab-first protocols.
Germany
Statutory health insurance coverage for corticosteroid-sparing regimens expands immunotherapy access. EMA priority medicines framework compresses assessment timelines for novel biologics. Munich and Heidelberg university hospitals standardize MRI urography protocols for therapy monitoring.
United Kingdom
NICE technology appraisals tighten reimbursement linkages to renal function preservation endpoints. Specialist commissioning frameworks consolidate rare disease treatment into designated centers of excellence. London's NHS Foundation Trusts concentrate multidisciplinary urology-nephrology coordination.
Switzerland
Swissmedic accelerated pathways attract biologic manufacturers seeking European market entry. PET-CT diagnostic infrastructure expands through private radiology networks in Zurich and Geneva. Basel's pharmaceutical corridor anchors corticosteroid active pharmaceutical ingredient production.
Japan
PMDA sakigake designation system prioritizes review of agents demonstrating superior ureteral patency outcomes. Aging demographic pressures favor geriatric-adapted corticosteroid taper protocols. Tokyo and Osaka academic medical centers concentrate fellowship-trained urologic oncologist supply.
Retroperitoneal Fibrosis Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue diagnostic-guided patient stratification and corticosteroid-sparing regimens. The competitive structure consolidates around integrated pharmaceutical portfolios with transplant immunology and autoimmune franchises. Three archetypes dominate: diversified biopharma conglomerates with rare disease infrastructure, mid-cap immunology specialists, and diagnostic-platform integrators. Capacity expansion in biologic manufacturing and strategic partnerships for real-world evidence generation represent the dominant competitive moves.
Among diversified biopharma conglomerates, Novartis and Roche occupy positions anchored by transplant immunology and diagnostic-guided stratification capabilities respectively. Bristol-Myers Squibb exemplifies the autoimmune franchise archetype. These three companies represent the competitive core around which tertiary hospital procurement consolidation revolves.
| Leading Market Players |
|---|
| Sanofi |
| AstraZeneca |
| GlaxoSmithKline |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| Teva Pharmaceutical Industries |
| Novartis |
| Roche |
| Pfizer |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialty distributors of biologic immunotherapies anchor procurement leverage in tertiary hospital networks, compressing vendor margins while enforcing contract standardization across integrated delivery systems. This ownership concentration shapes both upstream manufacturing commitments and downstream pricing discipline for corticosteroid-sparing regimens.
Pricing Analysis
Volume concentration in corticosteroid protocols trades margin depth for market breadth, while immunotherapy segments command premium positioning through orphan drug exclusivity. Price differentiation rests on FDA breakthrough therapy designation status and bundled clinical support services. Pricing pressure stems from Medicare reimbursement tightening for surgical decompression procedures. Community oncology networks exhibit highest price sensitivity; academic medical centers prioritize outcome guarantees over per-unit cost.
Supply Chain Analysis
Direct-to-hospital procurement channels handle immunotherapy biologics requiring cold-chain integrity, while wholesale distributors manage oral corticosteroid formulations. API manufacturing concentrates in Switzerland, India, and the United States for corticosteroid active ingredients; biologic cell culture production centers on contract manufacturers in Germany and Ireland. Supply chain risk manifests in single-source vulnerability for IL-6 pathway monoclonal antibodies. Distribution runs through integrated delivery network central pharmacies for hospital-based administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among tertiary hospital systems is forcing mid-cap immunology specialists toward acquisition or alliance, compressing viable standalone positions. Margin pressure from standardized contracting terms accelerates this consolidation dynamic.
For Market Incumbents: Anticipate biosimilar entry in IL-6 pathway inhibitors by deepening backward integration into cell culture manufacturing capacity in Basel and Boston corridors. Lock in exclusive formulary positioning through real-world evidence registry partnerships with Medicare Advantage plans. Counter emerging diagnostic-platform integrators by embedding PET-CT stratification tools into bundled therapy contracts.
For New Entrants and Emerging Players: Capture ambulatory infusion network expansion in community oncology settings outside academic medical center catchment zones. Target geriatric-adapted corticosteroid taper protocols in Japan and Germany where statutory reimbursement favors steroid-sparing alternatives. Lead with remote renal function monitoring platforms that reduce hospital outpatient department dependency.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation awards for ureteral patency endpoints are the leading indicator that biologic development programs have achieved regulatory de-risking sufficient for late-stage capital deployment. Five-to-ten year viability favors platforms with diagnostic-guided stratification capabilities and transplant immunology cross-application potential. Watch for EMA priority medicines framework approvals as European market entry signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Registry Development | CMS reimbursement linkages to renal function preservation endpoints require post-market surveillance infrastructure investment. |
| Orphan Drug Designation Pursuit | FDA accelerated approval pathway compresses development timelines for idiopathic retroperitoneal fibrosis indications. |
| Diagnostic Platform Integration | PET-CT fibroblast activation protein inhibitor protocols enable precise patient selection for corticosteroid-sparing regimens. |
| Ambulatory Infusion Network Expansion | Community oncology settings reduce cost burden for integrated delivery networks managing immunotherapy maintenance. |
| Manufacturing Capacity Diversification | Cell culture production redundancy mitigates single-source contract manufacturer vulnerability for biologic supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving drug development executives, hospital procurement managers, payer access specialists, and regulatory affairs leads. FDA orphan drug designation databases, EMA priority medicines submissions, ClinicalTrials.gov records, and Medicare reimbursement code analyses supplied validation layers. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Data-stream reconciliation across therapeutic modality, patient physiology, diagnostic technology, and care delivery infrastructure shaped the analytical framework. Segmentation dimensions included pharmacologic mechanism, age cohort tolerance, imaging modality selection, and site-of-service economics. CAGRs derived from trend extrapolation of Medicare reimbursement expansion, EMA accelerated assessment adoption, and tertiary hospital consolidation patterns. Ureteral patency outcome benchmarks and renal function preservation endpoints informed biologic adoption curve assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory reimbursement tightening, biosimilar entry timing, and radiographic-renal endpoint alignment in payer frameworks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Central Pontine Myelinolysis Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market