
 US C-Arms Market | 2026-2036
US C-Arms Market Size, Share, and Industry Trends Forecast 2026-2036
US C-Arms Market Intelligence
FDA 510(k) premarket notification is bifurcating the competitive landscape, separating established vendors with extensive regulatory histories from new entrants. Siemens Healthineers leverages its broad imaging portfolio to offer integrated solutions for hybrid operating rooms. GE Healthcare competes on the strength of its digital flat-panel detector technology and extensive service network across the US. Meanwhile, specialists like OrthoScan differentiate by focusing exclusively on mini C-arm systems for extremity imaging.
A C-arm is a medical imaging apparatus with a C-shaped gantry connecting an X-ray source and a detector. It provides real-time fluoroscopic imaging to guide minimally invasive procedures in surgery and interventional medicine. Mobile C-arms represent the largest product segment, valued for their flexibility in hospitals and ambulatory surgical centers. The adoption of digital flat-panel detectors is a critical technology trend, offering superior image resolution compared to legacy image intensifiers.
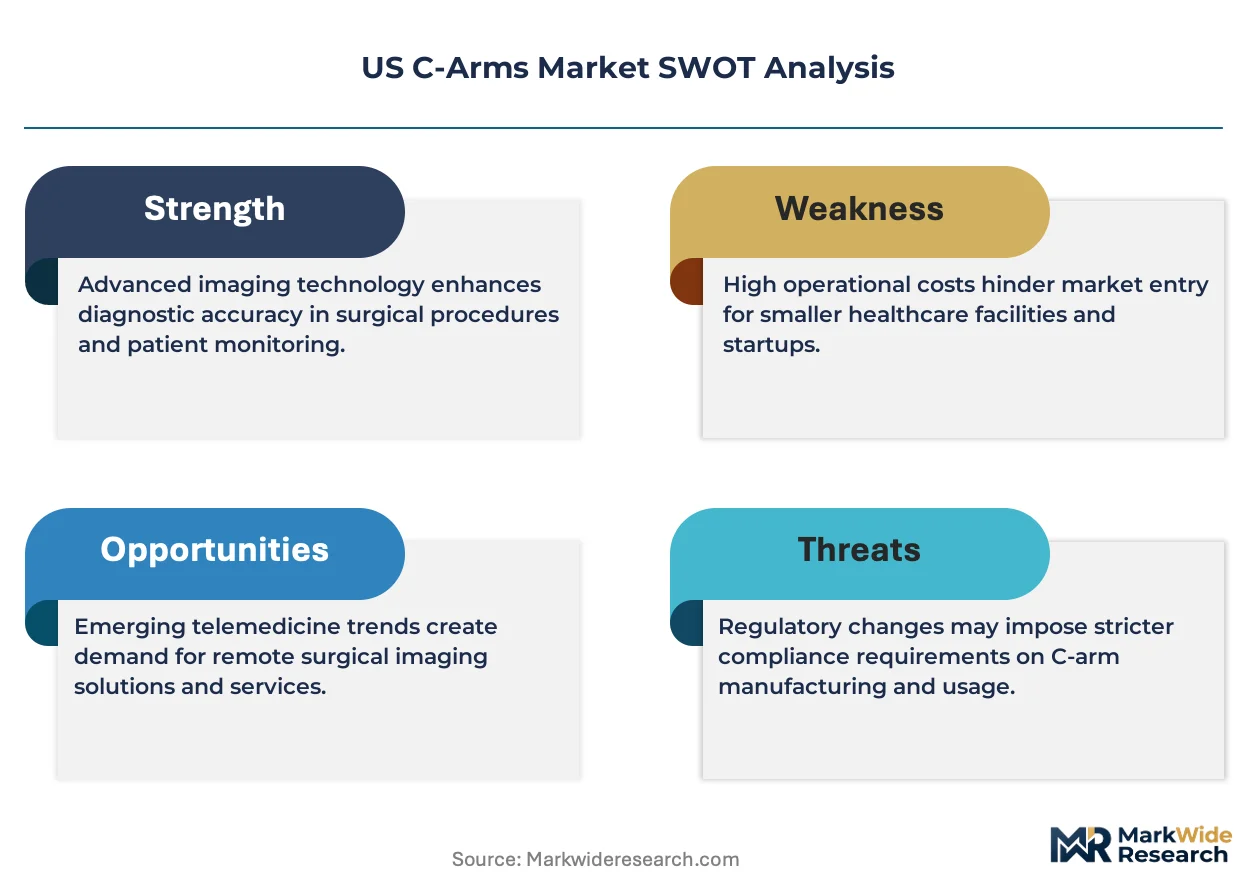
The US Food and Drug Administration (FDA) stringently regulates C-arm systems as Class II medical devices, requiring premarket clearance for market access. Compliance with HIPAA is mandatory to ensure the security of patient imaging data, while OSHA standards govern workplace radiation safety for clinical staff. Vendors must navigate evolving reimbursement policies from Medicare while continuing to innovate on dose reduction technologies.
Market Dynamics
The central force shaping the US C-arms market is the procedural shift from inpatient hospital settings to ambulatory surgical centers. This migration demands greater equipment mobility, enhanced workflow efficiency, and superior dose management to accommodate higher patient throughput in outpatient environments.
Growth Catalysts
- Digital Detector Adoption:The transition from image intensifiers to digital flat-panel detectors (FPDs) enhances image quality and diagnostic confidence, particularly for complex orthopedic and cardiovascular procedures, accelerating system upgrades in US hospitals.
- Minimally Invasive Surgery:An expanding volume of minimally invasive procedures across specialties like orthopedics, spine, and vascular surgery directly increases the need for real-time fluoroscopic guidance that C-arm systems provide.
- Reimbursement Policies:Favorable reimbursement structures from Medicare for procedures conducted in ambulatory surgical centers (ASCs) incentivize the acquisition of C-arms, especially in states with a high density of outpatient facilities like Florida and California.
Market Restraints
- High Capital Costs:The significant upfront investment required for advanced C-arm systems, especially those with 3D imaging or robotic capabilities, remains a primary barrier for smaller hospitals, independent clinics, and facilities with constrained budgets.
- Regulatory Hurdles:The stringent and lengthy FDA 510(k) premarket clearance pathway for Class II medical devices creates a substantial barrier to entry for new and international manufacturers attempting to enter the US market.
- Substitution by Other Modalities:In certain diagnostic and interventional scenarios, alternative imaging technologies such as intraoperative MRI or ultrasound present viable substitutes, limiting the addressable applications for C-arm systems.
Strategic Opportunities
- AI and Software Integration:Integrating artificial intelligence algorithms for automated anatomical recognition, dose optimization, and predictive image adjustments presents a significant opportunity to enhance clinical workflows and diagnostic accuracy.
- Expansion into Pain Management:The growing field of interventional pain management offers a substantial opportunity, as procedures like nerve blocks and spinal injections increasingly rely on precise C-arm guidance in outpatient settings.
- Hybrid Operating Room Development:Equipping new and retrofitted hybrid operating rooms with advanced, integrated C-arm systems allows vendors to secure high-value, long-term contracts with large hospital networks across the United States.
Industry Challenges
- Technologist Skill Gaps:A shortage of radiologic technologists skilled in operating modern digital C-arms and managing complex radiation safety protocols under OSHA standards poses an operational challenge for healthcare facilities.
- System Interoperability:Ensuring seamless integration of new C-arm systems with existing hospital IT infrastructure, including Picture Archiving and Communication Systems (PACS) and Electronic Health Records (EHR), remains a complex technical hurdle.
- Cybersecurity Vulnerabilities:The increasing connectivity of C-arm devices to hospital networks exposes them to cybersecurity threats, requiring continuous software updates and adherence to strict HIPAA data security protocols to protect patient information.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US C-Arms Market |
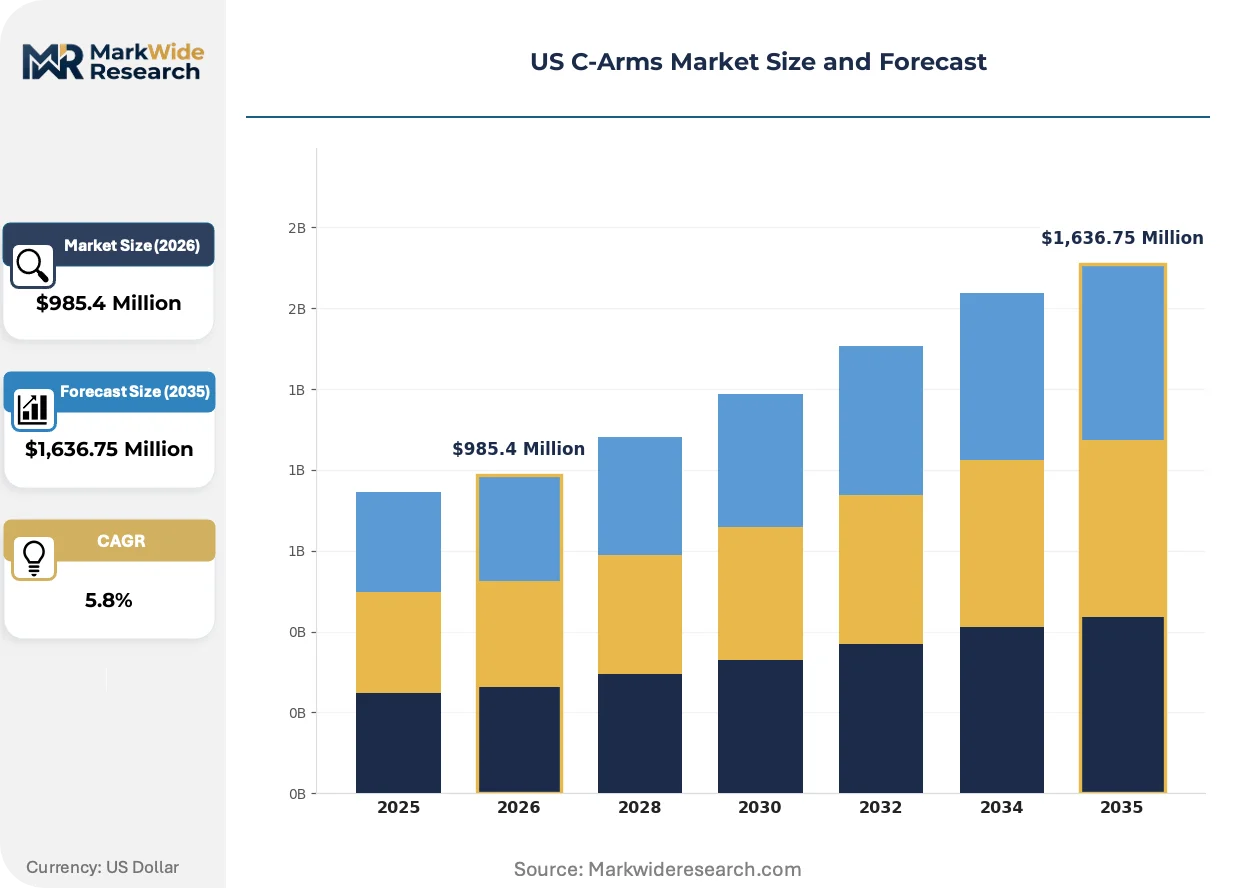
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,636.75 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile C-Arm, Fixed C-Arm, Compact C-Arm, Mini C-Arm, Hybrid C-Arm Technology: Digital Flat-Panel Detector, Image Intensifier, 3D Imaging, Pulsed Fluoroscopy, Roadmapping Technology Application: Orthopedic Surgery, Cardiovascular Procedures, Urology, Gastroenterology, Pain Management End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Ziehm Imaging, Canon Medical Systems, Shimadzu Corporation, Hologic, OrthoScan, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US C-Arms Market Strategic Shifts & Innovations
The US C-arms market is evolving under the dual pressures of improving clinical precision while simultaneously reducing radiation exposure for both patients and clinicians. This dynamic drives innovation toward intelligent automation, dose efficiency, and new service-oriented business models.
Robotic-assisted C-arm systems provide automated positioning and advanced 3D imaging capabilities for complex procedures. Large academic medical centers and specialty spine hospitals are the primary adopters of this technology for neurosurgery and orthopedic applications. This level of automation is decomposing the traditional, manual workflow by separating the imaging task from the surgeon's direct physical manipulation of the gantry.
Initiatives from the FDA promoting lower radiation dose standards are influencing device design and purchasing criteria across the US. This regulatory focus compels manufacturers to engineer and market dose-reduction features, including pulsed fluoroscopy, virtual collimation, and AI-driven dose modulation. The pediatric and interventional cardiology segments are most affected, with hospitals prioritizing systems that demonstrate clear adherence to ALARA principles.
A transition from outright capital purchases toward more flexible acquisition models, including long-term operational leases and managed equipment services, is gaining momentum. This shift disrupts the traditional one-time sales cycle, replacing it with recurring revenue contracts that bundle maintenance, software upgrades, and technical support. This trend is most visible among large, multi-site ambulatory surgery center networks seeking to standardize technology and manage operational expenses predictably.
US C-Arms Market Segmentation
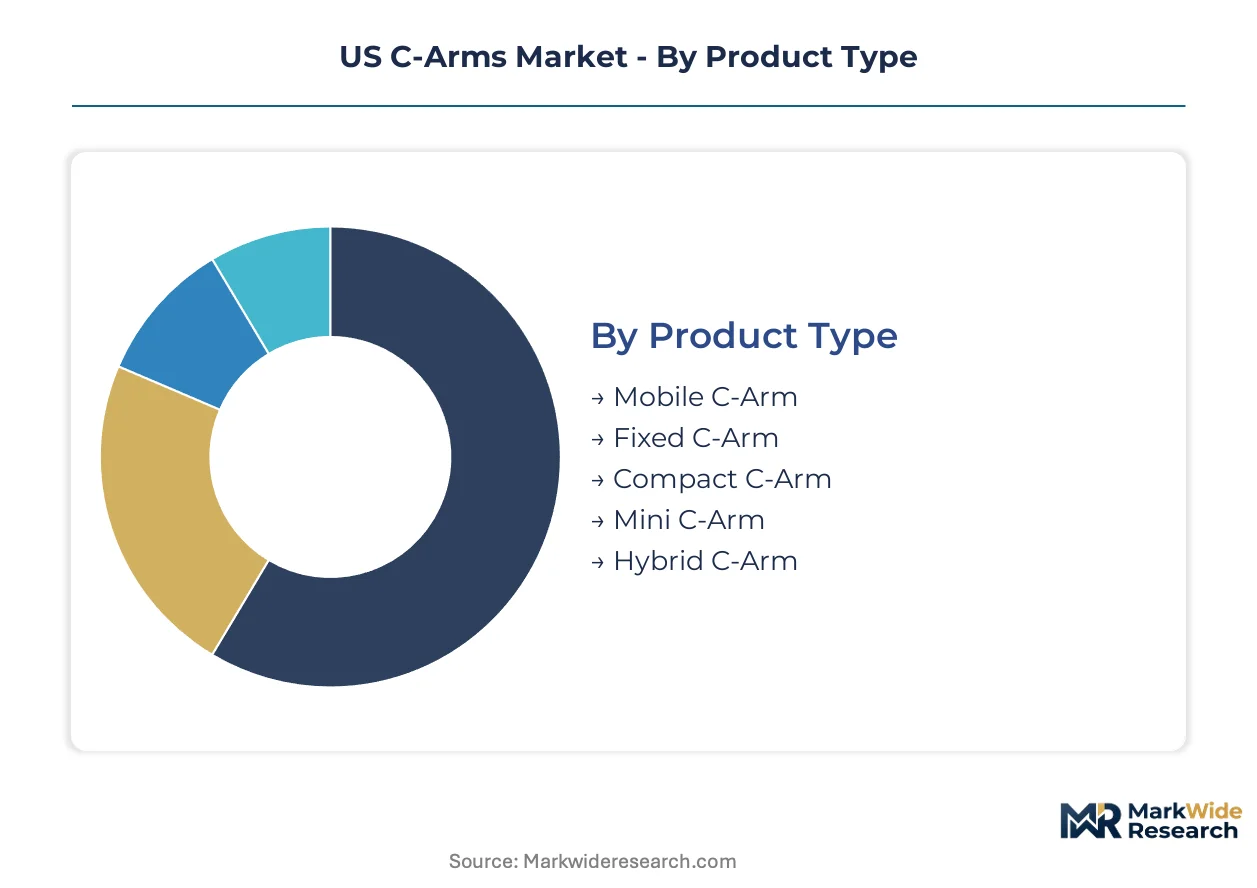
The US C-arms market segmentation highlights diverse product offerings and specialized applications catering to varied clinical needs across the nation. Understanding these segments provides clarity on demand drivers and technological preferences within different healthcare settings.
Product Type:
The distribution of C-arm product types varies across US states, with some types optimized for high-volume urban centers and others for specialized clinics.
- Mobile C-Arm:These compact, wheeled systems relocate easily. Their flexibility is indispensable for orthopedic and pain management in ambulatory surgical centers across California and Florida.
- Fixed C-Arm:Permanently installed systems offer enhanced power and imaging, found in dedicated cath labs within large hospital networks.
- Compact C-Arm:Smaller footprint devices for tight spaces, utilized in emergency departments or smaller clinics for basic fluoroscopic guidance.
- Mini C-Arm:Specialized for extremity imaging, these systems focus on hands, wrists, and feet, used by orthopedic specialists.
- Hybrid C-Arm:Advanced integrated systems combine C-arm imaging with robotics, adopted by academic medical centers for neurosurgery and complex spine procedures.
Mobile C-Arm holds the largest share; momentum sits with Hybrid C-Arm.
Technology:
Different C-arm technologies serve distinct clinical utilities, from fundamental real-time imaging to advanced procedural guidance and dose management. Each offers specific advantages.
- Digital Flat-Panel Detector:These modern detectors provide superior image resolution and reduced radiation dose. Their adoption is critical for complex orthopedic and cardiovascular procedures, accelerating system upgrades in US hospitals.
- Image Intensifier:Older, cost-effective technology converting X-rays into visible light, found in facilities with budget constraints.
- 3D Imaging:Incorporating volumetric data, 3D imaging enhances surgical precision with detailed anatomical views during complex interventions. This technology is utilized in large academic centers for neurosurgery and spine applications.
- Pulsed Fluoroscopy:A dose-reduction technique delivering X-ray pulses instead of continuous radiation, improving safety for patients and staff.
- Roadmapping Technology:Software overlays real-time fluoroscopic images with pre-acquired angiographic images, crucial for guiding vascular interventions.
The market prioritizes Digital Flat-Panel Detector for widespread adoption, while 3D Imaging is gaining traction for specialized needs.
Application:
Investment in C-arm systems is dictated by specific clinical applications, with high-volume surgical specialties requiring advanced and dedicated equipment. Each represents a distinct procedural workflow.
- Orthopedic Surgery:C-arms are essential for real-time guidance during fracture reductions, joint replacements, and spinal fusions. Expanding minimally invasive orthopedic procedures across the US increase the need for precise fluoroscopic guidance.
- Cardiovascular Procedures:Used in angiography, stent placement, and pacemaker implantation, these procedures demand high-resolution imaging and specialized roadmapping.
- Urology:C-arms assist in procedures like lithotripsy for kidney stones, stent placements, and other urinary tract interventions.
- Gastroenterology:Fluoroscopic guidance supports ERCP and other digestive system interventions requiring real-time visualization.
- Pain Management:This growing field heavily relies on C-arms for precise needle placement during nerve blocks and spinal injections in outpatient settings.
Demand remains strongest for Orthopedic Surgery, with Pain Management exhibiting rapid expansion.
End User:
Patient throughput and procedural volume significantly influence C-arm procurement decisions across different end-user segments. Facilities with higher patient loads prioritize efficiency and advanced imaging.
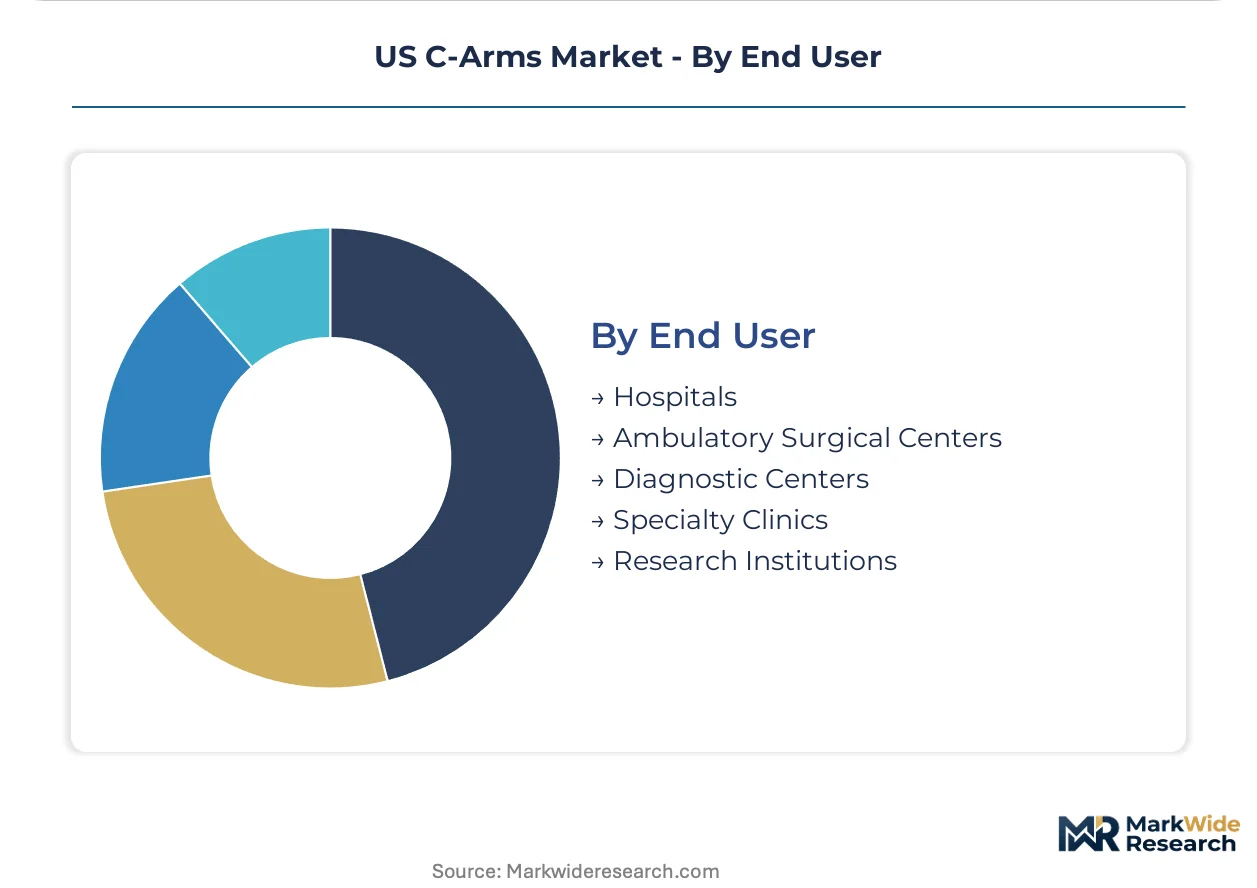
- Hospitals:Large acute care facilities utilize diverse C-arms for multiple departments, including emergency, surgery, and interventional cardiology. They invest in advanced systems for complex inpatient procedures.
- Ambulatory Surgical Centers:These outpatient facilities value mobile C-arms for flexibility and workflow efficiency, supporting high volumes of minimally invasive procedures. The procedural shift to ASCs drives significant equipment acquisition.
- Diagnostic Centers:Primarily focus on imaging for diagnostic purposes, often employing C-arms for specific fluoroscopic studies.
- Specialty Clinics:Include orthopedic, pain management, and vascular clinics, where C-arms are integral to their specialized interventional services.
- Research Institutions:Utilize C-arms for preclinical studies, medical device development, and clinical trials requiring real-time imaging.
The largest volume of C-arm procedures occurs in Hospitals, but Ambulatory Surgical Centers are experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement policies for ambulatory surgical centers (ASCs) are reshaping the US C-arms market. This policy shift incentivizes equipment acquisition in outpatient settings. These centers prioritize mobility and workflow efficiency to support higher patient throughput.
California
A high density of ambulatory surgical centers and complex orthopedic procedures drive demand in California. HIPAA compliance for patient data security remains a critical regulatory consideration for all medical imaging systems. Southern California’s medical device cluster drives innovation in C-arm technology development.
Texas
Large healthcare systems and a growing population in Texas create demand for diverse C-arm applications, including trauma care. OSHA standards for radiation safety significantly influence equipment selection and operational protocols. Houston's Texas Medical Center integrates advanced C-arms into its interventional suites for complex procedures.
Florida
Florida's aging population and high volume of orthopedic and pain management procedures stimulate C-arm procurement. State-specific licensing for medical imaging equipment ensures operational compliance and patient safety. Orlando and Miami healthcare networks expand C-arm use in outpatient pain clinics.
New York Metro
Academic medical centers and specialized surgical procedures in the New York Metro area demand high-performance C-arm systems. The New York State Department of Health oversees medical device deployment and operational standards. Manhattan's hospital systems adopt hybrid C-arms for neurosurgery applications.
Midwest (Illinois/Michigan)
The Midwest region, including Illinois and Michigan, sees demand from a manufacturing base for medical devices and growing spine surgery volumes. FDA 510(k) premarket clearance influences regional adoption patterns for new technologies. Chicago and Detroit medical facilities focus on C-arm integration for minimally invasive spine procedures.
US C-Arms Market Key Industry Players
Player mix skews toward large, diversified medical technology conglomerates in the US C-arms market. The market exhibits moderate consolidation at the high-end, alongside fragmentation in specialized segments. Established global players, specialized niche providers, and emerging technology innovators form distinct competitive archetypes. Portfolio diversification and strategic partnerships drive market share, while technology licensing also influences market dynamics.
Within the established vendor tier, Siemens Healthineers and GE Healthcare exemplify broad imaging portfolios. These companies offer integrated solutions for hybrid operating rooms and leverage extensive service networks. Siemens Healthineers represents providers with a wide array of imaging modalities. GE Healthcare occupies a position based on its digital flat-panel detector technology. OrthoScan, meanwhile, anchors the specialized niche for mini C-arm systems, focusing on extremity imaging. This specialization allows for differentiation from generalist providers.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Ziehm Imaging |
| Canon Medical Systems |
| Shimadzu Corporation |
| Hologic |
| OrthoScan |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Extended lead times for advanced C-arm components, particularly digital flat-panel detectors, amplify pricing power for established manufacturers. This supply concentration influences procurement strategies for hospitals and ambulatory surgical centers.
Pricing Analysis
Certification level, specifically FDA 510(k) clearance, creates the primary spread in C-arm system pricing. Value-based pricing models dominate, reflecting advanced features like digital flat-panel detectors and robotic capabilities. Price differentiation stems from dose reduction technologies and comprehensive service contracts. Pricing softness affects entry-level mobile C-arms due to increased competition, with smaller specialty clinics and ambulatory surgical centers being most price-sensitive. Large hospital networks exhibit lower price sensitivity for high-end hybrid systems.
Supply Chain Analysis
Germany and the United States anchor the manufacturing of advanced C-arm systems and their critical components. The supply chain draws from specialized producers of X-ray tubes, digital flat-panel detectors, and high-precision mechanical gantry systems. Single-source vulnerability for critical detector components presents a structural supply chain risk. Distribution runs primarily through direct sales forces and established medical device distributors, often managed via group purchasing organization contracts with large hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US C-arms market represents a high-growth disruption, driven by the technological inflection of digital flat-panel detectors and the procedural shift to ambulatory surgical centers. These dynamics create new opportunities and competitive pressures across the industry.
For Market Incumbents: Compound integrated solutions for hybrid operating rooms, leveraging broad imaging portfolios to counter substitution by alternative modalities like intraoperative MRI. Invest heavily in AI and software integration for automated anatomical recognition and dose optimization to differentiate from emerging entrants. Consolidate market share in ambulatory surgical centers through strategic partnerships and comprehensive service offerings, reinforcing channel control. Focus R&D on next-generation digital flat-panel detectors to maintain technological leadership.
For New Entrants and Emerging Players: A service-layer gap exists in providing flexible, cost-effective C-arm solutions tailored for high-throughput ambulatory surgical centers. Target the rapidly expanding pain management application segment with specialized mobile C-arms offering superior dose management. Focus on states with high ASC density like Florida and California for market penetration. Offer managed equipment services or operational leases as a compelling go-to-market angle, reducing upfront capital costs for smaller facilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the advanced C-arm systems segment, particularly for hybrid operating room development. This market demonstrates strong long-term viability over the next decade, driven by ongoing procedural migration to outpatient settings and technological advancements. Identify acquisition targets among specialized mini C-arm manufacturers or AI software developers focused on image processing and dose optimization. The signal to watch is the pace of FDA approvals for new dose-reduction technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-driven Image Processing Integration | Enhances diagnostic accuracy and workflow efficiency for complex orthopedic procedures, improving patient outcomes. |
| Expansion into Managed Equipment Services | Captures recurring revenue streams and addresses capital cost barriers for ambulatory surgical centers. |
| Development of Robotic-Assisted C-arms | Offers advanced 3D imaging and automated positioning for neurosurgery applications in academic medical centers. |
| Enhanced Cybersecurity Protocols | Protects sensitive patient data and ensures HIPAA compliance for connected C-arm devices in hospital networks. |
| Strategic Partnerships with ASC Networks | Secures long-term contracts and standardizes technology across high-volume outpatient facilities. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, CMS Medicare data, and hospital procurement databases. This approach involved extensive interviews with clinicians, hospital purchasing committees, biomedical engineers, and group purchasing organization managers. Data triangulation, employing both bottom-up and top-down methodologies, validated market size and growth projections. This ensured comprehensive market understanding and robust data integrity.
Product Type, Technology, Application, End User, and regional adoption patterns define the segmentation dimensions modeled across the analysis window. The analytical framework projects market evolution by assessing historical trends and future demand drivers. Compound Annual Growth Rates were derived from these insights and validated against industry benchmarks. Key forecast inputs include the projected increase in minimally invasive procedures and Medicare reimbursement policy shifts.
Forecasts assume regulatory continuity in US FDA and OSHA frameworks; material policy shifts would require re-modeling. Geopolitical events or significant disruptions in global component supply chains represent specific risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Prefilled Glass Syringes Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Medical Oxygen Concentrators Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Feeding Tubes Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Neuromodulation Devices Market