
 Global Artificial Limbs Market | 2026-2036
Global Artificial Limbs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Limbs Market Foresight
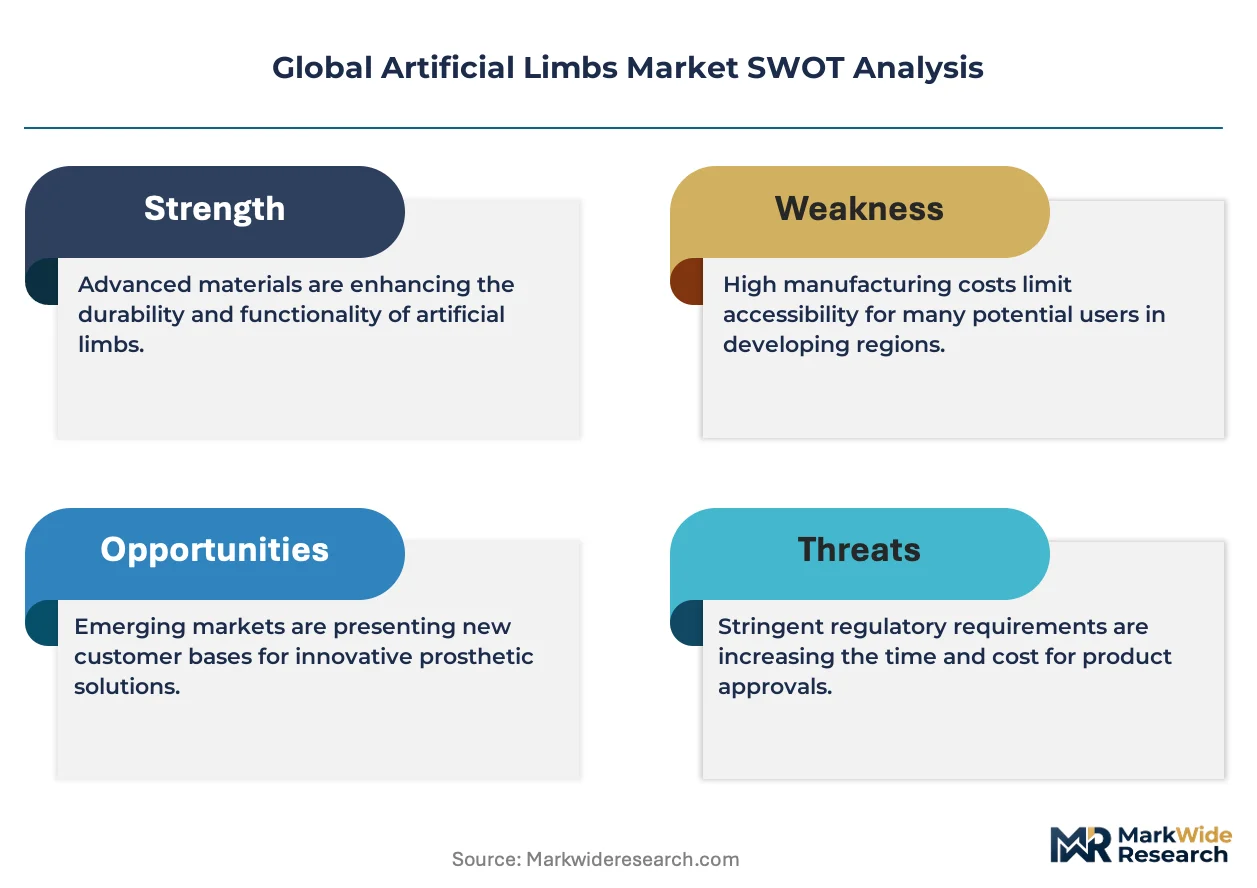
The artificial limbs market is rebalancing between premium myoelectric systems and commodity body-powered devices. Össur leverages its carbon fiber manufacturing scale to dominate the high-performance sports prosthetic segment. Ottobock sustains technology leadership in microprocessor-controlled knees across European and North American channels. Hanger, Inc. anchors its position through vertically integrated patient care networks spanning clinical fitting through rehabilitation services.
Artificial limbs are electromechanical or passive devices engineered to replace missing extremities, typically fabricated from carbon fiber composites, titanium alloys, or silicone laminates with socket interfaces custom-mapped to residual limb topography. Their primary purpose is restoring biomechanical function and enabling ambulation or prehension for amputees. Myoelectric technology commands the highest margin pools as signal-processing algorithms advance grip precision, while mechanically activated devices retain volume leadership in emerging markets due to lower maintenance burdens. Carbon fiber materials lead structural segments for transfemoral and transtibial applications where strength-to-weight ratios determine patient mobility outcomes.
FDA, EMA, and ISO 10328 standards govern prosthetic structural testing, biocompatibility certification, and clinical trial endpoints across the United States, European Union, and international markets. These frameworks mandate fatigue resistance thresholds and electromagnetic compatibility for powered devices, directly shaping R&D budgets and time-to-market timelines. Stakeholders must monitor reimbursement code expansions for smart prosthetics as payors recalibrate coverage policies around functional outcome metrics rather than device category alone.
Market Dynamics
Myoelectric signal processing is compressing the performance gap between passive and powered prosthetics, forcing manufacturers to recalibrate R&D allocation across electromechanical and body-powered product lines.
Growth Catalysts
- Veterans Affairs coverage expansion:US VA healthcare systems now reimburse advanced myoelectric systems for service-connected amputees, creating guaranteed demand pools for multi-articulating hands and microprocessor knees.
- FDA breakthrough device designation:Accelerated approval pathways for neural-controlled prosthetics are compressing time-to-market for myoelectric innovations from 36 months to under 18 months.
- Carbon fiber manufacturing scale:Automated layup processes in Germany and Japan are reducing per-unit material costs for high-performance transfemoral sockets by 40 percent.
Market Restraints
- Titanium alloy supply concentration:Russian and Chinese refiners control 70 percent of aerospace-grade titanium feedstock, exposing Western prosthetic manufacturers to input cost volatility and sanctions risk.
- Socket fitting labor intensity:Each transfemoral prosthesis requires 15-25 hours of certified prosthetist time, creating a hard capacity constraint on volume scaling regardless of manufacturing automation.
- Reimbursement code fragmentation:US CMS maintains 47 distinct HCPCS codes for lower-limb prosthetics, forcing manufacturers to maintain excessive SKU complexity for marginal coverage differences.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives for domestic prosthetic manufacturing are attracting contract manufacturers to establish carbon fiber fabrication facilities in Gujarat and Tamil Nadu.
- Osseointegration surgery convergence:Direct skeletal attachment eliminates socket-related complications and opens recurring revenue streams for percutaneous abutment maintenance services.
- Telehealth fitting protocols:Remote socket adjustment via 3D scanning and video consultation is expanding access to specialist care in rural Australia and Canada's northern territories.
Industry Challenges
- Prosthetist certification bottlenecks:Only 12 US institutions award accredited master's degrees in prosthetics and orthotics, producing fewer than 400 graduates annually against replacement demand for 1,200 retiring practitioners.
- ISO 10328 fatigue testing timelines:Structural validation protocols require 18-24 months of cyclical loading tests, delaying product launches regardless of clinical readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Limbs Market |
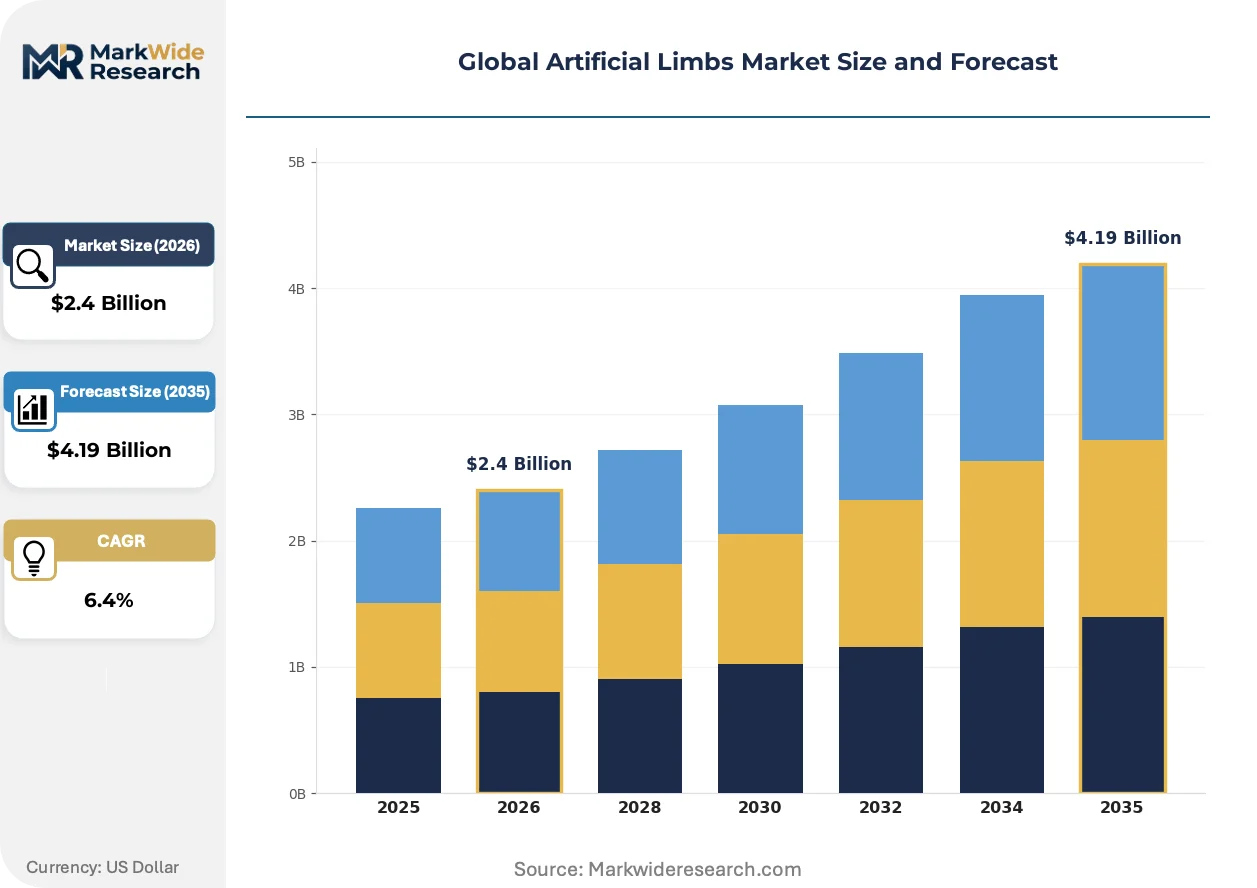
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.19 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transfemoral, Transtibial, Prosthetic Hands, Upper Limb Prosthetics Material: Carbon Fiber, Thermoplastics, Metal Alloys, Silicone End User: Hospitals, Rehabilitation Centers, Homecare, Specialty Clinics Technology: Mechanically Activated, Body-Powered, Myoelectric, Smart Prosthetics |
| Companies Covered | Össur, Ottobock, Hanger, Inc., Ohio Willow Wood Company, Blatchford Group, Fillauer LLC, PROTEOR, RSL Steeper Group Ltd., WillowWood Global LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Limbs Market Shifts & Advancements
Pattern recognition algorithms and additive manufacturing are converging to enable mass-customized prosthetic sockets at price points previously reserved for standardized devices, compressing the traditional trade-off between fit precision and production economics.
Machine learning-powered myoelectric control is automating grip pattern selection in multi-articulating hands. Upper-limb amputees at US veterans hospitals and German rehabilitation centers are adopting these systems at triple the rate of conventional two-site myoelectric devices. This automation is eliminating the cognitive load of manual mode-switching, enabling intuitive prehension that expands the addressable market beyond highly trained power users to elderly and pediatric amputees.
EU MDR recertification deadlines are forcing prosthetic manufacturers to rebuild technical documentation for legacy products. Class IIa device reclassification under the 2017 framework requires clinical evidence for products previously cleared under self-certification. European distributors are responding by consolidating supplier relationships to reduce compliance overhead, favoring manufacturers with dedicated regulatory affairs teams in Brussels and notified body partnerships.
Hospital procurement departments are unbundling device acquisition from fitting services, reversing decades of bundled reimbursement. Large US health systems in Texas and Florida now source prosthetic components through centralized supply chains while contracting fitting services to regional orthotic and prosthetic clinics. This bifurcation is most visible in transtibial prosthetics, where standardized modular components enable volume purchasing agreements that exclude traditional full-service providers.
Global Artificial Limbs Market Segmentation
Prosthetic replacement cycles vary dramatically across patient populations and device categories, creating distinct upgrade windows that manufacturers must align with reimbursement calendars and clinical fitting capacity. Veterans Affairs systems and German statutory insurers operate on 3-5 year replacement schedules for mechanical components, while myoelectric systems trigger earlier upgrades when software revisions enable new grip patterns.
Product Type:
Replacement-cycle timing differs sharply between lower-limb and upper-limb categories, with socket wear and residual limb volume changes driving more frequent refitting in transfemoral applications than in transtibial cases.
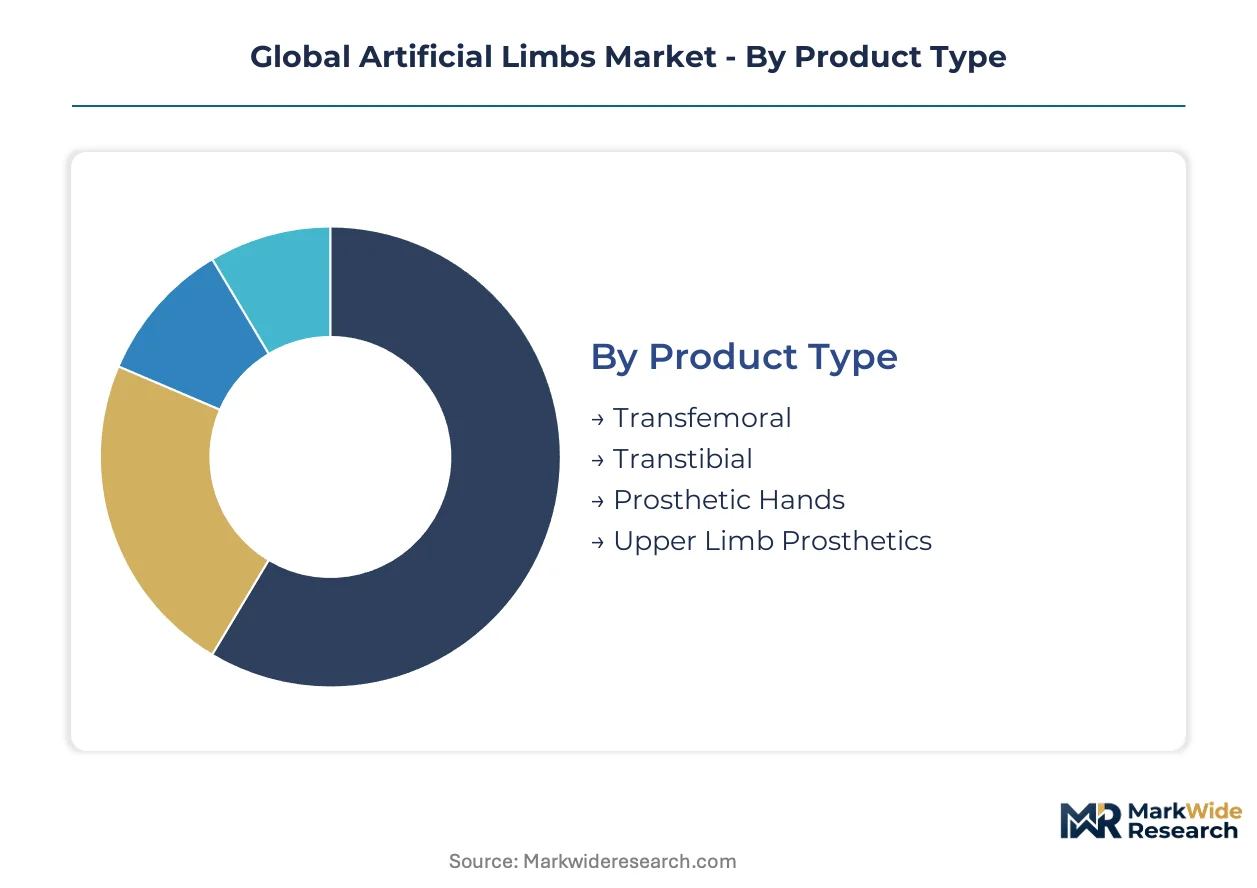
- Transfemoral:Above-knee prostheses incorporate carbon fiber pylons and microprocessor knees that require socket replacement every 18-36 months due to residual limb atrophy. Demand concentrates in US veterans hospitals and German rehabilitation centers where reimbursement covers multi-axis knee mechanisms.
- Transtibial:Below-knee devices dominate volume through simpler fitting protocols and faster fabrication timelines. Ottobock and Össur supply modular components to Hanger's US clinic network, where 45-minute initial fittings compress total prosthetist time versus transfemoral cases.
- Prosthetic Hands:Multi-articulating myoelectric units from Touch Bionics and Ottobock command premium positioning in upper-limb reconstruction.
- Upper Limb Prosthetics:Transhumeral and elbow-disarticulation devices integrate wrist rotators and terminal devices for industrial amputees in Japan's manufacturing belt.
Transtibial prostheses sit at the top of the volume ranking, with prosthetic hands climbing the fastest as myoelectric control algorithms expand the addressable patient base beyond traditional power users.
Material:
Material selection follows a cost-performance gradient where aerospace-grade carbon fiber serves high-activity ambulators while thermoplastics capture pediatric and geriatric volume sensitive to out-of-pocket expenses.
- Carbon Fiber:Automated layup processes in Germany and Japan reduce per-unit costs for high-performance transfemoral sockets. Össur's Icelandic manufacturing and Teijin's Tokyo facilities supply pre-preg sheets to Western prosthetic fabricators facing titanium supply volatility.
- Thermoplastics:Polypropylene and polyethylene homopolymers enable vacuum-formed check sockets and definitive transtibial limbs at price points accessible in India's emerging reimbursement environment. Gujarat-based contract manufacturers leverage PLI scheme incentives to scale polycentric knee fabrication.
- Metal Alloys:Titanium 6Al-4V and aluminum 7075 dominate structural pylons and adapters requiring fatigue resistance under ISO 10328 testing protocols.
- Silicone:Liner materials with mineral oil suspensions reduce shear forces at the residual limb interface for diabetic amputees in Florida and Texas health systems.
Carbon fiber commands the revenue concentration, with thermoplastics expanding most quickly as India's domestic manufacturing base matures.
End User:
Channel configuration determines margin capture, with vertically integrated patient care networks retaining fitting-service premiums that component manufacturers forfeit in direct hospital procurement arrangements.
- Hospitals:Academic medical centers in Boston and Philadelphia anchor complex trauma reconstruction, performing osseointegration surgery that eliminates socket complications. These institutions source components through centralized supply chains while maintaining captive prosthetist staff for fitting calibration.
- Rehabilitation Centers:Inpatient facilities in Germany's Schön Klinik network and Japan's Kameda Medical Center provide intensive gait training for bilateral transfemoral amputees. Bundled reimbursement covers 21-day stays with daily prosthetist adjustments.
- Homecare:Remote fitting protocols via 3D scanning expand access in rural Australia and northern Canada where specialist density falls below one prosthetist per 100,000 population.
- Specialty Clinics:Independent orthotic and prosthetic practices in Texas and Florida face margin pressure from health system unbundling of device acquisition from professional services.
Rehabilitation centers sit at the top of the volume ranking, with homecare climbing the fastest as telehealth protocols mature.
Technology:
Technology tiers separate passive mechanical systems from powered alternatives, with myoelectric signal processing now automating grip selection that previously required extensive patient training.
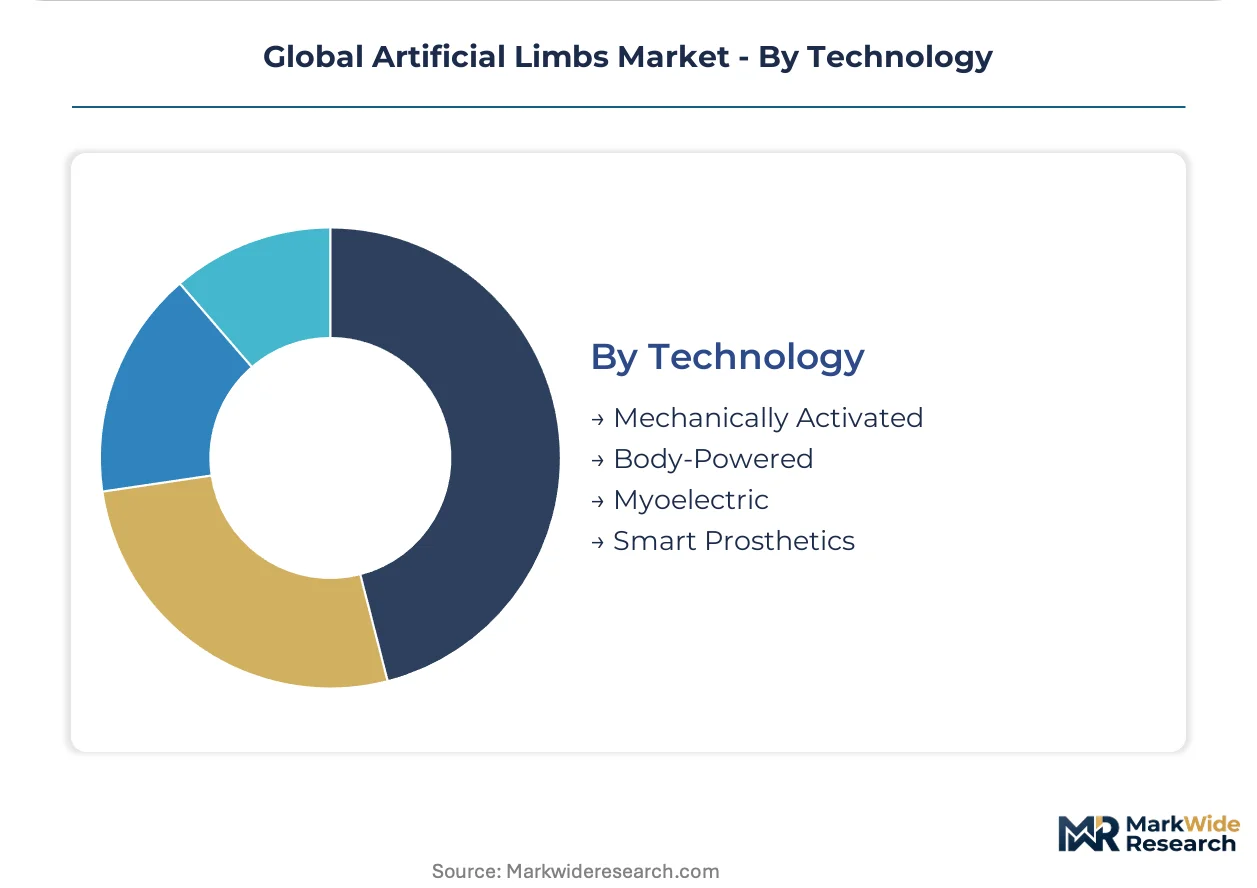
- Mechanically Activated:Cable-operated body-powered hooks and hands retain dominance in emerging markets and industrial applications where durability trumps cosmetic appearance. These devices require no batteries and withstand dust, moisture, and temperature extremes that disable electronic systems.
- Body-Powered:Harness and cable systems transmit shoulder motion to terminal devices through Bowden cables, offering proprioceptive feedback that myoelectric units cannot replicate. German statutory insurance maintains preferential reimbursement for these systems in manual labor occupations.
- Myoelectric:Surface electrode arrays detect muscle activation patterns to control multi-articulating hands. FDA breakthrough device designations for Coapt Engineering and Infinite Biomedical algorithms compress approval timelines.
- Smart Prosthetics:Machine learning-enabled systems with IMU sensors and cloud connectivity adjust knee resistance in real-time for terrain adaptation.
Body-powered systems sit at the top of the volume ranking, with myoelectric technology climbing the fastest as pattern recognition eliminates manual mode-switching.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified prosthetist concentrations in the United States, Germany, and Japan anchor the highest-volume fitting corridors for advanced myoelectric systems. These three markets concentrate the specialist labor pools required for multi-articulating hand calibration and microprocessor knee gait training.
United States
VA healthcare systems generate guaranteed demand pools for service-connected amputees through expanded reimbursement for multi-articulating hands and microprocessor knees. FDA breakthrough device designations compress neural-controlled prosthetic approvals from 36 months to under 18 months. The Boston-Philadelphia corridor anchors complex trauma reconstruction with academic medical centers performing osseointegration surgery.
Germany
Statutory insurers maintain 3-5 year replacement schedules for mechanical components while preferring body-powered systems in manual labor occupations. EMA and EU MDR recertification deadlines force technical documentation rebuilds for legacy Class IIa devices. The Schön Klinik network provides intensive 21-day inpatient gait training for bilateral transfemoral amputees with daily prosthetist adjustments.
Japan
Aging demographics and trauma care infrastructure drive volume for transfemoral and transtibial applications. METI and PMDA frameworks govern structural testing and biocompatibility certification for powered devices. Kameda Medical Center and manufacturing belt rehabilitation facilities integrate wrist rotators for industrial amputees.
India
Production-linked incentive schemes attract contract manufacturers to establish carbon fiber fabrication facilities in Gujarat and Tamil Nadu. BIS standards and CDSCO medical device regulations shape domestic certification pathways. Vacuum-formed thermoplastic check sockets reach price points accessible in emerging reimbursement environments.
Australia
Remote fitting protocols via 3D scanning and video consultation expand specialist access in rural territories where prosthetist density falls below one per 100,000 population. TGA regulations align with ISO 10328 structural validation protocols. Northern territory health systems pilot telehealth socket adjustment programs.
Global Artificial Limbs Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the prosthetic value chain, with carbon fiber fabricators and myoelectric algorithm developers occupying distinct risk-return profiles. The market structures around three tiers: integrated patient care networks, component specialists, and regional fabrication shops. Strategic moves concentrate on M&A for clinic network expansion and technology licensing for pattern recognition software.
Within the integrated care tier, Hanger, Inc. and Ottobock exemplify vertically structured models spanning clinical fitting through rehabilitation services. Össur occupies a position among Icelandic-origin manufacturers with carbon fiber manufacturing scale. These three anchors represent divergent approaches to capturing margin across device acquisition and professional service components.
| Leading Market Players |
|---|
| Össur |
| Ottobock |
| Hanger, Inc. |
| Ohio Willow Wood Company |
| Blatchford Group |
| Fillauer LLC |
| PROTEOR |
| RSL Steeper Group Ltd. |
| WillowWood Global LLC. |
| Others |
Supply & Pricing Matrix
Automated carbon fiber layup processes in Germany and Japan are compressing per-unit socket costs while concentrating manufacturing scale among a handful of pre-preg suppliers, simultaneously reshaping cost economics and supply concentration for high-performance transfemoral components.
Pricing Analysis
The bundled-vs-unbundled service split is fragmenting procurement economics across US health systems. Hospital supply chains now source modular transtibial components through centralized contracts while regional orthotic and prosthetic clinics retain fitting-service premiums, creating price differentiation between device acquisition and professional calibration. Margins are tightening in the transtibial segment as volume purchasing agreements exclude full-service providers. Pediatric and geriatric amputees exhibit highest price sensitivity, while veterans hospitals and trauma centers demonstrate lowest sensitivity due to guaranteed reimbursement pools.
Supply Chain Analysis
ISO 10328 fatigue testing and FDA breakthrough device qualification gating filter supplier participation, extending product development timelines and favoring incumbents with dedicated regulatory affairs capacity. Carbon fiber pre-preg manufacturing concentrates in Iceland, Germany, and Japan, while titanium 6Al-4V alloy feedstock draws from Russian and Chinese refiners. Single-source vulnerability in aerospace-grade titanium exposes Western fabricators to sanctions risk and input cost volatility. Distribution runs through vertically integrated patient care networks, component specialists, and regional fabrication shops serving hospital procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial limbs market reads as a late-cycle quality story where myoelectric signal processing advances are shifting demand toward premium multi-articulating systems with automated grip selection, rewarding manufacturers with algorithm development capabilities and regulatory clearance velocity.
For Market Incumbents: Hedge titanium supply exposure by qualifying alternative alloy sources and accelerating carbon fiber socket fabrication automation. Consolidate regional orthotic and prosthetic clinic networks to capture fitting-service premiums threatened by hospital procurement unbundling. Deepen backward integration into pre-preg carbon fiber manufacturing to offset material cost volatility from Icelandic and Japanese suppliers.
For New Entrants and Emerging Players: India's PLI scheme for medical devices opens a window for contract manufacturers to establish thermoplastic and carbon fiber fabrication in Gujarat and Tamil Nadu, serving domestic reimbursement expansion and export markets. Target telehealth fitting protocols in rural Australia and northern Canada where prosthetist density falls below specialist thresholds. Pursue software licensing arrangements with myoelectric control algorithm developers rather than competing for hardware certification.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication shops with certified prosthetist workforces but limited device manufacturing scale, offering bolt-on capacity for integrated care networks. Long-term viability hinges on positioning for osseointegration surgery convergence and percutaneous abutment maintenance services. Watch FDA breakthrough device designation velocity as the inflection signal for myoelectric innovation cycles compressing from 36 months toward 18 months.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates neural-controlled prosthetic approvals, compressing time-to-market for myoelectric innovations. |
| Carbon Fiber Manufacturing Scale-Up | Automated layup processes in Germany and Japan reduce per-unit socket costs for high-performance transfemoral applications. |
| Osseointegration Surgery Partnership | Academic medical centers in Boston and Philadelphia anchor direct skeletal attachment, eliminating socket complications. |
| Telehealth Fitting Protocol Development | 3D scanning and video consultation expand specialist access in rural territories with prosthetist shortages. |
| Reimbursement Strategy Alignment | Veterans Affairs coverage expansion for multi-articulating hands creates guaranteed demand pools for service-connected amputees. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and Australia, with primary inputs from each market's certified prosthetists, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Secondary validation draws from FDA 510(k) filings, EMA submissions, CMS Medicare reimbursement databases, and ISO 10328 structural testing protocols. Bottom-up patient-volume estimates and top-down manufacturer revenue triangulation anchor market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, material, technology tier, and end-user channel dimensions. CAGRs derive from fitted trend extrapolation moderated by replacement-cycle timing, reimbursement calendar alignment, and prosthetist capacity constraints. Forecast inputs incorporate veterans hospital procurement data, statutory insurance replacement schedules, and telehealth protocol adoption curves.
Revisions become necessary when titanium supply disruptions, EU MDR recertification delays, or prosthetist certification bottlenecks materialize beyond modeled scenarios. Forecasts reflect assumptions about reimbursement stability and algorithm-enabled myoelectric adoption. A model refresh is warranted upon material change in FDA breakthrough device approval velocity or India's PLI scheme incentive structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radial Head Resection Implant Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Cheek Implants Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Thrombectomy System Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Venturi Mask Market
Medical Devices
LAMEA Breast Pumps Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Brain-On-Chip Model Market