
 Interventional Oncology Ablation Market | 2026-2036
Interventional Oncology Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional Oncology Ablation Market Insights
The outpatient surgery center vertical is broadening faster than the hospital channel as payors push same-day oncology procedures. Medtronic plc leverages its integrated navigation platforms to anchor the radiofrequency ablation segment. Boston Scientific Corporation sustains R&D intensity across thermal and non-thermal modalities. AngioDynamics Inc. specializes in vascular access and oncology catheter systems that compete alongside ablation hardware.
Interventional oncology ablation encompasses percutaneous and intraoperative techniques that destroy malignant tissue through thermal, cryogenic, or electrical energy delivery, typically guided by cross-sectional imaging with probe temperatures reaching 60–100°C for coagulative necrosis. Microwave ablation systems achieve faster heating profiles and larger ablation zones than radiofrequency platforms, drawing capital investment from centers treating hepatic and lung tumors. CT-guided technology occupies the largest installed base among imaging modalities, though MRI-guided systems command premium positioning for soft-tissue visualization during kidney and bone tumor procedures.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for ablation system approvals. The Environmental Protection Agency and OSHA maintain workplace exposure limits for cryogenic agents used in cryoablation suites. Stakeholders must monitor reimbursement coding revisions for percutaneous tumor ablation as Medicare and private payors recalibrate site-of-service differentials between hospitals and ambulatory centers.
Market Dynamics
The migration of tumor ablation procedures from inpatient hospital suites to ambulatory surgery centers is compressing capital deployment cycles and forcing manufacturers to redesign systems for smaller footprints and faster turnover protocols.
Growth Catalysts
- Same-day reimbursement parity:Medicare site-of-service differentials now favor outpatient settings, accelerating capital allocation to freestanding interventional suites.
- Microwave thermal profiles:Faster heating cycles and larger ablation zones enable treatment of larger hepatic lesions in single sessions.
- MDR harmonization:Stricter EU clinical evidence standards are elevating barrier-to-entry for marginal competitors, consolidating share among validated platform holders.
Market Restraints
- Cryogen supply concentration:Liquid nitrogen and argon sourcing clusters in industrial gas hubs, exposing cryoablation operators to freight cost volatility and cold-chain failure risk.
- Probe cost structure:Single-use disposable components constitute 40-60% of per-procedure economics, limiting margin flexibility for high-volume centers.
- Technical limitation in lung:Pneumothorax rates and respiratory motion artifact constrain percutaneous lung tumor ablation adoption relative to hepatic applications.
Strategic Opportunities
- Japan's aging tumor burden:Hepatocellular carcinoma incidence and constrained surgical capacity create addressable white space for image-guided thermal ablation.
- MRI-thermometry convergence:Real-time temperature mapping during ablation enables precision dosing in renal and bone tumors previously excluded from thermal protocols.
- Direct-to-ambulatory distribution:Bypassing traditional hospital purchasing committees through specialty distributor networks accelerates capital equipment placement.
Industry Challenges
- Interventional radiology workforce gaps:Fellowship-trained operators remain concentrated in academic medical centers, limiting procedure volume expansion in community settings.
- 510(k) predicate drift:FDA clearance pathways for next-generation ablation systems face heightened scrutiny as predicates age and technological discontinuities emerge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional Oncology Ablation Market |
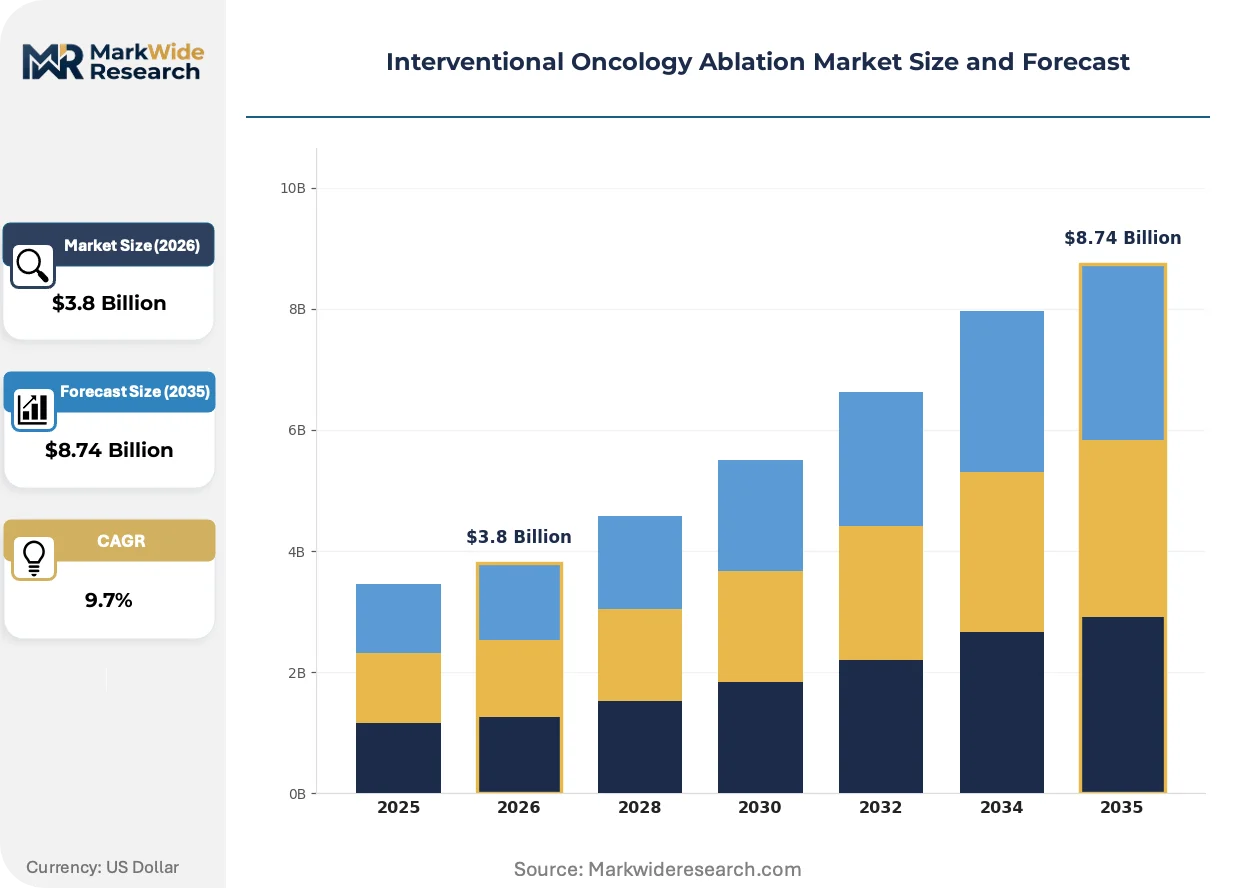
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
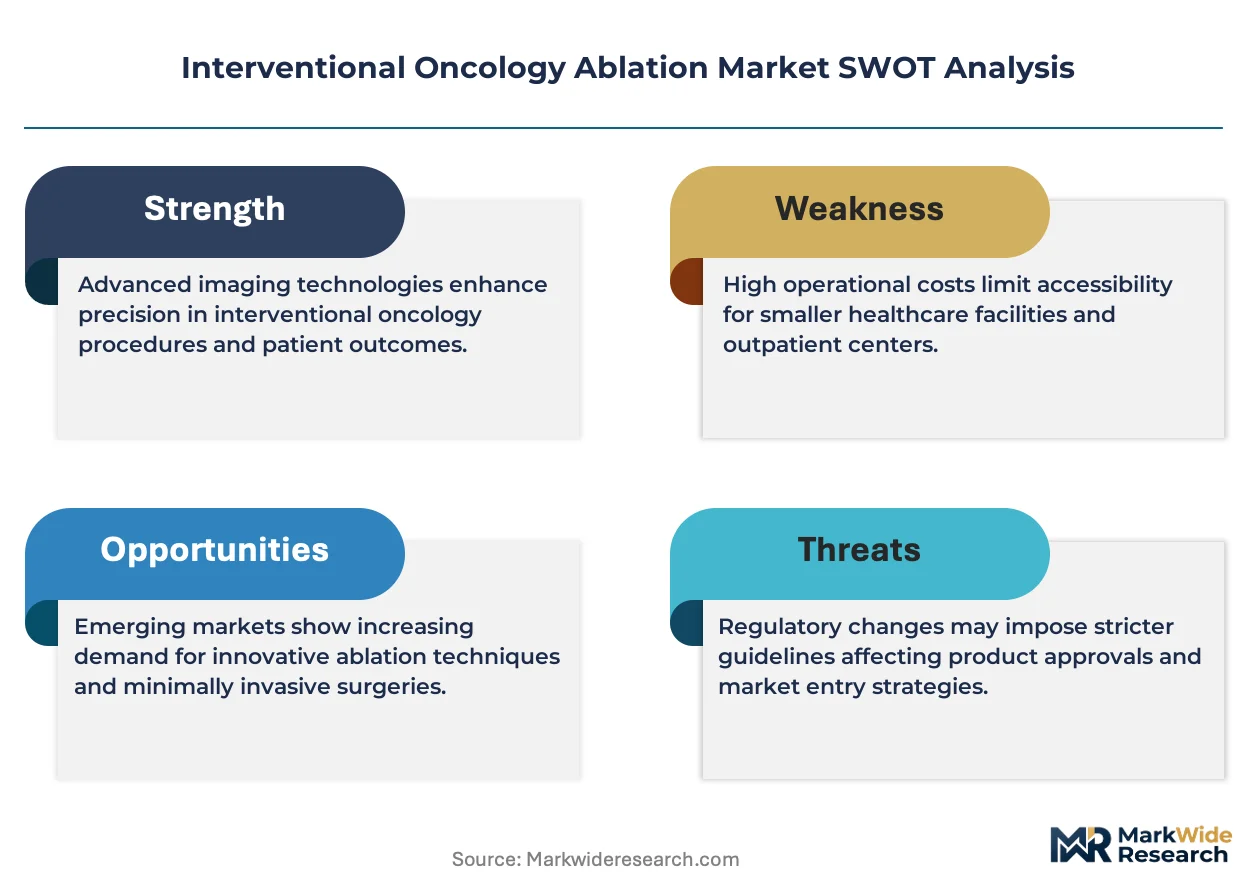
| Segmentation | Product Type: Radiofrequency Ablation, Microwave Ablation, Cryoablation, Laser Ablation End User: Hospitals, Outpatient Surgery Centers, Specialty Clinics, Research Institutions Technology: Ultrasound-Guided, CT-Guided, MRI-Guided, Fluoroscopy-Guided Application: Hepatic Tumors, Lung Tumors, Kidney Tumors, Bone Tumors |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, AngioDynamics Inc., Siemens Healthineers, Terumo Corporation, Johnson & Johnson, Merit Medical Systems, Cook Medical, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional Oncology Ablation Market Trends and Innovations
Energy delivery modalities and imaging guidance architectures are converging to enable procedure migration outside traditional operating theaters, with software-defined control systems displacing fixed-parameter hardware.
Irreversible electroporation systems are decentralizing oncologic intervention by enabling non-thermal tumor destruction near critical structures. Outpatient surgery centers in the United States and Germany are adopting these platforms for pancreatic and prostate applications previously reserved for surgical resection. The technology is decentralizing treatment planning authority from academic tumor boards to community interventional suites.
The EU Medical Device Regulation imposes post-market surveillance obligations and clinical evidence standards that extend approval timelines for novel ablation modalities. Manufacturers must maintain technical documentation and periodic safety reporting across notified body jurisdictions. Small-cap entrants without established quality management systems face disproportionate compliance burdens relative to platform incumbents.
Service contracting is displacing capital purchase models as ambulatory surgery centers seek to convert fixed equipment costs into variable per-procedure expenses. Leasing structures with utilization-based pricing are gaining traction among multi-site operators managing cash flow across procedure mix fluctuations. Germany and Japan exhibit the strongest uptake of equipment-as-a-service arrangements in interventional oncology.
Interventional Oncology Ablation Market Segmentation
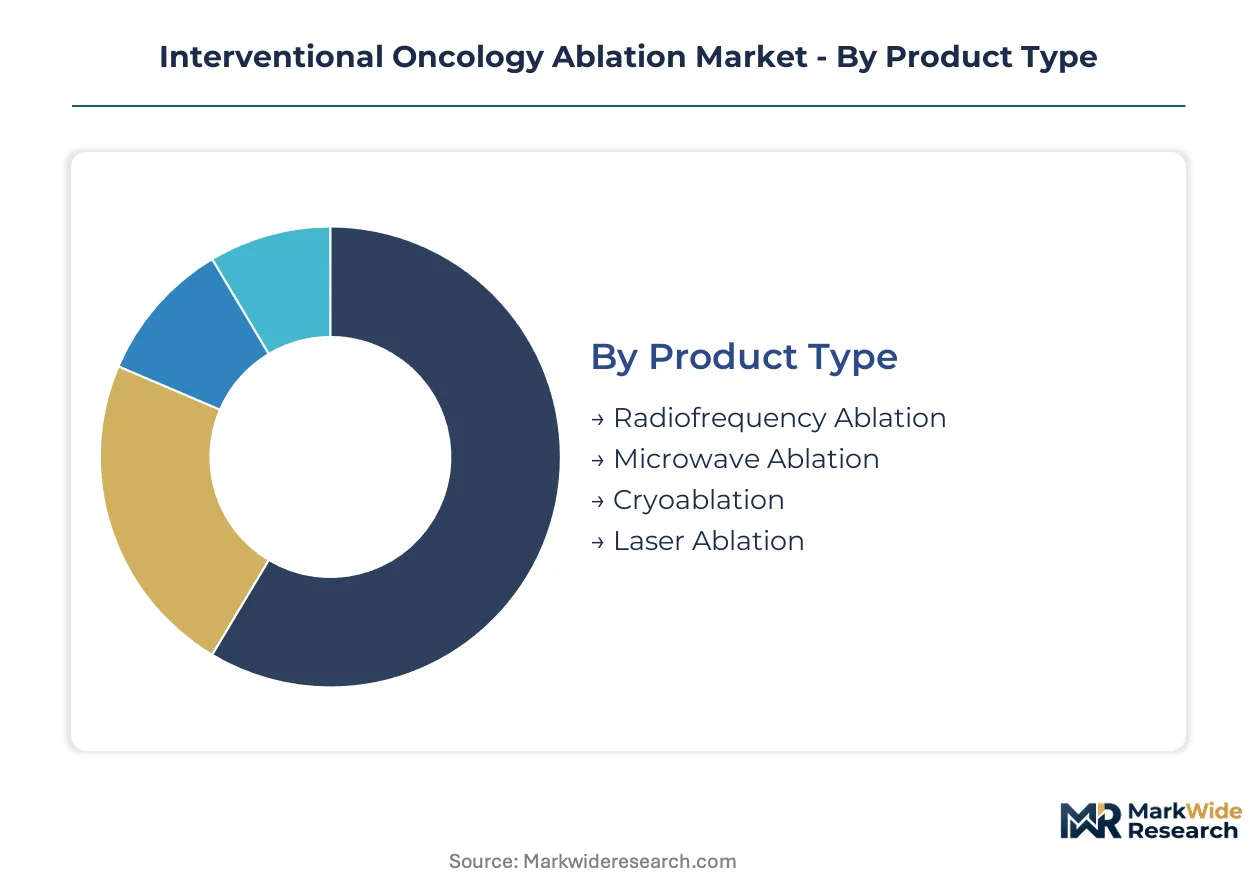
Energy modality selection and imaging guidance architecture determine capital allocation patterns across treatment settings. Site-of-service economics and reimbursement differentials reshape demand concentration by end-user category. Procedure migration toward ambulatory environments compresses equipment footprint requirements while elevating throughput specifications.
Product Type:
Radiofrequency platforms dominate installed base volume while microwave systems command premium positioning through faster thermal profiles. Cryogenic and laser modalities occupy specialized niches with distinct clinical risk-reward profiles.
- Radiofrequency Ablation:Electrode-based thermal delivery achieves coagulative necrosis at 60–100°C through resistive heating. United States hospital networks favor this modality for hepatic lesions given established reimbursement codes and predicate device familiarity. Probe cost concentration in single-use disposables constrains margin flexibility at high-volume centers.
- Microwave Ablation:Electromagnetic field heating generates larger ablation zones with faster rise times than radiofrequency equivalents. German outpatient surgery centers allocate capital to these systems for lung and hepatic applications where single-session treatment of larger lesions reduces patient throughput bottlenecks. Equipment footprint requirements exceed radiofrequency platforms, limiting placement in smaller ambulatory suites.
- Cryoablation:Argon-helium gas cycling creates precisely controlled freeze-thaw cycles for tumor destruction near critical structures.
- Laser Ablation:Fiber-optic thermal delivery enables minimally invasive access to anatomically constrained lesions with MRI compatibility.
Today's leader: Radiofrequency Ablation. Tomorrow's challenger: Microwave Ablation.
End User:
Capital deployment cycles diverge sharply between integrated hospital networks and freestanding surgical facilities. Reimbursement parity legislation accelerates site-of-service migration while reshaping equipment financing structures.
- Hospitals:Academic medical centers maintain comprehensive interventional radiology suites with multi-modality imaging integration. Japan's constrained surgical capacity concentrates complex ablation procedures in tertiary hospital settings where fellowship-trained operators manage larger tumor burdens. Capital budgets favor platform purchases with service contracting overlays.
- Outpatient Surgery Centers:Freestanding facilities pursue same-day discharge protocols with compressed room turnover requirements. United States Medicare site-of-service differentials now favor ambulatory settings, accelerating capital allocation to these environments. Equipment-as-a-service arrangements convert fixed costs to variable per-procedure expenses.
- Specialty Clinics:Focused oncology practices concentrate specific tumor types with dedicated operator expertise.
- Research Institutions:Academic research hospitals evaluate next-generation modalities through clinical trial infrastructure.
Outpatient Surgery Centers are expanding most quickly; Hospitals retain the largest procedure volume concentration.
Technology:
Imaging modality selection determines soft-tissue resolution capabilities and real-time thermometry access. CT platforms maximize installed base while MRI systems command premium positioning for precision applications.
- CT-Guided:Cross-sectional anatomical visualization with rapid image acquisition supports high-throughput hepatic and lung procedures. United States community hospital networks standardize on CT-guided platforms given radiologist familiarity and capital cost accessibility. Respiratory motion artifact management remains a technical limitation in thoracic applications.
- MRI-Guided:Superior soft-tissue contrast enables real-time temperature mapping during renal and bone tumor ablation. German academic centers allocate premium capital to these systems for procedures near critical structures where precision dosing reduces complication rates. Longer procedure times and higher equipment costs constrain adoption in volume-focused settings.
- Ultrasound-Guided:Real-time imaging without ionizing radiation supports superficial lesion access and intraoperative applications.
- Fluoroscopy-Guided:Continuous X-ray visualization enables vascular access and probe positioning in interventional suites.
CT-Guided systems anchor current installed base. MRI-Guided platforms show the steepest expansion trajectory in precision oncology.
Application:
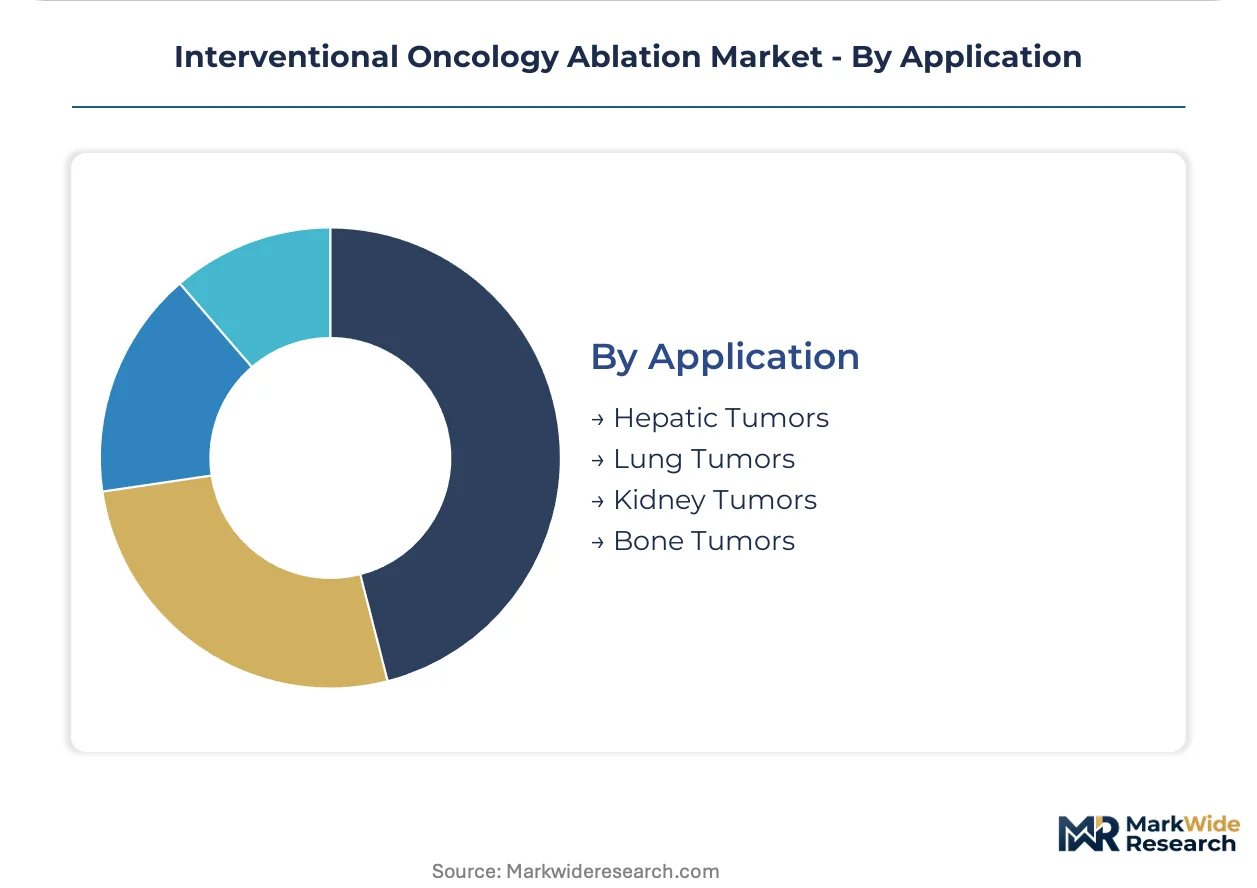
Anatomical site determines technical feasibility, complication risk profiles, and reimbursement pathway maturity. Hepatic applications dominate volume while lung and renal sites present distinct adoption barriers.
- Hepatic Tumors:Hepatocellular carcinoma and metastatic colorectal lesions represent the most established ablation indications with mature reimbursement frameworks. Japan's aging tumor burden and constrained surgical capacity create sustained demand concentration for image-guided thermal destruction of primary liver malignancies. Microwave systems gain share for larger lesions previously requiring staged procedures.
- Lung Tumors:Percutaneous ablation of primary and metastatic pulmonary lesions encounters pneumothorax risk and respiratory motion challenges. United States academic centers develop specialized protocols for high-risk surgical candidates, though adoption lags hepatic applications significantly. Cryoablation platforms show particular utility near pleural surfaces where thermal spread requires precise control.
- Kidney Tumors:Small renal masses in elderly or comorbid patients increasingly undergo thermal ablation as active surveillance alternatives.
- Bone Tumors:Metastatic bone lesion palliation utilizes thermal and cryogenic modalities for pain control and local tumor control.
Hepatic Tumors command current procedure volume leadership. Lung Tumors present the largest unaddressed clinical opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA 510(k) pathways and EU MDR compliance costs is redirecting R&D investment toward jurisdictions with faster commercialization timelines. Manufacturers now prioritize market entry sequencing that exploits these cost-of-compliance gaps.
United States
Outpatient surgery centers drive capital deployment as Medicare site-of-service differentials favor ambulatory settings. FDA 510(k) premarket notification requirements govern device clearance, though predicate drift is extending review timelines for next-generation systems. The Greater Boston and Minneapolis-St. Paul clusters concentrate interventional radiology training programs and early-stage ablation technology development.
Germany
Academic medical centers maintain premium MRI-guided ablation capacity for precision renal and bone tumor applications. EU MDR imposes stricter clinical evidence standards and post-market surveillance obligations, elevating barriers for marginal competitors. The Baden-Württemberg region anchors equipment-as-a-service adoption among multi-site ambulatory operators.
Japan
Aging hepatocellular carcinoma incidence and constrained surgical capacity create sustained demand for image-guided thermal ablation. PMDA regulatory frameworks align with international standards while METI industrial policy supports domestic medical device manufacturing. The Kanto region around Tokyo concentrates tertiary hospital infrastructure and fellowship-trained interventional radiology specialists.
China
Expanding hospital infrastructure in tier-2 and tier-3 cities is broadening access to percutaneous tumor ablation beyond academic centers. NMPA medical device registration requirements are harmonizing with international standards, accelerating market access for validated platform holders. The Yangtze River Delta cluster around Shanghai concentrates domestic ablation system manufacturing and imaging equipment integration capabilities.
United Kingdom
NHS reimbursement frameworks are recalibrating site-of-service incentives to reduce inpatient procedural costs. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining approval pathways for innovative modalities. The London-Southeast corridor concentrates private ambulatory surgery center investment and interventional oncology service line expansion.
Interventional Oncology Ablation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated navigation platform holders commanding premium positioning in hospital networks while focused catheter specialists penetrate ambulatory channels. The vendor base concentrates among three strategic tiers: diversified medical technology conglomerates with cross-modal imaging integration, mid-cap ablation modality pure-plays, and vascular access specialists extending into oncology applications. Dominant competitive moves include strategic partnerships for imaging-therapeutic convergence and geographic licensing arrangements to bypass direct regulatory submission burdens.
Within the diversified medical technology tier, Medtronic plc and Boston Scientific Corporation occupy positions as archetypal platform holders with integrated navigation and multi-modality energy delivery capabilities. AngioDynamics Inc. exemplifies the vascular access-to-oncology extension archetype. Siemens Healthineers and Terumo Corporation represent imaging-therapeutic convergence specialists leveraging diagnostic installed bases for procedural equipment placement.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| AngioDynamics Inc. |
| Siemens Healthineers |
| Terumo Corporation |
| Johnson & Johnson |
| Merit Medical Systems |
| Cook Medical |
| Stryker Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive supply of argon and helium through long-term industrial gas partnerships anchors both cryoablation manufacturers' supply security and their premium pricing power against competitors dependent on spot markets. This integration choice insulates validated platform holders from freight cost volatility while forcing smaller entrants into unfavorable third-party supply contracts that compress margins.
Pricing Analysis
Distributor margin layers in the United States absorb 15-25 points before equipment reaches ambulatory surgery centers. Three-tier pricing structure across premium navigation-integrated systems, standard thermal platforms, and economy radiofrequency generators reflects FDA predicate familiarity and imaging compatibility grades. Cost compression in the economy tier intensifies because outpatient centers negotiate volume-based service contracts that convert capital purchases to per-procedure expenses. Community hospital networks exhibit highest price sensitivity; academic medical centers with research funding show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for probe and catheter inventory. Component sourcing draws from Malaysia for electronic assemblies, Ireland for precision gas valves, and Minnesota for imaging navigation hardware. Single-source vulnerability concentrates in superconducting magnet cryogen supplies for MRI-guided systems. Distribution runs through specialty medical device distributors with GPO contracting relationships rather than direct manufacturer-to-hospital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Interventional Oncology Ablation Market compounds steadily as aging tumor burdens in Japan and Germany sustain procedure volume expansion regardless of macroeconomic cycles.
For Market Incumbents: Deepen backward integration into disposable probe manufacturing to capture the 40-60% cost component currently outsourced to contract manufacturers. Lock in multi-year service contracts with United States outpatient surgery centers before Medicare site-of-service differentials shift again. Microwave ablation specialists threaten radiofrequency installed bases through faster thermal profiles; defend by accelerating MRI-thermometry software development. For New Entrants and Emerging Players: Freestanding ambulatory surgery centers in the United Kingdom's NHS reimbursement recalibration zones represent an underserved buyer archetype with compressed procurement cycles and limited incumbent relationships. Japan's constrained surgical capacity creates white space for image-guided thermal ablation in hepatocellular carcinoma. Enter through equipment-as-a-service leasing structures that convert capital barriers to per-procedure partnerships. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap ablation modality pure-plays because EU MDR compliance costs disproportionately burden smaller competitors without established quality management systems. Five-to-ten year viability hinges on imaging-therapeutic convergence capabilities rather than single-modality hardware. Watch FDA 510(k) predicate drift scrutiny as the inflection signal: heightened review timelines will accelerate consolidation among platform holders with aging predicate libraries.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Predicate device selection determines review timeline for next-generation thermal platforms. |
| CE Marking under EU MDR | Clinical evidence requirements elevate barriers for marginal competitors in European markets. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate purchasing authority across multiple sites. |
| Software Companion Development | Real-time MRI-thermometry integration enables precision dosing in renal and bone applications. |
| Reimbursement Strategy | CPT code maintenance determines site-of-service economics between hospitals and ambulatory centers. |
Research Methodology
Multiple input streams — primary interviews with interventional radiologists and hospital purchasing committees, secondary validation against CMS Medicare reimbursement databases and FDA 510(k) filings, and trade data from industrial gas supply chains — were reconciled through bottom-up and top-down triangulation. Conversations with GPO contracts managers, biomedical engineers, and outpatient surgery center administrators informed equipment procurement cycle dynamics. Secondary sources included hospital procurement databases, EU MDR notified body documentation, and PMDA submission records.
Data-stream reconciliation across energy modality segmentation, imaging guidance architecture, and end-user category dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from procedure volume trajectories and capital equipment replacement cycles modeled against reimbursement pathway maturity. Industry-specific forecast inputs incorporated hepatocellular carcinoma incidence curves and fellowship-trained operator pipeline constraints.
Underlying measurement precision varies by segment; hepatic tumor applications carry tighter precision than lung ablation given established reimbursement codes and mature procedure protocols. Forecasts reflect assumptions about Medicare site-of-service parity maintenance and EU MDR compliance cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Thymus Cancer Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Esophageal Cancer Market
Oncology
Global Proton Therapy Market
Oncology
Pituitary Cancer Market
Oncology
Gynecological Cancers Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Global Interventional Oncology Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Oncology Devices Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Tumor Lysis Syndrome Treatment Market