
 C-Arms Market | 2026-2036
C-Arms Market Size, Share, and Industry Trends Forecast 2026-2036
C-Arms Market Intelligence
Equipment leasing and pay-per-use financing is reconfiguring competitive dynamics in the C-Arms market, lowering capital barriers for mid-tier hospitals and ambulatory surgical centers. Siemens Healthineers leverages its service network to anchor long-term contracts across European hospital systems. GE Healthcare competes through backward integration into flat panel detector manufacturing, securing component supply. Ziehm Imaging specializes in mobile surgical C-arms, dominating intraoperative imaging for orthopedic and trauma applications.
C-Arms are articulated X-ray imaging systems with a C-shaped gantry connecting an X-ray source and detector, typically operating at 50-110 kVp with real-time fluoroscopic output for surgical guidance. Flat panel C-arms have displaced image intensifier technology in premium segments due to superior spatial resolution and reduced dose profiles. Mobile C-arms command the largest installed base, though digital C-arms with pulsed fluoroscopy represent the fastest-growing technology tier as hospitals prioritize dose reduction. Orthopedic surgery generates the highest procedure volume, while cardiovascular applications sustain premium pricing due to specialized detector requirements and integration with hemodynamic monitoring.
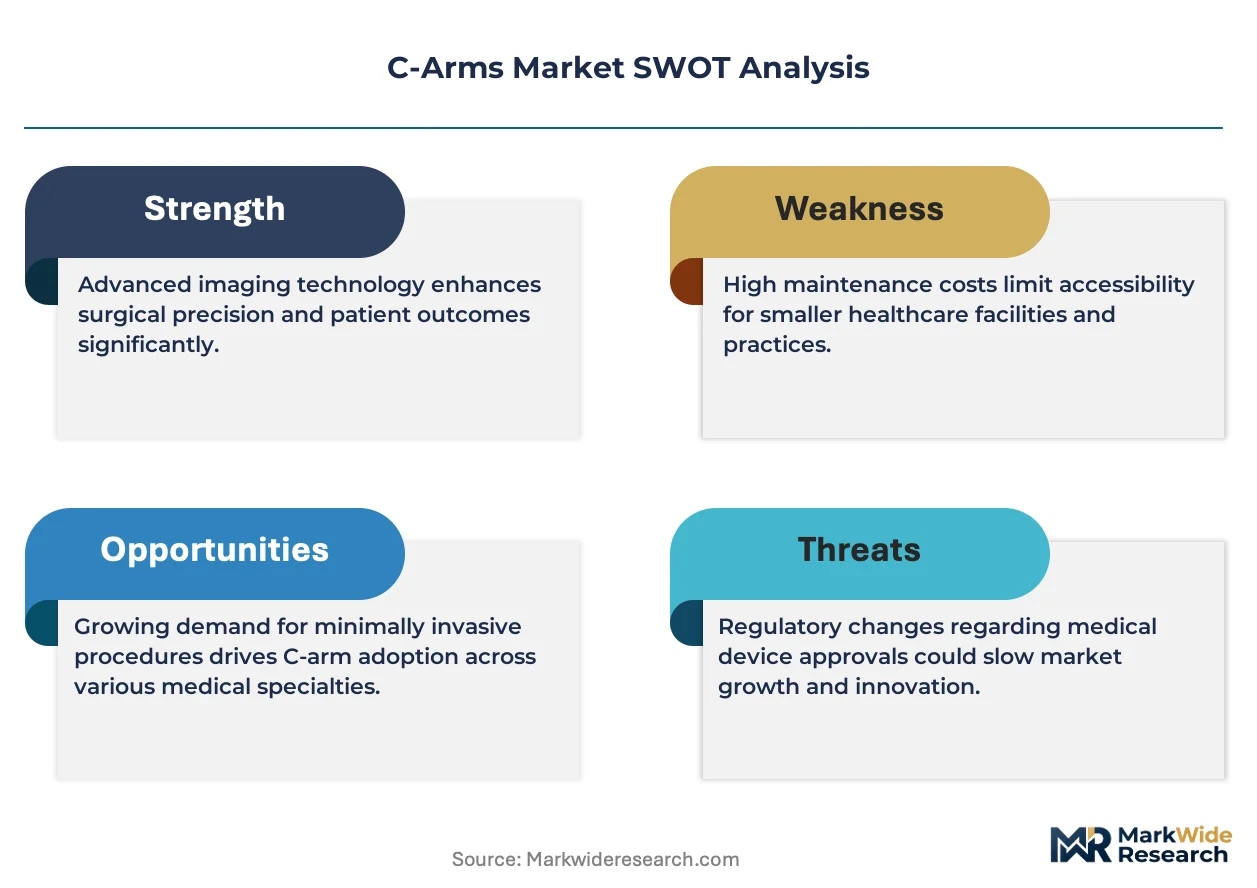
The FDA's 510(k) clearance framework governs device approval in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for fluoroscopy systems sold in Europe. Both frameworks elevate compliance costs for new entrants but reinforce incumbent positions among manufacturers with established quality management systems. Japan's PMDA maintains distinct standards for radiation dose reporting that shape product configurations for the Asian market. Stakeholders must monitor reimbursement shifts for outpatient surgical imaging, as ambulatory surgical center expansion and site-of-care migration redefine volume distribution across customer segments.
Market Dynamics
Flat panel detector technology is collapsing the installed base of image intensifier C-arms, compressing replacement cycles and redistributing procurement power toward health systems with centralized capital planning.
Growth Catalysts
- Outpatient surgical migration:Ambulatory surgical centers in Germany are deploying mini C-arms for same-day orthopedic discharge, bypassing inpatient imaging queues.
- FDA 510(k) pathway:Streamlined digital radiography upgrades accelerate hardware refresh timelines for US hospital networks.
- Dose reduction mandates:EU Medical Device Regulation fluoroscopy requirements push European facilities toward pulsed fluoroscopy systems with automated exposure control.
Market Restraints
- Flat panel supply concentration:Detector manufacturing clusters in South Korea and Japan create single-source vulnerability for mid-tier OEMs.
- Capital intensity barrier:Premium flat panel C-arms require cath lab infrastructure that rural US hospitals cannot amortize.
- Image intensifier residual value:Secondary market refurbishment in India and Southeast Asia delays full technology displacement.
Strategic Opportunities
- Pay-per-use financing:Equipment leasing models unlock ambulatory surgical center penetration without balance sheet strain.
- AI-integrated surgical navigation:Convergence of fluoroscopy with machine learning guidance creates premium pricing for spine and trauma applications.
- Japan PMDA dose reporting:Specialized product configurations for Asian regulatory requirements open differentiated service contracts.
Industry Challenges
- Clinical engineering talent scarcity:Flat panel calibration and detector replacement require specialized biomedical technician certification that outpaces training pipeline output.
- Legacy system integration:PACS connectivity standards vary across hospital networks, forcing custom interface development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | C-Arms Market |
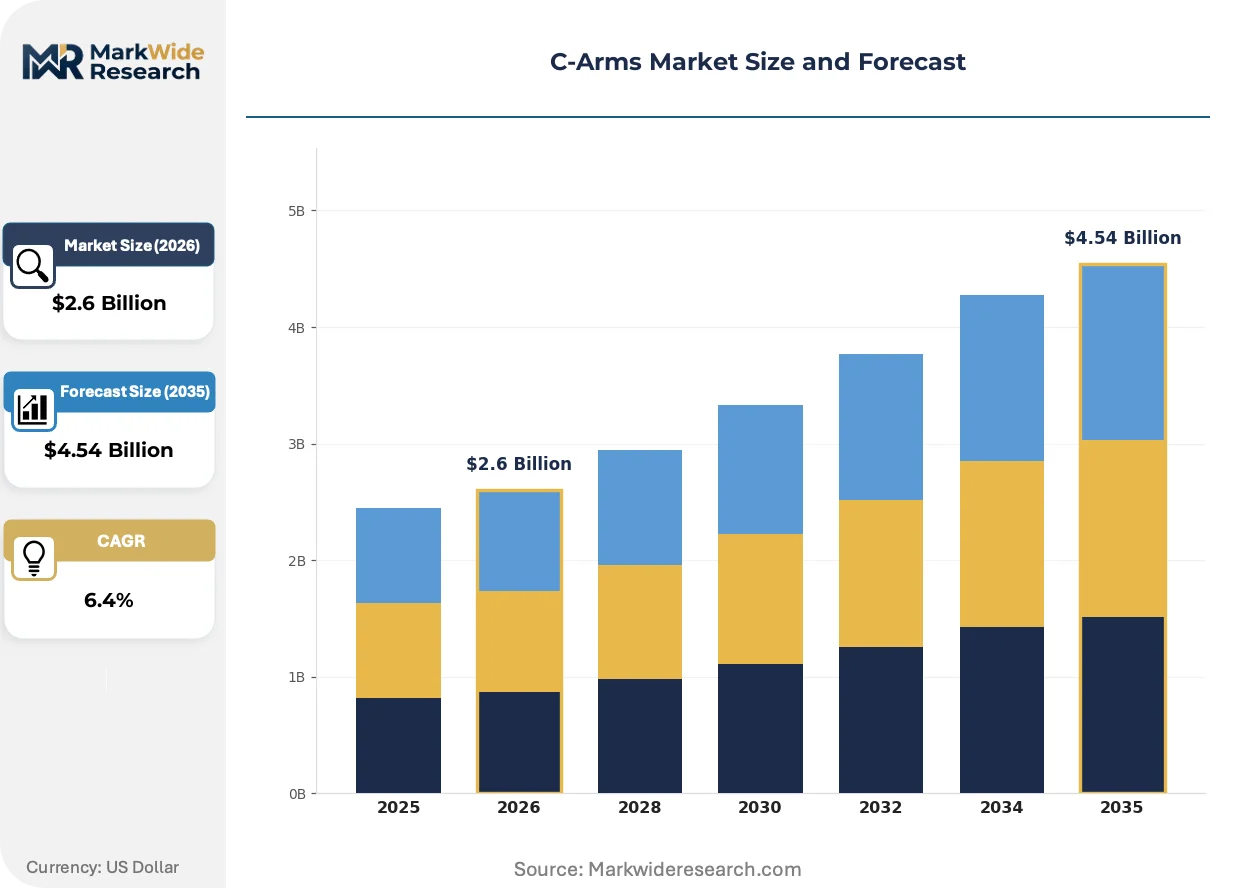
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.54 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile C-Arms, Fixed C-Arms, Mini C-Arms, Flat Panel C-Arms, Digital C-Arms Technology: Fluoroscopy, Cone Beam CT, Digital Radiography, Pulsed Fluoroscopy, Image Intensifier Application: Orthopedic Surgery, Cardiovascular Procedures, Pain Management, Urology, Gastroenterology End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Clinics, Specialty Clinics, Trauma Centers |
| Companies Covered | Ziehm Imaging, Hologic, Inc., GE Healthcare, DMS Imaging, Canon Medical Systems Corporation, Siemens Healthineers, Shimadzu Corporation, Orthoscan, Inc., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
C-Arms Market Strategic Shifts & Innovations
Digital detector technology is collapsing the economic viability of legacy imaging chains while regulatory pressure on radiation exposure forces simultaneous hardware and software upgrades across installed bases.
CMOS flat panel detectors are collapsing the cost-performance gap that previously protected image intensifier market share. Orthopedic surgery suites in German and US hospital systems are adopting these detectors for trauma and extremity procedures. The technology is collapsing service revenue models built on vacuum tube replacement cycles.
EU Medical Device Regulation clinical evidence requirements for fluoroscopy systems are elevating documentation burdens for new market entrants. Established manufacturers with ISO 13485 quality management systems capture disproportionate share of European tenders. Cardiovascular C-arm configurations face the steepest compliance cost escalation due to hemodynamic monitoring integration complexity.
Site-of-care migration is fragmenting procurement authority away from hospital radiology departments toward ambulatory surgical center administrators. Equipment financing specialists and third-party leasing firms are displacing traditional capital equipment sales channels in the US and Germany. This shift concentrates most visibly in outpatient orthopedic networks seeking monthly payment structures over lump-sum acquisition.
C-Arms Market Segmentation
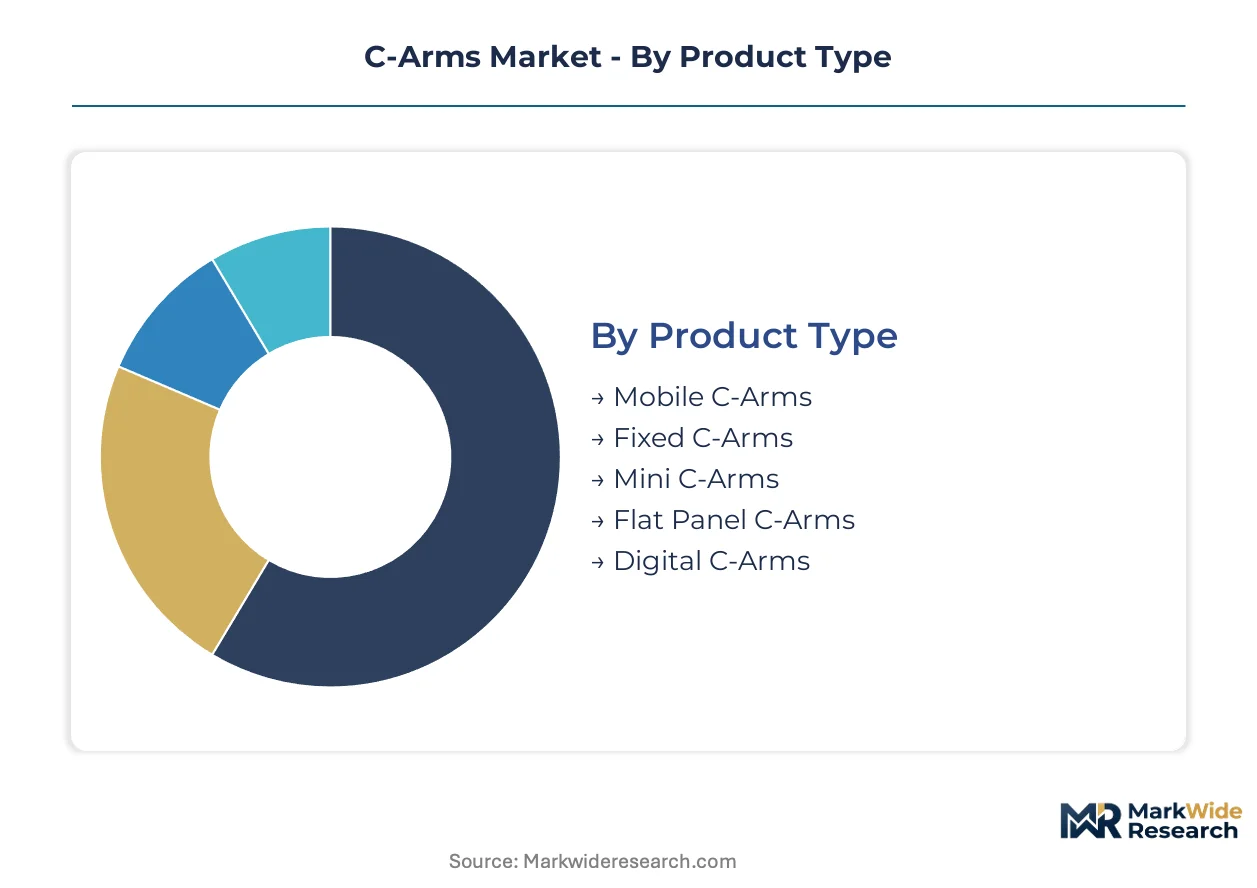
C-Arms segmentation reveals distinct procurement patterns across product tiers and clinical settings. Technology trajectories and site-of-care economics determine margin structures and replacement cycles for each category.
Product Type:
Use-case spectrum spans high-volume trauma suites to specialized outpatient extremity imaging, with mobility and detector architecture as primary differentiators.
- Mobile C-Arms:Articulated gantry systems mounted on motorized bases enable intraoperative positioning across OR suites. German hospital networks and US health systems concentrate procurement here for orthopedic and trauma throughput, driven by flexibility demands across multi-specialty surgical schedules.
- Flat Panel C-Arms:Solid-state digital detectors replace vacuum tube image intensifiers, delivering superior spatial resolution at reduced radiation dose. Demand clusters in cardiovascular suites requiring high-frame-rate fluoroscopy, where dose reduction mandates from EU MDR accelerate displacement of legacy systems.
- Mini C-Arms:Compact extremity-focused systems serve ambulatory surgical centers with space-constrained footprints.
- Fixed C-Arms:Permanent installation systems anchor dedicated cardiac catheterization laboratories with integrated hemodynamic monitoring.
- Digital C-Arms:Pulsed fluoroscopy variants with automated exposure control address regulatory dose reporting requirements in Japan and Europe.
The dominant share belongs to Mobile C-Arms, while Flat Panel C-Arms is closing the gap fastest.
Technology:
Cost tier stratification separates premium integrated systems from legacy equipment facing accelerated obsolescence.
- Fluoroscopy:Continuous X-ray beam imaging enables real-time surgical guidance with frame rates exceeding 30 fps. Cardiac catheterization labs in US academic medical centers sustain premium pricing for this modality despite dose exposure concerns.
- Digital Radiography:Static high-resolution capture supports pre-operative planning and post-operative verification workflows. German outpatient orthopedic networks favor this technology for same-day discharge protocols, leveraging streamlined FDA 510(k) upgrade pathways.
- Cone Beam CT:Three-dimensional volumetric reconstruction from rotational fluoroscopy data enables intraoperative navigation.
- Pulsed Fluoroscopy:Intermittent X-ray emission reduces cumulative dose while maintaining temporal resolution for interventional guidance.
- Image Intensifier:Vacuum tube-based analog detection persists in secondary markets through refurbishment channels in India and Southeast Asia.
Fluoroscopy retains installed base leadership, though Digital Radiography is expanding most quickly through upgrade cycles.
Application:
Volume concentration in high-procedure specialties contrasts with premium pricing in technically complex interventions.
- Orthopedic Surgery:Extremity fixation, spine instrumentation, and joint replacement procedures generate the highest annual imaging volume. Ambulatory surgical centers in Germany and the US deploy mini C-arms here for cost-efficient same-day discharge.
- Cardiovascular Procedures:Percutaneous coronary intervention and electrophysiology mapping demand specialized large-field detectors with hemodynamic integration. Japanese PMDA dose reporting requirements shape product configurations for this segment.
- Pain Management:Fluoroscopy-guided injections and nerve blocks utilize compact mobile systems in outpatient settings.
- Urology:Endourological procedures leverage C-arm guidance for percutaneous nephrolithotomy and stent placement.
- Gastroenterology:ERCP and biliary interventions require specialized detector geometries for abdominal imaging.
Orthopedic Surgery commands procedure volume leadership, while Cardiovascular Procedures sustains the steepest expansion trajectory through technology premiumization.
End User:
Customer type determines capital deployment models and service contract structures across centralized and distributed care networks.
- Hospitals:Integrated delivery networks consolidate procurement authority for multi-system deployments, favoring long-term service agreements with OEMs. Siemens Healthineers anchors contracts across European hospital systems through preventive maintenance networks.
- Ambulatory Surgical Centers:Outpatient facilities prioritize pay-per-use financing and equipment leasing to avoid balance sheet strain. German orthopedic networks and US independent ASCs concentrate mini C-arm demand here.
- Diagnostic Clinics:Standalone imaging centers seek versatile systems supporting multiple procedural types.
- Specialty Clinics:Orthopedic and pain management focused practices require dedicated extremity imaging capacity.
- Trauma Centers:Level I emergency departments mandate 24/7 mobile fluoroscopy availability for polytrauma response.
Hospitals retain procurement volume dominance, while Ambulatory Surgical Centers is gaining share fastest through site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in advanced imaging equipment concentrate manufacturing in Germany, Japan, and the United States, while demand growth accelerates in outpatient surgical networks across Western Europe and North America. Trade flows reflect detector component dependencies from South Korean and Japanese suppliers feeding assembly operations in Düsseldorf and Milwaukee. Regulatory divergence between FDA 510(k) pathways and EU MDR compliance costs is fragmenting product configurations by destination market.
United States
Ambulatory surgical centers in Texas and Florida are deploying mini C-arms for outpatient orthopedic volume, bypassing inpatient imaging queues. The FDA's streamlined 510(k) clearance for digital radiography upgrades accelerates hardware refresh cycles across US hospital networks. GE Healthcare anchors manufacturing and service operations in Wisconsin, feeding domestic health system contracts with backward integration into flat panel detector supply.
Germany
Hospital consolidation in North Rhine-Westphalia and Bavaria drives centralized procurement of premium flat panel systems by integrated delivery networks. The EU Medical Device Regulation imposes stricter clinical evidence requirements for fluoroscopy systems, elevating compliance costs that reinforce incumbent positions. Siemens Healthineers leverages its service network across German hospital systems to anchor long-term preventive maintenance contracts.
Japan
PMDA dose reporting standards shape specialized product configurations for cardiovascular C-arm deployments in Tokyo and Osaka academic medical centers. Domestic manufacturers face import competition in flat panel detectors while maintaining edge in pulsed fluoroscopy integration. Shimadzu Corporation anchors production in Kyoto, serving Asian markets with regulatory-tailored system variants.
India
Secondary market refurbishment of image intensifier C-arms in Delhi-Mumbai corridors delays full technology displacement by premium flat panel systems. The country's national pharmaceutical regulator maintains distinct import licensing requirements for radiation-emitting devices that shape product entry strategies. Mid-tier hospitals in Maharashtra and Karnataka rely on refurbished equipment channels from Southeast Asian trading networks.
South Korea
Flat panel detector manufacturing clusters in Suwon and Seoul create single-source vulnerability for mid-tier OEMs sourcing solid-state digital components. Domestic health technology procurement favors local assembly partnerships for mobile C-arm systems serving orthopedic networks in Gyeonggi Province. Samsung and LG display technology divisions supply detector substrates to global imaging equipment assemblers.
C-Arms Market Key Industry Players
On the supply side, the industry is consolidating around integrated imaging conglomerates with captive detector manufacturing and long-term service networks. Three strategic archetypes dominate: full-stack manufacturers with backward integration into flat panel production, specialized mobile surgical C-arm vendors, and diversified health technology conglomerates leveraging cross-modal service infrastructure. Competitive moves concentrate on M&A for detector technology access and geographic expansion through leasing partnerships.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the full-stack archetype with integrated manufacturing and service footprints. Ziehm Imaging occupies a specialist position exemplifying the mobile surgical C-arm pure-play model. These three anchors represent distinct competitive vectors—service network density, component supply security, and clinical application focus—that structure procurement decisions across German hospital systems and US ambulatory surgical networks.
| Leading Market Players |
|---|
| Ziehm Imaging |
| Hologic, Inc. |
| GE Healthcare |
| DMS Imaging |
| Canon Medical Systems Corporation |
| Siemens Healthineers |
| Shimadzu Corporation |
| Orthoscan, Inc. |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Flat panel detector supply concentration in South Korea and Japan determines both premium-tier pricing spreads and the geographic shape of C-arm assembly networks. This single-source dependency for solid-state digital components compresses margins for mid-tier OEMs while reinforcing pricing power for integrated manufacturers with captive detector supply.
Pricing Analysis
Hospital procurement committees anchor C-arm pricing through multi-year service bundling and centralized capital planning across integrated delivery networks. Pricing stratifies across premium flat panel systems with AI-integrated navigation, standard mobile configurations for orthopedic throughput, and refurbished image intensifier units serving cost-constrained facilities. Cost compression in the standard tier intensifies as ambulatory surgical centers demand pay-per-use financing structures over lump-sum acquisition. German hospital systems exhibit the least price sensitivity due to consolidated procurement authority, while independent ASCs in the US demonstrate acute sensitivity to total cost of ownership.
Supply Chain Analysis
Extended payment terms from South Korean detector suppliers strain working capital for European and North American OEMs assembling finished systems. Manufacturing clusters center on Germany, Japan, and the United States for final C-arm assembly, while CMOS substrate production feeds from Samsung and LG display divisions in Suwon and Seoul. Raw material dependencies include amorphous silicon panels, scintillator crystals, and precision-machined gantry components. Single-source vulnerability in detector substrates creates exposure to export licensing shifts. Distribution runs through direct OEM service networks for hospital systems and third-party leasing firms for ambulatory surgical center penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
C-arm incumbents face substitution pressure from intraoperative CT and 3D navigation systems that bypass fluoroscopy entirely for complex spine procedures. Defense of installed base requires preemptive technology integration before clinical workflows migrate to alternative imaging modalities.
For Market Incumbents: Pre-empt flat panel detector supply disruption by securing long-term offtake agreements with South Korean substrate manufacturers or accelerating in-house CMOS production capabilities. Anchor hospital system loyalty through preventive maintenance contracts that embed proprietary calibration protocols, raising switching costs against competitors. Counter the intraoperative CT substitution threat by integrating cone beam CT reconstruction into mobile C-arm platforms, preserving fluoroscopy's real-time guidance advantage.
For New Entrants and Emerging Players: Mini C-arm leasing for US ambulatory surgical centers in Texas and Florida represents the most penetrable entry point, bypassing capital-intensive cath lab infrastructure requirements. Refurbished image intensifier systems for Indian secondary markets offer volume scale without premium detector supply constraints. A pay-per-use financing go-to-market angle aligns with ASC administrator procurement authority and avoids balance sheet strain objections.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors detector technology specialists and AI-integrated navigation platforms over legacy equipment assemblers. Long-term viability across a 5-10 year window rests on software-enabled service revenue streams rather than hardware shipment volumes. Acquisition targets should demonstrate installed base density in German hospital networks or proprietary flat panel calibration IP. The signal to watch is ambulatory surgical center reimbursement parity with inpatient settings, which would accelerate site-of-care migration and reshape volume distribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Flat Panel Detector Backward Integration | Captive CMOS supply secures component availability against South Korean export constraints. |
| AI-Integrated Surgical Navigation Development | Machine learning guidance commands premium pricing for spine and trauma applications. |
| Pay-per-Use Financing Program Launch | Equipment leasing unlocks ambulatory surgical center penetration without capital expenditure barriers. |
| EU MDR Compliance Certification Investment | ISO 13485 quality systems capture disproportionate share of European hospital tenders. |
| Hospital System Preventive Maintenance Partnership | Long-term service contracts embed Siemens Healthineers across German integrated delivery networks. |
Research Approach
A spread of perspectives from hospital purchasing committee directors, ambulatory surgical center administrators, biomedical engineering managers, and flat panel detector procurement leads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and GPO pricing benchmarks. Bottom-up triangulation across detector shipment volumes and top-down reconciliation against health system capital expenditure disclosures anchored the market sizing framework.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, modeling segmentation by product mobility tier, detector architecture, clinical application specialty, and end-user facility type. CAGRs derived from replacement cycle compression rates and site-of-care migration patterns, with fluoroscopy dose regulation stringency and reimbursement parity shifts as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, medical device import tariffs, or radiation safety regulation enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding technology substitution rates and supply chain resiliency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Specialty PACS Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Dental Imaging Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Italy Digital X-Ray Market