
 France Minimally Invasive Surgery Devices Market | 2026-2036
France Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Minimally Invasive Surgery Devices Market Foresight
The EU Green Deal's medical device sustainability criteria is consolidating purchasing power around energy-efficient surgical platforms and reusable instrument systems. Stryker Corporation leverages its endoscopy portfolio to anchor positions in French public hospital networks. Siemens Healthineers sustains R&D intensity in imaging-integrated surgical navigation across the country's university hospital centers. Intuitive Surgical dominates robotic-assisted procedure volumes through specialized training partnerships with regional surgical clusters.
Minimally invasive surgery devices encompass instruments, visualization systems, electrosurgical tools, and robotic platforms engineered for percutaneous or natural-orifice access with reduced tissue disruption, typically operating through 5-12 mm ports with high-definition or 3D optical feedback. These systems enable shorter recovery cycles and lower complication rates in abdominal, thoracic, and joint procedures. Robotic surgery systems command premium positioning due to capital intensity and dedicated service contracts, while laparoscopy instruments constitute the highest-volume segment driven by routine cholecystectomy and hernia repair volumes. Electrosurgical equipment captures concentrated margin pools through disposable blade and generator upgrade cycles in France's blended public-private procurement environment.
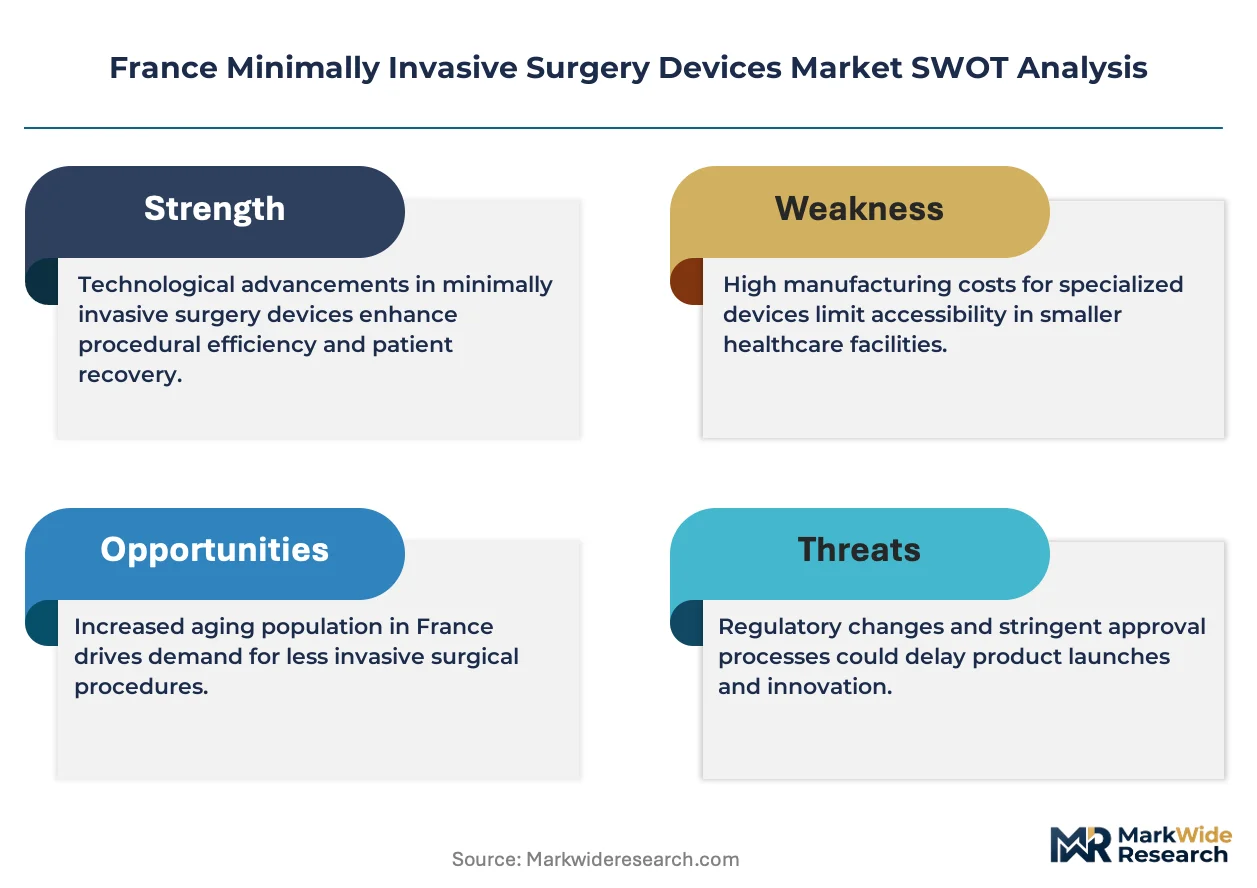
ANSM oversees clinical evaluation and post-market surveillance of active implantable and class III surgical devices, while the EU MDR transition mandates expanded technical documentation and notified body recertification for legacy products. France's HAS (Haute Autorité de Santé) health technology assessment framework shapes reimbursement velocity and hospital capital allocation toward proven minimally invasive platforms. Stakeholders must monitor MDR implementation timelines and HAS evaluation criteria to anticipate access bottlenecks and prioritize evidence generation for novel surgical technologies entering French procurement channels.
Market Dynamics
The EU MDR recertification timeline is compressing procurement cycles for legacy surgical platforms while ANSM intensifies post-market surveillance requirements, forcing device manufacturers to accelerate clinical evidence generation and hospital buyers to consolidate supplier relationships around compliant portfolios.
Growth Catalysts
- EU Green Deal procurement mandates:Public hospital networks now prioritize energy-efficient surgical platforms and reusable instrument systems, redirecting capital toward sustainable device categories.
- Auvergne-Rhône-Alpes surgical cluster expansion:Regional university hospital centers are scaling robotic-assisted procedure volumes through dedicated training infrastructure and outcome-based reimbursement pilots.
- HAS accelerated assessment pathways:The health technology assessment framework is streamlining evaluation timelines for proven minimally invasive platforms, reducing access bottlenecks for novel surgical technologies.
Market Restraints
- Notified body capacity constraints:EU MDR transition has created severe bottlenecks in technical documentation review, delaying market entry for class III surgical devices by 12-18 months.
- Capital intensity of robotic platforms:Dedicated service contracts and per-procedure consumables lock public hospitals into long-term financial commitments that crowd out laparoscopy investments.
- Single-use instrument cost inflation:Electrosurgical blade and trocar supply chains face input cost pressure from specialized polymer and ceramic sourcing constraints.
Strategic Opportunities
- Ile-de-France private hospital networks:Underpenetrated ambulatory surgical centers present white space for compact laparoscopy platforms with flexible leasing structures.
- Imaging-integrated navigation convergence:Real-time fluorescence overlay and augmented reality guidance systems are creating new procedure categories in hepatobiliary and colorectal surgery.
- ANSM innovation fast-track:The national regulator's priority review pathway for breakthrough surgical devices offers accelerated market access for first-in-class visualization systems.
Industry Challenges
- Robotic surgery credentialing gaps:Regional surgical clusters face acute shortages of proctors certified for advanced platform training, constraining procedure volume scaling.
- Legacy laparoscope integration friction:Hospital IT infrastructure requires costly middleware upgrades to accommodate 4K and 3D visualization standards alongside existing endoscopy towers.
- MDR technical documentation complexity:Expanded clinical evaluation requirements for legacy electrosurgical generators are consuming disproportionate regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Minimally Invasive Surgery Devices Market |
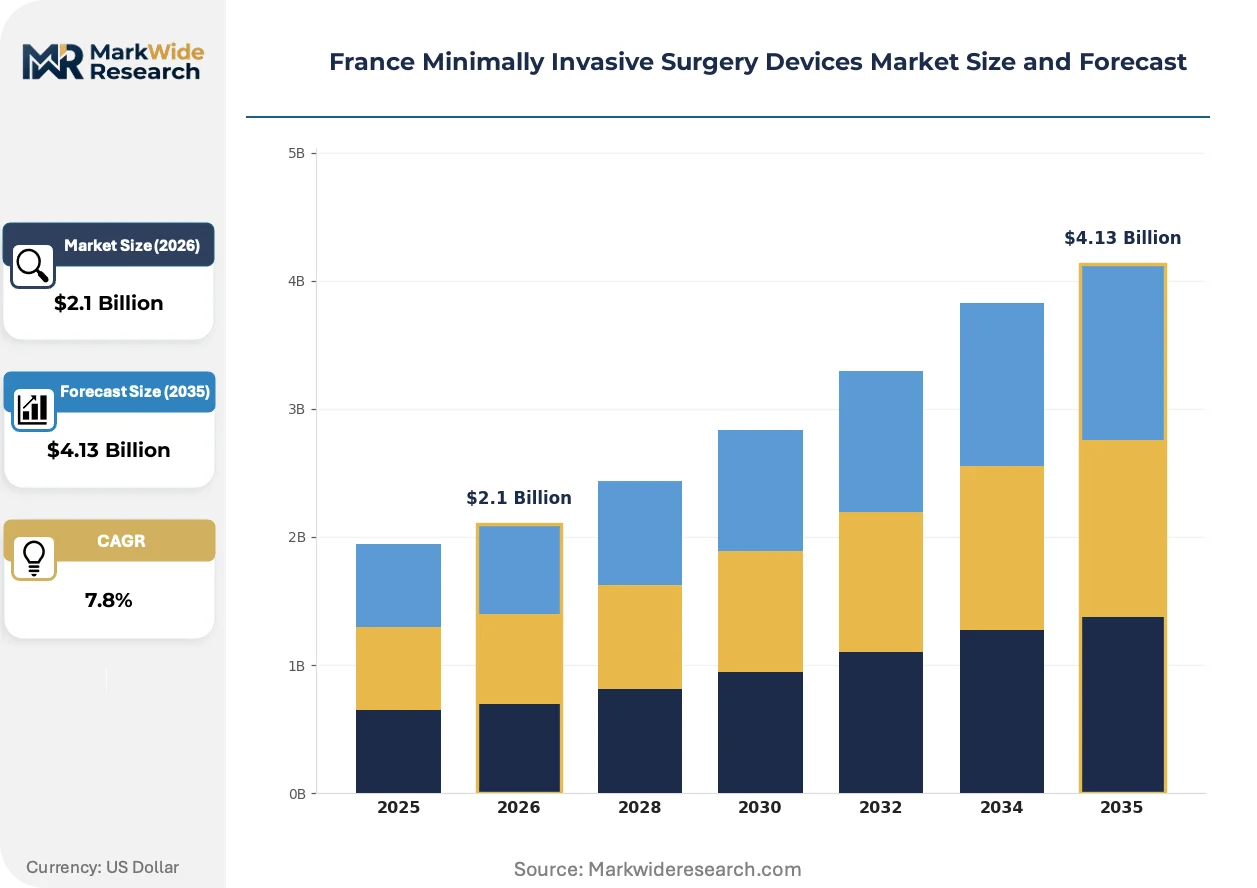
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopy Instruments, Endoscopic Devices, Robotic Surgery Systems, Electrosurgical Equipment, Visualization Systems Application: Gastrointestinal Surgery, Cardiothoracic Procedures, Urology Treatments, Gynecological Operations, Orthopedic Interventions End User: Public Hospitals, Private Clinics, Specialized Surgical Centers, Ambulatory Surgical Facilities Technology: High-Definition Imaging, 3D Visualization, Wireless Connectivity, Artificial Intelligence Integration, Haptic Feedback |
| Companies Covered | Smith & Nephew PLC, Siemens Healthineers, Stryker Corporation, Koninklijke Philips NV, General Electric Company (GE Healthcare), Intuitive Surgical Inc, Zimmer Biomet, Karl Storz GmbH, Olympus Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Minimally Invasive Surgery Devices Market Shifts & Advancements
Digital surgical platforms are redefining intraoperative decision support through real-time data integration, while sustainability imperatives reshape instrument lifecycle economics and procurement evaluation criteria across French hospital networks.
Single-port robotic access systems are electrifying abdominal surgery by collapsing multiple instrument channels through one 25mm entry point. CHU clusters in Lyon and Paris are piloting these platforms for colorectal resections, compressing conversion rates to open surgery and reducing trocar-site complications that drive readmission costs.
France's ANSM alignment with EU MDR Article 10 technical documentation requirements is elevating post-market clinical follow-up obligations for active surgical devices. Manufacturers must now maintain systematic procedure registries, which favors incumbent portfolios with established surveillance infrastructure over novel entrants lacking longitudinal data.
Hospital purchasing consortia are consolidating bargaining power through multi-year framework agreements that bundle capital equipment, disposables, and training services. The GCS Sante publique network in Ile-de-France is displacing transactional spot-buying with outcome-guaranteed contracts that tie supplier payments to complication rate thresholds and equipment uptime metrics.
France Minimally Invasive Surgery Devices Market Segmentation
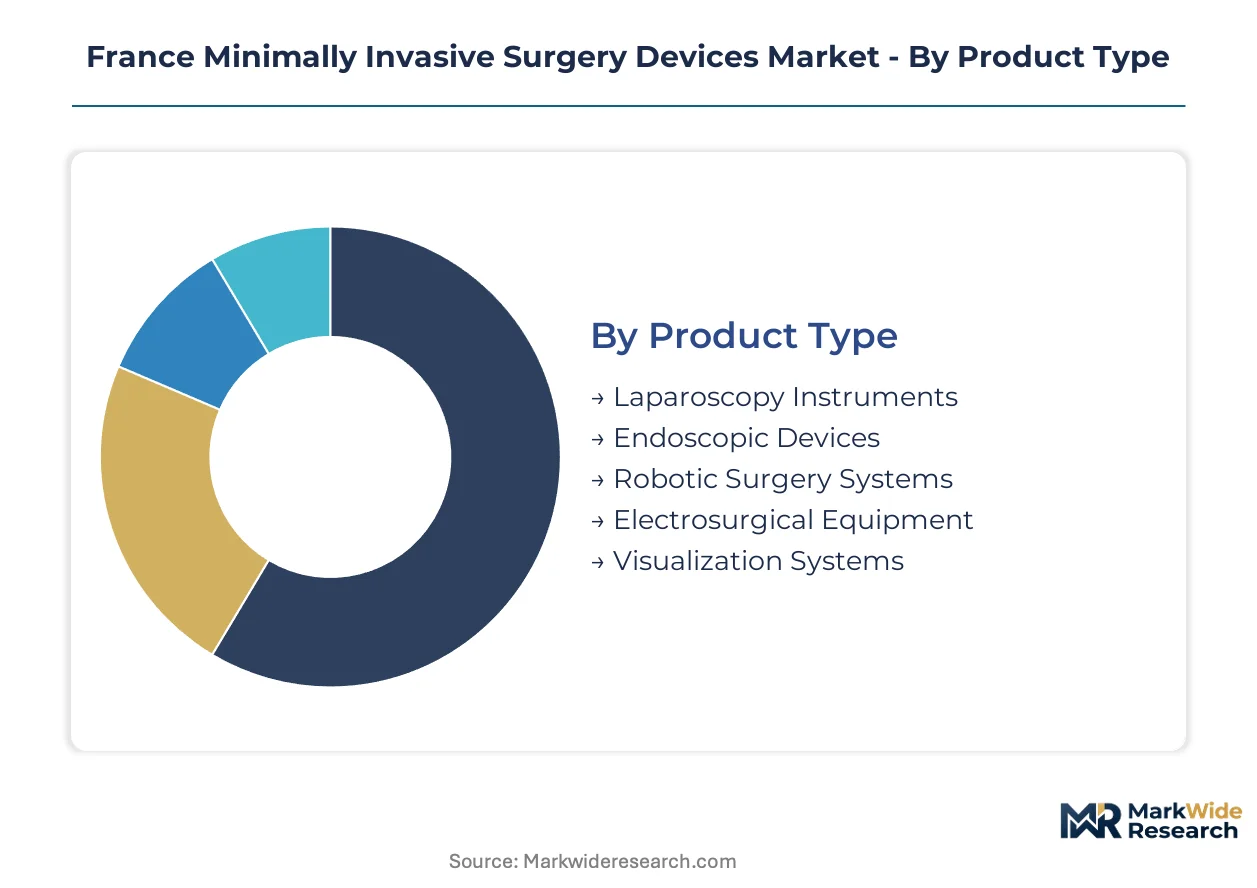
Device segmentation in France reflects divergent capital allocation strategies across public hospital networks and private surgical facilities. Procurement patterns differ sharply between high-volume laparoscopy platforms and capital-intensive robotic systems, with reimbursement velocity and HAS assessment outcomes determining segment prioritization.
Product Type:
Standalone instruments dominate high-volume abdominal procedures, while integrated platforms anchor specialized surgical clusters requiring coordinated visualization and robotic assistance.
- Laparoscopy Instruments:Trocars, graspers, and scissors engineered for 5-12mm port access constitute the highest-procedure-volume category. Public hospital procurement in Ile-de-France concentrates here for routine cholecystectomy and hernia repair volumes, constrained by single-use polymer cost inflation.
- Robotic Surgery Systems:Capital-intensive platforms with dedicated service contracts and per-procedure consumables command premium positioning. Auvergne-Rhône-Alpes university hospital clusters scale volumes through specialized training infrastructure and outcome-based reimbursement pilots.
- Endoscopic Devices:Flexible scopes and accessory channels for natural-orifice procedures serve diagnostic and therapeutic gastrointestinal workflows.
- Electrosurgical Equipment:Generators and disposable blades capture concentrated margin pools through upgrade cycles in France's blended procurement environment.
- Visualization Systems:4K and 3D optical towers requiring middleware integration with legacy hospital IT infrastructure.
Volume placements concentrate in Laparoscopy Instruments; the faster expansion belongs to Robotic Surgery Systems.
Application:
Procedure complexity and reimbursement tiers reshape demand concentration across surgical specialties, with abdominal interventions anchoring baseline volumes and cardiac procedures driving technology premiums.
- Gastrointestinal Surgery:Colorectal resections and hepatobiliary procedures absorb the largest device volumes across French public hospital networks. Lyon CHU clusters pilot single-port robotic access for these interventions, compressing conversion rates to open surgery.
- Gynecological Operations:Hysterectomy and myomectomy volumes sustain dedicated minimally invasive service lines in regional university hospitals. HAS accelerated assessment pathways streamline reimbursement for proven platforms in this category.
- Urology Treatments:Prostatectomy and nephrectomy procedures drive robotic platform utilization in specialized centers.
- Cardiothoracic Procedures:Valve repair and lung resection applications demand imaging-integrated navigation with premium capital requirements.
- Orthopedic Interventions:Arthroscopy platforms serve sports medicine and joint replacement preparation across ambulatory settings.
Reimbursement velocity favors Gynecological Operations; steepest expansion trajectory belongs to Cardiothoracic Procedures.
End User:
Capital intensity thresholds and procurement autonomy separate centralized public purchasing from decentralized private facility decision-making.
- Public Hospitals:CHU networks and regional hospital groups dominate capital equipment procurement through GCS Sante publique framework agreements. Bundled contracts tie supplier payments to complication rate thresholds and equipment uptime metrics.
- Private Clinics:Underpenetrated ambulatory surgical centers in Ile-de-France present white space for compact laparoscopy platforms with flexible leasing structures.
- Specialized Surgical Centers:Focused facilities concentrate robotic-assisted volumes through dedicated proctor networks.
- Ambulatory Surgical Facilities:Same-day discharge requirements favor disposable instrument systems and rapid-cycle sterilization workflows.
Procurement scale concentrates in Public Hospitals; margin expansion belongs to Private Clinics.
Technology:
Digital integration depth separates legacy optical platforms from next-generation systems embedding real-time data and autonomous guidance.
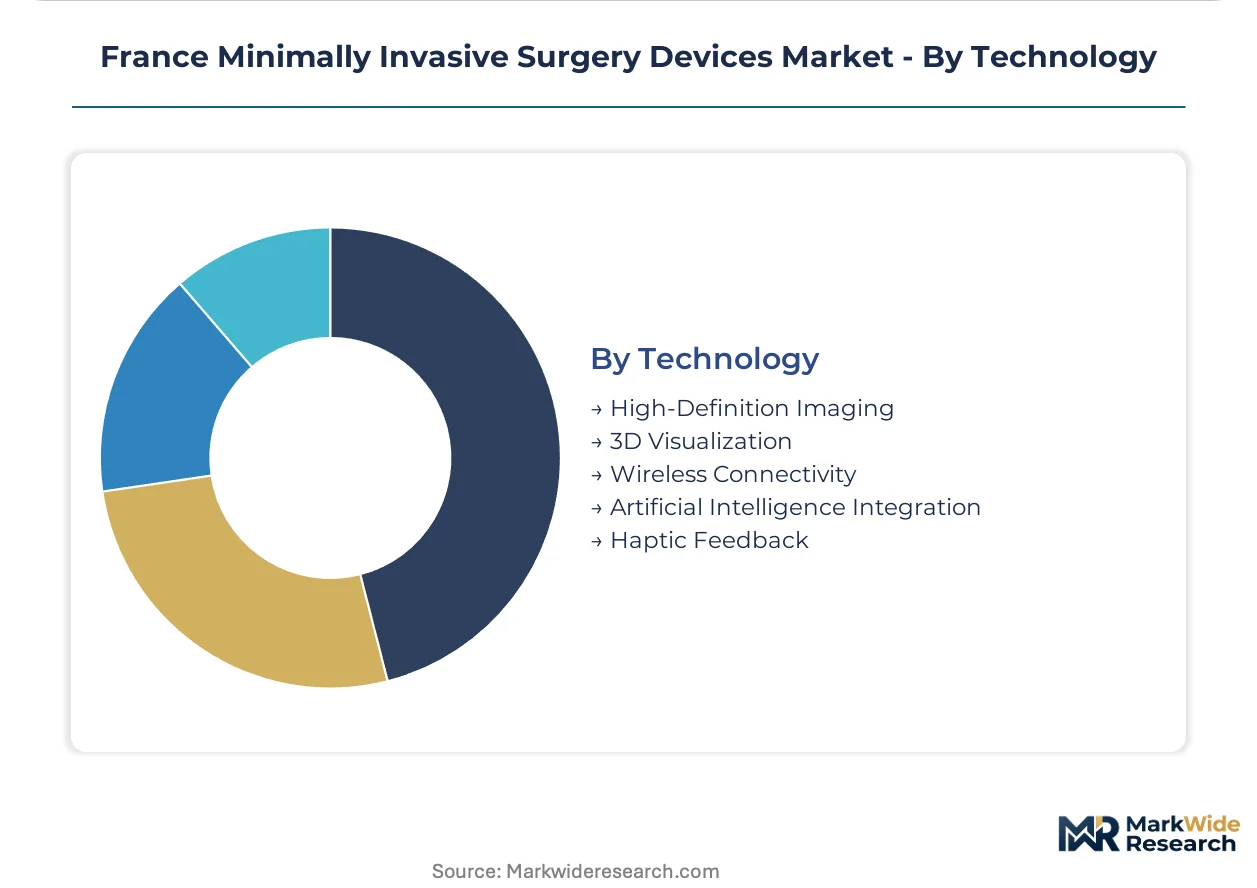
- High-Definition Imaging:4K resolution standards now baseline for new hospital tower installations, displacing 1080p legacy systems. Middleware upgrade costs constrain integration speed in older Ile-de-France facilities.
- Artificial Intelligence Integration:Real-time fluorescence overlay and augmented reality guidance create new procedure categories in hepatobiliary and colorectal surgery. ANSM innovation fast-track offers accelerated market access for first-in-class visualization systems.
- 3D Visualization:Stereoscopic displays reduce surgeon fatigue in prolonged robotic procedures.
- Haptic Feedback:Force-sensing instruments enhance tissue handling precision in delicate dissection workflows.
- Wireless Connectivity:Cordless instrument channels reduce OR clutter and sterilization complexity.
Installed base concentrates in High-Definition Imaging; technology transition momentum belongs to Artificial Intelligence Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors France's minimally invasive surgery device demand through the Île-de-France hospital cluster, where GCS Sante publique procurement frameworks concentrate capital allocation for laparoscopic and robotic platforms.
Île-de-France
Public hospital networks in Paris and surrounding departments drive the highest procedure volumes for routine cholecystectomy and hernia repair. HAS accelerated assessment pathways streamline reimbursement for proven laparoscopy platforms in this cluster. CHU networks in Paris pilot imaging-integrated navigation systems for complex hepatobiliary interventions.
Auvergne-Rhône-Alpes
Lyon's university hospital centers scale robotic-assisted surgery volumes through dedicated training infrastructure and outcome-based reimbursement pilots. ANSM innovation fast-track applications concentrate here for first-in-class visualization systems. The regional surgical cluster compresses conversion rates to open surgery through single-port robotic access platforms.
Provence-Alpes-Côte d'Azur
Marseille's hospital groups face capital intensity constraints from robotic platform service contracts that crowd out laparoscopy investments. EU Green Deal procurement mandates redirect capital toward energy-efficient surgical platforms and reusable instrument systems. Private clinics in Nice present white space for compact laparoscopy platforms with flexible leasing structures.
Hauts-de-France
Lille's regional hospital network experiences MDR technical documentation bottlenecks delaying class III surgical device market entry. Notified body capacity constraints compress procurement cycles for legacy electrosurgical generators. The cluster maintains systematic procedure registries to satisfy ANSM post-market clinical follow-up obligations.
France Minimally Invasive Surgery Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with robotic platform specialists commanding dedicated service contract revenue streams while laparoscopy instrument manufacturers compete on single-use polymer cost efficiency. The vendor base organizes into three tiers: integrated platform conglomerates with imaging-surgical navigation convergence, standalone instrument specialists with high-volume disposable throughput, and regional training-service bundlers anchoring hospital loyalty. Consolidation pressures favor M&A activity around visualization technology assets and strategic partnerships linking capital equipment vendors to hospital purchasing consortia.
Among diversified medical technology conglomerates, Stryker Corporation and Siemens Healthineers occupy positions spanning capital equipment and disposables, while Intuitive Surgical exemplifies the premium-tier robotic platform archetype through specialized training infrastructure. Smith & Nephew PLC and Zimmer Biomet represent orthopedics-anchored diversification into minimally invasive workflows, with Karl Storz GmbH and Olympus Corporation sitting within the visualization-specialist tier. Koninklijke Philips NV and General Electric Company anchor imaging-integrated surgical navigation convergence.
| Leading Market Players |
|---|
| Smith & Nephew PLC |
| Siemens Healthineers |
| Stryker Corporation |
| Koninklijke Philips NV |
| General Electric Company (GE Healthcare) |
| Intuitive Surgical Inc |
| Zimmer Biomet |
| Karl Storz GmbH |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Captive service contracting by robotic platform manufacturers anchors both supply security and pricing power across French hospital networks. These long-term agreements bundle capital equipment, disposable instruments, and specialized training into unified procurement frameworks that resist spot-market competition and lock purchasing committees into predictable expenditure profiles.
Pricing Analysis
Outcome-guaranteed contracts tied to complication rate thresholds anchor pricing structures across public hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates robotic systems with dedicated proctor networks from laparoscopy towers and disposable instrument bundles. Pricing pressure stems from single-use polymer cost inflation in trocar and electrosurgical blade supply chains. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while CHU networks prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Specialized polymer and ceramic component manufacturing concentrates in Germany, Switzerland, and the United States for precision surgical instruments. Supply chains draw from German optical glass foundries for 4K and 3D visualization towers, Swiss precision machining for robotic instrument arms, and US polymer extrusion for single-use trocar sheaths. Single-source vulnerability in ceramic electrosurgical blade substrates creates procurement risk for French distributors. Distribution runs through GCS Sante publique purchasing consortia and specialized medical device distributors serving private clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification timelines and notified body capacity constraints are compressing weaker manufacturers out of the French market, consolidating procurement relationships around compliant incumbents with established clinical evidence portfolios.
For Market Incumbents: Hedge regulatory exposure by accelerating clinical evaluation documentation for legacy electrosurgical generators before ANSM post-market surveillance deadlines. Prioritize backward integration into reusable instrument sterilization services to capture recurring revenue streams displaced from single-use polymer sales by EU Green Deal mandates.
For New Entrants and Emerging Players: Direct-to-clinic digital training platforms offer lower-friction entry points than capital equipment sales, enabling remote proctoring partnerships with regional surgical clusters lacking certified training infrastructure. Target Ile-de-France ambulatory surgical centers with compact laparoscopy leasing structures that bypass GCS Sante publique framework agreements.
For Investors and Strategic Acquirers: Exit pathways concentrate in visualization technology assets with ANSM innovation fast-track eligibility and established hospital training partnerships. Long-term viability in this market hinges on regulatory compliance infrastructure rather than product differentiation alone. Monitor HAS accelerated assessment pathway approval velocity as the primary inflection indicator for reimbursement-accessible acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation alignment with ANSM post-market surveillance accelerates French market entry. |
| Hospital System Partnership | GCS Sante publique framework agreements bundle capital, disposables, and training into multi-year supplier relationships. |
| Software Companion Development | Real-time fluorescence overlay and augmented reality guidance create new hepatobiliary procedure categories. |
| Reimbursement Strategy | HAS accelerated assessment pathways streamline capital allocation toward proven minimally invasive platforms. |
| Backward Integration into Reusable Systems | EU Green Deal procurement mandates redirect hospital capital toward sustainable instrument lifecycle economics. |
Research Methodology
Multi-period observation of hospital procurement volumes, MDR certification timelines, and HAS assessment outcomes anchored the trend analysis, supplemented by interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee chairs, and regulatory affairs leads at device manufacturers. Secondary validation drew from ANSM device registration databases, HAS health technology assessment publications, EU MDR implementation guidance documents, and GCS Sante publique framework agreement disclosures. Bottom-up procedure volume modeling and top-down capital expenditure triangulation converged on segment-level estimates.
Input-output matrices mapped laparoscopy instrument throughput, robotic platform utilization rates, and visualization system upgrade cycles against end-user procurement autonomy and technology integration depth. CAGRs were derived from segmented procedure volume projections and capital replacement schedules across the analysis window. Forecast inputs incorporated ANSM innovation fast-track application velocity and HAS reimbursement decision timelines.
The model holds under stable MDR implementation timelines and notified body capacity recovery; deviation in regulatory delay extension or polymer supply disruption would shift procurement concentration patterns. Forecasts reflect documented assumptions regarding hospital capital budget allocation and sustainability mandate enforcement. Material deviation in EU Green Deal procurement compliance thresholds or ANSM post-market surveillance intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
Light Therapy Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Brazil Respiratory Devices Market