
 Neuromodulation Devices Market | 2026-2036
Neuromodulation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neuromodulation Devices Market Intelligence
The EU Medical Device Regulation (MDR) is recalibrating design and post-market surveillance obligations for implantable neurostimulation systems sold across European member states. Medtronic leverages its vertically integrated manufacturing footprint to sustain CE-marked product flows despite notified body bottlenecks. Abbott anchors its competitive stance through differentiated directional lead technology for deep brain stimulation. Boston Scientific Corporation competes on rechargeable platform longevity, reducing surgical replacement frequency for chronic pain patients.
Neuromodulation devices deliver targeted electrical or magnetic stimuli to neural tissue to restore physiological function or suppress pathological signaling, typically operating at pulse widths between 60-450 microseconds and frequencies spanning 2-120 Hz depending on indication. Spinal cord stimulators occupy the largest revenue pool within device type segmentation, though closed-loop systems represent the fastest structural expansion as real-time biomarker feedback reduces patient programming burden. Pain management dominates therapy area allocation, while hospitals retain the highest procedural volume among end users despite outpatient clinic encroachment for device reprogramming.
The FDA maintains stringent premarket approval requirements for implantable pulse generators, while the EU MDR demands enhanced clinical evidence for legacy device recertification. Japan's PMDA operates a separate shonin approval track that shapes market entry sequencing for multinational manufacturers. Stakeholders must monitor reimbursement parity between invasive and non-invasive modalities as health technology assessment bodies recalibrate value frameworks for chronic neurological conditions.
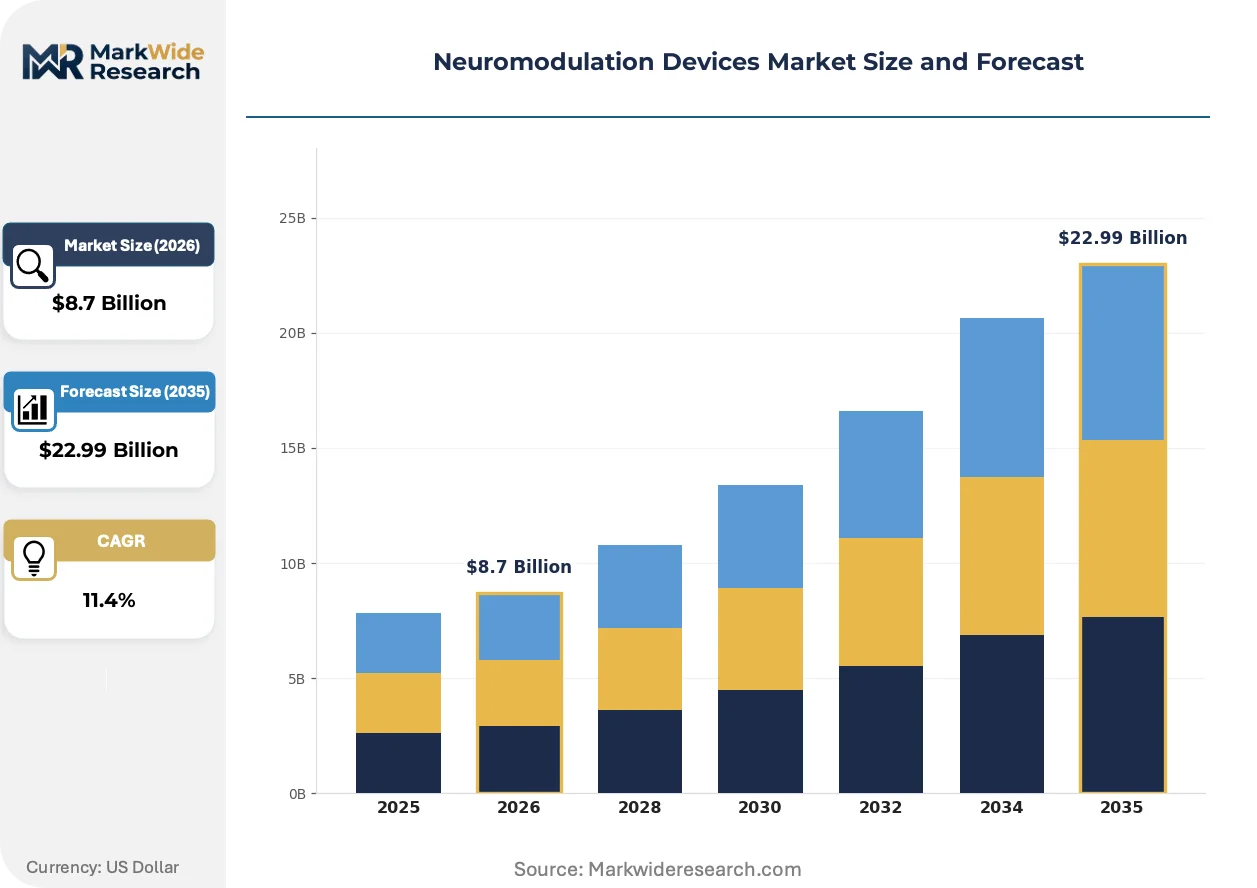
Market Dynamics
Closed-loop spinal cord stimulators are compressing programming cycles and expanding addressable patient populations through real-time biomarker feedback, fundamentally altering competitive positioning around algorithm sophistication rather than hardware alone.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates commercial timelines for novel neurostimulation platforms, compressing the gap between clinical validation and reimbursement establishment for implantable pulse generators.
- Aging Demographics in Developed Economies:Japan, Germany, and the United States exhibit concentrated demand as chronic pain and movement disorder prevalence rises with population aging, expanding the procedural base for deep brain and spinal cord stimulation.
- Rechargeable Platform Longevity:Extended battery life reduces surgical replacement frequency, lowering lifetime cost burdens for chronic pain patients and improving payer value propositions across Medicare and private insurance frameworks.
Market Restraints
- EU MDR Recertification Burden:Enhanced clinical evidence requirements for legacy implantable neurostimulation systems create notified body bottlenecks, delaying CE-marked product flows and compressing European revenue recognition timelines.
- Biocompatible Material Concentration:Supply of specialized polymers and hermetic sealing components concentrates among a limited supplier base in Switzerland and Germany, exposing manufacturers to input cost volatility and qualification delays.
- Invasive Procedure Substitution:Non-invasive transcranial magnetic stimulation and focused ultrasound neuromodulation capture mild-to-moderate indication segments, constraining volume growth for fully implantable systems in early-stage patients.
Strategic Opportunities
- Outpatient Clinic Reprogramming:Remote and ambulatory settings for device parameter adjustment reduce hospital dependency, opening channel expansion in the United States where site-of-service reimbursement differentials favor non-hospital venues.
- India's Underpenetrated Pain Management Infrastructure:Low existing implant density relative to chronic pain prevalence creates whitespace for market development, contingent upon CDSCO approval pathway navigation and private insurance expansion.
- AI-Enabled Closed-Loop Algorithms:Machine learning integration with real-time neural signal processing enables personalized stimulation adaptation, converging computational neuroscience with implantable hardware engineering.
Industry Challenges
- Neuroelectrophysiology Talent Scarcity:The specialized skill set spanning neural signal processing, biocompatibility engineering, and clinical trial design concentrates among a limited pool of researchers, constraining R&D velocity for emerging competitors.
- Premarket Approval Timeline Compression:FDA PMA requirements for implantable pulse generators demand extensive safety and efficacy dossiers, extending capital lockup periods and elevating burn rates for development-stage enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuromodulation Devices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Transcranial Magnetic Stimulation, Spinal Cord Stimulators, Deep Brain Stimulators, Vagus Nerve Stimulators Therapy Area: Pain Management, Epilepsy Treatment, Depression Therapy, Movement Disorders End User: Hospitals, Outpatient Clinics, Home Healthcare, Rehabilitation Centers Technology: Invasive Technologies, Non-Invasive Technologies, Closed-Loop Systems, Remote Monitoring |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, LivaNova PLC, Nevro Corp, NeuroPace, Saluda Medical, Aleva Neurotherapeutics, Biotronik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuromodulation Devices Market Strategic Shifts & Innovations
Algorithmic personalization is displacing fixed-parameter stimulation paradigms, with real-time neural feedback loops enabling adaptive therapeutic delivery that responds to physiological state changes rather than static programming.
Directional lead technology is converging with segmented electrode arrays to enable precise current steering around neural targets, reducing off-target stimulation and side effect profiles. Pain management centers in Germany and the United States are adopting these platforms at accelerated cadences, prioritizing patient-specific anatomical targeting over conventional cylindrical lead designs. The structural consequence is compressing competitive differentiation around lead engineering sophistication rather than generator hardware specifications alone.
The EU Medical Device Regulation is recalibrating post-market surveillance obligations for implantable neurostimulation systems, mandating enhanced clinical follow-up and periodic safety reporting across European member states. Manufacturers must maintain active implant registries and real-world evidence generation capabilities, elevating compliance infrastructure costs. High-complexity devices with long implant durations face the steepest recertification burdens, driving consolidation among smaller notified body capacities.
Hospital purchasing committees are unbundling device procurement from implantation service contracts, separating hardware acquisition from procedural reimbursement and physician training packages. This disintermediation pressures traditional bundled pricing models and elevates transparent value demonstration requirements. The United States exhibits the most advanced unbundling, with IDNs and GPOs extracting discrete line-item negotiations for generators, leads, and external programmers.
Neuromodulation Devices Market Segmentation
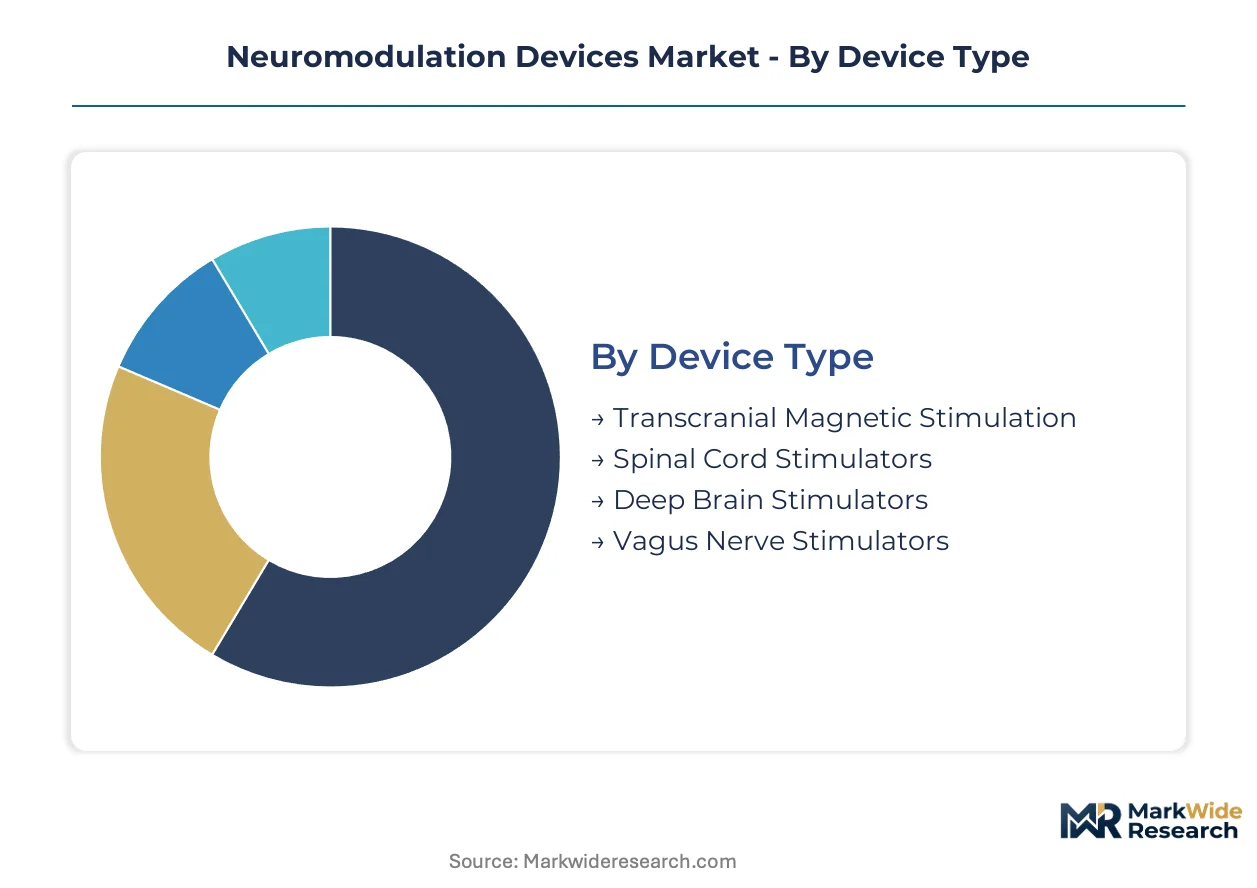
Neuromodulation device segmentation reveals divergent supply chain configurations across hardware categories, with implantable pulse generators demanding vertically integrated manufacturing while external stimulation systems tolerate modular sourcing. Therapy area and technology splits expose reimbursement-driven demand concentration that reshapes competitive investment priorities.
Device Type:
Supply concentration for implantable generators clusters around specialized polymer foundries in Switzerland and Germany, while external magnetic stimulation hardware sources from broader electronics contract manufacturers.
- Spinal Cord Stimulators:Implantable pulse generators paired with cylindrical or paddle leads deliver epidural electrical stimulation at 2-120 Hz for chronic intractable pain. Demand concentrates in pain management centers across the United States and Germany, where aging demographics expand the addressable procedural base for failed back surgery syndrome and complex regional pain syndrome.
- Deep Brain Stimulators:Bilaterally implanted subthalamic nucleus or globus pallidus interna targeting systems incorporate directional lead technology for Parkinson's disease and essential tremor. Abbott anchors competitive positioning through segmented electrode arrays that enable precise current steering, reducing off-target stimulation in movement disorder patients.
- Transcranial Magnetic Stimulation:Non-invasive coil-based systems generate magnetic fields inducing cortical depolarization for depression and migraine.
- Vagus Nerve Stimulators:Implantable neck-worn generators with helical electrodes provide intermittent cervical vagus stimulation for drug-resistant epilepsy.
Today's leader: Spinal Cord Stimulators. Tomorrow's challenger: Deep Brain Stimulators.
Therapy Area:
Reimbursement parity between invasive and non-invasive modalities determines volume allocation across therapy areas, with chronic pain commanding premium procedural codes in Medicare frameworks.
- Pain Management:Spinal cord stimulation and peripheral nerve field stimulation address neuropathic and nociceptive pain conditions through programmable electrical patterns. Hospital purchasing committees in the United States unbundle device procurement from implantation services, extracting transparent value demonstration for generator and lead combinations.
- Movement Disorders:Deep brain stimulation targets Parkinson's disease, dystonia, and essential tremor through precisely localized neural inhibition. Japan's PMDA shonin approval track shapes market entry sequencing for multinational manufacturers targeting this indication.
- Epilepsy Treatment:Responsive neurostimulation and vagus nerve stimulation provide adjunctive therapy for drug-resistant seizure disorders.
- Depression Therapy:Transcranial magnetic stimulation and emerging invasive approaches address treatment-resistant major depressive disorder.
Pain Management captures current procedural volume. Movement Disorders show the steepest expansion trajectory as directional lead technology improves patient selection.
End User:
Site-of-service reimbursement differentials in the United States accelerate channel migration toward lower-acuity settings for device reprogramming and follow-up care.
- Hospitals:Academic medical centers and community hospitals retain implantation volume for complex surgical procedures requiring anesthesia support and overnight observation. The EU MDR mandates enhanced clinical follow-up and periodic safety reporting for implantable systems, elevating compliance infrastructure costs in hospital-based registries.
- Outpatient Clinics:Ambulatory surgical centers and dedicated neuromodulation clinics perform generator replacements and parameter adjustments under local anesthesia. Remote programming capabilities reduce hospital dependency, opening channel expansion where reimbursement frameworks favor non-hospital venues.
- Home Healthcare:External trial stimulators and patient-controlled magnetic devices enable residential therapy administration.
- Rehabilitation Centers:Post-implant physical therapy integration supports functional restoration for movement disorder patients.
Hospitals dominate implantation revenue. Outpatient Clinics gain share fastest in reprogramming and replacement procedures.
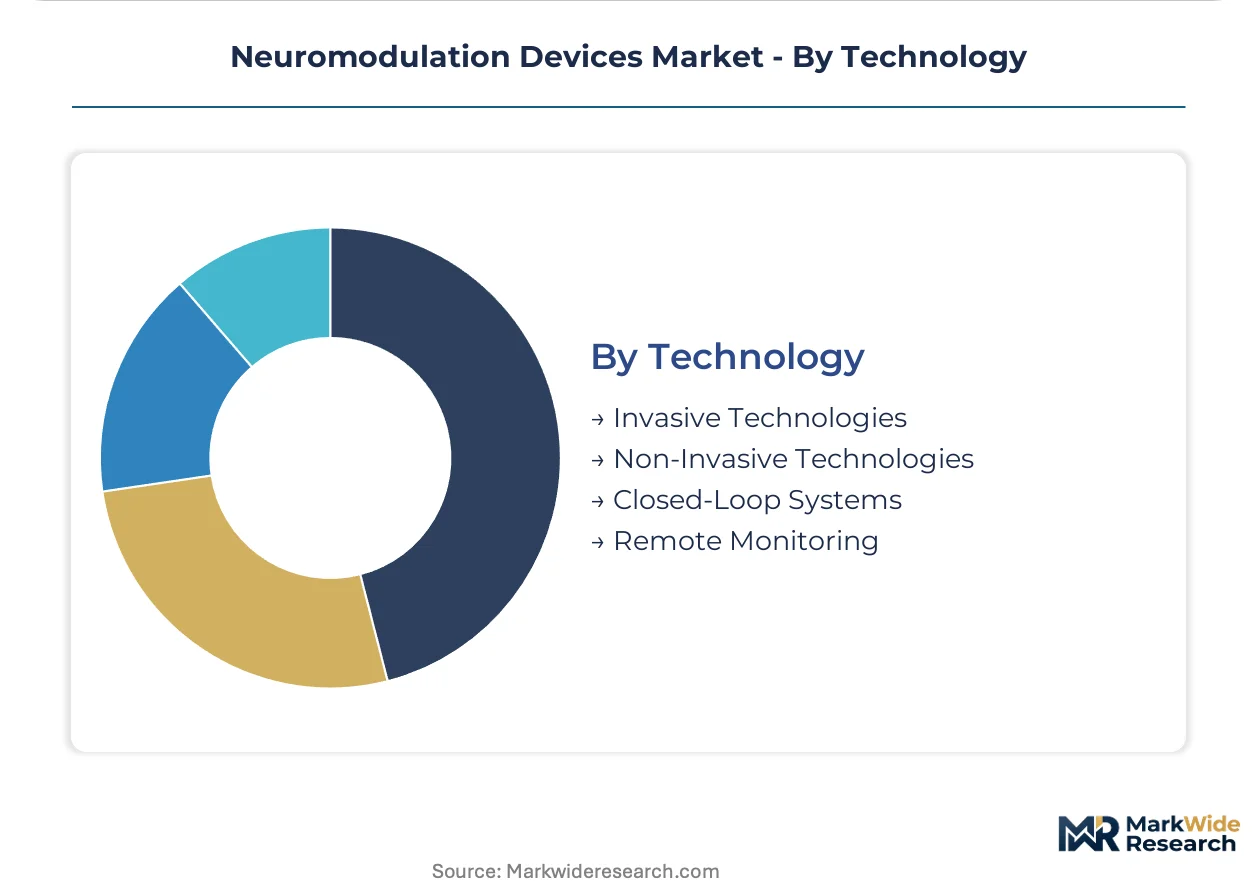
Technology:
Algorithm sophistication now differentiates competitive positioning as hardware commoditization pressures traditional generator specifications.
- Closed-Loop Systems:Real-time biomarker feedback enables adaptive stimulation adjustment based on physiological state changes rather than static programming. Pain management centers in Germany and the United States adopt these platforms at accelerated cadences, compressing programming cycles and expanding addressable patient populations.
- Invasive Technologies:Fully implantable pulse generators with transcutaneous charging or primary cell designs require surgical placement and replacement. Biocompatible material supply concentrates among limited suppliers, exposing manufacturers to input cost volatility and qualification delays.
- Non-Invasive Technologies:Transcranial magnetic and electrical stimulation systems avoid surgical risk but require repeated patient visits.
- Remote Monitoring:Cloud-connected patient programmers and clinician dashboards enable parameter adjustment without clinic visits.
Closed-Loop Systems command R&D investment priority. Remote Monitoring expands most quickly as telehealth infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neuroelectrophysiology specialists cluster in Boston, Minneapolis, and Zurich, anchoring R&D pipelines for implantable pulse generators. These talent concentrations attract venture funding and accelerate clinical trial timelines for closed-loop systems.
United States
Pain management centers in Texas and Florida expand procedural volumes for spinal cord stimulation as Medicare reimbursement codes stabilize. The FDA breakthrough device designation compresses commercial timelines for novel neurostimulation platforms. Minneapolis hosts Medtronic's vertically integrated manufacturing footprint sustaining generator production.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia drive chronic pain prevalence and deep brain stimulation demand. The EU MDR recertification burden creates notified body bottlenecks, delaying CE-marked product flows for legacy implantable systems. Berlin's Charité hospital system anchors post-market surveillance infrastructure for active implant registries.
Japan
Movement disorder specialists in Tokyo and Osaka prioritize directional lead technology for Parkinson's disease patients. The PMDA shonin approval track shapes market entry sequencing for multinational manufacturers targeting neuromodulation indications. Kansai's medical device cluster concentrates reprogramming expertise for outpatient clinic migration.
Switzerland
Specialized polymer foundries in the Lake Geneva region supply hermetic sealing components for implantable pulse generators. Swissmedic maintains stringent premarket requirements for neurostimulation systems alongside EU MDR alignment. Zurich's ETH spin-offs concentrate algorithm development for closed-loop biomarker feedback.
India
Chronic pain prevalence in Maharashtra and Karnataka far exceeds current implant density, creating whitespace for market development. CDSCO approval pathway navigation remains contingent upon private insurance expansion for device reimbursement. Delhi-NCR's tertiary hospitals pilot deep brain stimulation programs for movement disorders.
Neuromodulation Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the neuromodulation landscape, with vertically integrated manufacturers sustaining CE-marked flows despite regulatory bottlenecks. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with full-stack capabilities, mid-cap specialists in directional lead engineering, and emerging players in closed-loop algorithm development. Dominant competitive moves include M&A for neuroelectrophysiology talent acquisition and strategic partnerships for biocompatible material supply security.
Within the diversified conglomerate tier, Medtronic and Abbott anchor competitive positioning through manufacturing scale and lead technology differentiation respectively. Boston Scientific Corporation occupies a position emphasizing rechargeable platform longevity. Among emerging specialists, Nevro Corp and NeuroPace exemplify closed-loop algorithm innovation, while Saluda Medical represents real-time biomarker feedback advancement. LivaNova PLC and Aleva Neurotherapeutics sit within the mid-cap specialist tier targeting movement disorder applications. Biotronik anchors European manufacturing presence for implantable pulse generators.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| LivaNova PLC |
| Nevro Corp |
| NeuroPace |
| Saluda Medical |
| Aleva Neurotherapeutics |
| Biotronik |
| Others |
Cost & Logistics Intelligence
Closed-loop algorithm integration into implantable pulse generators simultaneously elevates R&D amortization burdens and concentrates procurement leverage among vertically integrated manufacturers with captive neuroelectrophysiology talent pools. This technological inflection compresses hardware commoditization timelines while expanding the premium attachable to real-time biomarker feedback capabilities.
Pricing Analysis
Three-tier pricing structure across premium closed-loop systems, standard rechargeable platforms, and economy primary-cell devices dominates procurement negotiations. Price differentiation rests on battery longevity specifications and FDA breakthrough designation status, with rechargeable platforms commanding sustained premiums against primary-cell alternatives. Cost compression in the economy tier is intensifying because hospital purchasing committees unbundle device procurement from implantation services. Academic medical centers exhibit the lowest price sensitivity due to bundled research funding, while community hospitals face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Zurich, and Singapore anchor hub-and-spoke patterns for implantable pulse generators and external programmers. Manufacturing concentration clusters in Switzerland, Germany, and the United States for specialized polymers, hermetic sealing components, and neuroelectrophysiology talent. Raw material dependencies center on biocompatible titanium alloys, platinum-iridium electrodes, and medical-grade silicone elastomers. Single-source vulnerability in Swiss polymer foundries exposes manufacturers to qualification delays. Distribution runs through hospital purchasing committees and GPO contracts in the United States, with direct-to-clinic channels gaining share for reprogramming services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where the FDA breakthrough device designation pathway accelerates commercial timelines and expands addressable patient populations for novel neurostimulation platforms.
For Market Incumbents: Extend algorithm development partnerships with ETH Zurich and MIT spin-offs to secure closed-loop biomarker feedback capabilities before hardware commoditization erodes generator margins. Deepen backward integration into Swiss polymer foundries to mitigate single-source supply risk. Lock in long-term contracts with pain management center networks to defend against outpatient clinic channel migration.
For New Entrants and Emerging Players: Capture India's underpenetrated pain management infrastructure where chronic pain prevalence far exceeds current implant density. Target movement disorder applications in Japan's PMDA shonin approval track as the fastest-penetrable regulatory pathway for directional lead technology. Pursue strategic licensing arrangements with established European notified bodies to navigate EU MDR recertification bottlenecks.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists with directional lead engineering capabilities and active CE-marked product flows despite regulatory headwinds. Long-term viability over the next decade hinges on algorithmic personalization convergence with implantable hardware. Monitor FDA breakthrough designation awards as the critical inflection signal for platform commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Accelerates premarket approval timelines for closed-loop spinal cord stimulators targeting chronic pain. |
| CE Marking Pathway Navigation | Secures European market access amid EU MDR recertification bottlenecks for legacy implantable systems. |
| Hospital System Partnership | Locks in implantation volume through bundled service contracts with academic medical centers. |
| Software Companion Development | Enables remote patient monitoring and parameter adjustment without clinic visits. |
| Reimbursement Strategy | Establishes Medicare procedural codes for closed-loop systems in pain management centers. |
Research Approach
Bottom-up pain management center modeling reconciled against top-down implantable pulse generator production tracking forms the analytical core of this study. Primary interviews with pain management physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers inform procedural volume and procurement pattern assumptions. Secondary validation draws from FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, EU MDR notified body registries, and hospital procurement contract disclosures. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of spinal cord stimulator and deep brain stimulator implantation rates establishes baseline growth trajectories across the projection horizon. The analytical framework models device type, therapy area, end user, and technology splits alongside regional regulatory cluster differentiation. CAGRs derive from fitted growth curves adjusted for FDA approval velocity and EU MDR implementation timelines. Forecast inputs incorporate aging demographic projections and reimbursement parity assumptions between invasive and non-invasive modalities.
Regulatory approval delays, notified body capacity constraints, and biocompatible material supply disruptions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding FDA breakthrough designation velocity and EU MDR recertification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Hormonal Implants Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Cervical Retractors Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Disposable Lancets Market
Medical Devices
Prescription Lens Market