
 Medical Oxygen Concentrators Market | 2026-2036
Medical Oxygen Concentrators Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Oxygen Concentrators Market Analysis
Chinese medical device manufacturing is expanding its concentrator output capacity to serve both domestic chronic respiratory care needs and export channels. Koninklijke Philips N.V. leverages its global service infrastructure to sustain recurring revenue from replacement parts and consumables. Inogen, Inc. specializes in lightweight portable systems that anchor its position in the mobile oxygen therapy segment. CAIRE Inc. dominates military and commercial aviation oxygen applications, extending its technical base into clinical concentrators.
A medical oxygen concentrator separates ambient air into concentrated oxygen through pressure swing adsorption or membrane filtration, typically delivering 85-96% oxygen purity at flow rates from 1-10 liters per minute for therapeutic use. Portable units incorporating pulse-dose delivery and lithium-ion batteries now command the fastest-growing product category as patients prioritize mobility over stationary bedside systems. Homecare end users represent the deepest margin pool due to recurring device rentals and long-term service contracts, while hospital procurement concentrates on high-flow stationary units with dual-pressure capabilities. PSA technology leads unit shipments but VPSA systems are gaining share in institutional settings requiring continuous high-output supply.
The FDA classifies oxygen concentrators as Class II medical devices requiring 510(k) clearance, while ISO 13485 certification governs quality management for manufacturers targeting multiple jurisdictions. The EU MDR framework intensifies clinical evidence requirements for concentrator software and alarm systems, reshaping product development timelines for entrants. Stakeholders must monitor reimbursement code revisions from CMS and parallel agencies, as coverage determinations directly influence patient access and manufacturer pricing power across outpatient and home-based care models.
Market Dynamics
Pressure swing adsorption technology is converging with portable battery systems to compress the stationary-to-mobile product mix, while FDA 510(k) clearance timelines and ISO 13485 certification requirements reshape competitive entry barriers across manufacturing bases.
Growth Catalysts
- Chronic respiratory disease prevalence:Homecare oxygen therapy demand from COPD and sleep apnea patients is accelerating device rentals and long-term service contracts in the United States.
- EU MDR clinical evidence mandates:The intensified software and alarm system requirements are filtering out marginal competitors and consolidating quality-certified manufacturers.
- Lithium-ion energy density improvements:Extended battery life in portable units is displacing stationary bedside systems among mobility-prioritized patient cohorts.
Market Restraints
- Zeolite molecular sieve supply concentration:PSA system production depends on specialized adsorbent materials sourced from limited chemical processing clusters in China.
- High-flow stationary unit capex intensity:Dual-pressure VPSA systems require substantial upfront investment, constraining hospital procurement cycles.
- Reimbursement code volatility:CMS coverage determination revisions create pricing uncertainty across outpatient and home-based care models in the United States.
Strategic Opportunities
- Rural India respiratory care penetration:Underpenetrated district hospital networks present white space for affordable concentrator deployment under CDSCO medical device regulations.
- Military aviation oxygen crossover:Technical expertise from commercial aviation applications is extending into clinical-grade portable systems for emergency response units.
- Direct-to-patient subscription channels:Bypassing traditional durable medical equipment distributors through telehealth-integrated rental platforms is capturing margin pool in Germany.
Industry Challenges
- Biomedical engineer talent scarcity:Cross-functional expertise combining pneumatic system design with embedded software development is concentrating among established manufacturers.
- Legacy alarm integration complexity:EU MDR software validation requirements are forcing extended recertification timelines for devices with non-modular control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Oxygen Concentrators Market |
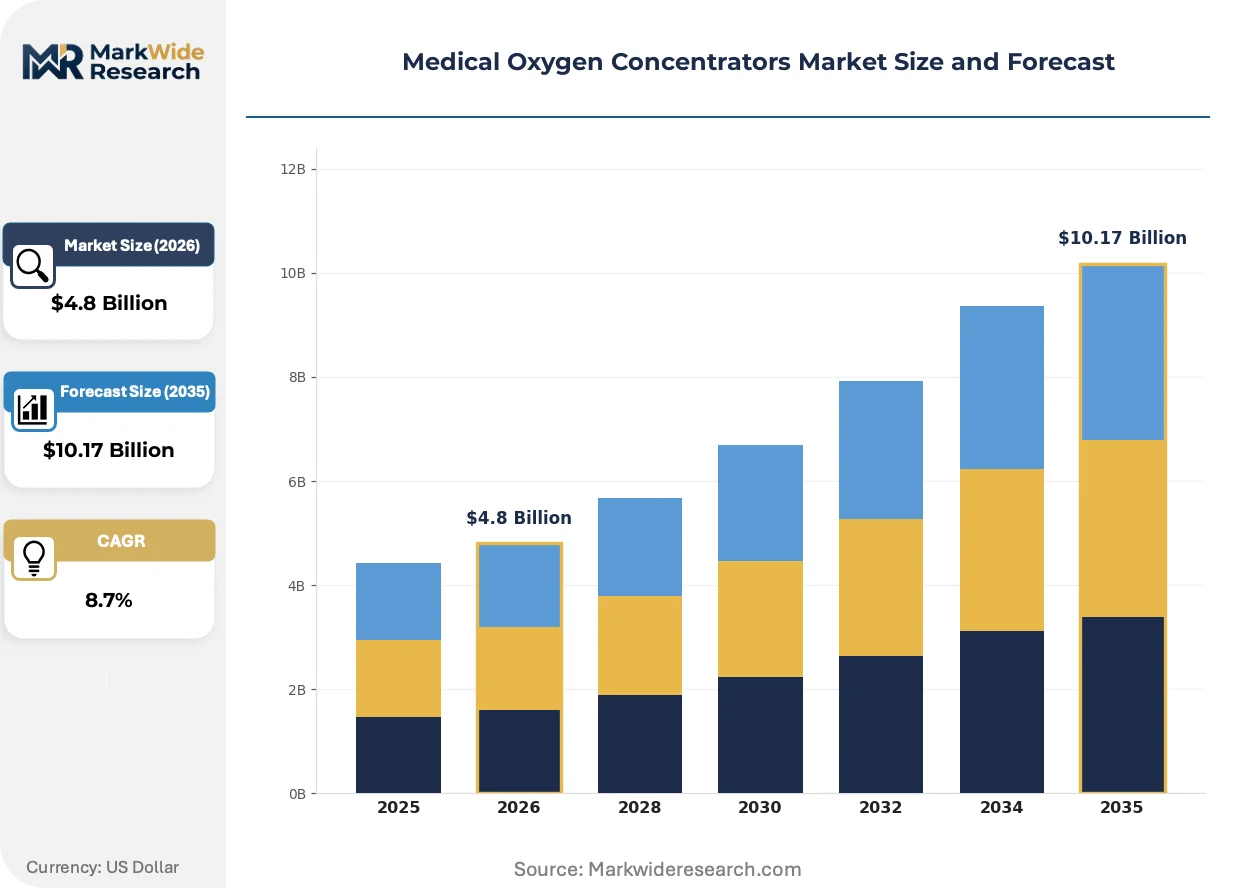
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Liquid, Hybrid End User: Hospitals, Homecare, Emergency Services, Clinics Technology: PSA, VPSA, Membrane Separation, Cryogenic Distribution Channel: Online, Retail, Direct Sales, Third-Party Distributors |
| Companies Covered | Koninklijke Philips N.V., Inogen, Inc., CAIRE Inc., Drive DeVilbiss Healthcare, React Health, Nidek Medical Products, Inc., Invacare Corporation, GCE Group, Chart Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Oxygen Concentrators Market Emerging Trajectories
Three intersecting developments are compressing product lifecycles and redistributing margin pools: hardware-software convergence in portable systems, regulatory evidence requirements tightening quality tiers, and patient-directed procurement bypassing traditional equipment channels.
Pulse-dose oxygen delivery algorithms are converging with real-time SpO2 sensor feedback to enable closed-loop therapeutic adjustment. Homecare patients with active lifestyles are adopting these systems faster than institutional buyers, compressing the replacement cycle for legacy continuous-flow devices and forcing manufacturers to restructure service revenue around software updates rather than hardware turnover.
The EU MDR framework is extending clinical evidence requirements to concentrator alarm systems and connectivity software. Manufacturers targeting European markets must now generate post-market surveillance data that incumbents with established quality management systems can leverage while new entrants face extended development timelines, consolidating competitive position among ISO 13485-certified producers.
Patients are initiating device selection through pulmonologist-telehealth platforms rather than durable medical equipment intermediaries. This channel disintermediation is most visible in United States Medicare Advantage networks, where direct manufacturer-patient relationships are capturing recurring revenue streams that previously fragmented across regional equipment distributors and service contractors.
Medical Oxygen Concentrators Market Segmentation
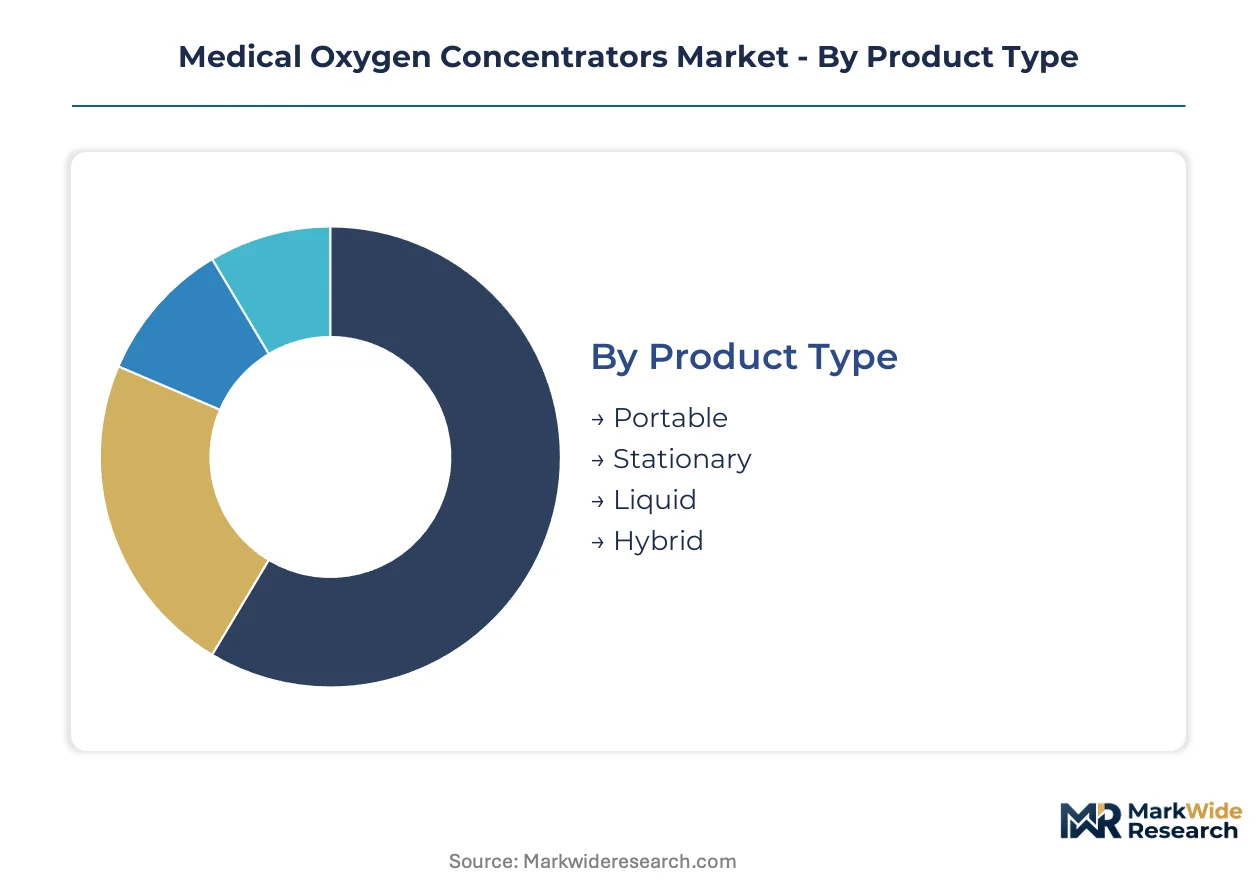
Oxygen concentrator procurement patterns diverge sharply across patient mobility requirements, care settings, and oxygen purity specifications. Manufacturers configure product portfolios around these structural differences to capture recurring revenue streams from replacement cycles and service contracts.
Product Type:
Cost tier differentiation separates patients prioritizing mobility investment from those accepting stationary bedside systems.
- Portable:Pulse-dose delivery systems incorporate lithium-ion battery packs enabling 4-8 hours of ambulatory oxygen therapy. Demand concentrates in United States Medicare Advantage networks where patients self-select devices through telehealth-integrated platforms rather than durable medical equipment intermediaries.
- Stationary:Continuous-flow bedside units deliver 5-10 liters per minute through PSA or VPSA architectures. Hospital procurement in Germany favors dual-pressure systems with 96% purity ratings for intensive respiratory care wards.
- Liquid:Cryogenic storage systems provide highest-density oxygen reserves for high-flow requirements. United States homecare patients with severe COPD utilize liquid reservoirs as backup during power outages.
- Hybrid:Dual-mode systems switch between stationary continuous-flow and portable pulse-dose operation. Chinese manufacturers are expanding production capacity for hybrid units targeting export channels.
Stationary systems lead volumes today; portable configurations are gaining share fastest.
End User:
Application setting determines flow rate requirements, reimbursement pathways, and service intensity.
- Hospitals:High-flow VPSA installations with dual-pressure capabilities serve operating theaters and intensive care units. Procurement cycles in Germany extend 18-24 months due to capital expenditure approval processes.
- Homecare:Long-term rental contracts with recurring service revenue dominate this segment. United States patients with COPD and sleep apnea drive device utilization through Medicare reimbursement codes.
- Emergency Services:Lightweight portable units with rapid-deployment features equip ambulance fleets and field response teams. Military aviation oxygen expertise from CAIRE Inc. extends into clinical emergency applications.
- Clinics:Mid-flow stationary systems support outpatient respiratory therapy and diagnostic procedures. District hospital networks in rural India present deployment opportunities under CDSCO medical device regulations.
Homecare generates the deepest margin pool; emergency services show the steepest expansion trajectory.
Technology:
Supply concentration of specialized adsorbent materials shapes competitive positioning across technical architectures.
- PSA:Pressure swing adsorption using zeolite molecular sieves dominates unit shipments. Chinese chemical processing clusters control specialized adsorbent supply, creating procurement dependencies for manufacturers.
- VPSA:Vacuum pressure swing adsorption enables continuous high-output supply for institutional settings. Hospital buyers in Germany specify VPSA for 24/7 oxygen generation requirements.
- Membrane Separation:Polymer membrane filtration delivers lower purity levels suitable for specific therapeutic applications. Niche deployment in aviation and military contexts leverages compact form factors.
- Cryogenic:Air liquefaction systems achieve highest purity and volume outputs for industrial-scale medical oxygen. Limited to centralized hospital supply infrastructure due to capital intensity.
PSA leads installed base; VPSA is climbing the fastest in institutional procurement.
Distribution Channel:
Customer type and procurement authorization level determine channel selection and margin capture.
- Online:Direct-to-patient platforms bypass traditional equipment distributors. United States telehealth-integrated rental systems capture recurring revenue previously fragmented across regional contractors.
- Retail:Pharmacy and medical supply storefronts serve walk-in patients with prescription authorization. German retail channels support outpatient oxygen therapy initiation.
- Direct Sales:Manufacturer field representatives negotiate hospital and clinic procurement contracts. Extended sales cycles in Germany reflect capital expenditure committee requirements.
- Third-Party Distributors:Regional equipment and service contractors manage patient relationships and maintenance logistics. United States Medicare reimbursement flows through this channel for legacy installations.
Third-party distributors maintain volume leadership; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined medical device approval pathways and lower cost-of-compliance structures. Production capacity is migrating to regions where ISO 13485 certification can be achieved with reduced documentation burden while maintaining FDA-equivalent quality standards.
United States
Medicare Advantage networks and COPD patient cohorts drive concentrator rentals through telehealth-integrated platforms. FDA 510(k) clearance requirements and CMS reimbursement code revisions shape competitive entry timing. Manufacturing clusters in Minnesota and Ohio host established quality-certified producers serving domestic homecare demand.
Germany
Hospital procurement committees specify dual-pressure VPSA systems for intensive respiratory care wards with extended 18-24 month capital cycles. EU MDR clinical evidence mandates for software and alarm systems filter marginal competitors from European market access. Industrial concentration in Baden-Württemberg and North Rhine-Westphalia anchors precision pneumatic component supply.
China
Domestic chronic respiratory care expansion and export channel development accelerate concentrator output capacity growth. NMPA medical device registration and GB standards compliance govern quality thresholds for domestic and overseas markets. Chemical processing clusters in Jiangsu and Zhejiang provinces control specialized zeolite molecular sieve supply for PSA system production.
India
Underpenetrated district hospital networks in rural states present deployment white space for affordable concentrator models. CDSCO medical device regulations and PLI scheme incentives for domestic manufacturing reshape import dependency. Industrial corridors in Maharashtra and Gujarat host emerging assembly operations targeting price-sensitive institutional procurement.
Japan
Aging demographics and sleep apnea diagnosis rates sustain homecare oxygen therapy device utilization. PMDA quality management requirements and JIS standards certification maintain high barriers for non-domestic manufacturers. Medical device engineering concentration in the Kansai region supports precision component fabrication for portable system miniaturization.
Medical Oxygen Concentrators Market Vendor Landscape
Chinese producers anchor the volume tier through concentrated adsorbent material access and scaled assembly operations; German and US specialists hold premium positioning through quality-certified pneumatic engineering and recurring service revenue models. The vendor base stratifies across three tiers: multinational healthcare conglomerates with global service infrastructure, mid-cap specialists in portable or military-aviation crossover applications, and regional fabricators competing on price-accessible stationary units. Dominant competitive moves include backward integration into zeolite sieve supply and direct-to-patient channel development bypassing traditional equipment distributors.
Within the multinational infrastructure tier, Koninklijke Philips N.V. and Invacare Corporation exemplify quality-certified producers with established recurring revenue streams from replacement parts and long-term service contracts. Among portable system specialists, Inogen, Inc. and CAIRE Inc. occupy positions anchored in lightweight pulse-dose delivery and military-aviation technical crossover respectively. Nidek Medical Products, Inc. represents the mid-cap fabrication archetype with concentrated presence in specific regional markets. These named entities serve as reference points for understanding how competitive positioning distributes across technology specialization, geographic origin, and channel access vectors rather than definitive market share claims.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Inogen, Inc. |
| CAIRE Inc. |
| Drive DeVilbiss Healthcare |
| React Health |
| Nidek Medical Products, Inc. |
| Invacare Corporation |
| GCE Group |
| Chart Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up durable medical equipment distributors now control patient-facing pricing across United States Medicare networks, compressing manufacturer margins while amplifying working capital demands for inventory-heavy channel partners serving homecare oxygen therapy markets.
Pricing Analysis
Distributor margin layers dominate pricing architecture, with regional equipment contractors capturing 25-35 points before patient copay. Three-tier pricing structure across FDA-cleared premium systems, CE-marked standard units, and economy-grade stationary concentrators separates reimbursement-eligible from cash-pay segments. Cost compression in the economy tier intensifies because Chinese assembly capacity expansion outpaces brand differentiation. Hospital procurement committees exhibit lowest price sensitivity due to capital budget insulation, while rural Indian district hospitals demonstrate acute elasticity.
Supply Chain Analysis
Ocean freight cost volatility from Shanghai to Rotterdam and Long Beach reshapes landed cost calculations for PSA system imports. Zeolite molecular sieve production draws from specialized chemical processing clusters in Jiangsu and Zhejiang provinces, while precision pneumatic components source from Baden-Württemberg and North Rhine-Westphalia industrial corridors. Single-source vulnerability concentrates in Chinese adsorbent supply, with no qualified alternative achieving ISO 13485 certification at scale. Distribution runs through third-party regional equipment contractors managing patient logistics and preventive maintenance scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU MDR clinical evidence mandates and FDA 510(k) software validation requirements filter marginal competitors, concentrating margin capture among ISO 13485-certified producers serving mobility-prioritized COPD patient cohorts.
For Market Incumbents: Deploy backward integration into zeolite molecular sieve supply to secure PSA system production continuity against Chinese export restriction risk. Consolidate service revenue through telehealth-integrated direct-to-patient platforms, bypassing distributor margin erosion in United States Medicare Advantage networks. Threat substitution from lightweight portable pulse-dose systems demands accelerated lithium-ion battery energy density partnerships. For New Entrants and Emerging Players: Telehealth platform operators represent the most accessible channel partnership archetype for bypassing legacy distributor lock-in. Rural Indian district hospitals under CDSCO regulations offer penetrable white space for affordable stationary concentrator deployment. Target military-aviation technical crossover applications leveraging existing CAIRE Inc. competency adjacencies. Go-to-market through direct-to-patient subscription rental models captures recurring revenue streams previously fragmented across regional contractors. For Investors and Strategic Acquirers: Healthcare private equity consolidators are the most active acquirer in this space, rolling up regional durable medical equipment distributors to capture Medicare reimbursement flow aggregation. Long-term viability centers on software-enabled service revenue multiples rather than hardware shipment volumes. Acquisition target archetype: mid-cap portable system specialists with ISO 13485 certification and established pulmonologist-telehealth channel relationships. Signal to watch: CMS reimbursement code revisions affecting homecare oxygen therapy coverage determination timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zeolite Supply | Secures PSA system production against Chinese adsorbent export concentration risk. |
| EU MDR Software Validation Investment | Accelerates market access while filtering uncertified competitors from European procurement. |
| Telehealth-Integrated Rental Platform | Captures recurring revenue from United States Medicare Advantage patient self-selection. |
| Hospital System Direct Partnership | Bypasses distributor margin layers in German VPSA procurement committee sales cycles. |
| Lithium-Ion Battery Energy Density R&D | Extends portable system ambulatory operation hours for mobility-prioritized COPD cohorts. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market's stakeholder ecosystem. The analysis combines structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and homecare oxygen therapy patients with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR post-market surveillance registries, and NMPA medical device registration records. Bottom-up shipment modeling triangulates against top-down healthcare expenditure allocation estimates.
Granularity-level modeling disaggregates volume and value across product type, end user setting, technology architecture, and distribution channel dimensions throughout the forecast period. CAGRs derive from segmented growth trajectory analysis incorporating chronic respiratory disease prevalence projections, lithium-ion battery cost curves, and reimbursement code revision probabilities. Industry-specific forecast inputs include zeolite molecular sieve supply elasticity and portable system pulse-dose algorithm adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS coverage determination volatility, EU MDR enforcement intensity, and Chinese export licensing shifts for specialized adsorbent materials. Forecasts reflect documented assumptions about patient mobility preference evolution and telehealth platform penetration trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
Supraglottic Device Market
Medical Devices
Endoprosthesis Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Global Prosthetics Market
Medical Devices
South Korea Respiratory Devices Market