
 Asia Pacific Apheresis Market | 2026-2036
Asia Pacific Apheresis Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Apheresis Market Outlook
Membrane separation technology is tilting the Asia Pacific apheresis landscape toward higher-efficiency therapeutic protocols with reduced patient processing times. Asahi Kasei Medical leverages its hollow-fiber membrane expertise to anchor premium device supply across Japanese hospital networks. Terumo BCT competes on integrated system platforms that combine centrifugation with real-time monitoring. Haemonetics dominates aftermarket consumables through dense service contracts with blood donation centers.
Apheresis denotes the extracorporeal separation of blood components, typically employing centrifugal force or semipermeable membranes to isolate platelets, plasma, leukocytes, or erythrocytes while returning uncollected elements to the donor or patient. The procedure operates at blood flow rates of 50-100 mL/min through sterile disposable sets, serving therapeutic removal of pathogenic substances or collection of specific cellular fractions for transfusion or cellular therapy manufacturing. Platelet apheresis and plasma apheresis command the largest installed base, though leukapheresis generates superior margins as CAR-T cell therapy feedstock demand intensifies across oncology and hematology applications. Centrifugation technology retains structural dominance in routine collection settings, while membrane separation is penetrating therapeutic neurology and autoimmune protocols where selective filtration offers clinical advantages.
Japan's PMDA, China's NMPA, and India's CDSCO enforce divergent device classification and clinical evidence requirements that fragment product registration strategies across the region. The EU MDR's extraterritorial influence on Japanese and Korean exporters additionally shapes quality management investments. Stakeholders must monitor regulatory convergence pressures around single-use set sterility standards and software-driven device controls as therapeutic indications expand beyond traditional blood banking into outpatient autoimmune management.
Market Dynamics
Membrane separation technology is compressing patient processing times across Asia Pacific therapeutic apheresis programs, forcing equipment upgrade cycles and reshaping hospital procurement priorities toward integrated system platforms.
Growth Catalysts
- Autoimmune disease burden:Rising lupus and myasthenia gravis caseloads across China and Japan are expanding therapeutic apheresis service lines in tertiary hospitals.
- CDSCO pathway streamlining:India's tightened device registration timelines are accelerating compliance investments from multinational suppliers seeking market entry.
- CAR-T feedstock demand:Leukapheresis collections for cellular therapy manufacturing are commanding premium pricing from oncology centers in South Korea and Australia.
Market Restraints
- Polymer membrane import dependence:Hollow-fiber membrane raw materials concentrate among Japanese and German specialty chemical suppliers, exposing Chinese device assemblers to input cost volatility.
- Single-use set sterility standards:Divergent PMDA and NMPA validation requirements for disposable tubing sets are fragmenting production runs and inflating per-unit costs.
- Centrifugation technology lock-in:Blood donation centers across Australia and Thailand face high switching costs from legacy centrifugal platforms, slowing membrane adoption in routine collection settings.
Strategic Opportunities
- Outpatient autoimmune protocols:Underpenetrated same-day therapeutic apheresis clinics in Vietnam and Indonesia offer first-mover positioning for membrane-based portable systems.
- PLI scheme alignment:India's production-linked incentive framework for medical devices is attracting component localization investments from membrane module suppliers.
- Software-driven device controls:Integration of real-time hematocrit monitoring with automated anticoagulant dosing is opening differentiation paths for next-generation platforms.
Industry Challenges
- Perfusionist training scarcity:Qualified operators for therapeutic apheresis procedures remain concentrated in Japan and South Korea, constraining service expansion in Southeast Asia.
- Dual registration burden:Exporters serving both Japanese hospital networks and Chinese domestic manufacturers must maintain parallel quality management systems under PMDA and NMPA inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Apheresis Market |
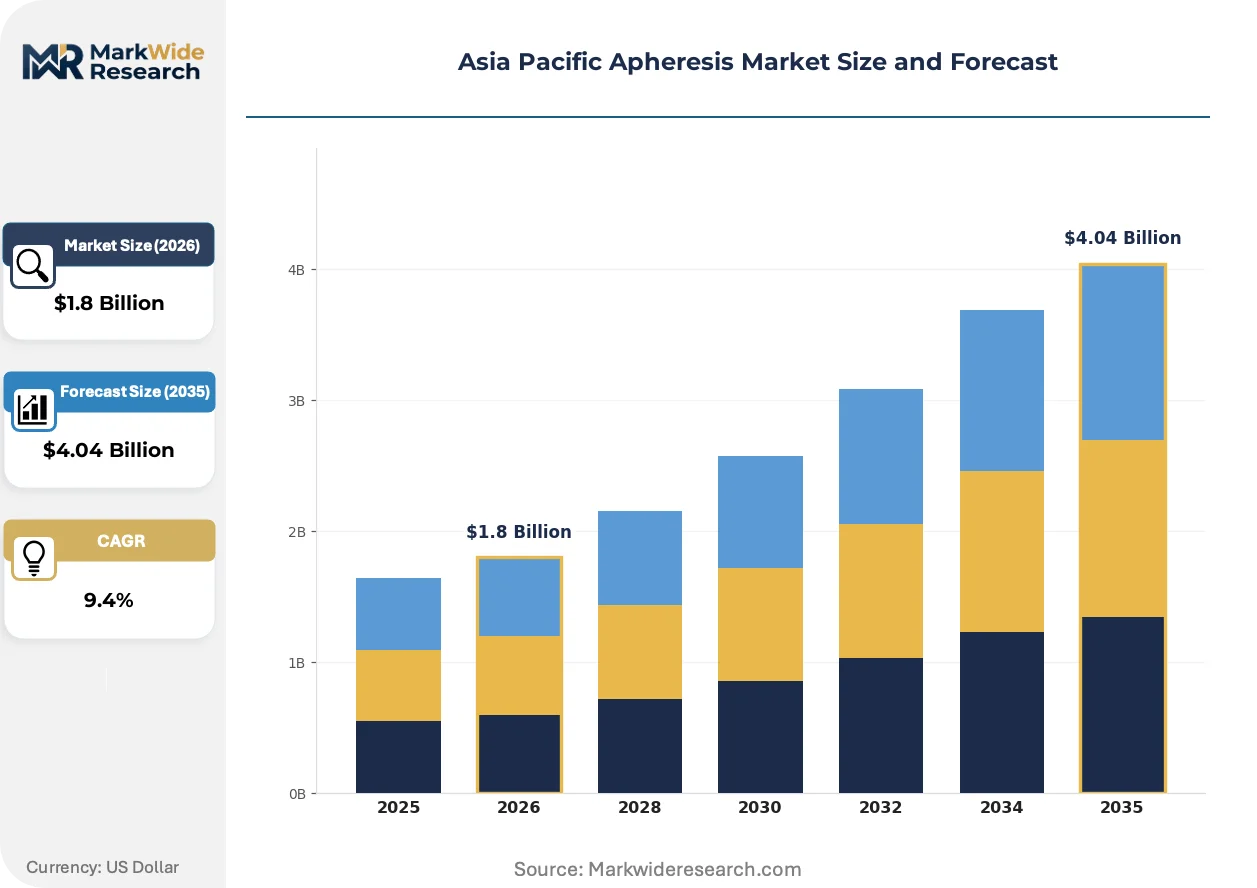
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platelet Apheresis, Plasma Apheresis, Leukapheresis, Erythrocytapheresis End User: Hospitals, Blood Donation Centers, Clinical Research Organizations, Diagnostic Laboratories Technology: Membrane Separation, Centrifugation, Continuous Flow Processing, Filtration Technology Application: Oncology, Hematology, Neurology, Autoimmune Disorders |
| Companies Covered | Asahi Kasei Medical Co., Ltd., Terumo BCT, Inc., Haemonetics Corporation, Fresenius Medical Care, B. Braun Melsungen AG, Kaneka Corporation, Cerus Corporation, Nikkiso Co., Ltd., Kawasumi Laboratories Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Apheresis Market Strategic Shifts
Automation and selective filtration are compressing the gap between blood banking efficiency and therapeutic precision, redrawing competitive boundaries among device architectures.
Continuous-flow membrane separation systems are penetrating neurology and autoimmune protocols where selective plasma filtration replaces bulk centrifugal processing. Japanese university hospitals are piloting these platforms for myasthenia gravis and Guillain-Barré syndrome cases, rendering obsolete the extended dwell times associated with intermittent centrifugal cycles. The shift is compressing treatment sessions from four hours to ninety minutes.
China's NMPA is tightening software validation requirements for apheresis device controls, mandating cybersecurity documentation and algorithm transparency for automated anticoagulant dosing modules. Domestic manufacturers in Suzhou and Shenzhen are restructuring development pipelines to accommodate pre-market submission delays. Japanese exporters face parallel scrutiny under METI's cybersecurity labeling framework for connected medical devices.
Service unbundling is fragmenting traditional equipment-consumable bundling contracts across Australian and South Korean blood centers. Procurement teams are separating device purchases from disposable set supply agreements, introducing competitive bidding for membrane module suppliers independent of platform OEMs. The decoupling is most advanced in Victoria's hospital procurement consortium, where three-year disposable tenders now run on separate cycles from capital equipment refresh programs.
Asia Pacific Apheresis Market Segmentation
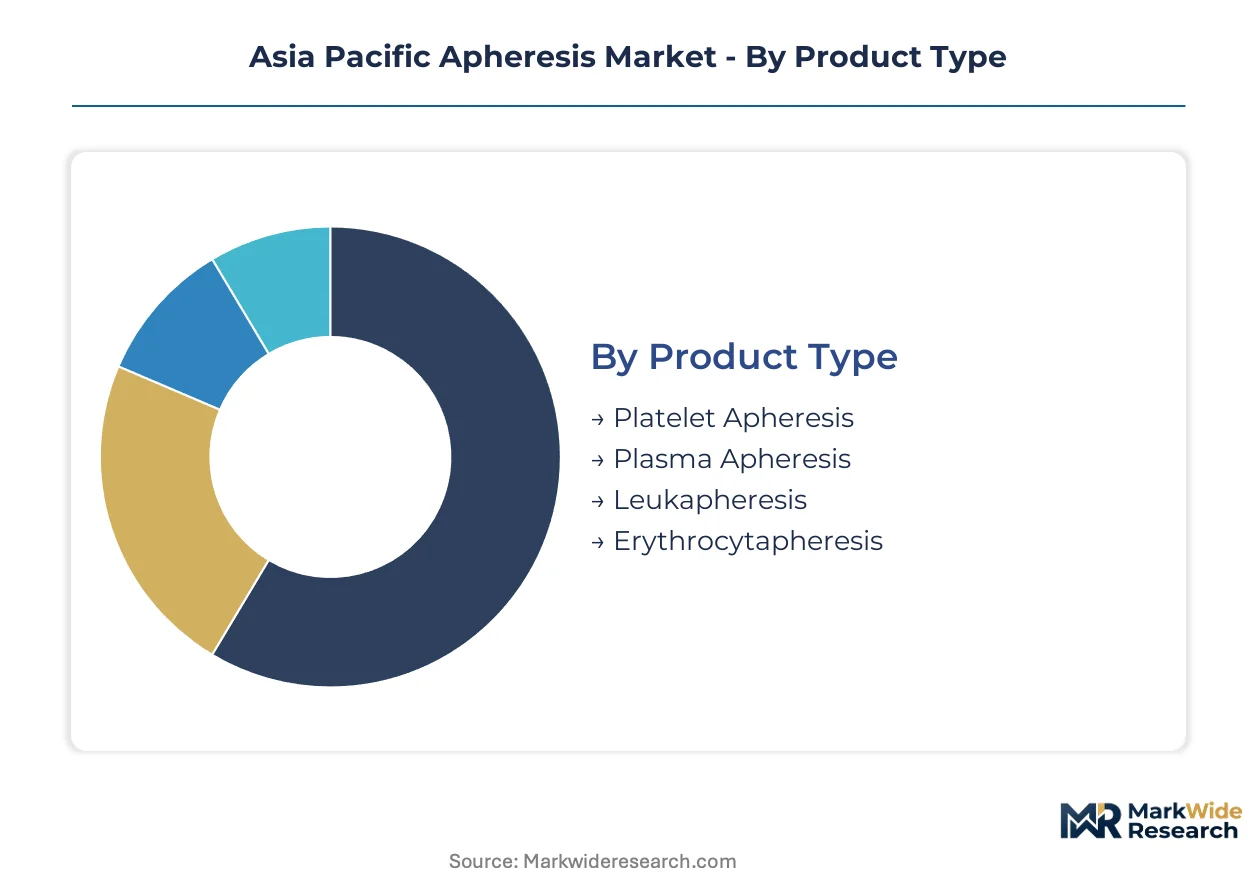
Segmentation in the Asia Pacific apheresis market reveals divergent technology maturities and application intensities. Product architecture, end-user infrastructure, and therapeutic protocols each create distinct procurement patterns and margin profiles across the region's healthcare systems.
Product Type:
Mature collection modalities coexist with emerging therapeutic segments across hospital and blood center procurement cycles.
- Platelet Apheresis:Centrifugal separation systems harvest platelet concentrates from single donors at yields exceeding traditional pooled donations. Japanese and Australian blood centers deploy these platforms for routine transfusion inventory, though membrane-based alternatives are penetrating selective protocols in tertiary hospitals.
- Plasma Apheresis:Therapeutic plasma exchange dominates autoimmune and neurological service lines in South Korea and China. Shanghai's tertiary hospitals report expanding session volumes for lupus nephritis and myasthenia gravis cases, compressing treatment timelines through continuous-flow membrane systems.
- Leukapheresis:CAR-T manufacturing feedstock commands premium positioning across Singapore and Melbourne oncology hubs.
- Erythrocytapheresis:Sickle cell disease protocols in Thailand and Malaysia drive specialized red cell exchange demand.
Platelet apheresis retains volume leadership; leukapheresis holds the steepest expansion curve.
End User:
Facility infrastructure and reimbursement pathways fragment procurement authority across institutional categories.
- Hospitals:Tertiary medical centers in Tokyo, Seoul, and Beijing anchor therapeutic apheresis service expansion. Myasthenia gravis and Guillain-Barré protocols are migrating from inpatient to same-day settings, forcing capital equipment refresh cycles and perfusionist training investments.
- Blood Donation Centers:Routine component collection concentrates in national blood services across Australia, Japan, and South Korea. Legacy centrifugal platform lock-in slows membrane adoption despite processing efficiency gains.
- Clinical Research Organizations:Cell therapy manufacturing partnerships in Singapore and Sydney drive specialized leukapheresis contracting.
- Diagnostic Laboratories:Specialized reference labs in Mumbai and Jakarta deploy apheresis for rare disease sample processing.
Blood donation centers dominate installed base; hospitals generate the fastest margin expansion.
Technology:
Platform architecture determines processing speed, selectivity, and regulatory compliance burden across therapeutic and collection applications.
- Membrane Separation:Hollow-fiber and flat-sheet membranes enable selective plasma filtration without cellular sedimentation. Japanese university hospitals pilot these systems for ninety-minute autoimmune sessions, displacing four-hour centrifugal cycles.
- Centrifugation:Density-gradient separation remains structurally dominant in routine blood banking. Australian and Thai donation centers face high switching costs from installed base amortization and operator retraining requirements.
- Continuous Flow Processing:Integrated pump-membrane architectures reduce anticoagulant exposure in extended therapeutic protocols.
- Filtration Technology:Adsorptive and selective filtration modules target pathogenic antibody removal in specialized neurology applications.
Centrifugation commands current installed base; membrane separation is climbing the fastest.
Application:
Therapeutic indication intensity varies by disease prevalence, reimbursement coverage, and specialist availability across national health systems.
- Oncology:Leukapheresis for CAR-T feedstock manufacturing concentrates in Seoul, Singapore, and Sydney cellular therapy hubs. Premium pricing reflects sterile collection requirements and tight turnaround windows for cryopreservation.
- Hematology:Sickle cell and thalassemia protocols drive erythrocytapheresis demand in Thailand, Malaysia, and India's southern states. Transfusion-dependent patient populations justify dedicated service line investments.
- Neurology:Guillain-Barré and chronic inflammatory demyelinating polyneuropathy cases expand plasma exchange volumes in Japanese and South Korean tertiary centers.
- Autoimmune Disorders:Lupus nephritis and myasthenia gravis are penetrating outpatient settings in China's tier-one cities.
Hematology retains procedural volume leadership; oncology holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese membrane manufacturers export hollow-fiber modules to Chinese device assemblers, while Australian blood centers import centrifugal platforms from European suppliers. This trade architecture shapes competitive positioning across the region's therapeutic and collection segments.
China
Shanghai's tertiary hospitals are expanding plasma exchange volumes for lupus nephritis and myasthenia gravis cases. NMPA tightened software validation requirements for automated anticoagulant dosing modules in 2024. Suzhou and Shenzhen manufacturers are restructuring development pipelines to accommodate pre-market submission delays.
Japan
Kanto region university hospitals pilot ninety-minute autoimmune protocols using continuous-flow membrane systems. PMDA enforces cybersecurity labeling under METI's framework for connected medical devices. Tokyo hospital networks anchor premium device supply through dense service contracts with domestic membrane specialists.
India
Mumbai's reference laboratories deploy apheresis for rare disease sample processing. CDSCO streamlined device registration timelines, accelerating compliance investments from multinational suppliers. Maharashtra and Gujarat are attracting component localization under the PLI scheme for medical devices.
South Korea
Seoul's oncology centers command premium pricing for leukapheresis collections serving CAR-T manufacturing. MFDS aligns with international sterility standards for single-use disposable sets. The Busan-Ulsan corridor concentrates cell therapy manufacturing partnerships driving specialized contracting.
Australia
Victoria's hospital procurement consortium unbundles equipment and disposable set contracts, introducing competitive bidding for membrane modules. TGA oversees device registration with emphasis on software-driven controls. Melbourne anchors cellular therapy hub demand alongside Sydney's research infrastructure.
Asia Pacific Apheresis Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Premium integrated system platforms anchor Japanese and Australian hospital networks through dense service relationships. Mid-tier membrane module suppliers penetrate unbundled procurement channels in South Korea and Victoria. Value-oriented device assemblers in China scale production for domestic therapeutic expansion. Dominant competitive moves include geographic licensing partnerships and backward integration into hollow-fiber membrane production.
Among Japanese medical technology conglomerates, Asahi Kasei Medical Co., Ltd. and Terumo BCT, Inc. exemplify the premium integrated platform archetype, occupying positions that leverage membrane expertise and real-time monitoring capabilities respectively. Haemonetics Corporation represents the consumables-dominant model, anchoring aftermarket revenue through service density with blood donation centers. These three entities collectively illustrate the strategic divergence between technology-led platform control and recurring revenue capture in the regional market structure.
| Leading Market Players |
|---|
| Asahi Kasei Medical Co., Ltd. |
| Terumo BCT, Inc. |
| Haemonetics Corporation |
| Fresenius Medical Care |
| B. Braun Melsungen AG |
| Kaneka Corporation |
| Cerus Corporation |
| Nikkiso Co., Ltd. |
| Kawasumi Laboratories Inc. |
| Others |
Value Chain & Pricing Dynamics
Hollow-fiber membrane production concentrates in Japan and Germany, anchoring premium pricing power for therapeutic device OEMs while Chinese assemblers absorb margin compression from polymer import volatility. This upstream concentration funnels value toward membrane specialists and squeezes downstream device margins across the Asia Pacific therapeutic apheresis landscape.
Pricing Analysis
Centrifugal platform pricing holds steady against membrane system premiums spanning three technology generations. Three-tier pricing structure across premium, standard, and economy levels separates Japanese university hospital contracts from mid-tier South Korean installations and value-oriented Chinese domestic tenders. Price differentiation rests on software validation tier and hollow-fiber membrane origin, with PMDA-certified modules commanding substantial premiums over NMPA-equivalent alternatives. Cost compression in standard-tier equipment is intensifying because domestic Chinese manufacturers are scaling membrane module assembly. Blood donation centers exhibit highest price sensitivity due to government procurement mandates, while CAR-T feedstock collectors show lowest sensitivity given sterile collection requirements.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk planning for membrane-dependent device assemblers. Geographic supply concentration centers on Japan for hollow-fiber spinning, Germany for specialty polymer resins, and China for disposable set injection molding. Raw material dependencies draw from polysulfone polymers, polypropylene housings, and anticoagulant coating chemistries. Single-source vulnerability persists for sub-micron pore membrane grades qualified under PMDA sterility protocols. Distribution runs through hospital procurement consortia in Australia and South Korea, blood service national tenders in Japan, and provincial health authority frameworks across China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across autoimmune service line deployment creates niche positioning opportunities for technology-differentiated entrants. Outpatient protocol expansion in Southeast Asia and unbundled procurement trends in Australia and South Korea reward specialized membrane module suppliers.
For Market Incumbents: Build regulatory certification moats through simultaneous PMDA and NMPA quality management system maintenance. Defensive moves center on backward integration into hollow-fiber membrane production to offset polymer import volatility, and exclusive service contracting with Tokyo and Seoul tertiary hospital networks to lock out membrane platform competitors. The threat of unbundled procurement in Australian blood centers demands channel control investments through integrated device-consumable bundling. For New Entrants and Emerging Players: Vietnam and Indonesia outpatient autoimmune clinics represent the most penetrable geographic expansion corridor. White-space targets include portable membrane systems for same-day therapeutic protocols and software-driven anticoagulant dosing modules for NMPA pre-market submission. Go-to-market positioning should emphasize ninety-minute treatment compression against legacy centrifugal cycle times, targeting perfusionist-scarce Southeast Asian markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across software-validated device control development. Long-term viability over the next decade favors platform players with regulatory certification density across multiple Asia Pacific jurisdictions. Acquisition target archetypes include hollow-fiber membrane specialists with PMDA master files and regional service organizations with dense hospital technician training networks. The signal to watch is NMPA software validation backlog duration as an indicator of competitive moat durability for compliant device portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA-NMPA Dual Certification | Parallel quality systems unlock premium hospital network access across Japan and China. |
| Membrane Module Localization | Indian PLI scheme alignment reduces polymer import exposure for device assemblers. |
| Software Companion Development | Real-time hematocrit monitoring integration differentiates next-generation therapeutic platforms. |
| Hospital System Partnership | Dense service contracts with Tokyo networks anchor recurring consumable revenue streams. |
| Reimbursement Strategy | Outpatient autoimmune protocol coding expansion drives membrane system adoption in China. |
Study Parameters
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings. Primary interviews with perfusionists, biomedical engineers, hospital purchasing committee members, and blood center operations directors combined with secondary validation against PMDA device registration records, NMPA submission databases, CDSCO approval timelines, and GPO contract repositories. Bottom-up installed base modeling and top-down therapeutic procedure volume estimates triangulate market sizing across the analysis window.
Calibration against historical membrane module shipment data and centrifugal platform replacement cycles refines projection accuracy. Segmentation dimensions modeled include technology architecture, end-user facility type, therapeutic application, and country-specific regulatory cluster. CAGRs derive from procedure volume elasticity to autoimmune disease prevalence and CAR-T manufacturing capacity expansion. Industry-specific forecast inputs incorporate leukapheresis collection pricing trends and software validation timeline assumptions.
Practitioners should monitor CDSCO registration pathway efficiency and NMPA cybersecurity documentation requirements for early signals of competitive positioning shifts. Forecasts reflect assumptions around membrane technology substitution rates and outpatient protocol reimbursement expansion that could revise trajectory if sterility standards diverge further or perfusionist training bottlenecks intensify. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
China General Surgical Devices Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Lyophilized Injectable Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Cheek Implants Market
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
US C-Arms Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market