
 Global Vaccine Delivery Devices Market | 2026-2036
Global Vaccine Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vaccine Delivery Devices Market Foresight
Aftermarket service revenue for device calibration and needle-free injector maintenance is rewriting margin economics for incumbent suppliers. Becton Dickinson and Company leverages its installed base of traditional syringes to cross-sell auto-injector platforms. Gerresheimer AG anchors European glass primary packaging demand through captive borosilicate capacity. SCHOTT AG dominates pharmaceutical tubing supply for prefilled syringe customers across three continents.
Vaccine delivery devices are precision-engineered instruments designed to administer antigenic formulations through intramuscular, subcutaneous, intradermal, or mucosal routes, with critical specifications including dead-space volume below 0.05 mL, siliconization consistency, and elastomer plunger compatibility with biological stabilizers. Their primary commercial purpose is to ensure dose accuracy, reduce contamination risk, and enable cold-chain-independent distribution in resource-limited settings. Prefilled syringes capture the largest revenue share among product types due to their integration with biologics manufacturing workflows and reduction of medication errors at the point of care. Microneedle patches represent the fastest-expanding delivery technology segment, driven by thermostability advantages and elimination of sharps waste disposal requirements. Pediatric immunization applications command sustained volume demand through government procurement contracts tied to national immunization schedules.
The FDA regulates these devices as combination products under 21 CFR 3.2, requiring human factors validation for self-administration platforms, while the EMA's Medical Device Regulation mandates clinical evidence for novel delivery mechanisms seeking CE marking. WHO prequalification standards shape access for low-income country tenders, creating a dual-track compliance burden for multinational manufacturers. Stakeholders must monitor evolving sterilization validation requirements for polymer-based devices as regulatory agencies tighten endotoxin thresholds for parenteral administration systems.
Market Dynamics
FDA's updated biocompatibility standards for combination products are forcing engineering redesigns across the installed base, while WHO prequalification requirements create parallel compliance tracks for multinational suppliers serving low-income tenders.
Growth Catalysts
- Pediatric immunization schedules:Government procurement contracts tied to national vaccination programs sustain volume demand across public health systems in the United States, India, and Brazil.
- EMA Medical Device Regulation:Clinical evidence mandates for novel delivery mechanisms accelerate CE marking investments, filtering out undercapitalized entrants.
- Microneedle thermostability:Cold-chain-independent distribution capabilities unlock last-mile delivery in resource-limited settings without refrigerated infrastructure.
Market Restraints
- Borosilicate glass supply concentration:Captive furnace capacity in Germany and China limits primary packaging expansion for prefilled syringe customers.
- Endotoxin threshold tightening:FDA and EMA sterilization validation requirements for polymer-based devices extend qualification timelines by 12-18 months.
- Siliconization consistency:Elastomer plunger compatibility failures with biological stabilizers force batch rejection rates above acceptable thresholds for biologics manufacturers.
Strategic Opportunities
- Needle-free injector maintenance services:Aftermarket revenue streams for device calibration rewrite margin economics for incumbent suppliers with installed bases.
- Intramuscular-to-intradermal route migration:Dose-sparing applications in tuberculosis and rabies vaccines create demand for precision-depth control mechanisms.
- India's PLI scheme for medical devices:Production-linked incentives attract component manufacturing for auto-injector and pen-injector platforms serving domestic and export markets.
Industry Challenges
- Human factors engineering talent:Self-administration platform design requires specialized usability validation expertise that outpaces current training pipeline output.
- Legacy sterilization asset reconfiguration:Ethylene oxide alternatives for polymer-based devices demand capital-intensive facility upgrades without guaranteed regulatory acceptance.
- Dual-track compliance documentation:WHO prequalification standards diverge from FDA and EMA requirements, forcing redundant clinical evidence generation for the same device architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vaccine Delivery Devices Market |
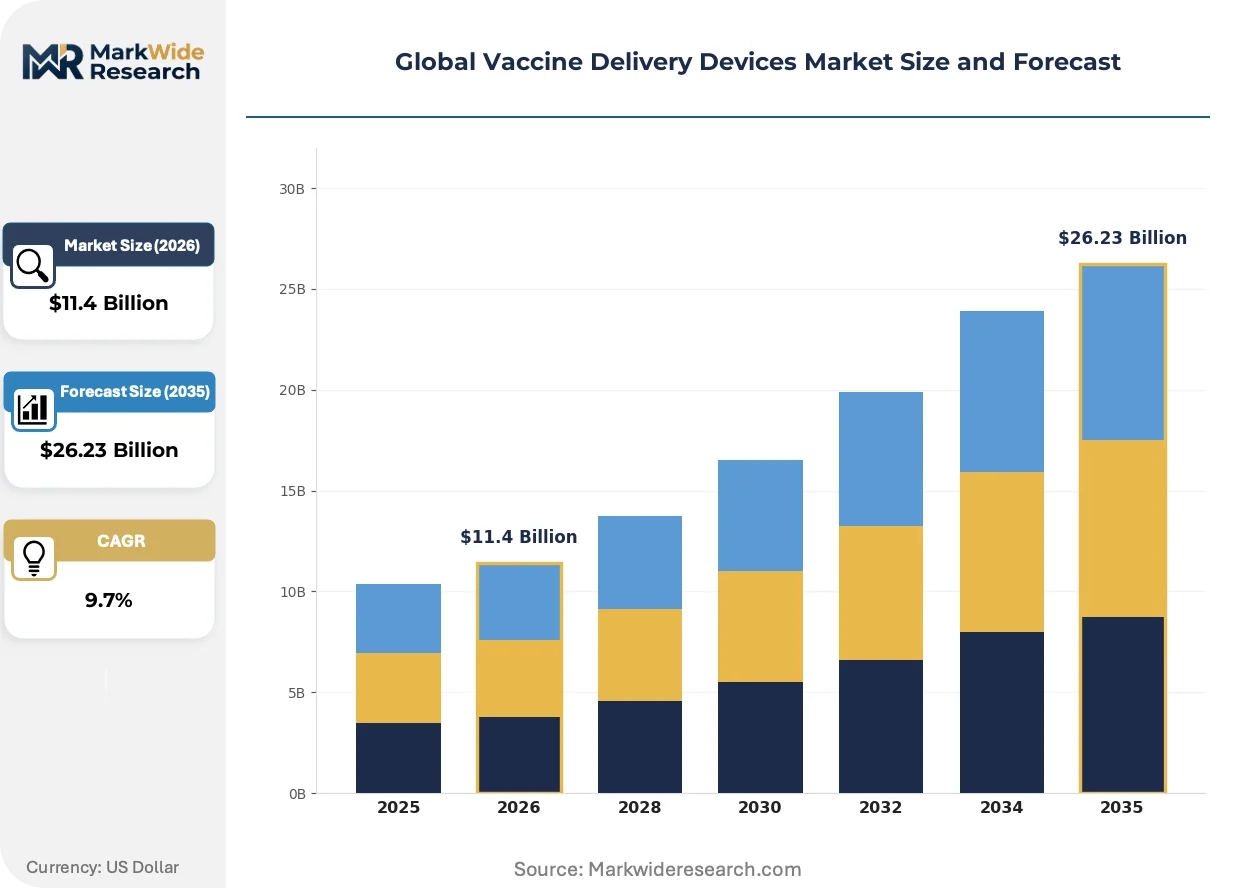
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.23 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle-Free Injectors, Auto-Injectors, Prefilled Syringes, Jet Injectors, Traditional Syringes Application: Pediatric Immunization, Adult Immunization, Travel Vaccination, Occupational Health, Veterinary Vaccination End User: Hospitals, Immunization Clinics, Pharmaceutical Companies, Government Health Agencies, Research Laboratories Delivery Technology: Microneedle Patches, Intradermal Delivery, Needle and Syringe, Aerosol Vaccination, Nasal Sprays |
| Companies Covered | Becton Dickinson and Company, Gerresheimer AG, SCHOTT AG, Terumo Corporation, West Pharmaceutical Services, Nipro Corporation, PharmaJet, Vaxxas, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vaccine Delivery Devices Market Shifts & Advancements
Device architecture is compressing around cold-chain elimination and sharps waste reduction, with regulatory convergence on combination product standards accelerating platform consolidation.
Microneedle patches are collapsing the distinction between vaccine storage and administration by integrating antigen stabilization directly into the delivery substrate. Public health programs in Ghana and Bangladesh are piloting thermostable measles-rubella formulations that eliminate refrigerated transport requirements. This convergence is collapsing total cost per immunized patient by removing logistics infrastructure from the value chain.
REACH restrictions on extractables and leachables from pharmaceutical contact materials are forcing polymer reformulation for syringe barrels and plunger components. European manufacturers are migrating to cyclic olefin polymer alternatives ahead of 2026 compliance deadlines. Prefilled syringe customers with biologics portfolios face the steepest reformulation costs due to protein-surface interaction sensitivity.
Service unbundling from device procurement is fragmenting supplier-buyer relationships in the United States. Large hospital systems are separating calibration contracts from capital equipment purchases, pressuring traditional bundled pricing models. This shift is most visible in IDN procurement for influenza and COVID-19 mass vaccination campaigns, where device utilization rates vary seasonally.
Global Vaccine Delivery Devices Market Segmentation
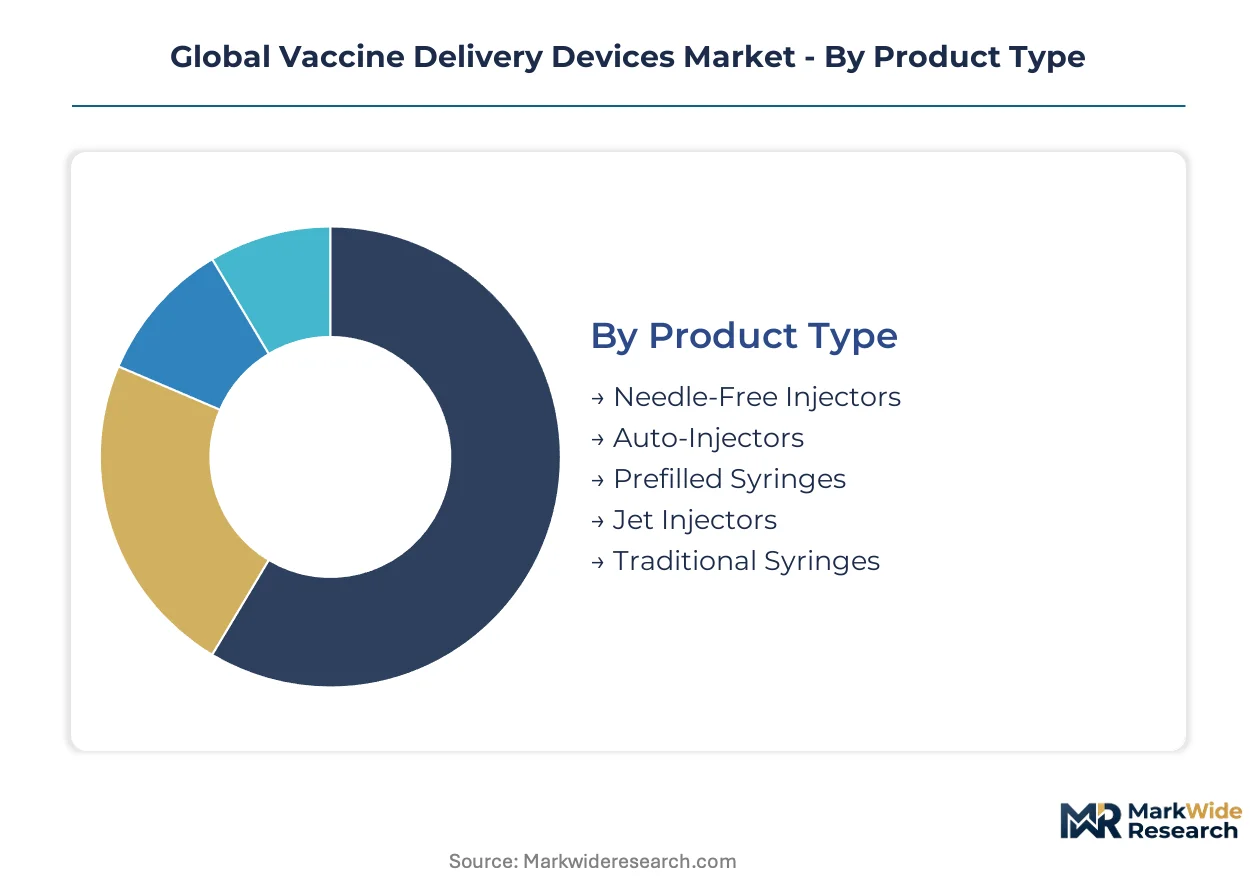
Segmentation in vaccine delivery devices reveals how procurement priorities diverge across clinical settings and regulatory environments. Product architecture, application context, and end-user purchasing power collectively determine pricing tolerance and compliance requirements.
Product Type:
Cost tier stratification across device categories separates capital-intensive platforms from commodity consumables, with reimbursement codes reinforcing these boundaries.
- Prefilled Syringes:Glass-barrel assemblies with elastomer plungers and bonded needle systems integrate directly into biologics fill-finish operations. Demand concentrates in the United States and Germany where pharmaceutical manufacturers prioritize contamination risk reduction and medication error prevention in institutional settings.
- Auto-Injectors:Spring-loaded or gas-powered mechanisms with hidden needles enable self-administration by patients without clinical training. Demand concentrates in Germany and Japan where EMA and PMDA human factors validation requirements have created specialized engineering competencies among domestic suppliers.
- Needle-Free Injectors:High-pressure liquid or powder projection systems eliminate sharps waste disposal requirements. Demand clusters in occupational health programs across Brazil and India.
- Jet Injectors:Multi-use nozzle systems with sterilizable fluid pathways serve mass immunization campaigns. Procurement flows through government health agencies in Bangladesh and Nigeria.
- Traditional Syringes:Luer-lock or slip-tip disposable designs remain the lowest-cost option for high-volume pediatric programs. Volume concentrates in India's Universal Immunization Programme and Brazil's Sistema Único de Saúde.
Prefilled syringes hold installed capacity. Auto-injectors are rotating up the share rankings.
Application:
Application context dictates device specification requirements, with pediatric programs demanding ultra-low dead-space designs and travel medicine prioritizing portability.
- Pediatric Immunization:Ultra-low dead-space syringes with 0.5 mL or 0.25 mL maximum volume and color-coded dose markers prevent medication errors. Government procurement contracts in India, Nigeria, and Indonesia sustain volume demand through national immunization schedules tied to WHO prequalification standards.
- Adult Immunization:Standard 1 mL to 3 mL syringes and emerging microneedle patch platforms serve influenza, pneumococcal, and shingles vaccination. Demand concentrates in the United States pharmacy retail channel and Japan's municipal health centers.
- Travel Vaccination:Compact auto-injector and prefilled syringe formats prioritize cold-chain independence and minimal storage footprint. Private clinics in the United Kingdom and Australia drive procurement for yellow fever and Japanese encephalitis protection.
- Occupational Health:Needle-free and jet injector systems reduce sharps injury liability in high-turnover workforce settings. Corporate health programs in Brazil and South Africa favor these platforms for hepatitis B and influenza campaigns.
- Veterinary Vaccination:Large-volume syringes with reinforced barrels and luer-lock security serve livestock operations. Demand clusters in cattle ranching regions of Argentina and dairy cooperatives in New Zealand.
Pediatric immunization anchors procurement volume. Adult immunization is climbing the fastest as aging demographics expand eligibility pools.
End User:
Customer purchasing power and compliance sophistication create distinct procurement channels, with pharmaceutical companies demanding device-drug combination validation and government agencies prioritizing unit cost minimization.
- Pharmaceutical Companies:Device selection occurs during late-stage clinical trials with FDA combination product filings or EMA marketing authorization applications. Biologics manufacturers in Switzerland and the United States drive specifications for siliconization consistency and extractables testing.
- Government Health Agencies:Tender-based procurement with WHO prequalification requirements shapes demand for low-cost, thermostable platforms. Ministries of health in India, Ethiopia, and Vietnam dominate volume through Gavi alliance funding mechanisms.
- Hospitals:Integrated delivery networks in the United States separate device procurement from pharmacy formulary decisions, creating multi-stakeholder approval processes. IDN consolidation is pressuring suppliers toward service-unbundled contracting.
- Immunization Clinics:Standalone vaccination centers in France and Canada require rapid patient throughput with minimal cold-chain infrastructure. These settings favor prefilled syringes with passive safety features.
- Research Laboratories:Investigational device exemptions and clinical trial supplies demand flexible, small-batch manufacturing with rapid design iteration. Contract research organizations in Singapore and Denmark source specialized delivery platforms for novel adjuvant formulations.
Pharmaceutical companies command specification authority. Government health agencies are gaining share fastest through pandemic preparedness stockpiling.
Delivery Technology:
Technology maturity separates established parenteral routes from emerging mucosal and transdermal platforms, with regulatory evidence requirements determining commercialization timelines.
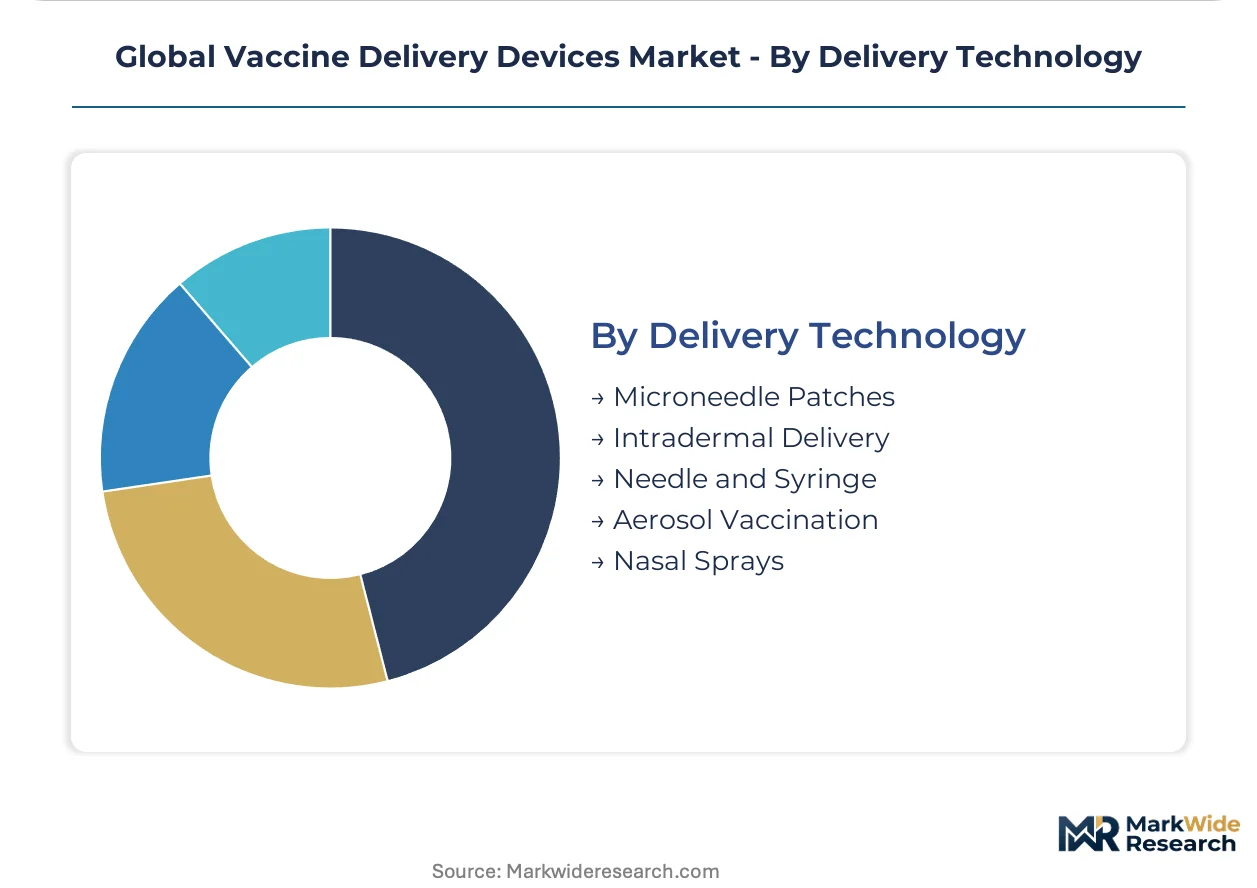
- Microneedle Patches:Dissolving or hydrogel-forming microprojections with integrated antigen stabilization enable cold-chain-independent distribution. Pilot programs in Ghana and Bangladesh for measles-rubella formulations are validating thermostability claims without refrigerated infrastructure.
- Needle and Syringe:Conventional hypodermic delivery with intramuscular, subcutaneous, or intradermal route flexibility remains the clinical standard. Regulatory familiarity and lowest unit cost sustain dominance in India's public health system and Nigeria's primary care networks.
- Intradermal Delivery:Precision-depth control mechanisms with 1-3 mm needle projection enable dose-sparing tuberculosis and rabies vaccination. Demand concentrates in Brazil's municipal health programs and Thailand's rabies post-exposure prophylaxis clinics.
- Nasal Sprays:Mucosal atomization devices targeting nasal-associated lymphoid tissue for respiratory pathogen vaccines. Development programs in the United States and United Kingdom are advancing live attenuated influenza and next-generation COVID-19 platforms.
- Aerosol Vaccination:Nebulized or dry powder inhalation for pulmonary mucosal immunity. Research-stage applications in South Africa and China are exploring tuberculosis and measles aerosol delivery for mass campaign efficiency.
Needle and syringe systems hold installed capacity. Microneedle patches are gaining share fastest as thermostability validation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive government tenders in India and Nigeria coexist with premium procurement in Germany and the United States, creating divergent margin structures across geographies. The analysis window reveals how regulatory stringency and purchasing power reshape competitive positioning.
United States
Hospital procurement consolidation and IDN service-unbundling are compressing supplier margins. FDA combination product regulations under 21 CFR 3.2 mandate human factors validation for self-administration platforms. Boston and Research Triangle Park host specialized engineering consultancies serving biologics manufacturers.
Germany
EMA Medical Device Regulation clinical evidence requirements filter undercapitalized entrants from the European market. REACH restrictions on extractables and leachables force polymer reformulation for syringe components ahead of 2026 deadlines. Bavaria's captive borosilicate furnace capacity anchors primary packaging supply for prefilled syringe customers.
China
NMPA marketing authorization applications for novel delivery mechanisms accelerate domestic platform development. National vaccination infrastructure scaling drives volume procurement for pediatric immunization programs. Shanghai and Suzhou industrial clusters concentrate auto-injector and pen-injector component manufacturing.
India
PLI scheme production-linked incentives attract medical device component manufacturing for export markets. WHO prequalification standards shape tender requirements for low-cost, thermostable platforms. Gujarat and Maharashtra host contract manufacturers serving Gavi alliance procurement mechanisms.
Brazil
ANVISA regulatory convergence with FDA standards accelerates CE-marked device import substitution. Municipal health programs drive demand for intradermal delivery precision-depth control in tuberculosis vaccination. São Paulo anchors occupational health procurement for needle-free hepatitis B campaigns.
Global Vaccine Delivery Devices Market Competitive Landscape
Capability concentration sits with precision-engineering specialists; scale advantage sits with diversified healthcare conglomerates. The market structures around three tiers: glass primary packaging incumbents with captive furnace assets, polymer device specialists with sterilization validation expertise, and emerging microneedle platform developers with thermostability IP. Dominant competitive moves include backward integration into borosilicate supply and strategic partnerships for combination product regulatory filings.
Among diversified healthcare conglomerates, Becton Dickinson and Company occupies a position exemplifying installed-base leverage for cross-selling auto-injector platforms. SCHOTT AG and Gerresheimer AG represent the glass primary packaging tier, anchoring pharmaceutical tubing and borosilicate capacity respectively. Vaxxas sits within the emerging platform tier, exemplifying microneedle patch developers pursuing thermostability validation.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Gerresheimer AG |
| SCHOTT AG |
| Terumo Corporation |
| West Pharmaceutical Services |
| Nipro Corporation |
| PharmaJet |
| Vaxxas |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Borosilicate furnace capacity in Germany and China anchors primary packaging supply for prefilled syringe customers, concentrating margin capture with glass incumbents while forcing polymer device specialists to compete on aftermarket service attach rates rather than unit economics.
Pricing Analysis
Aftermarket calibration and needle-free injector maintenance contracts drive lifetime value for incumbent suppliers with installed bases. Three-tier pricing structure across premium auto-injector platforms, standard prefilled syringes, and economy traditional syringes separates specification-grade biologics customers from government tender buyers. Cost compression in polymer-based devices is intensifying because REACH extractables compliance demands reformulation investment. Government health agencies in India and Nigeria exhibit highest price sensitivity; pharmaceutical companies in Switzerland and the United States demonstrate lowest sensitivity due to combination product validation requirements.
Supply Chain Analysis
High-purity borosilicate glass feedstock draws from captive furnace operations in Bavaria and specialized tubing manufacturers across three continents. Elastomer plunger formulations and cyclic olefin polymer syringe barrels rest on petrochemical supply chains concentrated in Germany, China, and Japan. Single-source vulnerability in pharmaceutical-grade siliconization chemistry extends qualification timelines when primary suppliers face capacity constraints. Distribution runs through pharmaceutical fill-finish manufacturers for prefilled syringes, direct government tender channels for pediatric programs, and IDN procurement offices for hospital-system auto-injector deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States and Gavi alliance procurement centralization in low-income markets, fragmenting supplier pricing authority across divergent purchasing archetypes.
For Market Incumbents: Insulate installed-base economics by locking in multi-year calibration service contracts before IDN procurement unbundling accelerates. Backward integration into borosilicate furnace capacity secures primary packaging margin pools threatened by Chinese furnace expansion. Microneedle platform developers with thermostability IP represent the most credible substitute technology threat requiring monitoring. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported component manufacturing for auto-injector platforms serving export markets. Occupational health needle-free procurement in Brazil offers the most penetrable segment given limited incumbent service infrastructure. A regulatory-first go-to-market angle targeting WHO prequalification ahead of FDA submission reduces dual-track compliance burden. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed polymer device specialists holding sterilization validation expertise but lacking glass primary packaging integration. The five-to-ten year viability window favors platforms with demonstrated thermostability validation over early-stage delivery technology. Watch for microneedle patch pilot program conversion rates in Ghana and Bangladesh as inflection indicators for cold-chain-independent platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Supply | Captive furnace capacity locks in primary packaging margins for prefilled syringe customers across three continents. |
| WHO Prequalification Fast-Track | Accelerated tender access for low-income country procurement through Gavi alliance funding mechanisms. |
| Aftermarket Service Unbundling | Separate calibration contracts from capital equipment sales to capture IDN procurement flexibility in the United States. |
| Microneedle Thermostability Validation | Pilot program evidence in Ghana and Bangladesh unlocks cold-chain-independent distribution for last-mile delivery. |
| Dual-Track Regulatory Filing | Parallel FDA combination product and EMA MDR submissions filter undercapitalized competitors from European markets. |
Research Methodology
A standing panel of biomedical engineers, hospital GPO contracts managers, pharmaceutical regulatory affairs leads, and WHO prequalification specialists provided ongoing calibration across primary fieldwork and secondary validation. FDA 510(k) filings, EMA MDR technical documentation, ClinicalTrials.gov device listings, and Gavi alliance procurement databases supplied triangulation anchors. Bottom-up modeling of device unit demand and top-down reconciliation with pharmaceutical fill-finish capacity data ensured cross-verification.
Scenario-bracketing across regulatory approval timelines, borosilicate furnace capacity expansion, and microneedle pilot conversion rates bounded projection uncertainty across the analysis window. Segmentation dimensions included product architecture, application context, end-user purchasing power, and delivery technology maturity. CAGRs derived from weighted average of historical procurement growth and pharmaceutical pipeline conversion rates, with biologics fill-finish capacity utilization and pediatric immunization schedule expansion as key forecast inputs.
Stress conditions across endotoxin threshold tightening, REACH extractables compliance deadlines, and ethylene oxide sterilization alternative validation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory convergence and supply chain concentration. Cross-checking against WHO prequalification approval rates and IDN procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Global Medical Devices Market