
 Pulmonary Heart Valve Replacement Market | 2026-2036
Pulmonary Heart Valve Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Heart Valve Replacement Market Analytics
Transcatheter performance specifications is unwinding the premium tier of pulmonary valve replacement. Edwards Lifesciences dominates transcatheter innovation with sustained R&D commitments to catheter-delivered pulmonary platforms. Medtronic anchors the bioprosthetic segment through backward integration into tissue processing and valve frame manufacturing. Abbott Laboratories differentiates via its structural heart portfolio, leveraging electrophysiology cross-selling into cardiac centers performing hybrid pulmonary procedures.
Pulmonary heart valve replacement encompasses the surgical or percutaneous substitution of diseased pulmonary valves with bioprosthetic, mechanical, or transcatheter devices, typically constructed from bovine pericardium, porcine tissue, or polymeric materials and delivered through open-heart, minimally invasive, or catheter-based approaches to restore right ventricular outflow tract function and prevent right-sided heart failure. Transcatheter valves command the fastest expansion trajectory as cardiac centers shift volume from open-heart surgery toward catheter-based methods that reduce intensive care utilization and accelerate discharge timing. Bioprosthetic valves occupy the mature revenue core, with tissue valves capturing stable demand in pediatric congenital heart programs where durability requirements differ from adult populations.
FDA premarket approval pathways and the EU Medical Device Regulation shape product development timelines, with CE marking transitions under MDR extending certification cycles for novel transcatheter pulmonary platforms. The country's national pharmaceutical regulator in Germany enforces post-market surveillance through BfArM vigilance reporting, while ISO 5840 cardiovascular implant standards govern valve durability testing protocols across all marketed devices. Stakeholders must monitor reimbursement parity between catheter-based and surgical pulmonary valve replacement as health technology assessment bodies recalibrate value frameworks for congenital and acquired right-sided valve disease.
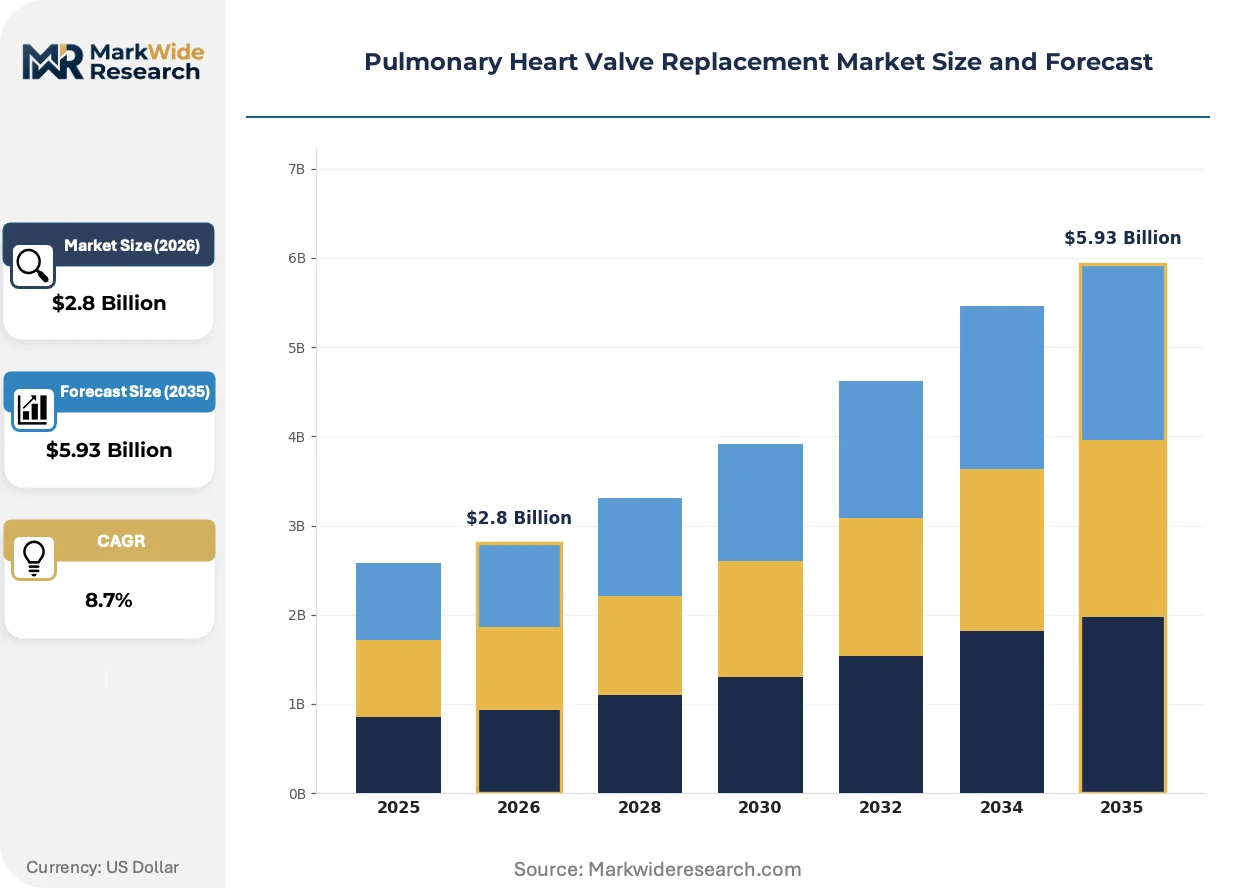
Market Dynamics
Transcatheter delivery platforms are compressing the surgical pulmonary valve replacement volume in cardiac centers, forcing incumbents to reconfigure R&D pipelines toward catheter-compatible designs while maintaining tissue processing capabilities for hybrid procedures.
Growth Catalysts
- EU MDR CE marking pathways:The Medical Device Regulation's streamlined conformity assessment for transcatheter valves accelerates market access for catheter-delivered pulmonary platforms in German, French, and Italian cardiac centers.
- Pediatric congenital heart programs:Specialized pediatric hospitals in the United States drive sustained demand for bioprosthetic tissue valves with growth-accommodating frame designs.
- Minimally invasive delivery modes:Catheter-based deployment reduces intensive care unit utilization and shortens hospital stays, aligning with bundled payment frameworks in Medicare reimbursement systems.
Market Restraints
- Bovine pericardium supply concentration:Tissue processing for bioprosthetic valves depends on concentrated slaughterhouse sourcing in Argentina and Australia, creating raw material vulnerability.
- Transcatheter durability limitations:Polymeric leaflet materials in catheter-delivered valves exhibit accelerated calcification in younger patients, restricting indications to specific age cohorts.
- FDA premarket approval timelines:Extended PMA review cycles for novel transcatheter pulmonary platforms delay commercialization by 18-24 months relative to CE marking pathways.
Strategic Opportunities
- Underpenetrated Indian cardiac centers:CDSCO regulatory harmonization with ISO 5840 standards creates entry pathways for transcatheter platforms in Mumbai, Delhi, and Bangalore hospital networks.
- Hybrid electrophysiology-pulmonary procedures:Convergence of catheter ablation systems with transcatheter valve delivery enables single-session interventions for arrhythmia-congenital valve patients.
- Japan's PMDA Sakigake designation:Fast-track approval incentives for breakthrough cardiovascular devices accelerate first-in-human transcatheter pulmonary trials at Tokyo and Osaka university hospitals.
Industry Challenges
- Interventional cardiologist training deficits:Catheter-based pulmonary valve deployment requires specialized imaging interpretation skills and right ventricular outflow tract navigation expertise that outpaces fellowship program expansion.
- ISO 5840 durability testing bottlenecks:Accelerated wear testing protocols for novel polymeric materials extend certification timelines and increase pre-launch R&D expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Heart Valve Replacement Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioprosthetic Valves, Mechanical Valves, Transcatheter Valves, Tissue Valves End User: Cardiac Centers, Hospitals, Specialty Clinics, Research Institutes Delivery Mode: Open-Heart Surgery, Minimally Invasive Surgery, Catheter-Based Methods, Hybrid Procedures Application: Pulmonary Stenosis, Heart Failure, Valve Regurgitation, Structural Heart Disease |
| Companies Covered | Medtronic, Edwards Lifesciences, Abbott Laboratories, Boston Scientific, CryoLife, LivaNova, Terumo Corporation, Artivion, JenaValve Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Heart Valve Replacement Market Evolving Landscape
Device miniaturization and real-time imaging integration are compressing the procedural learning curve for transcatheter pulmonary interventions while expanding treatable patient anatomies.
Bovine pericardium leaflet construction is bifurcating the transcatheter pulmonary valve segment. Premium cardiac centers in Germany and the United States adopt tissue-engineered pericardial constructs for enhanced durability. This material shift is bifurcating the market into high-durability bioprosthetic tiers and standard polymeric alternatives, with reimbursement differentiation following material cost structures.
EU MDR post-market surveillance requirements are extending vigilance reporting obligations for transcatheter pulmonary valves across all 27 member states. Manufacturers must submit periodic safety update reports to notified bodies, increasing compliance overhead. German BfArM enforcement of these provisions most heavily impacts mid-cap valve developers lacking dedicated regulatory affairs infrastructure.
Hospital procurement committees are consolidating vendor relationships for structural heart programs, bundling transcatheter pulmonary valves with electrophysiology and surgical valve contracts. Cardiac centers in the United States increasingly demand outcome guarantees and procedural training inclusion in purchasing agreements. This consolidation trend is most pronounced in integrated delivery networks across Texas, Florida, and California hospital systems.
Pulmonary Heart Valve Replacement Market Segmentation
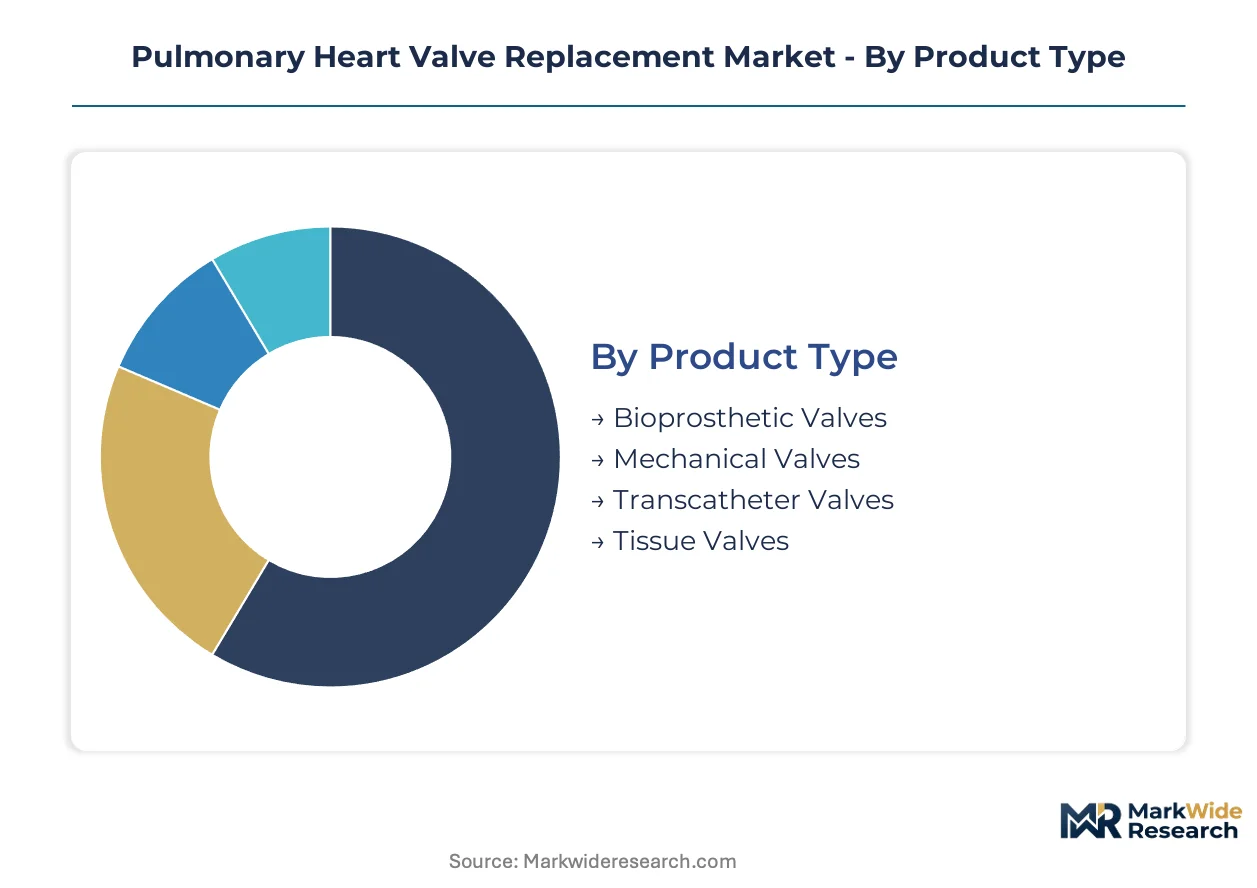
Pulmonary valve replacement segments diverge sharply by reimbursement environment and procedural volume. Product type and delivery mode classifications determine which cardiac centers qualify for bundled payment programs.
Product Type:
Bioprosthetic and transcatheter valves dominate domestic hospital procurement in the United States and Germany, while mechanical valves retain export concentration to emerging cardiac programs.
- Bioprosthetic Valves:Constructed from bovine pericardium or porcine tissue mounted on metallic frames, these devices offer hemodynamic performance without lifelong anticoagulation. Demand concentrates in U.S. pediatric congenital heart programs where valve growth accommodation matters most, though tissue processing costs constrain margin expansion.
- Transcatheter Valves:Delivered via femoral or jugular catheter access, these devices deploy self-expanding nitinol frames with trileaflet tissue constructs. German cardiac centers in Munich and Hamburg drive CE-marked adoption under EU MDR pathways, with reimbursement parity accelerating volume shift from surgical suites.
- Mechanical Valves:Pyrolytic carbon leaflets in titanium housings deliver indefinite durability but require warfarin anticoagulation.
- Tissue Valves:Decellularized xenograft constructs for pediatric reconstruction applications.
Bioprosthetic valves hold the largest share; momentum sits with transcatheter platforms.
End User:
Procurement authority concentrates differently across customer types — integrated delivery networks dominate hospital purchasing while specialty clinics operate on device consignment models.
- Cardiac Centers:Dedicated structural heart facilities in Cleveland, Texas Medical Center, and Berlin's Charité campus perform high-volume transcatheter pulmonary procedures. These centers negotiate direct manufacturer contracts bypassing group purchasing organizations, extracting training and outcome guarantees as procurement conditions.
- Hospitals:General acute-care facilities with catheterization laboratories but without dedicated congenital programs. Volume concentrates in Medicare-reimbursed cases across Florida and California systems where bundled payment frameworks favor rapid discharge protocols.
- Specialty Clinics:Outpatient-focused facilities performing diagnostic catheterization and valve surveillance.
- Research Institutes:Academic medical centers conducting IDE trials and post-market surveillance studies.
Hospitals command the largest procurement volume; cardiac centers are climbing the fastest in per-site device utilization.
Delivery Mode:
Reimbursement tiers separate surgical from catheter-based approaches, with hybrid procedures commanding premium coding in U.S. Medicare fee schedules.
- Open-Heart Surgery:Median sternotomy with cardiopulmonary bypass remains the reference standard for complex congenital reconstructions. Pediatric hospitals in Boston and Philadelphia maintain surgical volume for Ross procedures and conduit replacements where transcatheter sizing is anatomically prohibited.
- Catheter-Based Methods:Percutaneous deployment via femoral or internal jugular access eliminates sternotomy and bypass time. German cardiac centers report 40% reductions in intensive care utilization versus surgical cohorts, aligning with DRG reimbursement incentives for shortened length of stay.
- Minimally Invasive Surgery:Right thoracotomy or partial sternotomy approaches without full bypass.
- Hybrid Procedures:Combined surgical exposure with catheter deployment in hybrid operating suites.
Open-heart surgery retains the largest procedural base; catheter-based methods are gaining share fastest.
Application:
Indication severity determines device selection — regurgitation dominates transcatheter eligibility while stenosis often requires surgical conduit replacement.
- Pulmonary Stenosis:Congenital or acquired narrowing of the right ventricular outflow tract requiring relief. Surgical conduit replacement in U.S. pediatric programs addresses complex subvalvular obstruction where transcatheter balloons prove insufficient, though reintervention rates drive repeat procedure volume.
- Valve Regurgitation:Incompetent pulmonary valve causing right ventricular volume overload. Transcatheter edge-to-edge repair and valve-in-valve replacement concentrate in adult congenital programs across German university hospitals, with CE-marked devices enabling outpatient procedural migration.
- Heart Failure:Right-sided decompensation secondary to chronic valve dysfunction.
- Structural Heart Disease:Multivalve or complex congenital anatomies requiring staged intervention.
Valve regurgitation holds the largest addressable patient population; pulmonary stenosis presents the steepest expansion trajectory in pediatric volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material sourcing for bioprosthetic tissue valves concentrates in Argentina and Australia, while transcatheter platform development clusters in Germany and the United States where cardiac centers drive procedural innovation.
United States
Pediatric congenital heart programs in Boston and Philadelphia sustain surgical valve demand through Ross procedures and complex conduit replacements. FDA premarket approval pathways shape transcatheter commercialization timelines, with PMA review cycles extending 18-24 months. Medicare bundled payment frameworks in Florida and California hospital systems accelerate catheter-based adoption by rewarding shortened length of stay.
Germany
Cardiac centers in Munich and Hamburg report 40% reductions in ICU utilization from catheter-based pulmonary procedures versus surgical cohorts. BfArM vigilance reporting under EU MDR post-market surveillance requirements tightens compliance obligations for valve manufacturers. The Charité campus in Berlin anchors high-volume transcatheter programs that negotiate direct manufacturer contracts bypassing group purchasing organizations.
Japan
Tokyo and Osaka university hospitals conduct first-in-human transcatheter pulmonary trials under PMDA Sakigake fast-track designation for breakthrough cardiovascular devices. METI industrial policy supports domestic valve frame manufacturing capabilities. Adult congenital programs in Kansai region drive outpatient procedural migration for valve-in-valve replacements.
India
Underpenetrated cardiac centers in Mumbai, Delhi, and Bangalore hospital networks present entry pathways as CDSCO regulatory harmonization with ISO 5840 standards advances. The central government's pharmaceutical regulator enforces cardiovascular implant durability testing protocols that align with international benchmarks. Pediatric cardiac surgery volume concentrates in southern metropolitan clusters where bioprosthetic demand outstrips transcatheter availability.
Australia
Tissue processing supply chains for bovine pericardium leaflets cluster in southeastern slaughterhouse regions serving global valve manufacturers. TGA approval pathways for novel transcatheter platforms run parallel to CE marking timelines. Sydney and Melbourne cardiac centers participate in multinational post-market surveillance studies under ISO governance frameworks.
Pulmonary Heart Valve Replacement Market Competitive Landscape
Concentration sits with diversified cardiovascular conglomerates that command structural heart portfolios spanning surgical, transcatheter, and electrophysiology platforms. The market structure divides into three tiers: integrated multinationals with captive tissue processing, mid-cap specialists focused on single delivery modalities, and regional distributors serving emerging cardiac programs. Strategic moves center on backward integration into bovine pericardium supply chains and hospital procurement consolidation through bundled structural heart contracts.
Among integrated cardiovascular conglomerates, Medtronic anchors the bioprosthetic segment through in-house tissue processing and valve frame manufacturing capabilities. Edwards Lifesciences occupies the transcatheter innovation tier with sustained commitments to catheter-delivered pulmonary platforms. Abbott Laboratories exemplifies the hybrid-procedure archetype, leveraging electrophysiology cross-selling into cardiac centers performing combined arrhythmia-valve interventions.
| Leading Market Players |
|---|
| Medtronic |
| Edwards Lifesciences |
| Abbott Laboratories |
| Boston Scientific |
| CryoLife |
| LivaNova |
| Terumo Corporation |
| Artivion |
| JenaValve Technology |
| Others |
Value Network & Pricing Analysis
Scale economies in bovine pericardium tissue processing anchor cost floors across the pulmonary valve replacement market, concentrating supply leverage among manufacturers with captive slaughterhouse relationships in Argentina and Australia while compressing margins for mid-tier competitors lacking backward integration into raw material sourcing.
Pricing Analysis
FDA premarket approval pathways and EU MDR CE marking tiers dictate the pricing structure for pulmonary valve replacement devices. Premium-mid-economy pricing differentiation separates transcatheter platforms with enhanced durability testing from standard bioprosthetic alternatives. Cost compression in the standard tier is intensifying because hospital procurement committees in U.S. integrated delivery networks demand outcome guarantees bundled with training support. Pediatric congenital heart programs exhibit the lowest price sensitivity due to clinical outcome prioritization, while general acute-care hospitals in Medicare bundled payment systems drive the hardest procurement negotiations.
Supply Chain Analysis
Slaughterhouse concentration in Argentina's Pampas region and Australia's southeastern corridors creates a chokepoint for bovine pericardium leaflet supply that underwrites global bioprosthetic valve manufacturing. Nitinol frame fabrication draws from specialized metallurgical facilities in Germany and the United States, while polymeric leaflet materials hinge on pharmaceutical-grade polymer suppliers in Japan and Switzerland. Single-source vulnerability in tissue processing exposes manufacturers to livestock disease outbreaks and export restriction risks. Distribution runs through direct manufacturer contracts with cardiac centers and group purchasing organization channels for general hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in the pulmonary heart valve replacement market as U.S. integrated delivery networks and German hospital procurement alliances consolidate vendor relationships, forcing manufacturers to bundle training, outcome guarantees, and multi-product contracts to defend shelf position.
For Market Incumbents: Consolidate backward integration into bovine pericardium tissue processing to secure raw material cost control against Argentine and Australian supply volatility. Deepen hospital system partnerships in Texas and Florida by embedding biomedical engineers within catheterization laboratory teams to raise switching costs. Defend against transcatheter durability limitations by accelerating polymeric material R&D investment ahead of ISO 5840 certification cycles. For New Entrants and Emerging Players: Anchor in underpenetrated Indian cardiac centers in Mumbai and Bangalore where CDSCO regulatory harmonization with ISO 5840 standards creates first-mover pathways before incumbent bundled contracts solidify. Target pediatric congenital applications with growth-accommodating frame designs where established players maintain surgical focus. Pursue electrophysiology cross-selling partnerships to access hybrid procedure volumes in German university hospitals. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors transcatheter platform specialists with differentiated catheter delivery systems over legacy surgical valve manufacturers facing procedural volume compression. Long-term viability over the next decade rests on regulatory navigation capabilities across FDA, EU MDR, and Japan PMDA pathways rather than manufacturing scale alone. Watch for inflection signals in reimbursement parity decisions by U.S. Medicare and German DRG authorities that would accelerate catheter-based volume migration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Streamlined conformity assessment accelerates German cardiac center market access for novel transcatheter platforms. |
| Hospital System Partnership | Direct contracts with Cleveland Clinic and Texas Medical Center bypass GPO intermediaries and extract outcome commitments. |
| Backward Integration into Tissue Processing | Captive bovine pericardium supply chains in Argentina insulate against raw material cost volatility and quality inconsistency. |
| Software Companion Development | Real-time imaging integration for transcatheter deployment reduces procedural learning curves and expands treatable anatomies. |
| Reimbursement Strategy | Medicare bundled payment alignment in Florida and California accelerates catheter-based adoption through length-of-stay incentives. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cardiac surgeons, interventional cardiologists, hospital purchasing committee members, and biomedical engineers at high-volume centers across the United States, Germany, and Japan; and secondary validation through FDA PMA filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up device shipment modeling and top-down cardiac procedure volume estimates were triangulated to constrain forecast variance.
Across the analysis window, segmentation modeling incorporated product type, delivery mode, end-user facility tier, and application severity to capture reimbursement-driven demand divergence. CAGRs were derived from procedure volume elasticity to pricing shifts and technology substitution curves observed in catheter-based versus surgical cohorts. Forecast inputs included EU MDR certification cycle timelines, pediatric congenital program capacity expansion plans, and ISO 5840 durability testing protocol evolution.
Decision-makers should treat outputs as directional under assumptions of stable regulatory harmonization and reimbursement parity advancement; material deviation in FDA review timelines or EU MDR vigilance enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as bovine pericardium supply chain disruptions and transcatheter durability data maturity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electrosurgical Generators Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Lactate Meter Market
Medical Devices
Cranial Orthoses Market