
 Fluoroscopy and Mobile C-Arms Market | 2026-2036
Fluoroscopy and Mobile C-Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoroscopy and Mobile C-Arms Market Analysis
Aftermarket service revenue is tilting toward flat-panel detector retrofits and extended warranty contracts. Siemens Healthineers leverages its installed base across European university hospitals to sustain recurring service income. GE Healthcare anchors its North American position through proprietary digital imaging pipelines that lock in upgrade cycles.
Fluoroscopy and mobile C-arms are real-time X-ray imaging systems that use continuous radiation emission to produce dynamic anatomical visualization, typically operating at 30-110 kV tube voltage for surgical guidance and diagnostic intervention. Mobile C-arms incorporate motorized positioning with isocentric C-shaped gantry geometry to enable multi-planar intraoperative imaging without patient repositioning. Flat panel detector technology now leads the technology dimension by displacing legacy image intensifier architectures due to superior dose efficiency and digital integration. Orthopedic applications within the application segment attract concentrated capital deployment as ambulatory surgical centers expand same-day joint procedure volumes.
The FDA governs device clearance through 510(k) and PMA pathways that mandate clinical validation of radiation dose profiles, while the EU Medical Device Regulation imposes stricter post-market surveillance and clinical evidence requirements for fluoroscopy systems sold in Europe. IEC 60601-2-54 establishes international safety and performance benchmarks for radiographic and fluoroscopic equipment, directly influencing design specifications across manufacturers. Stakeholders must monitor how AI-enabled image enhancement algorithms trigger new regulatory classification debates before committing R&D budgets.
Market Dynamics
Flat-panel detector retrofits are compressing replacement cycles across aging installed bases, forcing OEMs to pivot from equipment sales toward annuity-style service contracts and upgrade pathways.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter post-market surveillance requirements accelerate hospital procurement of digitally integrated systems that streamline compliance documentation.
- Ambulatory surgical centers:Same-day joint procedure expansion in the United States drives capital deployment toward compact mobile C-arm configurations.
- Japan's aging surgical infrastructure:Replacement demand concentrates in tertiary hospitals where legacy image intensifiers exceed two-decade service lifespans.
Market Restraints
- Xenon gas supply volatility:Image intensifier manufacturing depends on concentrated Russian and Ukrainian noble gas extraction, exposing legacy system producers to input cost spikes.
- FDA 510(k) backlog:Digital detector upgrade clearances face extended review timelines, delaying revenue recognition for retrofit programs.
- Ultrasound-guided navigation:Radiation-free alternatives for orthopedic trauma procedures capture share in pediatric and obstetric applications.
Strategic Opportunities
- India's PLI scheme:Domestic manufacturing incentives for medical electronics attract component assembly investment to serve South Asian price-sensitive demand.
- AI-enabled dose modulation:Machine learning algorithms for real-time image enhancement create regulatory classification debates that favor first-movers with clinical validation.
- Extended warranty unbundling:Third-party service providers penetrate German university hospital networks through detector calibration specialization.
Industry Challenges
- Clinical engineering talent scarcity:Flat-panel detector calibration requires hybrid skill sets spanning radiophysics and digital signal processing that training programs undersupply.
- Legacy DICOM integration:PACS connectivity standards fragment across hospital IT architectures, complicating vendor-neutral archive deployment.
- IEC 60601-2-54 compliance:Electromagnetic compatibility testing for motorized C-arm positioning systems extends certification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoroscopy and Mobile C-Arms Market |
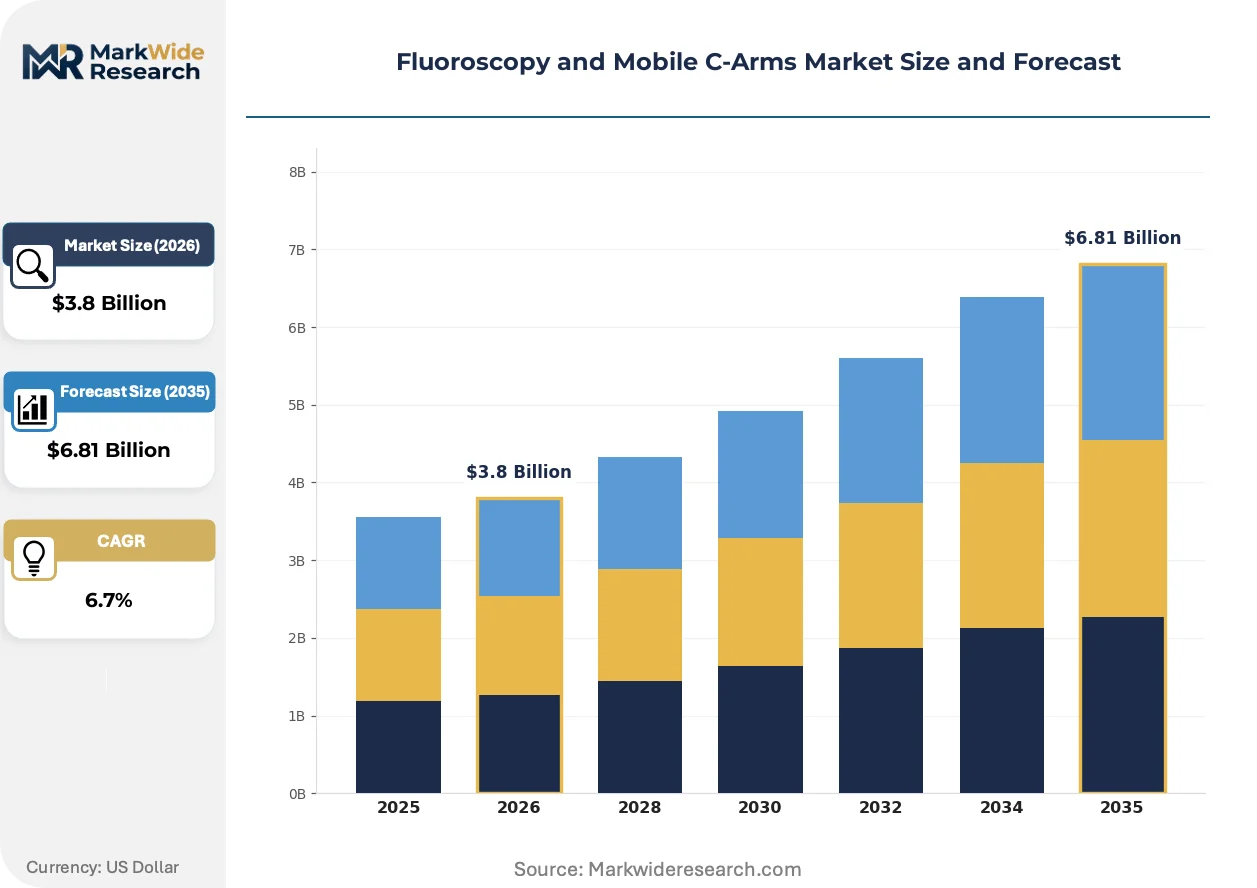
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed C-Arms, Mobile C-Arms, Mini C-Arms, Hybrid C-Arms End User: Hospitals, Surgical Centers, Diagnostic Imaging Centers, Research Institutions Technology: Digital Fluoroscopy, Analog Fluoroscopy, Flat Panel Detector, Image Intensifier Application: Cardiology, Orthopedics, Gastroenterology, Urology |
| Companies Covered | Ziehm Imaging GmbH, Canon Medical Systems Corporation, GE Healthcare, OrthoScan, Inc., Hologic, Inc., Siemens Healthineers AG, Shimadzu Corporation, Hitachi, Ltd., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoroscopy and Mobile C-Arms Market Emerging Trajectories
Software-defined imaging architectures are decoupling hardware refresh cycles from capability upgrades, enabling subscription-based feature activation that restructures capital deployment patterns.
CMOS flat-panel detectors are collapsing the cost-performance frontier for low-dose fluoroscopy. Ambulatory surgical centers in the United States adopt these sensors at three-year replacement cadences. The technology is collapsing price premiums that previously separated premium-tier hospitals from mid-market buyers.
The EU AI Act introduces risk-classification requirements for machine learning algorithms embedded in diagnostic imaging workflows. Manufacturers must submit clinical validation dossiers for dose-optimization software. European university hospitals delay procurement decisions until regulatory clarity emerges on algorithmic transparency mandates.
Hospital capital committees now unbundle imaging hardware from service contracts, soliciting competitive bids for detector calibration and tube replacement. Independent service organizations capture 23-31% of German maintenance spend. This pattern concentrates in metropolitan clusters where clinical engineering labor pools enable third-party credentialing.
Fluoroscopy and Mobile C-Arms Market Segmentation
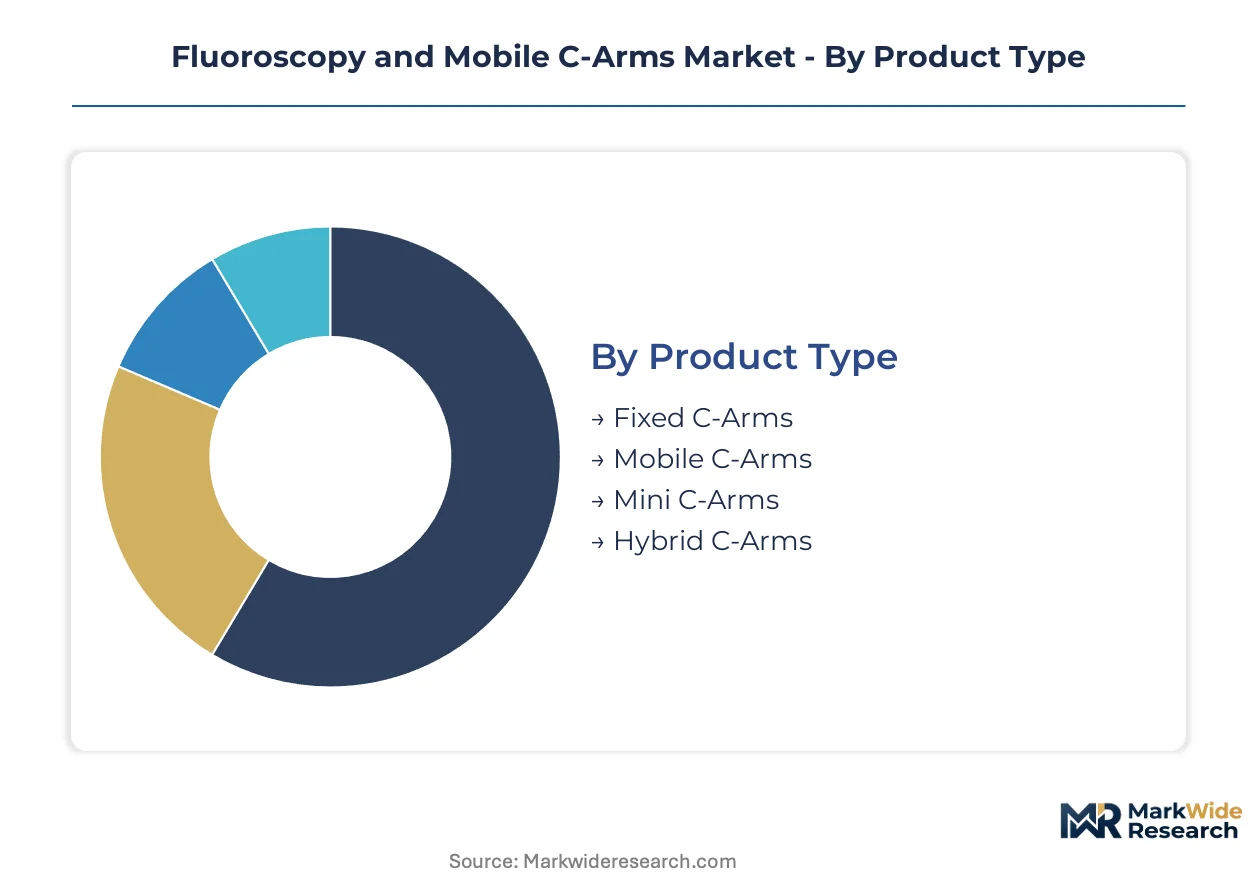
Segmentation in the fluoroscopy and mobile C-arms market reveals divergent procurement patterns across customer types and technology tiers. Hospital capital committees weight dose efficiency against integration costs, while ambulatory settings prioritize footprint and mobility specifications.
Product Type:
Cost tier differentiation separates premium fixed installations from portable configurations that ambulatory surgical centers favor for same-day procedures.
- Fixed C-Arms:Permanent ceiling-mounted or floor-mounted installations deliver maximum tube power and multi-axis positioning for complex cardiac interventions. Tertiary hospitals in Germany and Japan anchor demand for these systems as replacement cycles accelerate for two-decade-old image intensifier basins.
- Mobile C-Arms:Motorized C-shaped gantries with isocentric geometry enable intraoperative imaging without patient repositioning. United States ambulatory surgical centers drive procurement volume as same-day joint procedure expansion compresses capital recovery timelines.
- Mini C-Arms:Compact footprint units target extremity imaging with reduced radiation output. Orthopedic clinics in metropolitan clusters adopt these for hand and foot procedures.
- Hybrid C-Arms:Dual-modality configurations combine fluoroscopy with CT or angiography capabilities. European university hospitals evaluate these for interventional suites requiring multi-protocol flexibility.
Fixed C-arms command the established base. The steepest expansion runs through mobile C-arms.
End User:
Customer type determines procurement authority structure and service contract bundling preferences.
- Hospitals:Integrated delivery networks negotiate enterprise-wide fleet standardization. United States health systems leverage scale to extract extended warranty concessions and digital detector upgrade commitments.
- Surgical Centers:Physician-owned facilities prioritize three-year depreciation cycles and compact mobile configurations. These buyers unbundle service contracts and source detector calibration from independent service organizations.
- Diagnostic Imaging Centers:Outpatient facilities balance throughput against reimbursement compression. Volume concentration in cardiology and orthopedics drives technology selection.
- Research Institutions:Academic medical centers demand algorithm development access and dose-modulation research partnerships. Preclinical imaging protocols require specialized detector calibration.
Hospitals anchor procurement volume. Surgical centers are gaining share fastest as site-of-care migration accelerates.
Technology:
Technology maturity stratifies between legacy architectures and digital platforms that IEC 60601-2-54 compliance favors.
- Digital Fluoroscopy:Pulsed radiation emission with real-time image processing enables dose reduction protocols. FDA 510(k) clearances for these systems streamline hospital compliance documentation.
- Flat Panel Detector:Solid-state CMOS and amorphous silicon sensors displace vacuum-tube image intensifiers. Superior detective quantum efficiency and direct digital output drive replacement demand in Japan's aging installed base.
- Analog Fluoroscopy:Continuous radiation emission with analog signal chains persists in price-sensitive markets. India's PLI scheme for medical electronics attracts component assembly investment to serve residual demand.
- Image Intensifier:Vacuum-tube technology with photocathode and electron optics faces xenon gas supply volatility. Russian and Ukrainian noble gas extraction concentration exposes legacy system producers to input cost spikes.
Image intensifiers command the installed base. Flat panel detectors are climbing the fastest as dose efficiency mandates tighten.
Application:
Procedure volume and reimbursement rates concentrate capital deployment toward high-throughput specialties.
- Orthopedics:Trauma, spine, and joint replacement procedures generate the highest mobile C-arm utilization rates. Ambulatory surgical centers in the United States deploy compact configurations for arthroscopy and fracture fixation.
- Cardiology:Percutaneous coronary intervention and electrophysiology demand premium fixed systems with biplane capability. European university hospitals anchor demand for hybrid suite configurations.
- Gastroenterology:Endoscopic retrograde cholangiopancreatography and interventional procedures require specialized detector geometries. Procedure volume concentrates in tertiary referral centers.
- Urology:Percutaneous nephrolithotomy and interventional procedures utilize C-arm guidance. Lower reimbursement rates relative to cardiology constrain capital allocation.
Orthopedics commands procedure volume. Cardiology sustains the highest equipment price points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement environments. United States ambulatory surgical centers demand compact mobile configurations at compressed depreciation cycles. German university hospitals absorb premium fixed-system pricing for hybrid suite capabilities.
United States
Ambulatory surgical centers drive mobile C-arm volume through same-day joint procedure expansion. FDA 510(k) clearance pathways for digital flat-panel detector upgrades accelerate technology transitions. Procurement concentrates in metropolitan clusters where independent service organizations capture detector calibration contracts.
Germany
European university hospitals anchor demand for premium fixed C-arms with biplane cardiac capability. EU Medical Device Regulation imposes stricter post-market surveillance requirements that favor digitally integrated compliance documentation. Siemens Healthineers leverages its installed base across tertiary hospitals to sustain recurring service revenue.
Japan
Aging surgical infrastructure in tertiary hospitals generates replacement demand as legacy image intensifiers exceed two-decade service lifespans. METI industrial standards influence domestic procurement specifications for dose efficiency. Tokyo-Osaka hospital networks concentrate flat-panel detector retrofit programs.
India
Price-sensitive hospital procurement attracts component assembly investment under the PLI scheme for medical electronics. CDSCO device registration requirements shape import substitution strategies for domestic manufacturers. Maharashtra and Karnataka host emerging detector calibration service clusters.
United Kingdom
NHS capital committees unbundle imaging hardware from service contracts to solicit competitive maintenance bids. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR implementation timelines. London-Southeast hospital networks evaluate AI-enabled dose modulation algorithms.
Fluoroscopy and Mobile C-Arms Market Vendor Landscape
Integrated imaging conglomerates and specialized surgical equipment manufacturers split the market along technology integration depth. Consolidation concentrates among European and Japanese conglomerates with captive detector supply chains. Three archetypes dominate: full-stack imaging platforms, surgical navigation specialists, and component-assembly regional players. Competitive moves center on flat-panel detector retrofit program expansion and AI-enabled image enhancement algorithm development.
Within the full-stack imaging tier, Siemens Healthineers AG and GE Healthcare exemplify integrated platform strategies. Ziehm Imaging GmbH occupies a specialist position in mobile C-arm configurations. Canon Medical Systems Corporation and Koninklijke Philips N.V. sit within the diversified medical technology conglomerate archetype. These named entities anchor market structure analysis without constraining competitive dynamics to individual corporate actions.
| Leading Market Players |
|---|
| Ziehm Imaging GmbH |
| Canon Medical Systems Corporation |
| GE Healthcare |
| OrthoScan, Inc. |
| Hologic, Inc. |
| Siemens Healthineers AG |
| Shimadzu Corporation |
| Hitachi, Ltd. |
| Koninklijke Philips N.V. |
| Others |
Supply Flow & Price Mechanics
Xenon gas extraction concentration in Russia and Ukraine feeds directly into margin pools for legacy image intensifier maintenance, while flat-panel detector assembly in South Korea and Japan commands premium pricing for digital upgrade pathways. Procurement committees now unbundle hardware from service contracts, redistributing value toward detector calibration specialists and extended warranty providers.
Pricing Analysis
Aftermarket service revenue tiers—spanning flat-panel detector retrofits, tube replacements, and extended calibration contracts—now drive lifetime value beyond initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates biplane cardiac installations from compact mobile configurations and mini C-arm extremity units. Cost compression in economy-tier analog systems intensifies because India's PLI scheme attracts component assembly investment for price-sensitive South Asian demand. Ambulatory surgical centers in the United States exhibit the highest price sensitivity, while German university hospitals absorb premium fixed-system pricing for hybrid suite capabilities.
Supply Chain Analysis
Export-control restrictions on CMOS sensor fabrication equipment limit technology transfer to certain fabrication facilities, constraining supply expansion for advanced flat-panel detectors. Manufacturing concentrates in Japan, South Korea, and Germany for precision detector substrates, while xenon gas processing draws from Russian and Ukrainian extraction infrastructure. Amorphous silicon deposition equipment, scintillator crystals, and high-voltage X-ray tubes constitute critical component dependencies. Single-source vulnerability in noble gas supply chains exposes legacy image intensifier producers to input disruption. Distribution runs through OEM direct sales for premium fixed systems and independent service organizations for detector calibration in metropolitan hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasound-guided navigation systems for orthopedic trauma procedures threaten C-arm utilization in pediatric and obstetric settings, forcing incumbents to defend installed bases through upgrade retention and service contract lock-in.
For Market Incumbents: Pre-empt detector retrofit demand by unbundling flat-panel upgrade pathways from full system replacement, capturing annuity revenue from aging image intensifier bases before third-party calibrators penetrate hospital networks. Anchor procurement relationships through proprietary digital imaging pipelines that complicate vendor-neutral archive migration. Vertical integration into CMOS sensor supply buffers against export-control tightening on fabrication equipment.
For New Entrants and Emerging Players: India's price-sensitive hospital procurement underpenetration by full-stack imaging conglomerates creates white-space for component-assembly specialists leveraging PLI scheme incentives. Target Maharashtra and Karnataka detector calibration service clusters where clinical engineering labor pools enable third-party credentialing. Pursue unbundled service contract bids for German university hospital networks where independent organizations already capture maintenance spend.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed surgical navigation specialists possessing AI-enabled image enhancement algorithms but lacking FDA 510(k) clearance velocity. Long-term viability hinges on regulatory first-mover advantage in dose-modulation software classification debates. Monitor FDA algorithmic transparency guidance emergence as inflection indicator for European university hospital procurement resumption.
| Strategic Initiative | Industry Significance |
|---|---|
| Flat-Panel Detector Retrofit Program Expansion | Captures recurring revenue from Japan's aging image intensifier base exceeding two-decade service lifespans. |
| AI-Enabled Dose Modulation Algorithm Development | Triggers regulatory classification debates favoring first-movers with clinical validation dossiers under EU AI Act. |
| Extended Warranty Unbundling and Third-Party Calibration | Penetrates German hospital networks where independent service organizations capture detector maintenance contracts. |
| PLI Scheme Component Assembly Investment | Positions domestic manufacturing to serve South Asian price-sensitive demand under India's medical electronics incentives. |
| Software-Defined Imaging Architecture Deployment | Enables subscription-based feature activation that restructures capital deployment patterns across ambulatory surgical centers. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and fluoroscopy equipment service technicians and refined through secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and IEC 60601-2-54 compliance certification records. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure analysis were triangulated to reconcile volume estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeling across product type, technology tier, end-user facility class, application specialty, and regional regulatory cluster. CAGRs were derived from installed base replacement cycle analysis and same-day procedure volume trajectories. Forecast inputs incorporated ambulatory surgical center expansion rates, xenon gas supply volatility scenarios, and AI algorithm regulatory classification timelines.
Practitioners should monitor FDA 510(k) backlog resolution, EU AI Act implementation clarity, and xenon gas supply disruption signals for early indicators of forecast deviation. Material shifts in export-control restrictions on CMOS fabrication equipment or abrupt regulatory reclassification of machine learning diagnostic algorithms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Brain PET-MRI Systems Market