
 South America Single-Use Medical Device Reprocessing Market | 2026-2036
South America Single-Use Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
South America Single-Use Medical Device Reprocessing Market Analytics
The South America single-use medical device reprocessing market is repositioning around a widening split between premium validated reprocessing services and commodity-tier sterilization offerings. Hygia leverages its Brazilian manufacturing footprint to dominate southeastern hospital networks. Medline Industries anchors regional distribution through direct procurement contracts with large public health systems. Johnson & Johnson competes on technology leadership in automated cleaning validation systems.
Single-use medical device reprocessing encompasses the collection, cleaning, functional testing, sterilization, and regulatory relabeling of disposable instruments originally manufactured for one-time use, employing gamma irradiation or ethylene oxide cycles validated to ISO 11135 and ISO 11137 sterility assurance levels. The practice reduces per-procedure costs for healthcare providers while maintaining clinical performance equivalent to virgin devices. Surgical instruments command the largest volume share within product type segments, though catheters generate disproportionate margin pools due to polymer complexity and specialized revalidation requirements. Off-site processing grows fastest among delivery modes as regional centralized sterilization hubs achieve economies of scale unavailable to individual hospitals.
ANVISA governs device reprocessing through Resolução da Diretoria Colegiada norms requiring biocompatibility and sterility documentation for relabeled products, while Brazil's Agência Nacional de Vigilância Sanitária coordinates with state health secretariats on facility inspections. These frameworks elevate compliance costs for smaller reprocessors while creating barrier-to-entry advantages for validated operators. Stakeholders must monitor pending regulatory harmonization between Mercosur members, as divergent national standards currently fragment cross-border service expansion.
Market Dynamics
ANVISA's sterility assurance mandates are compressing the reprocessor landscape toward validated operators with capital-intensive gamma and ethylene oxide infrastructure, marginalizing smaller facilities unable to absorb compliance documentation burdens.
Growth Catalysts
- Cost-containment mandates:Brazilian state health secretariats are expanding centralized sterilization programs in public hospital networks to reduce per-procedure instrument expenditure.
- ISO 11135 validation protocols:Standardized ethylene oxide sterilization documentation is enabling third-party reprocessors to demonstrate equivalence to virgin device performance.
- São Paulo hospital concentration:Southeastern Brazil's dense network of tertiary care facilities generates economies of scale for off-site processing hubs serving multiple institutions.
Market Restraints
- Polymer degradation limits:Catheter reprocessing faces structural yield losses due to thermoplastic elastomer fatigue after repeated gamma irradiation cycles.
- Cross-border regulatory fragmentation:Divergent Mercosur national standards block Argentine and Paraguayan reprocessors from serving Brazilian hospital clients without separate ANVISA facility certifications.
- Single-use virgin device pricing:Chinese-manufactured disposable surgical instruments are compressing reprocessor margin pools through aggressive import pricing in price-sensitive public procurement.
Strategic Opportunities
- Colombian market entry:INVIMA regulatory harmonization talks with ANVISA are creating pathways for validated Brazilian reprocessors to access Andean hospital networks.
- Automated cleaning validation:Machine vision systems integrated with aqueous washing lines are reducing manual inspection labor and expanding reprocessable device categories.
- Direct-to-hospital logistics:Cold-chain distribution partnerships with regional medical couriers are enabling just-in-time sterilized instrument delivery outside traditional group purchasing organization channels.
Industry Challenges
- Sterility assurance specialist shortage:ANVISA-certified quality managers command premium compensation, constraining reprocessor expansion timelines.
- Legacy hospital inventory systems:Manual tracking of reprocessed device lot numbers creates traceability gaps during adverse event investigations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Single-Use Medical Device Reprocessing Market |
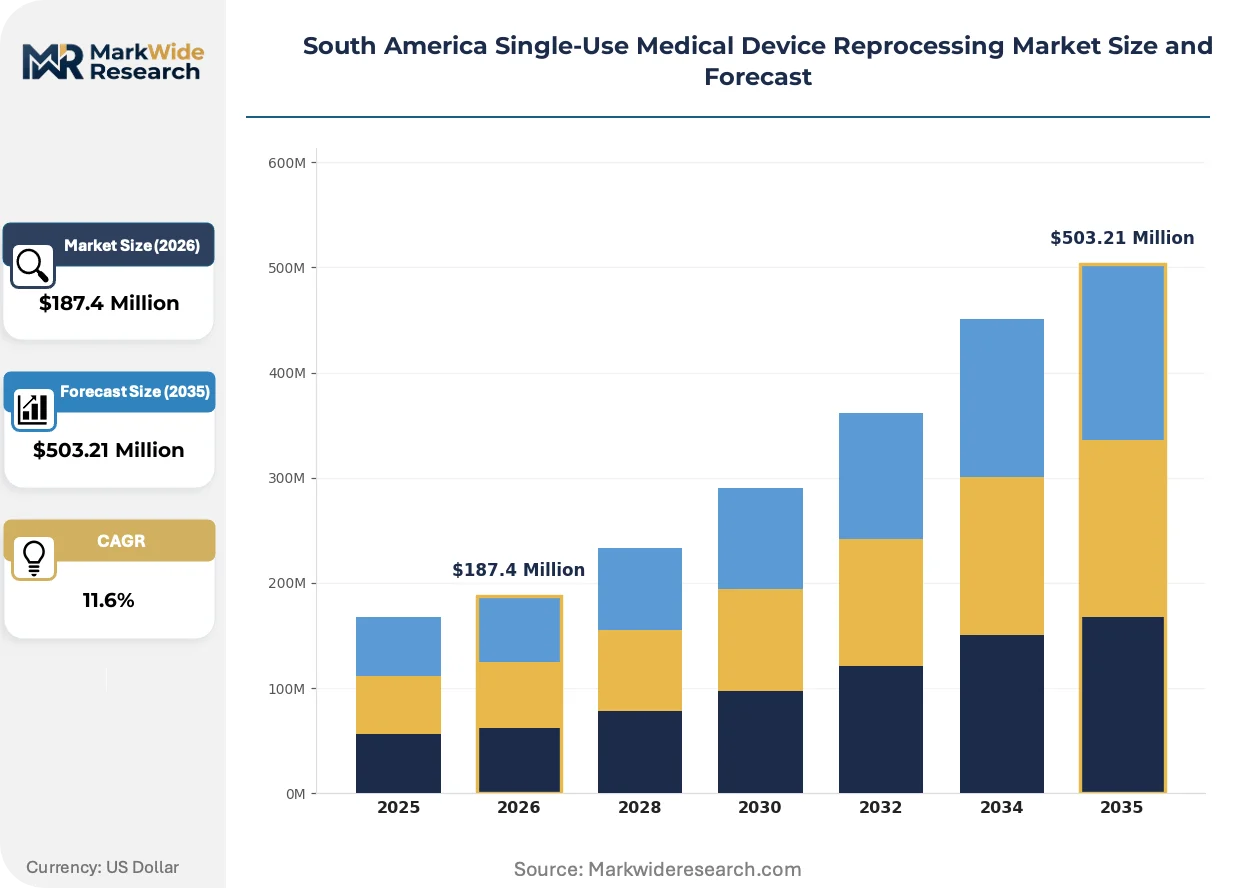
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Tools, Catheters, Endoscopes Application: Hospital Settings, Ambulatory Surgical Centers, Diagnostics, Home Healthcare End User: Healthcare Providers, Medical Facilities, Laboratories, Clinics Delivery Mode: On-site Processing, Off-site Processing, Centralized Sterilization, Automated Systems |
| Companies Covered | Hygia, Medline Industries, Johnson & Johnson, Stryker Corporation, Arjo, SureTek Medical, Vanguard AG, NEScientific, ReNu Medical, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Single-Use Medical Device Reprocessing Market Evolving Landscape
Reprocessing technology is pivoting from labor-intensive manual cleaning toward integrated automation platforms that compress cycle times while expanding the categories of devices eligible for safe reuse.
Automated aqueous cleaning systems with ultrasonic cavitation and detergent dosing controls are automating the removal of biological soil from laparoscopic instrument lumens. São Paulo's largest private hospital networks are deploying these platforms in centralized sterilization departments to handle rising surgical volumes. The technology is automating workforce requirements out of the reprocessing workflow while extending device functional life through standardized cleaning parameters.
ANVISA's updated Resolução da Diretoria Colegiada norms are mandating biocompatibility testing documentation for all relabeled single-use devices regardless of original manufacturer. Third-party reprocessors must now submit cytotoxicity and sensitization data equivalent to virgin device submissions. Catheter reprocessors face the steepest compliance burden due to polymer contact duration classifications, driving consolidation toward laboratories with in-house ISO 10993 testing capability.
Hospital procurement departments are unbundling sterilization services from traditional medical device supply contracts and sourcing reprocessing through standalone service agreements. Large public health systems in Minas Gerais and Rio de Janeiro are piloting performance-based contracts where reprocessor fees tie to validated sterility assurance levels rather than per-device throughput. This restructuring concentrates purchasing power with procurement officers trained in quality systems auditing rather than traditional supply chain generalists.
South America Single-Use Medical Device Reprocessing Market Segmentation
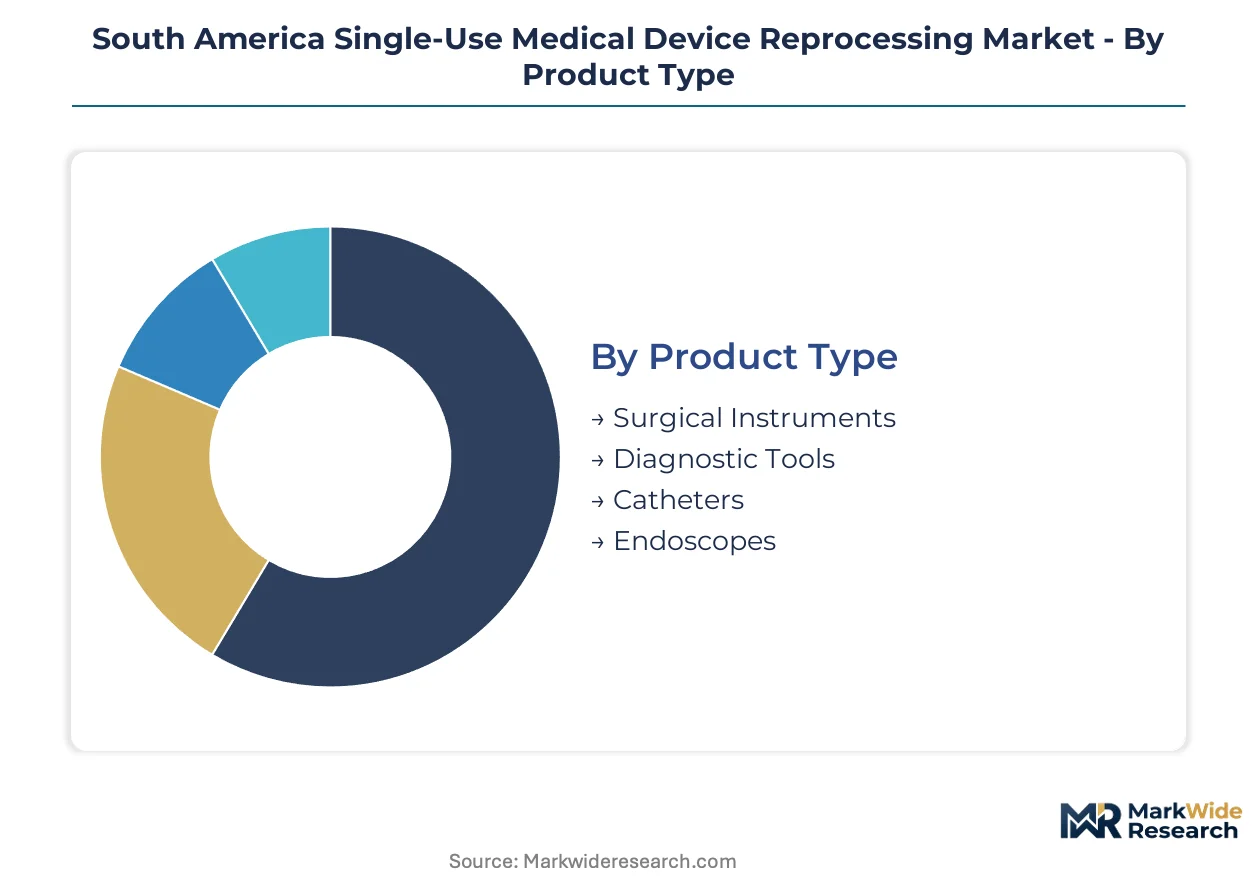
Device reprocessing economics diverge sharply across product categories and delivery configurations. Understanding these splits reveals where capital deployment concentrates and where margin compression threatens.
Product Type:
Surgical instruments dominate reprocessing volume while catheters command premium pricing tiers due to polymer complexity and regulatory burden.
- Surgical Instruments:Scalpels, forceps, and clamps constructed from stainless steel and titanium alloys withstand repeated gamma sterilization cycles with minimal structural degradation. São Paulo's tertiary hospital networks drive regional demand for validated instrument reprocessing, pressured by state health secretariat cost-containment procurement mandates.
- Catheters:Thermoplastic elastomer and polyurethane constructions require specialized biocompatibility revalidation under ANVISA's updated Resolução da Diretoria Colegiada norms. Southeastern Brazil's cardiovascular centers generate concentrated demand despite polymer fatigue constraints that limit reprocessing cycles.
- Diagnostic Tools:Specula, dilators, and biopsy instruments with simpler geometries face margin pressure from Chinese-manufactured virgin alternatives in public procurement channels.
- Endoscopes:Flexible fiber-optic and video systems demand aqueous cleaning automation with luminal flushing validation, restricting reprocessing to capital-intensive centralized facilities.
Today's leader: Surgical Instruments. Tomorrow's challenger: Catheters.
Application:
Facility scale and surgical throughput determine whether on-site investment or third-party service contracts deliver superior unit economics.
- Hospital Settings:Tertiary care institutions with daily surgical volumes exceeding fifty procedures justify dedicated sterilization departments. Minas Gerais public health systems are unbundling reprocessing from device supply contracts and sourcing through standalone performance-based service agreements.
- Ambulatory Surgical Centers:Lower throughput facilities rely on off-site processing hubs to avoid capital expenditure on gamma irradiation infrastructure. Rio de Janeiro's outpatient surgery networks are consolidating sterilization procurement across multiple ASCs.
- Diagnostics:Imaging centers and pathology laboratories generate intermittent reprocessing demand for biopsy forceps and specimen collection instruments.
- Home Healthcare:Dialysis catheter and infusion set reprocessing faces distribution complexity and traceability requirements that limit commercial viability.
Hospital Settings anchor current revenue. Ambulatory Surgical Centers are climbing the fastest.
End User:
Purchasing authority sits with procurement officers trained in quality systems auditing rather than traditional supply chain generalists.
- Healthcare Providers:Physician-owned surgical practices and specialty clinics with direct sterilization contracts.
- Medical Facilities:Integrated hospital networks with centralized procurement functions spanning multiple campuses.
- Laboratories:Clinical and research facilities with specialized biocompatibility documentation requirements.
- Clinics:Primary care and specialty outpatient centers with sporadic reprocessing needs.
Medical Facilities concentrate purchasing power. Healthcare Providers are gaining procurement sophistication fastest.
Delivery Mode:
Capital intensity and regulatory compliance burden are concentrating viable operations toward centralized and automated configurations.
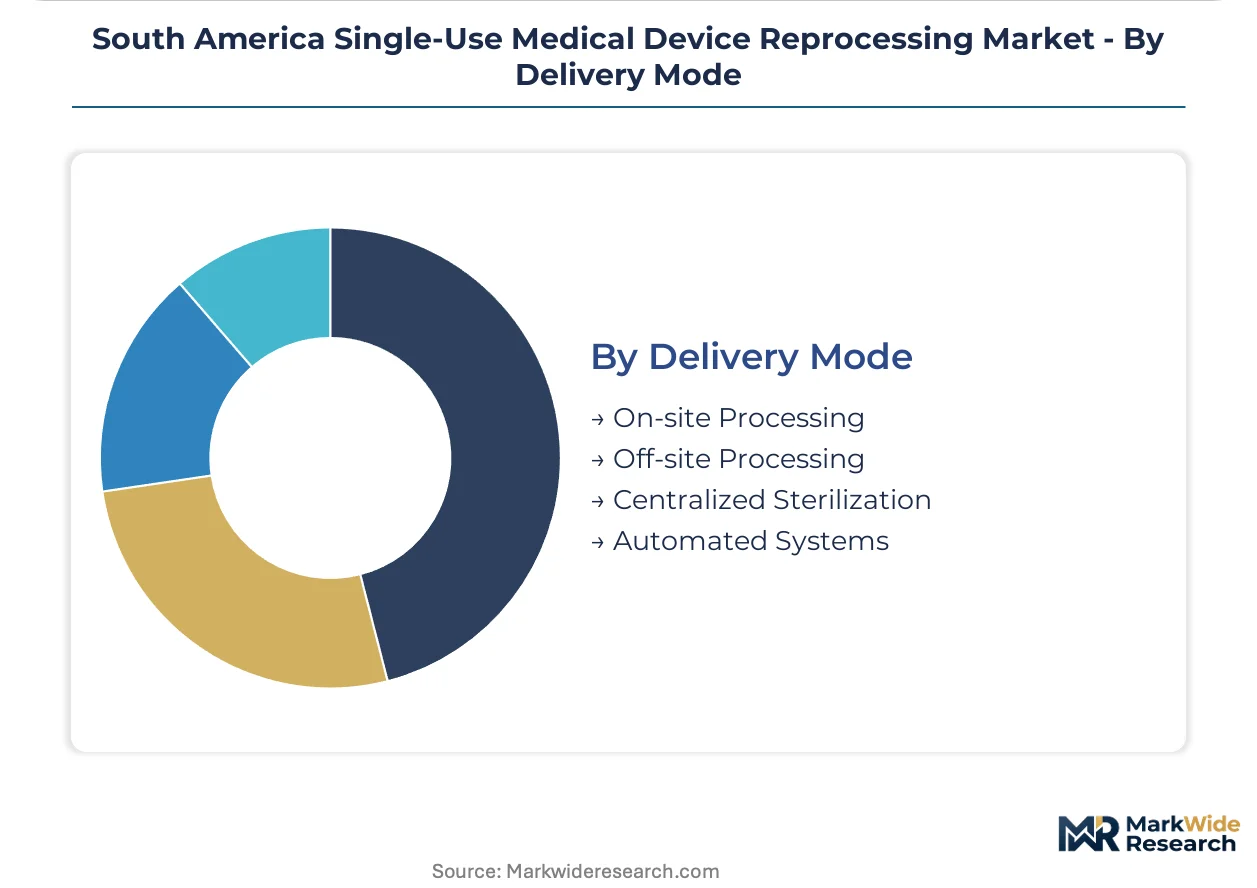
- Off-site Processing:Regional hubs serving multiple institutions achieve economies of scale unavailable to individual hospitals. Cold-chain distribution partnerships with Brazilian medical couriers are enabling just-in-time sterilized instrument delivery outside traditional group purchasing organization channels.
- Centralized Sterilization:Multi-hospital networks in southeastern Brazil are consolidating gamma and ethylene oxide infrastructure into dedicated facilities with ANVISA-certified quality management systems.
- On-site Processing:Individual hospital sterilization departments face rising compliance documentation burdens and specialist salary premiums.
- Automated Systems:Machine vision-integrated aqueous washing lines are reducing manual inspection labor and expanding reprocessable device categories.
Centralized Sterilization dominates investment flows. Automated Systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the largest reprocessing infrastructure base in South America, while Colombia and Chile are accelerating regulatory harmonization efforts that could unlock cross-border service expansion for validated operators.
Brazil
State health secretariats in Minas Gerais and Rio de Janeiro are unbundling sterilization services from device supply contracts and piloting performance-based procurement models. ANVISA's Resolução da Diretoria Colegiada norms mandate biocompatibility documentation that elevates compliance costs for smaller facilities. São Paulo's hospital networks anchor southeastern demand, with tertiary care institutions driving adoption of centralized gamma and ethylene oxide infrastructure.
Colombia
INVIMA regulatory harmonization talks with ANVISA are creating pathways for validated Brazilian reprocessors to access Andean hospital networks. The national pharmaceutical regulator is modernizing sterility assurance frameworks to align with ISO 11135 validation protocols. Bogotá's cardiovascular centers generate concentrated demand for catheter reprocessing despite polymer fatigue constraints that limit cycle counts.
Argentina
Public hospital networks in Buenos Aires province face fiscal pressure to reduce per-procedure instrument expenditure through third-party sterilization contracts. Divergent Mercosur national standards currently block Argentine reprocessors from serving Brazilian clients without separate ANVISA facility certifications. The metropolitan Buenos Aires cluster concentrates domestic demand for surgical instrument reprocessing services.
Chile
Private healthcare providers in Santiago are expanding centralized sterilization departments to handle rising surgical volumes from aging demographic profiles. The national pharmaceutical regulator maintains sterility assurance requirements that lag ANVISA's updated biocompatibility documentation mandates. Santiago's tertiary hospital networks drive regional adoption of automated aqueous cleaning systems with ultrasonic cavitation.
Peru
Lima's public health systems are exploring performance-based reprocessing contracts modeled on Brazilian procurement innovations. The country's national pharmaceutical regulator is evaluating harmonization with ANVISA frameworks to attract validated regional operators. Metropolitan Lima concentrates demand for diagnostic tool reprocessing despite margin pressure from Chinese-manufactured virgin alternatives.
South America Single-Use Medical Device Reprocessing Market Competitive Landscape
Top-tier vendors anchor validated gamma and ethylene oxide infrastructure, while smaller facilities face marginalization from ANVISA's compliance documentation burdens. The vendor base stratifies across capital-intensive centralized operators, regional distribution specialists, and technology-focused automation providers. Three archetypes dominate: manufacturing-integrated reprocessors with captive sterilization capacity, third-party service specialists with multi-hospital contracts, and equipment-technology providers licensing validation systems. Competitive moves concentrate on geographic expansion through regulatory harmonization and portfolio diversification into automated cleaning platforms.
Among Brazil-based operators, Hygia leverages its southeastern manufacturing footprint to dominate hospital network procurement. Medline Industries anchors regional distribution through direct contracts with large public health systems. Johnson & Johnson occupies a position exemplifying technology leadership in automated cleaning validation systems. These three represent the premium-tier vector where capital intensity and regulatory compliance create sustainable differentiation.
| Leading Market Players |
|---|
| Hygia |
| Medline Industries |
| Johnson & Johnson |
| Stryker Corporation |
| Arjo |
| SureTek Medical |
| Vanguard AG |
| NEScientific |
| ReNu Medical |
| Others |
Value Network & Pricing Analysis
ANVISA-certified quality manager scarcity in southeastern Brazil widens labor-cost spreads between premium validated operators and commodity-tier reprocessors, compressing mid-market pricing tiers toward polarized extremes.
Pricing Analysis
The bundled-vs-unbundled service split separates legacy device-supply contracts from standalone sterilization procurement. Hospital networks in Minas Gerais and Rio de Janeiro are piloting performance-based agreements where fees tie to validated sterility assurance levels rather than per-device throughput. Price differentiation hinges on ISO 11135 certification grade and after-sales documentation depth. Cost compression in public procurement channels intensifies as Chinese-manufactured virgin instruments undercut reprocessed alternatives. Ambulatory surgical centers exhibit highest price sensitivity; tertiary hospital networks with captive sterilization departments demonstrate lowest.
Supply Chain Analysis
Direct-to-hospital logistics partnerships with regional medical couriers handle just-in-time sterilized instrument delivery outside traditional group purchasing organization channels. Gamma irradiation and ethylene oxide sterilization equipment concentrates in Brazil, with emerging hub development in Colombia and Chile. Raw material flows draw from stainless steel surgical instrument foundries, thermoplastic elastomer catheter polymer suppliers, and aqueous cleaning detergent formulators. Single-source vulnerability in ANVISA-certified quality manager talent constrains reprocessor expansion timelines. Distribution runs through centralized sterilization hubs serving multi-institutional networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ANVISA's evolving Resolução da Diretoria Colegiada biocompatibility mandates continuously elevate compliance barriers and consolidate demand around validated operators.
For Market Incumbents: Extend automated cleaning validation capabilities to capture catheter reprocessing margin pools threatened by polymer fatigue constraints. Deepen backward integration into ISO 10993 testing laboratories to internalize compliance documentation burdens that marginalize smaller competitors. Anchor multi-hospital network contracts in southeastern Brazil before INVIMA-ANVISA harmonization opens Colombian market entry pathways. For New Entrants and Emerging Players: Machine vision-integrated aqueous washing systems offer a technology-first wedge into diagnostic tool reprocessing segments underserved by capital-intensive gamma infrastructure. Target ambulatory surgical center clusters in Rio de Janeiro consolidating procurement across multiple facilities. Pursue direct-to-hospital logistics partnerships as primary go-to-market angle, bypassing incumbent group purchasing organization channel control. For Investors and Strategic Acquirers: Hospital network procurement departments are the most active acquirer in this space, seeking captive sterilization capacity to unbundle from third-party service contracts. The five-to-ten year viability window favors validated operators with ANVISA-certified quality systems and gamma or ethylene oxide infrastructure. Acquisition target archetype: regional third-party reprocessors with multi-hospital contracts and underinvested automation platforms. Monitor INVIMA-ANVISA regulatory harmonization progress as inflection indicator for cross-border service expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cleaning Validation Investment | Machine vision systems reduce manual inspection labor while expanding reprocessable device categories for catheter segments. |
| ISO 10993 Testing Laboratory Acquisition | In-house biocompatibility documentation capability internalizes ANVISA compliance burdens and accelerates relabeling timelines. |
| Multi-Hospital Network Contract Expansion | Performance-based procurement pilots in Minas Gerais concentrate purchasing power with quality-systems-trained procurement officers. |
| Direct-to-Hospital Logistics Partnership | Cold-chain medical courier alliances enable just-in-time delivery outside incumbent group purchasing organization channels. |
| Cross-Border Regulatory Harmonization Positioning | INVIMA-ANVISA alignment creates first-mover pathways into Colombian Andean hospital networks before competitor facility certification. |
Research Methodology
Direct dialogue with hospital procurement officers, biomedical engineers, ANVISA regulatory consultants, third-party reprocessor operations directors, and group purchasing organization contract managers grounded qualitative insights. Secondary validation drew from ANVISA Resolução da Diretoria Colegiada filings, hospital procurement databases, GPO contract disclosures, ISO 11135 and ISO 11137 certification registries, and Brazilian state health secretariat sterilization program announcements. Bottom-up demand modeling across device categories triangulated against top-down macro healthcare expenditure trends.
Bottom-up volume projections aggregated surgical throughput data from tertiary hospital networks and ambulatory surgical center clusters across São Paulo, Rio de Janeiro, Minas Gerais, Bogotá, Santiago, and Buenos Aires metropolitan regions. Top-down validation calibrated against national healthcare expenditure trajectories and medical device procurement budget allocations. Segmentation dimensions spanned product type, application setting, delivery mode configuration, and end-user purchasing authority structure. CAGRs derived from regression analysis of historical reprocessing adoption rates against sterilization infrastructure investment cycles.
The model holds under sustained ANVISA enforcement of biocompatibility documentation requirements and stable hospital network consolidation patterns; deviation in Mercosur regulatory harmonization timelines or Chinese virgin device import pricing would shift reprocessor margin pool projections. Forecasts reflect base-case assumptions regarding sterilization specialist labor availability and gamma irradiation capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
UK Surgical Devices Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Global Dermatome Device Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
Oxygenator Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Ventilator Breathing Circuit Market