
 France Radiation Oncology Market | 2026-2036
France Radiation Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
France Radiation Oncology Market Insights
France's Medical Device Regulation transposition of EU MDR is consolidating the cost-of-entry calculus for radiation oncology equipment suppliers. Varian Medical Systems leverages its installed base of linear accelerators to sustain service revenue streams across French hospital networks. Elekta AB anchors proton therapy development through its European research partnerships. Siemens Healthineers AG differentiates via integrated imaging-radiation platforms that compete on workflow consolidation.
Radiation oncology encompasses the clinical discipline and technical systems directing ionizing radiation to destroy malignant cells while preserving surrounding healthy tissue, utilizing megavoltage photon beams typically generated by linear accelerators operating at 6–18 MV energies with multileaf collimator shaping for intensity-modulated delivery. The discipline serves curative, adjuvant, and palliative cancer treatment across breast, lung, prostate, and brain malignancies. Linear accelerators occupy the dominant capital expenditure tier among product categories, while proton therapy represents the fastest-growing delivery mode segment constrained by cyclotron infrastructure costs. Cancer treatment centers capture the highest patient throughput volume among end users, though research institutions command premium pricing for protocol development.
ANSM oversees medical device vigilance and market authorization for radiation equipment in France, while CE marking under EU MDR mandates updated clinical evidence and quality management system certifications that extend product registration timelines. France's national cancer plan frameworks shape reimbursement and capacity planning for radiotherapy service expansion. Stakeholders must monitor MDR transition completion timelines and proton therapy commissioning decisions by regional hospital agencies to anticipate capital allocation shifts.
Market Dynamics
France's radiation oncology sector is experiencing structural compression as EU MDR compliance timelines force equipment suppliers to consolidate clinical evidence portfolios while regional hospital agencies accelerate proton therapy commissioning decisions.
Growth Catalysts
- Île-de-France Capacity Expansion:Parisian academic hospital networks are commissioning advanced linear accelerator installations to address patient throughput bottlenecks in the country's densest cancer treatment corridor.
- EU MDR Clinical Evidence Requirements:Stricter post-market surveillance mandates are filtering out marginal equipment suppliers, concentrating procurement authority among validated vendors with robust quality management systems.
- Proton Therapy Infrastructure Commitments:Regional health agencies in Lyon and Toulouse are allocating capital to cyclotron-based treatment facilities, creating demand for specialized technical workforce training programs.
Market Restraints
- Cyclotron Capital Intensity:Proton therapy systems require facility investments exceeding conventional linear accelerator deployments by an order of magnitude, limiting commissioning to flagship academic centers.
- Isotope Supply Concentration:France's reliance on centralized radiopharmaceutical production creates vulnerability to reactor maintenance schedules at the Institut Laue-Langevin in Grenoble.
- MDR Transition Friction:Extended conformity assessment timelines under ANSM oversight are delaying product registration renewals for legacy linear accelerator models.
Strategic Opportunities
- AI-Integrated Treatment Planning:Machine learning algorithms for automated contouring and dose optimization are converging with existing linear accelerator fleets to compress planning workflow timelines.
- Occitanie Regional Undersupply:Peripheral regions outside Parisian hospital networks exhibit lower linear accelerator density per capita, creating whitespace for satellite treatment center development.
- France's National Cancer Plan:Government-mandated radiotherapy access targets are channeling reimbursement authority toward centers demonstrating measurable patient outcome improvements.
Industry Challenges
- Medical Physics Workforce Scarcity:Specialized training programs for dosimetrists and medical physicists are failing to match retirement rates in provincial hospital networks.
- Legacy System Integration Complexity:New linear accelerator installations must interface with decade-old record-and-verify systems, extending commissioning timelines and elevating cybersecurity exposure.
- CE Marking Documentation Burden:EU MDR technical file requirements are consuming engineering resources that previously supported product innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Radiation Oncology Market |
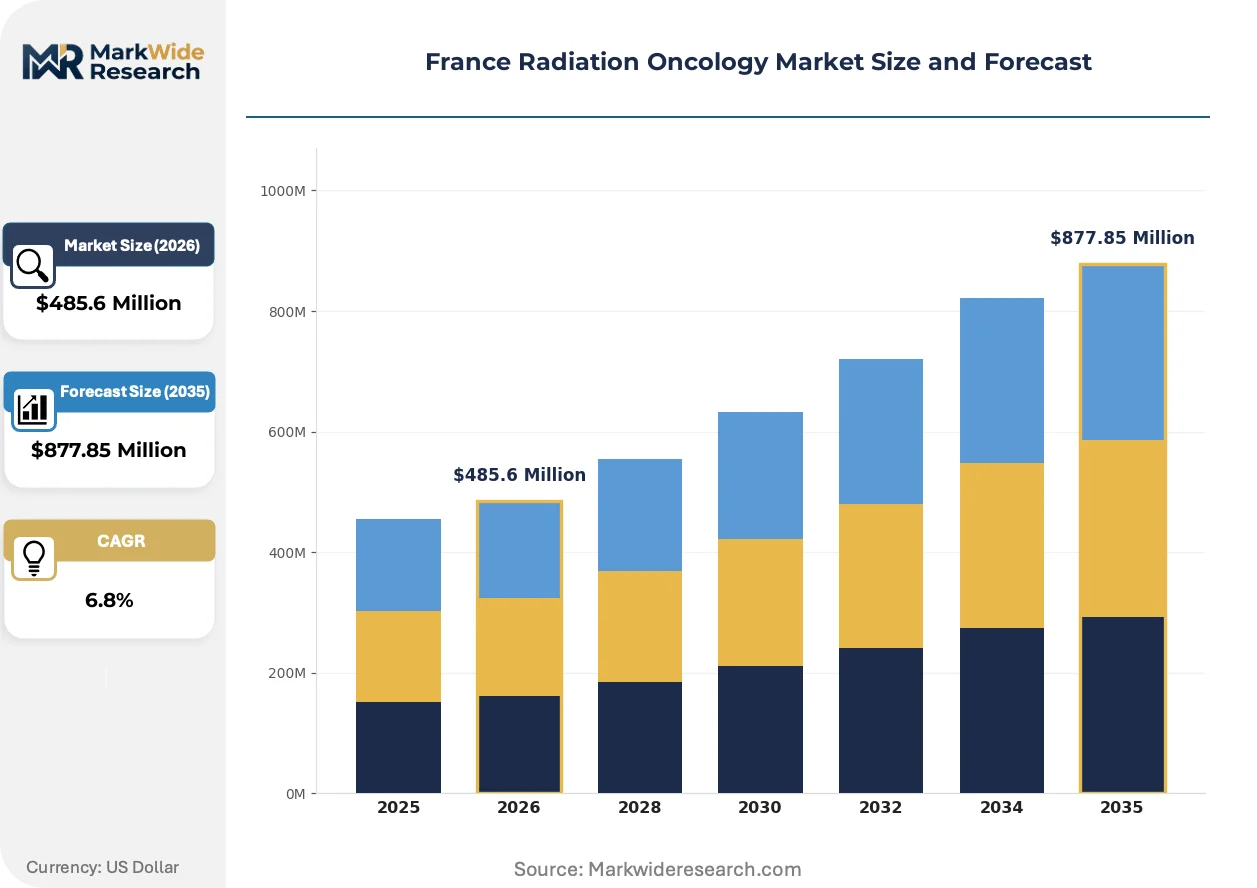
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $877.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy Devices, Radiation Therapy Planning Software, Imaging Systems End User: Hospitals, Cancer Treatment Centers, Research Institutions, Diagnostic Clinics Delivery Mode: External Beam Radiation Therapy, Internal Radiation Therapy, Stereotactic Radiosurgery, Proton Therapy Application: Breast Cancer, Lung Cancer, Prostate Cancer, Brain Tumors |
| Companies Covered | Varian Medical Systems, Elekta AB, Accuray Incorporated, Siemens Healthineers AG, GE HealthCare Technologies Inc., Koninklijke Philips NV, Canon Medical Systems Corporation, IBA Worldwide SA, Mevion Medical Systems Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Radiation Oncology Market Trends and Innovations
Adaptive radiation therapy protocols are compressing treatment fraction schedules while elevating real-time imaging requirements, forcing equipment architecture toward integrated delivery platforms.
Magnetic resonance-guided linear accelerators are overtaking conventional CT-based systems in premium treatment center procurement cycles. French cancer institutes in Marseille and Bordeaux are prioritizing MR-linac installations for soft-tissue visualization advantages in abdominal and pelvic malignancies. This modality shift is compressing demand for standalone simulation CT suites and redirecting capital toward hybrid imaging-radiation infrastructure.
ANSM's transposition of EU MDR post-market surveillance requirements is elevating clinical evidence submission burdens for linear accelerator software updates. Equipment suppliers must now document patient safety outcomes for algorithm modifications that previously qualified as routine maintenance. Radiation oncology departments are responding by consolidating vendor relationships to reduce compliance fragmentation across mixed-equipment fleets.
Service contract unbundling is disrupting traditional linear accelerator procurement economics. French hospital purchasing consortiums are separating hardware acquisition from multiyear maintenance agreements, subjecting aftermarket service pricing to competitive tender. This behavioral shift is most pronounced in the Provence-Alpes-Côte d'Azur region, where regional hospital groups are negotiating performance-based service level agreements tied to machine uptime guarantees rather than fixed annual fees.
France Radiation Oncology Market Segmentation
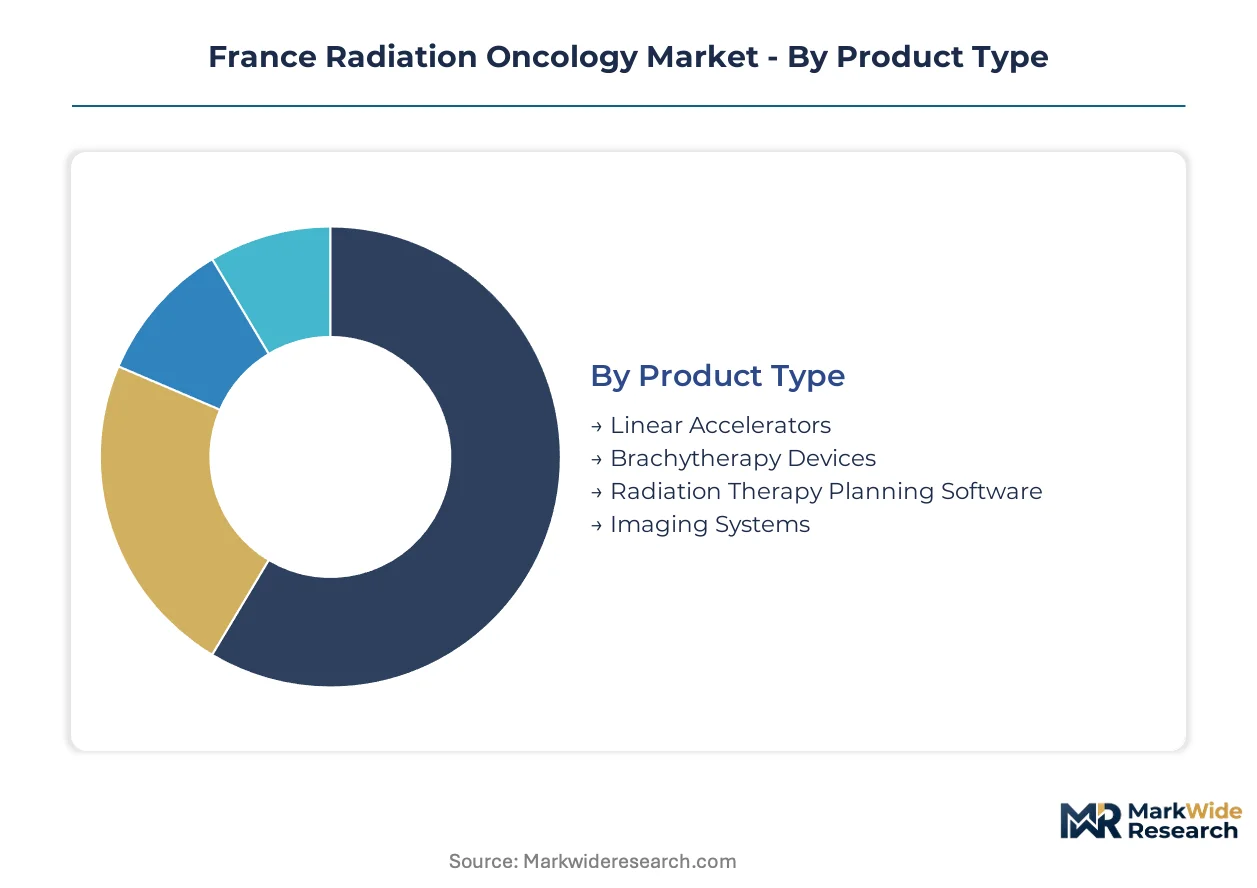
Equipment procurement decisions in France's radiation oncology sector diverge sharply between high-volume linear accelerator deployments and premium proton therapy installations. Segmentation reveals how reimbursement frameworks, clinical evidence requirements, and regional capacity planning reshape capital allocation across delivery modalities and end-user settings.
Product Type:
Linear accelerators dominate procurement volumes while proton therapy systems command premium capital commitments; software and imaging segments capture recurring revenue through upgrade cycles and integrated platform sales.
- Linear Accelerators:These megavoltage photon beam systems operate at 6–18 MV energies with multileaf collimator shaping for intensity-modulated delivery. Île-de-France hospital networks are prioritizing MR-guided linac replacements to address patient throughput bottlenecks in Parisian academic centers.
- Brachytherapy Devices:These systems deliver radioactive sources directly to tumor sites via catheter-based applicators for cervical, prostate, and breast malignancies. Regional cancer centers in Lyon and Marseille are expanding high-dose-rate afterloader installations to complement external beam programs.
- Radiation Therapy Planning Software:AI-integrated contouring and dose optimization modules are compressing planning timelines across French hospital networks.
- Imaging Systems:Cone-beam CT and MR-simulation platforms are converging with linac architectures for adaptive therapy protocols.
Today's leader: Linear Accelerators. Tomorrow's challenger: Imaging Systems.
End User:
Cancer treatment centers capture the highest patient throughput volumes while research institutions command premium pricing for protocol development and clinical trial infrastructure.
- Cancer Treatment Centers:These dedicated facilities manage the bulk of radiotherapy delivery across France's regional health agency networks. Commissioning decisions by ARS Île-de-France are accelerating linear accelerator density expansion in Parisian corridors.
- Hospitals:General hospital oncology departments integrate radiation therapy within broader cancer care pathways. University hospital centers in Toulouse and Strasbourg are anchoring proton therapy development through cyclotron infrastructure commitments.
- Research Institutions:Gustave Roussy and Institut Curie drive protocol innovation and vendor clinical evidence generation.
- Diagnostic Clinics:Private imaging centers are entering radiation therapy planning through teleradiology partnerships.
Cancer Treatment Centers command current procurement volume. Research Institutions are climbing the fastest as ANSM elevates clinical evidence requirements.
Delivery Mode:
External beam modalities absorb the majority of installed base maintenance while proton therapy represents the steepest expansion trajectory constrained by cyclotron capital intensity.
- External Beam Radiation Therapy:Conventional linac-based photon delivery remains the workhorse modality across French treatment centers. ANSM's MDR transposition is filtering equipment suppliers based on post-market surveillance capabilities.
- Proton Therapy:Cyclotron-based proton beam delivery enables Bragg peak dose deposition for pediatric and ocular malignancies. Regional health agencies in Lyon and Toulouse are allocating flagship academic center capital to proton facility commissioning.
- Internal Radiation Therapy:Brachytherapy programs are consolidating around high-dose-rate remote afterloader systems.
- Stereotactic Radiosurgery:Frameless and mask-based cranial and extracranial ablation platforms are penetrating satellite treatment centers.
External Beam Radiation Therapy anchors installed base economics. Proton Therapy is gaining share fastest among new commissioning decisions.
Application:
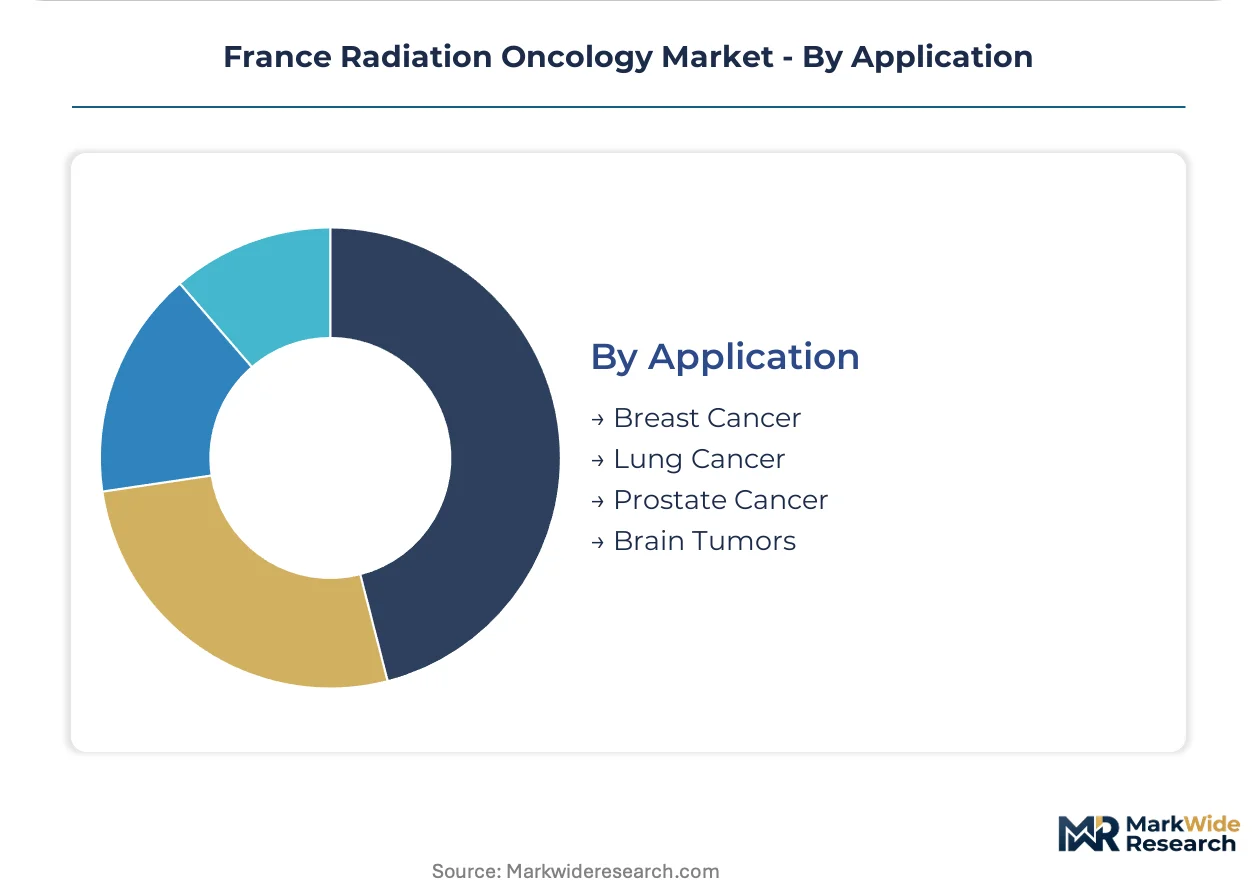
Breast and prostate cancer indications drive screening-linked volume while lung and brain applications concentrate in academic centers with advanced motion management capabilities.
- Breast Cancer:Adjuvant radiotherapy following lumpectomy represents the highest-volume indication across French cancer centers. Île-de-France screening program expansion is channeling demand toward hypofractionated whole-breast protocols.
- Lung Cancer:Stereotactic ablative radiotherapy for early-stage non-small cell lung cancer requires advanced motion management and functional imaging integration. Parisian academic networks are prioritizing MR-linac installations for soft-tissue visualization in thoracic treatment planning.
- Prostate Cancer:Ultra-hypofractionation protocols are compressing treatment courses to five fractions or fewer.
- Brain Tumors:Proton therapy access is concentrating in pediatric neuro-oncology at flagship centers.
Breast Cancer maintains volume leadership. Lung Cancer applications are expanding most quickly as screening programs and stereotactic protocols converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiation oncology infrastructure in France traces its modern lineage to the post-war establishment of national cancer centers under state-directed health planning, with capacity consolidation accelerating through regional hospital agency networks since the 2000s.
Île-de-France
Parisian academic hospital networks drive the densest linear accelerator deployment in Europe, with Gustave Roussy and Institut Curie anchoring proton therapy research. ARS Île-de-France commissioning decisions prioritize MR-guided linac installations to resolve patient throughput bottlenecks. The Petite Couronne treatment corridor concentrates satellite center development to absorb screening-program volume growth.
Auvergne-Rhône-Alpes
Lyon's Centre Léon Bérard anchors cyclotron-based proton therapy commissioning decisions by the regional health agency. Hospices Civils de Lyon integrate brachytherapy expansion with external beam programs for cervical and prostate malignancies. The Grenoble-Annecy corridor maintains isotope production dependency through Institut Laue-Langevin reactor proximity.
Provence-Alpes-Côte d'Azur
Marseille's Institut Paoli-Calmettes prioritizes MR-linac installations for soft-tissue visualization in abdominal treatment planning. Regional hospital groups negotiate performance-based service agreements separating hardware acquisition from maintenance contracts. The Aix-Marseille-Metropole cluster exhibits the most pronounced service contract unbundling behavior nationally.
Occitanie
Toulouse's University Hospital Center anchors proton therapy infrastructure commitments through cyclotron facility development. Peripheral departments exhibit lower linear accelerator density per capita, creating whitespace for satellite treatment center deployment. The Montpellier-Nîmes corridor attracts private imaging centers entering radiation therapy planning through teleradiology partnerships.
Nouvelle-Aquitaine
Bordeaux's Institut Bergonié converges on hybrid imaging-radiation infrastructure for adaptive therapy protocols. The regional health agency channels France's National Cancer Plan reimbursement authority toward centers demonstrating measurable patient outcome improvements. The Bayonne-Pau periphery exhibits medical physics workforce scarcity most acutely among provincial networks.
France Radiation Oncology Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with established service revenue streams. Equipment procurement authority concentrates among vendors possessing robust EU MDR quality management certifications, filtering marginal suppliers from tender participation. Three archetypes dominate: legacy linear accelerator incumbents with dense installed bases, proton therapy specialists with cyclotron integration capabilities, and imaging-radiation convergence platforms competing on workflow consolidation. Strategic moves center on unbundling service contracts from hardware sales and consolidating clinical evidence portfolios for MDR compliance.
Within the integrated platform tier, Siemens Healthineers AG and GE HealthCare Technologies Inc. exemplify imaging-radiation convergence strategies, while Varian Medical Systems anchors the legacy installed base archetype through linear accelerator service revenue retention. These three occupy positions reflecting divergent responses to ANSM's MDR transposition timelines and regional hospital agency procurement consolidation.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Accuray Incorporated |
| Siemens Healthineers AG |
| GE HealthCare Technologies Inc. |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| IBA Worldwide SA |
| Mevion Medical Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up service contractors dominate aftermarket maintenance, compressing margins for independent parts suppliers while anchoring pricing discipline through multi-year performance guarantees that hospital purchasing consortiums now mandate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies linear accelerator procurement, with CE-MDR certification tier and MR-guidance capability as primary price differentiation drivers. Cost compression in standard-tier conventional linacs intensifies because regional hospital groups unbundle service contracts from hardware acquisition. Cancer treatment centers in the Île-de-France corridor exhibit the least price sensitivity due to throughput urgency, while peripheral Occitanie satellite centers face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with German and Dutch precision-machined component suppliers for multileaf collimator assemblies. Cyclotron superconducting magnet production draws from specialized foundries in Switzerland and the United States, while software development clusters concentrate in Sweden and California. Tariff exposure on Chinese-sourced rare-earth magnets for linear accelerator waveguides elevates input cost volatility. Distribution runs through authorized dealer networks directly to ARS-managed hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's radiation oncology market functions as a geographic-arbitrage play, with proton therapy commissioning costs running substantially below equivalent US deployments due to centralized ARS capital planning and absence of facility-level profit-margin requirements.
For Market Incumbents: Anticipate AI-integrated treatment planning software displacing standalone contouring modules by embedding machine learning directly into linear accelerator control systems. Consolidate clinical evidence portfolios for EU MDR post-market surveillance compliance to filter smaller competitors from tender participation. Capacity addition in Auvergne-Rhône-Alpes proton therapy infrastructure anchors service revenue retention against emerging cyclotron specialists. For New Entrants and Emerging Players: The premium-to-economy pricing gap in MR-linac versus conventional linac procurement creates entry space for refurbished equipment platforms with upgraded software stacks. Occitanie's satellite treatment center whitespace offers the most penetrable geography, with teleradiology partnerships as the specific go-to-market angle for private diagnostic clinics entering radiation therapy planning. For Investors and Strategic Acquirers: Valuations sit cheapest among proton therapy cyclotron integrators lacking installed linear accelerator service revenue streams. Long-term viability over the coming decade hinges on MDR compliance completion timelines and proton commissioning decisions by regional health agencies. Watch ARS Île-de-France capacity expansion announcements as the specific signal indicating inflection in capital allocation intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements filter marginal suppliers from French hospital tenders. |
| Hospital System Partnership | ARS regional agency relationships determine proton therapy commissioning priority queues. |
| Software Companion Development | AI-integrated contouring modules compress planning timelines for Gustave Roussy protocols. |
| Reimbursement Strategy | National Cancer Plan outcome metrics channel authority toward proven patient improvement centers. |
| Backward Integration into Superconducting Magnets | Cyclotron component captive supply reduces Swiss foundry dependency for proton facility developers. |
Research Methodology
Bottom-up cancer treatment center capacity modeling reconciled against top-down linear accelerator shipment tracking forms the analytical core of this study. Primary interviews with hospital biomedical engineers, ARS regional procurement officers, medical physicists, and GPO contracts managers combined with secondary validation from ANSM device vigilance databases, EU MDR notified body registries, hospital procurement consortium records, and regional health agency capital planning documents. Triangulation across these sources anchors volume estimates.
Input-output matrices map equipment procurement flows across delivery mode, end-user setting, and application indication dimensions over the projection horizon. CAGRs derive from segmented adoption curves weighted by reimbursement pathway maturity and clinical evidence publication velocity. Forecast inputs incorporate proton therapy commissioning timelines from regional hospital agencies and MR-linac replacement cycles in Parisian academic networks.
Caveats apply where MDR transition completion delays or isotope reactor maintenance disruptions could materially shift the outlook. Forecasts reflect assumptions about ARS capital allocation continuity and workforce training program expansion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
AI in Oncology Market
Oncology
Tumor Embolization Market
Oncology
Ustekinumab Market
Oncology
North America Tumor Ablation Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Metastases Spinal Tumor Market
Oncology
Australia Cancer Treatment Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Global Genomics in Cancer Care Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Europe Radiotherapy Market