
 US Biomedical Refrigerators and Freezers Market | 2026-2036
US Biomedical Refrigerators and Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
US Biomedical Refrigerators and Freezers Market Intelligence
Ultra-low temperature specification tiers is bifurcating the competitive landscape into premium precision manufacturers and cost-optimized suppliers. Thermo Fisher Scientific leverages its cryogenic engineering heritage to dominate the minus-eighty-degree segment. Eppendorf AG anchors its position through specialized laboratory freezer configurations for genomic workflows. Haier Biomedical competes aggressively on manufacturing scale, offering standardized pharmacy refrigerator platforms at volume price points.
US biomedical refrigerators and freezers are thermally insulated cabinet systems engineered to maintain precise temperature setpoints between minus one-hundred-fifty degrees Celsius and plus eight degrees Celsius, utilizing vapor-compression, cascade, or Stirling-cycle refrigeration architectures with redundant cooling loops and continuous digital monitoring. Blood bank refrigerators command the largest installed base due to mandatory FDA compliance for hemocomponent storage, while cryogenic freezers represent the fastest-expanding margin pool as cell therapy manufacturing scales. Pharmacy refrigerators occupy a mature replacement cycle segment where energy efficiency certifications now determine procurement outcomes.
FDA 21 CFR Part 11, CDC Vaccine Storage and Handling Toolkit guidelines, and Joint Commission accreditation standards collectively mandate temperature mapping, alarm redundancy, and documented calibration protocols that elevate equipment specifications and consolidate vendor qualification lists. The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is additionally reshaping compressor technology roadmaps. Stakeholders must monitor evolving USP <797> and <800> pharmaceutical compounding standards, as these will dictate next-generation cold storage infrastructure investments across hospital and outsourced compounding facilities.
Market Dynamics
The EPA's AIM Act hydrofluorocarbon phasedown is forcing compressor technology transitions across US biomedical cold storage, while hospital consolidation concentrates purchasing power among integrated delivery networks. This dual pressure is compressing vendor margins and accelerating qualification list consolidation.
Growth Catalysts
- FDA 21 CFR Part 11:Digital temperature monitoring mandates drive replacement cycles for legacy blood bank refrigerators lacking compliant data logging architectures.
- mRNA vaccine protocols:Academic medical centers in the Northeast corridor are procuring minus-eighty-degree units at elevated rates for research and clinical applications.
- Cell therapy manufacturing:Cryogenic freezers with redundant cooling loops are expanding installed base as bioprocessing scales beyond pilot volumes.
Market Restraints
- Copper and aluminum input volatility:Cascade refrigeration systems require substantial heat exchanger metals, exposing manufacturers to commodity price swings.
- Compressor supply concentration:Domestic production of Stirling-cycle engines relies on a limited supplier base concentrated in New England precision manufacturing clusters.
- Technical limitation:Ultra-low temperature units face energy density constraints that prevent portable configurations for field-deployed vaccine campaigns.
Strategic Opportunities
- Outsourced compounding facilities:USP <797> and <800> compliance investments create demand for purpose-built pharmacy refrigerators with validated temperature mapping.
- Energy efficiency certifications:DOE appliance standards are creating procurement preference shifts toward variable-speed compressor platforms.
- Remote monitoring convergence:IoT sensor integration with cloud-based alarm systems enables predictive maintenance contracts for hospital biomedical engineering departments.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized technicians for minus-one-hundred-fifty-degree system maintenance are concentrated among retiring workforce cohorts in legacy aerospace regions.
- Validation timeline compression:Joint Commission accreditation cycles now demand documented calibration protocols that extend equipment qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Biomedical Refrigerators and Freezers Market |
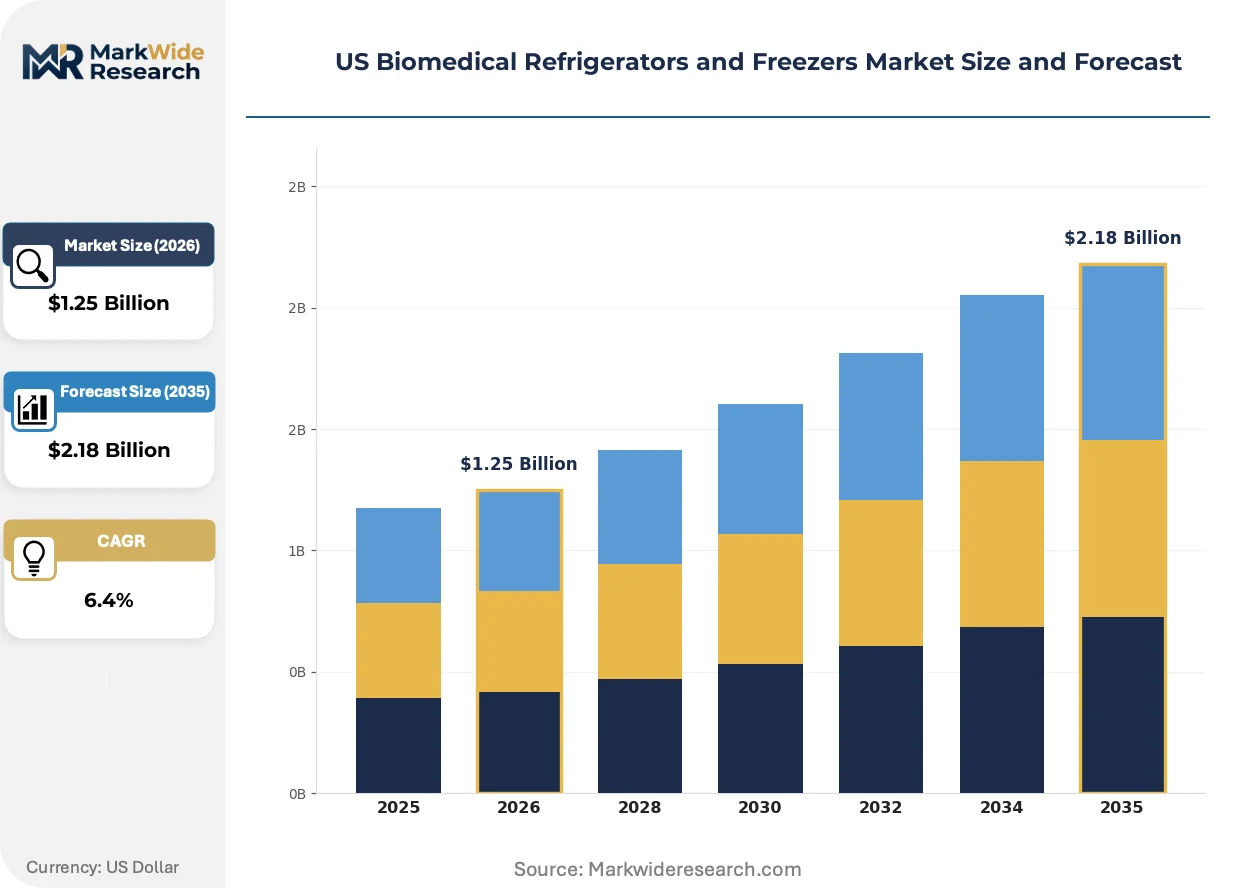
| Market Size in 2026 | $1.25 Billion |
| Market Size in 2035 | $2.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Undercounter Refrigerators, Laboratory Freezers, Pharmacy Refrigerators, Blood Bank Refrigerators, Cryogenic Freezers Technology: Compressor Cooling, Thermoelectric Cooling, Absorption Cooling, Cascade Cooling, Stirling Cooler Application: Vaccine Storage, Blood Storage, Pharmaceutical Storage, Research Labs, Organ Preservation End User: Hospitals, Diagnostic Centers, Research Institutes, Pharmaceutical Manufacturers, Blood Banks |
| Companies Covered | Eppendorf AG, Aegis Scientific Inc., Thermo Fisher Scientific Inc., Haier Biomedical, Follett Products LLC, PHC Holdings Corporation, Panasonic Healthcare Corporation, Power Scientific Inc., Helmer Scientific LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Biomedical Refrigerators and Freezers Market Strategic Shifts & Innovations
Refrigeration architecture choices are bifurcating as environmental mandates collide with precision requirements. Vapor-compression, cascade, and Stirling-cycle platforms are each finding distinct application niches based on temperature setpoint and redundancy needs.
Stirling-cycle freezers are supplanting traditional cascade systems in cell therapy manufacturing facilities requiring minus-eighty-degree stability with reduced refrigerant charge volumes. Biopharma contract manufacturers in the Research Triangle and Boston-Cambridge corridor are specifying these units for GMP-compliant storage. The shift is compressing maintenance requirements while elevating capital expenditure thresholds for new facility builds.
The EPA's AIM Act hydrofluorocarbon phasedown is mandating alternative refrigerant adoption across compressor technology roadmaps. Equipment manufacturers are redesigning heat exchange architectures to accommodate lower-global-warming-potential working fluids. Blood bank refrigerator segments face the steepest compliance curves due to large installed bases and extended replacement cycles.
Hospital procurement departments are consolidating vendor relationships through integrated delivery network frameworks that bundle cold storage with service contracts. Group purchasing organizations are displacing direct manufacturer relationships for standard pharmacy refrigerator categories. The Southeast and Southwest US regions exhibit the most pronounced concentration of purchasing authority under these consolidated structures.
US Biomedical Refrigerators and Freezers Market Segmentation
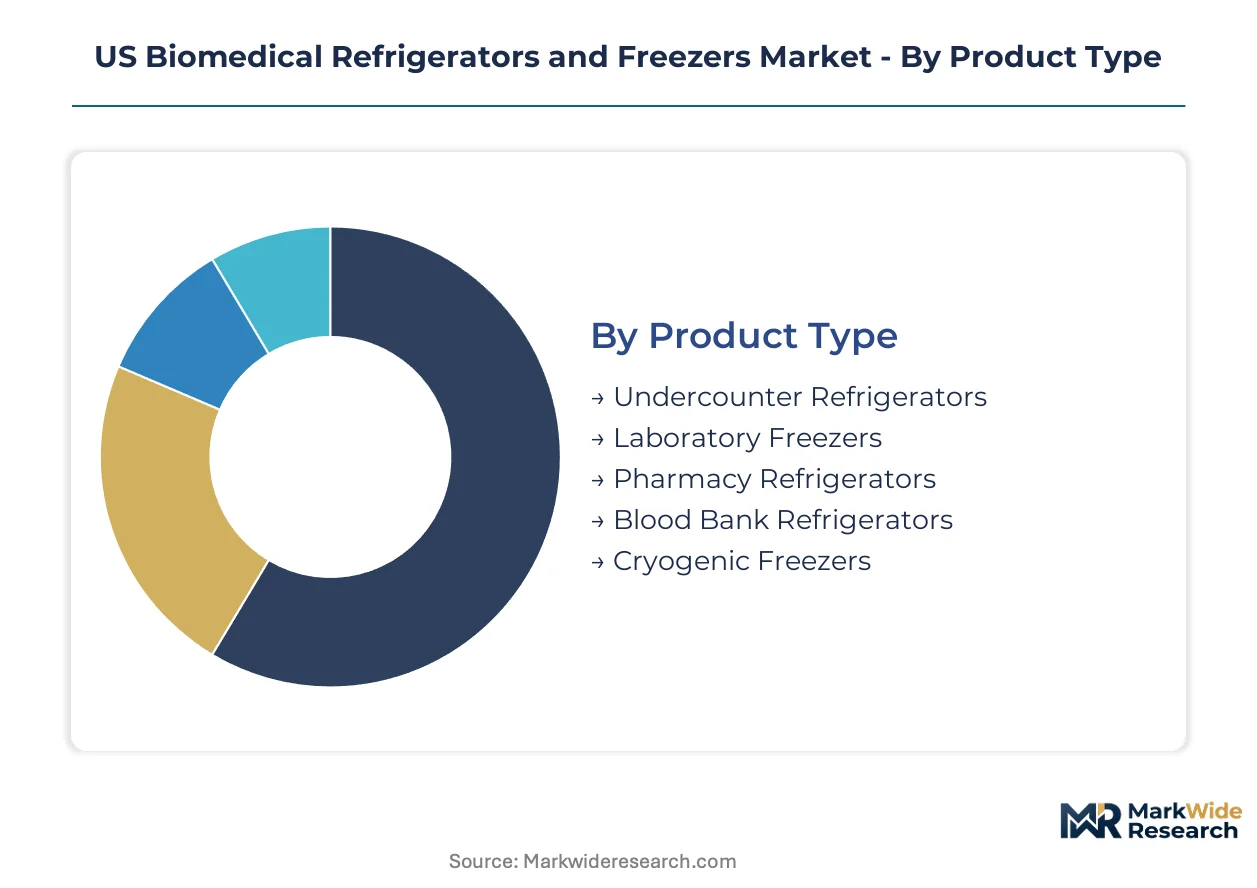
Equipment specifications diverge sharply across use cases in this market. Temperature precision requirements, regulatory compliance tiers, and redundancy architectures create distinct margin pools that reward specialization over volume scale.
Product Type:
Margin concentration tracks directly to thermal stability specifications and certification complexity.
- Cryogenic Freezers:Engineered for minus-one-hundred-fifty-degree setpoints using Stirling-cycle or cascade architectures with redundant cooling loops. Academic medical centers in the Northeast corridor are procuring these units at elevated rates for mRNA vaccine research and cell therapy manufacturing workflows.
- Blood Bank Refrigerators:FDA-validated systems maintaining plus-two-to-plus-six-degree setpoints with continuous digital monitoring and alarm redundancy. Hospital blood centers command the largest installed base due to mandatory hemocomponent storage compliance, though replacement cycles now accelerate under updated 21 CFR Part 11 data logging mandates.
- Pharmacy Refrigerators:Purpose-built units for pharmaceutical compounding with validated temperature mapping per USP standards.
- Laboratory Freezers:Minus-twenty-to-minus-forty-degree units for genomic sample preservation and reagent storage.
- Undercounter Refrigerators:Space-constrained clinical units for point-of-care medication storage with basic digital controls.
The dominant share belongs to Blood Bank Refrigerators, while Cryogenic Freezers is closing the gap fastest.
Technology:
Refrigeration architecture choices determine capital intensity, maintenance burden, and regulatory compliance trajectory.
- Stirling Cooler:Kinematic freezers with helium working fluid and no refrigerant charge, achieving minus-eighty-degree stability with reduced maintenance intervals. Biopharma contract manufacturers in the Research Triangle specify these for GMP-compliant cell therapy storage.
- Compressor Cooling:Vapor-compression systems with variable-speed drives dominating pharmacy and blood bank segments. The EPA's AIM Act hydrofluorocarbon phasedown is forcing heat exchanger redesigns to accommodate lower-global-warming-potential working fluids.
- Cascade Cooling:Stacked refrigeration circuits for ultra-low temperature achievement with higher energy density.
- Thermoelectric Cooling:Solid-state Peltier devices for portable and low-capacity configurations with limited temperature pull-down.
- Absorption Cooling:Heat-driven systems for off-grid or noise-sensitive deployments with reduced efficiency.
Compressor Cooling retains the widest installed base, though Stirling Cooler platforms are expanding most quickly in premium applications.
Application:
Demand fragmentation reflects divergent validation requirements and procurement authority concentration.
- Vaccine Storage:Ultra-low temperature protocols for mRNA formulations requiring minus-eighty-degree stability with continuous monitoring. Hospital systems are upgrading legacy units to meet CDC Vaccine Storage and Handling Toolkit guidelines.
- Blood Storage:Hemocomponent preservation with FDA-mandated temperature mapping and documented calibration protocols.
- Pharmaceutical Storage:USP-compliant cold chain for compounded sterile preparations.
- Research Labs:Flexible temperature setpoints for academic and biopharma discovery workflows.
- Organ Preservation:Specialized perfusion and static cold storage for transplant logistics.
Blood Storage commands established procurement volume, while Vaccine Storage is gaining share fastest on protocol standardization.
End User:
Purchasing power consolidation through integrated delivery networks reshapes vendor access patterns.
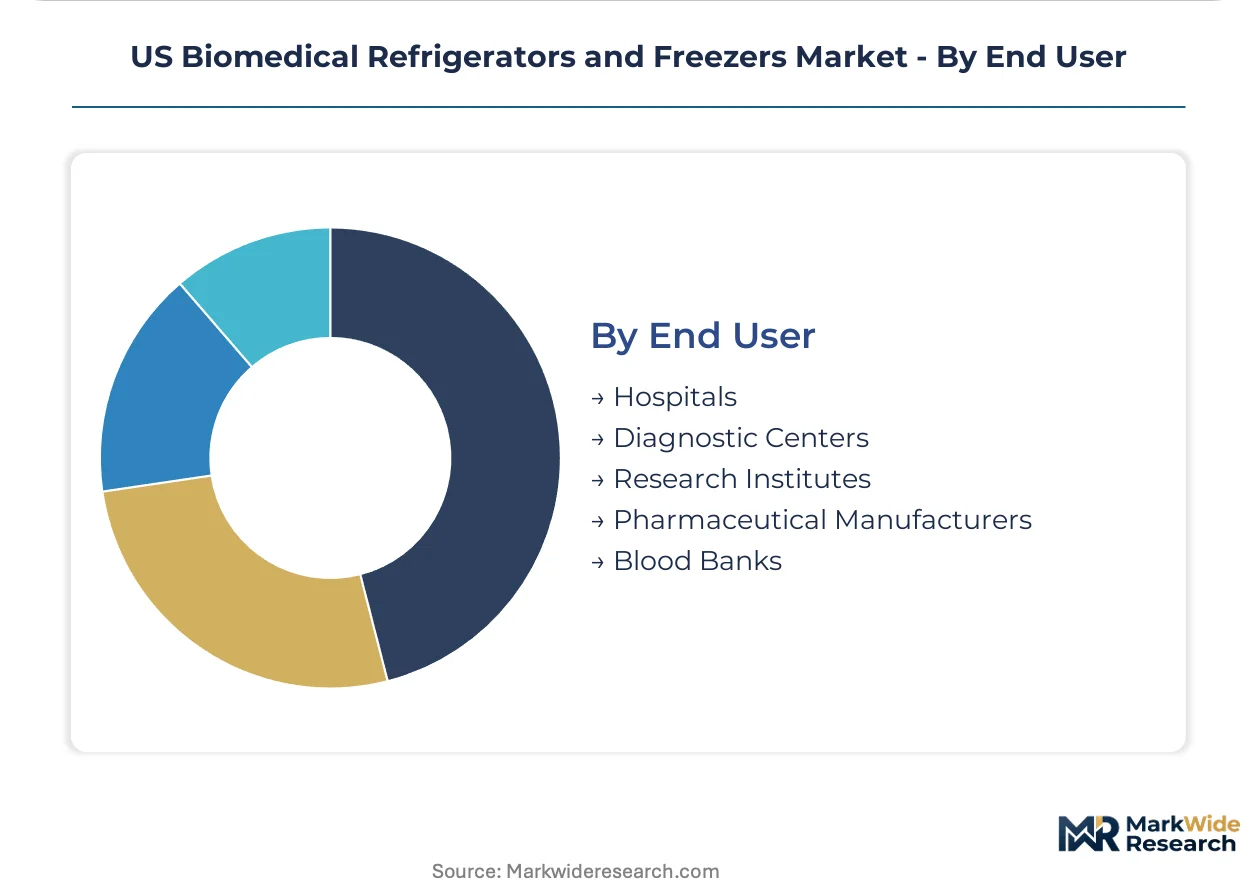
- Hospitals:Consolidated procurement through IDN frameworks bundling cold storage with multi-year service contracts. The Southeast and Southwest exhibit pronounced purchasing authority concentration under these structures.
- Pharmaceutical Manufacturers:GMP-validated requirements driving specification intensity for commercial-scale bioprocessing.
- Research Institutes:Academic medical centers with NIH funding driving premium unit specification in the Northeast corridor.
- Diagnostic Centers:Moderate-capacity reagent storage with standardized pharmacy refrigerator platforms.
- Blood Banks:Standalone hemocomponent facilities with dedicated regulatory compliance staff.
Hospitals anchor procurement volume, while Pharmaceutical Manufacturers are scaling fastest on cell therapy manufacturing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cryogenic engineering exports flow into US academic medical centers, while domestic biotech clusters in Massachusetts and California drive premium equipment specification. Trade corridors link European precision manufacturing with American cold chain infrastructure upgrades.
Northeast Corridor
Academic medical centers in Boston and New York Metro procure minus-eighty-degree units for mRNA vaccine research and cell therapy manufacturing workflows. FDA 21 CFR Part 11 compliance mandates accelerate replacement cycles at NIH-funded institutions. The Boston-Cambridge biotech cluster concentrates GMP-validated cryogenic freezer demand among contract manufacturers.
Southeast
Hospital consolidation through integrated delivery networks concentrates purchasing power across Florida and Georgia health systems. CDC Vaccine Storage and Handling Toolkit guidelines drive standardization of pharmacy refrigerator platforms. The Research Triangle in North Carolina anchors biopharma manufacturing expansion requiring redundant cooling loop configurations.
Texas Triangle
Standalone blood bank facilities in Houston and Dallas-Fort Worth maintain large installed bases of FDA-validated hemocomponent storage systems. EPA AIM Act hydrofluorocarbon phasedown timelines compress replacement decisions for legacy compressor fleets. Medical center expansion in Austin generates demand for purpose-built pharmacy refrigerators.
California
Cell therapy manufacturing scales beyond pilot volumes in South San Francisco and San Diego biotech corridors. USP <797> and <800> pharmaceutical compounding standards dictate cold storage infrastructure investments across hospital and outsourced facilities. Energy efficiency certifications under DOE appliance standards determine procurement outcomes in municipal utility territories.
Pacific Northwest
Research institutes in Seattle specify laboratory freezers for genomic sample preservation and reagent storage. Joint Commission accreditation cycles demand documented calibration protocols that extend equipment qualification periods. Precision manufacturing clusters in Portland supply Stirling-cycle engine components for domestic ultra-low temperature unit assembly.
US Biomedical Refrigerators and Freezers Market Key Industry Players
Listed leaders compete with private specialists across precision engineering and manufacturing scale dimensions. Publicly traded entities leverage capital market access for technology licensing and geographic expansion, while private fabricators defend niche positions through specialized service relationships. Three archetypes dominate: premium precision manufacturers, cost-optimized volume suppliers, and specialized laboratory equipment providers. Consolidation through strategic partnerships and portfolio diversification reshapes vendor qualification lists.
Among premium-tier precision manufacturers, Thermo Fisher Scientific Inc. and Eppendorf AG exemplify cryogenic engineering heritage positions. Haier Biomedical occupies a scale-driven archetype competing on manufacturing volume and standardized platform pricing. These three entities anchor the competitive structure, with Thermo Fisher Scientific Inc. representing listed market capitalization advantages and Eppendorf AG exemplifying European laboratory specialization. Private specialists including Aegis Scientific Inc., Follett Products LLC, and Helmer Scientific LLC sit within regional service-intensive tiers.
| Leading Market Players |
|---|
| Eppendorf AG |
| Aegis Scientific Inc. |
| Thermo Fisher Scientific Inc. |
| Haier Biomedical |
| Follett Products LLC |
| PHC Holdings Corporation |
| Panasonic Healthcare Corporation |
| Power Scientific Inc. |
| Helmer Scientific LLC |
| Others |
Cost & Logistics Intelligence
Multi-year service contracts bundling equipment with predictive maintenance lock in supply access and price visibility for hospital integrated delivery networks negotiating against compressor supply concentration. These arrangements insulate procurement teams from aluminum and copper volatility while compressing vendor margins through volume commitments.
Pricing Analysis
Current-generation Stirling-cycle platforms command substantial premiums over prior-generation cascade systems and emerging thermoelectric alternatives. Three-tier pricing structure across premium precision manufacturers, mid-tier laboratory specialists, and cost-optimized volume suppliers reflects certification complexity and redundant cooling loop specifications. Cost compression in standard pharmacy refrigerator segments is intensifying because group purchasing organizations displace direct manufacturer relationships. Blood bank facilities exhibit the highest price sensitivity due to extended replacement cycles and mandatory FDA compliance costs, while cell therapy manufacturers show least sensitivity given GMP validation requirements.
Supply Chain Analysis
Port congestion along Shanghai-to-Long Beach trade lanes elevates inbound logistics costs for precision-manufactured Stirling-cycle engine components sourced from German and Japanese cryogenic engineering clusters. Domestic assembly draws from concentrated copper heat exchanger suppliers in Arizona and Texas, helium working fluid distributors in Oklahoma, and compressor motor windings from Mexican maquiladora facilities. Single-source vulnerability concentrates in New England precision manufacturing clusters producing kinematic Stirling engines. Distribution runs through hospital group purchasing organization frameworks and direct biopharma contract manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US biomedical cold storage market rewards specialized cryogenic engineering capabilities that retiring workforce cohorts in legacy aerospace regions are taking with them. Equipment qualification timelines and FDA validation protocols create durable moats for incumbents possessing documented calibration expertise.
For Market Incumbents: Fortify service contract penetration through predictive maintenance IoT integration, locking out emerging competitors lacking cloud-based alarm system infrastructure. Deepen backward integration into Stirling-cycle engine component manufacturing to offset New England supplier concentration risk. Prioritize cryogenic engineering talent retention programs as retiring technician cohorts threaten maintenance capacity. For New Entrants and Emerging Players: Anchor in outsourced compounding facility segments where USP <797> and <800> compliance investments create demand for purpose-built pharmacy refrigerators with validated temperature mapping. Target Southeast integrated delivery networks exhibiting pronounced purchasing authority concentration under consolidated structures. Pursue energy efficiency certification differentiation under DOE appliance standards as procurement preference lever. For Investors and Strategic Acquirers: Regional service-intensive specialists with documented Joint Commission calibration protocols and established hospital biomedical engineering relationships represent attractive acquisition targets. Long-term viability hinges on exposure to cell therapy manufacturing expansion versus blood bank replacement cycle maturity. Monitor EPA AIM Act hydrofluorocarbon phasedown timeline acceleration as inflection indicator for compressor technology transition investments.| Strategic Initiative | Industry Significance |
|---|---|
| Stirling-Cycle Technology Licensing | Enables domestic manufacturers to bypass New England supplier concentration for minus-eighty-degree platforms. |
| Hospital System Partnership | Locks in multi-year service contracts through integrated delivery network procurement frameworks. |
| FDA 21 CFR Part 11 Compliance Investment | Accelerates replacement cycles for legacy blood bank refrigerators lacking digital data logging architectures. |
| Energy Efficiency Certification Program | Aligns variable-speed compressor platforms with DOE appliance standards driving procurement preferences. |
| Backward Integration into Heat Exchanger Manufacturing | Reduces exposure to copper and aluminum commodity price volatility affecting cascade refrigeration margins. |
Research Approach
The analysis maps cryogenic freezer, blood bank refrigerator, pharmacy refrigerator, and laboratory freezer sub-sectors, each validated through biomedical engineering directors, hospital procurement managers, GPO contracts specialists, and biopharma facility planners. Primary interview insights triangulate against FDA 21 CFR Part 11 guidance documents, CDC Vaccine Storage and Handling Toolkit protocols, EPA AIM Act refrigerant phasedown schedules, and hospital procurement database records. Bottom-up unit shipment estimates reconcile with top-down market value projections across temperature specification tiers.
Consistency checks validate volume and value outputs against external benchmarks including energy efficiency certification adoption rates and Stirling-cycle platform penetration in cell therapy manufacturing facilities. Segmentation dimensions span product type, refrigeration architecture, application protocol, and end-user procurement authority concentration. CAGRs derive from replacement cycle acceleration under digital monitoring mandates and bioprocessing scale-up beyond pilot volumes. Forecast inputs incorporate NIH funding trajectories for academic medical centers and biopharma manufacturing expansion in designated research corridors.
Decision-makers should treat outputs as directional under assumptions of continued hospital consolidation and EPA refrigerant phasedown adherence; material deviation in either would warrant model refresh. Specific risks include copper and aluminum commodity price spikes, Stirling-cycle supplier concentration disruptions, and Joint Commission accreditation timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Electrophysiology Equipment and Recording Systems Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
Global Radiation Therapy Equipment Market