
 US Pharmaceutical Sterility Testing Market | 2026-2036
US Pharmaceutical Sterility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Pharmaceutical Sterility Testing Market Intelligence
FDA's 2023 guidance on rapid microbiological methods is repositioning capital allocation across the sterility testing value chain. Charles River Laboratories leverages its biologics safety testing footprint to anchor high-complexity sterility programs. Thermo Fisher Scientific sustains instrument-installed base advantages through automated system refreshes. SGS SA competes on geographic coverage, extending its network of ISO 17025-accredited microbiology laboratories.
Pharmaceutical sterility testing encompasses validated procedures for detecting viable microbial contaminants in drug products, medical devices, and biological materials, typically requiring incubation periods of 14 days under specified temperature and atmospheric conditions to ensure absence of bacteria, fungi, and other microorganisms. Membrane filtration dominates parenteral applications due to its sensitivity with low-turbidity samples, while rapid sterility tests capture the fastest expansion as ATP bioluminescence and PCR-based platforms displace growth-dependent methods. Automated systems concentrate margin pools through reduced human intervention and compliant data integrity, whereas traditional methods retain volume share in generic injectables and established quality control protocols.
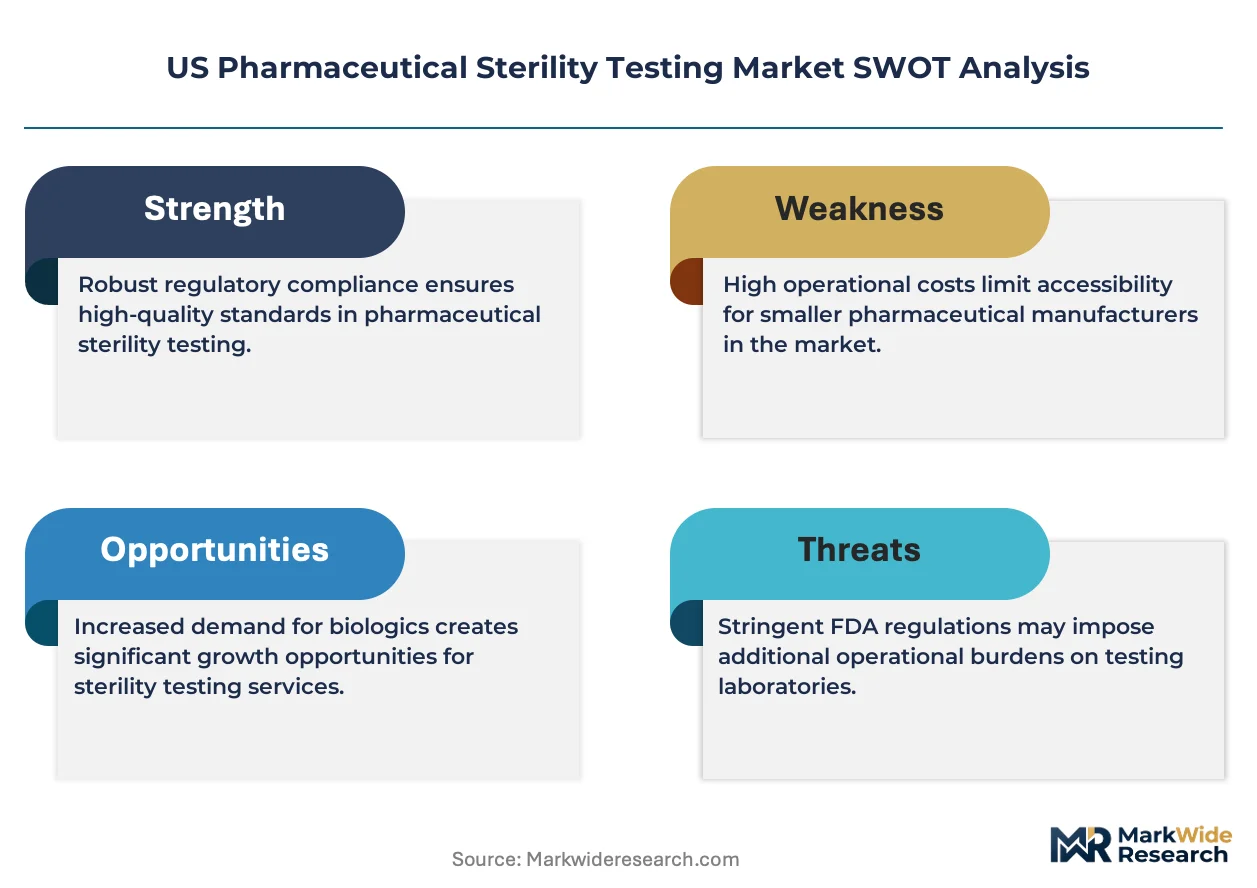
FDA, USP Chapter 71, and ISO 11737 collectively enforce method suitability requirements, incubation parameters, and validation standards that determine which laboratories qualify for commercial release testing. The agency's sterility test modernization initiative shapes demand by privileging technologies that demonstrate equivalence to compendial reference methods. Stakeholders must monitor FDA's evolving stance on alternative microbiological methods and align capability investments with the trajectory of regulatory acceptance.
Market Dynamics
FDA's sterility test modernization initiative is compressing validation timelines while ATP bioluminescence and PCR-based platforms rewrite method suitability requirements across parenteral manufacturing corridors.
Growth Catalysts
- Biologics pipeline expansion:Cell and gene therapy manufacturers in Massachusetts and California corridors are mandating high-complexity sterility programs that exceed traditional pharmaceutical QC protocols.
- USP Chapter 71 alignment:Compendial method harmonization is eliminating redundant validation studies, reducing time-to-release for multi-site manufacturing networks.
- Rapid microbiological methods:ATP bioluminescence platforms are capturing validation equivalency status, displacing 14-day growth-dependent incubation cycles in sterile injectables production.
Market Restraints
- ISO 17025 accreditation backlog:Laboratory certification queues in secondary US markets are extending qualification timelines for contract testing organizations.
- Instrument capital intensity:Automated sterility systems require seven-figure capital commitments that concentrate capability among large-scale parenteral manufacturers.
- Compendial reference method rigidity:FDA's equivalence demonstration requirements are creating friction for novel detection technologies seeking regulatory acceptance.
Strategic Opportunities
- Cell therapy CDMO penetration:Texas and North Carolina biomanufacturing clusters are underpenetrated for rapid sterility validation services.
- Continuous manufacturing integration:Real-time release testing architectures are converging with in-line bioburden monitoring for closed-system bioreactors.
- Advanced therapy tax incentives:IRA manufacturing credits are subsidizing sterility infrastructure investments for domestic gene therapy production.
Industry Challenges
- Microbiology talent scarcity:Rapid method specialists command premium compensation, constraining laboratory scaling in competitive hiring markets.
- Legacy LIMS integration:Automated sterility platforms require custom data integrity bridges to existing quality management systems.
- Method transfer complexity:Multi-site pharmaceutical networks face validation divergence when deploying rapid platforms across distributed manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pharmaceutical Sterility Testing Market |
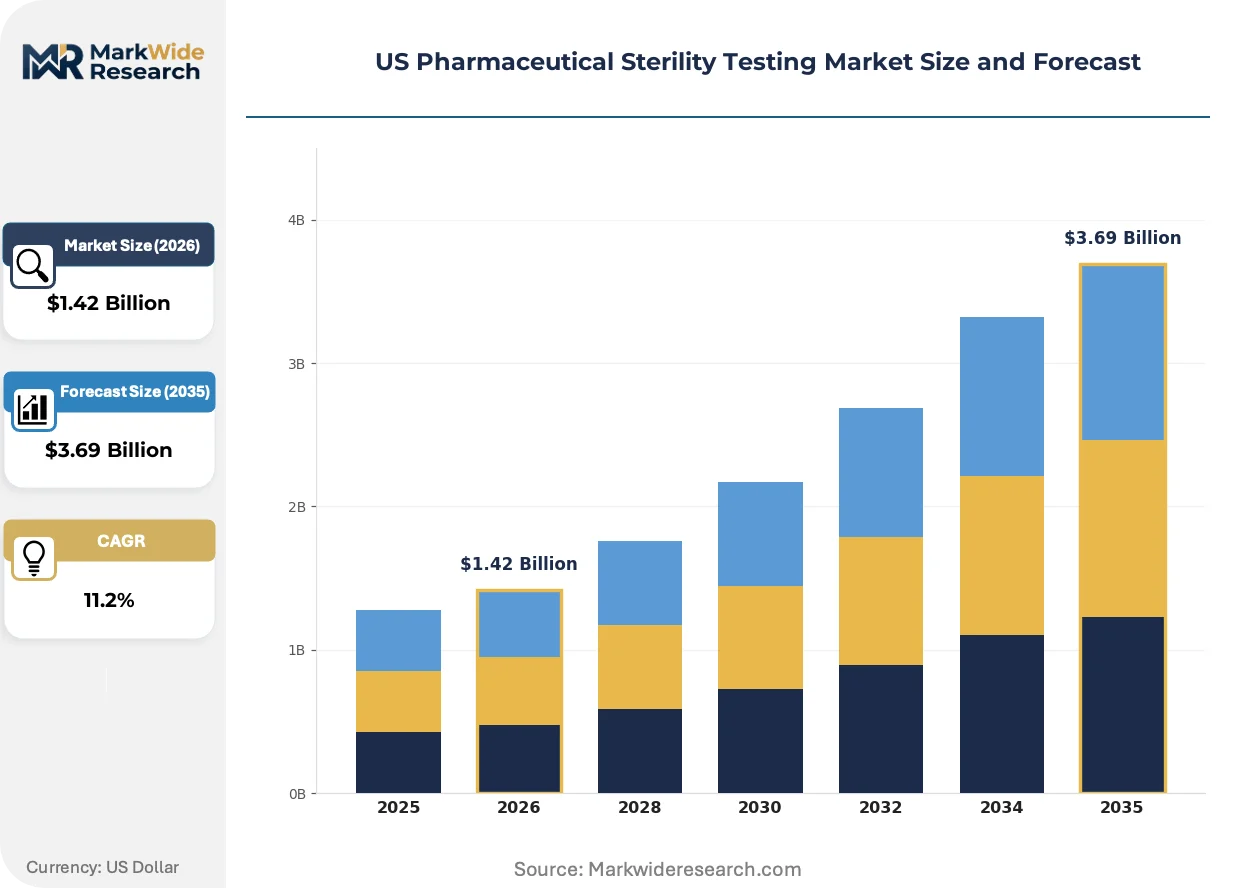
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.69 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Method: Membrane Filtration, Direct Inoculation, Test for Aseptic Conditions, Rapid Sterility Tests Product Type: Injectables, Biological Products, Medical Devices, Others End User: Pharmaceutical Manufacturers, Contract Research Organizations, Hospital Laboratories, Quality Control Laboratories Technology: Traditional Methods, Automated Systems, PCR Technology, Next-Generation Sequencing |
| Companies Covered | Charles River Laboratories, Thermo Fisher Scientific, SGS SA, Laboratory Corporation of America Holdings, STERIS, Pacific Biolabs, Boston Analytical, Pace Analytical, Nelson Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pharmaceutical Sterility Testing Market Strategic Shifts & Innovations
Technological substitution is compressing incubation cycles while regulatory guidance accelerates platform turnover. Three forces are restructuring capability requirements and procurement patterns.
ATP bioluminescence detection is rewriting sterility validation economics. Parenteral manufacturers in the Northeast corridor are adopting these platforms at accelerated pace, displacing growth-dependent reference methods. The technology is rewriting laboratory staffing models by reducing microbiologist bench time and enabling 24-hour release decisions for time-sensitive biologics.
FDA's 2023 rapid microbiological methods guidance is mandating equivalence study designs that privilege head-to-head compendial comparisons. Sterile injectables producers must now document statistical correlation between novel and reference methods prior to commercial deployment. Biologics manufacturers with internal QC laboratories are responding by establishing dedicated rapid method validation groups.
Buyer consolidation among top-tier pharmaceutical manufacturers is concentrating contract testing awards. Large parenteral producers are unbundling sterility testing from broader safety testing portfolios, creating direct procurement relationships with specialized microbiology laboratories. This pattern is most visible in California's San Francisco Bay Area biotech cluster, where gene therapy sponsors are qualifying single-source rapid sterility providers for clinical-to-commercial transitions.
US Pharmaceutical Sterility Testing Market Segmentation
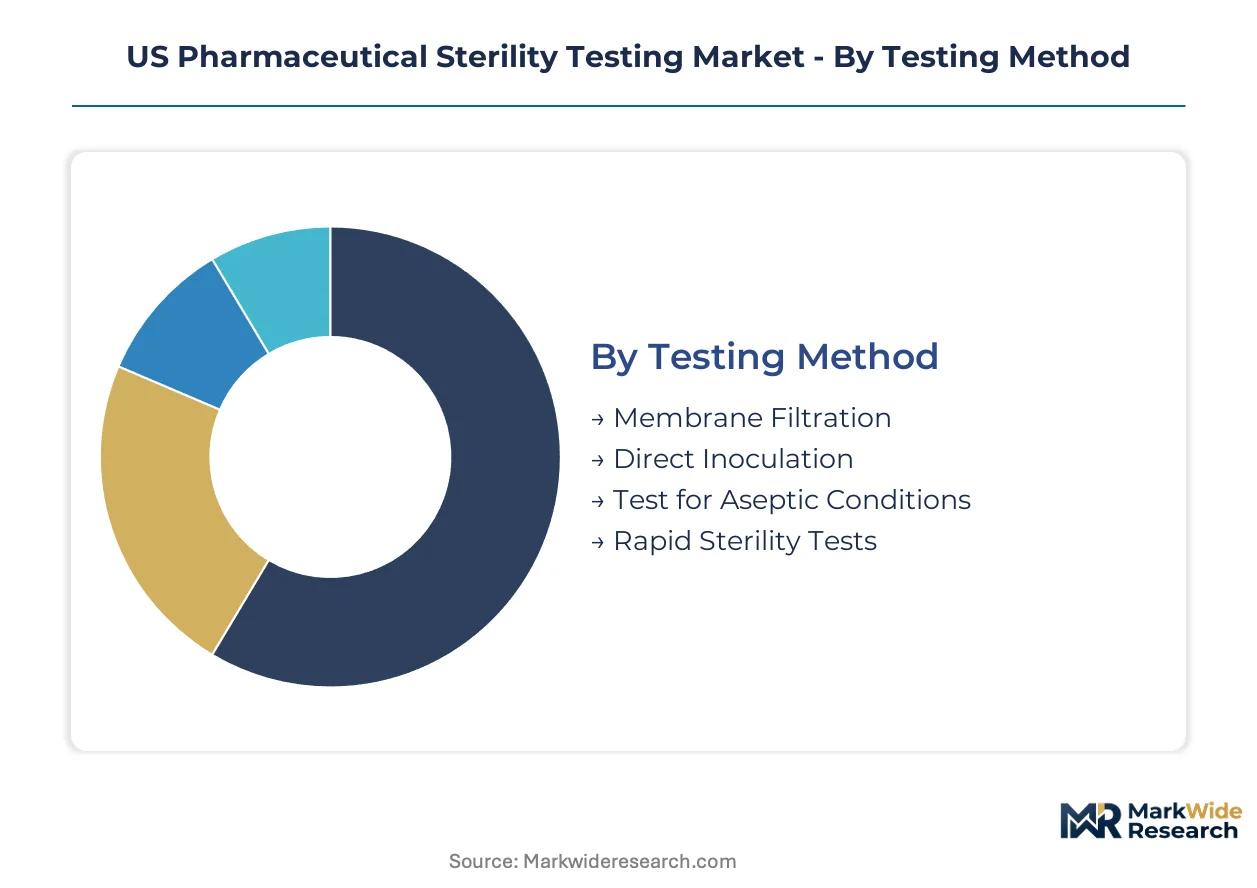
Segmentation in US pharmaceutical sterility testing reveals how capital allocation, regulatory compliance requirements, and manufacturing complexity fragment demand across distinct capability tiers. Each dimension—method, product, end user, and technology—carries specific validation protocols and margin structures that shape vendor positioning.
Testing Method:
Supply concentration in sterility testing methods reflects the tension between compendial acceptance and operational throughput, with platform selection determining laboratory staffing models and release timelines.
- Membrane Filtration:This technique passes samples through 0.45-micron membranes before incubating the retained microorganisms on culture media. Parenteral drug manufacturers in New Jersey and Pennsylvania corridors rely on membrane filtration for low-turbidity sterile injectables, though filter validation requirements extend method suitability studies.
- Rapid Sterility Tests:ATP bioluminescence and PCR-based platforms detect microbial contamination within 24-72 hours versus traditional 14-day cycles. Massachusetts cell therapy producers are mandating these platforms for autologous product release, where patient treatment windows compress quality control timelines.
- Direct Inoculation:Samples transfer directly into culture media without filtration, serving high-turbidity or oil-based formulations that clog membrane apparatus.
- Test for Aseptic Conditions:Environmental monitoring protocols validate cleanroom and isolator integrity through settle plates, contact plates, and active air sampling.
Membrane filtration absorbs the bulk of installed capacity; rapid sterility tests are expanding most quickly.
Product Type:
Product complexity determines sterility assurance level requirements, with biological materials demanding enhanced detection sensitivity compared to conventional small-molecule formulations.
- Injectables:Sterile solutions, suspensions, and emulsions administered parenteral require USP Chapter 71 compliance with 14-day incubation protocols or validated rapid alternatives. California's San Francisco Bay Area biotech cluster concentrates demand for high-throughput sterility validation supporting clinical-to-commercial transitions.
- Biological Products:Cell therapies, gene therapies, and recombinant proteins carry elevated bioburden risk from living production systems. North Carolina's Research Triangle manufacturers are building dedicated rapid sterility capabilities to match autologous therapy production cadences.
- Medical Devices:Implants, surgical instruments, and combination products follow ISO 11737 validation standards with sterility assurance levels typically set at 10^-6.
- Others:Ophthalmic preparations, inhalation products, and topical formulations occupy niche validation categories with method-specific suitability requirements.
Injectables command the deepest validation expertise; biological products are climbing the fastest as advanced therapy manufacturing scales.
End User:
End-user concentration tracks the geographic clustering of pharmaceutical manufacturing and the outsourcing decisions that partition testing between captive and contract laboratories.
- Pharmaceutical Manufacturers:Large parenteral producers in the Northeast corridor maintain internal sterility laboratories for routine release testing, capturing margin through vertical integration of quality control functions.
- Contract Research Organizations:CDMOs in Texas and North Carolina biomanufacturing clusters are qualifying rapid sterility platforms to attract cell therapy sponsors seeking integrated manufacturing and testing services.
- Hospital Laboratories:Compounding pharmacies and hospital-based manufacturing operations perform sterility testing for patient-specific preparations under USP Chapter 797 guidelines.
- Quality Control Laboratories:Independent testing facilities serve generic injectables manufacturers and medical device producers requiring ISO 17025-accredited microbiology capabilities.
Pharmaceutical manufacturers retain the largest captive capacity; contract research organizations are gaining share fastest through advanced therapy specialization.
Technology:
Technology segmentation captures the platform transition from growth-dependent detection to molecular and automated systems, with capital intensity filtering adoption by organization scale.
- Traditional Methods:Growth-based detection on liquid and solid culture media remains the compendial reference standard for FDA submissions. Generic injectables producers in the Midwest rely on these methods for cost-sensitive quality control protocols.
- Automated Systems:Robotic sample handling and incubation monitoring reduce human intervention while strengthening data integrity compliance. Large-scale parenteral manufacturers are refreshing instrument-installed bases to align with FDA's data integrity guidance.
- PCR Technology:Polymerase chain reaction amplifies microbial DNA for detection below traditional culture limits, supporting rapid release for time-sensitive biologics.
- Next-Generation Sequencing:Metagenomic approaches identify contaminant species without cultivation, enabling root-cause investigation of sterility failures in complex manufacturing environments.
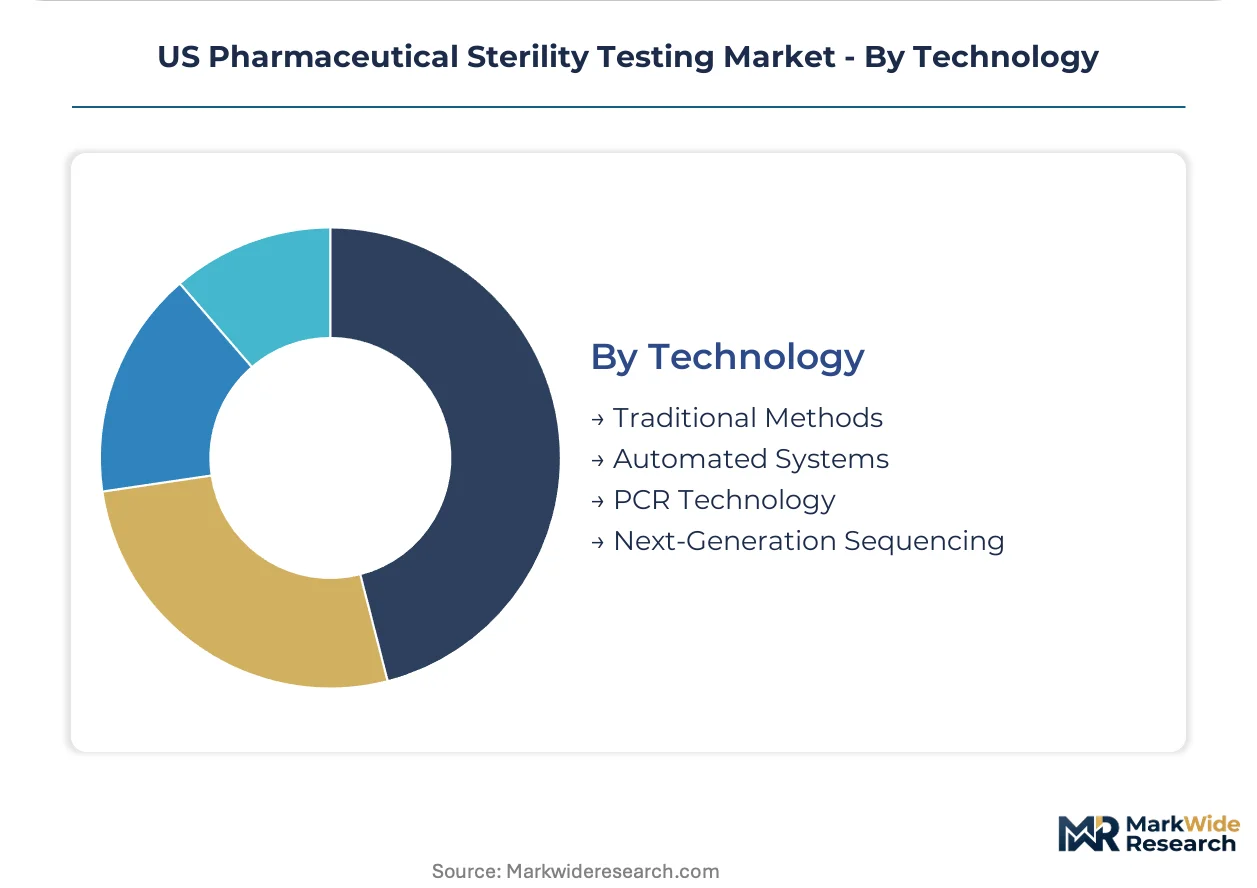
Traditional methods retain the widest installed base; automated systems are seeing the steepest expansion trajectory as laboratories modernize for compliance and throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US pharmaceutical sterility testing demand clusters in coastal biomanufacturing corridors and emerging Sun Belt production zones, with FDA regulatory proximity shaping laboratory qualification intensity across state boundaries.
Northeast Corridor
Massachusetts and New Jersey harbor the densest concentration of cell therapy manufacturers and sterile injectables producers. FDA's Boston district office maintains stringent inspection protocols for rapid microbiological method validations. Cambridge and Worcester biotech clusters are mandating ATP bioluminescence platforms for autologous therapy release timelines.
California
The San Francisco Bay Area and San Diego anchor gene therapy manufacturing scale-up. California's Office of Environmental Health Hazard Assessment imposes supplementary biosafety laboratory standards beyond federal baselines. South San Francisco contract testing organizations are qualifying single-source rapid sterility providers for clinical-to-commercial transitions.
North Carolina
The Research Triangle Park corridor attracts advanced therapy CDMOs seeking integrated manufacturing and testing services. North Carolina's biotechnology center tax credits subsidize sterility infrastructure investments. Durham and Raleigh laboratories are building dedicated rapid validation capabilities to match autologous therapy production cadences.
Texas
Houston and Dallas-Fort Worth biomanufacturing clusters remain underpenetrated for rapid sterility validation services. Texas Enterprise Fund incentives support pharmaceutical manufacturing facility buildouts. The Texas Medical Center ecosystem is incubating contract microbiology laboratories serving emerging cell therapy sponsors.
Midwest
Illinois and Ohio generic injectables producers rely on traditional growth-based methods for cost-sensitive quality control. FDA's Chicago district office maintains active surveillance of compendial method compliance. Indianapolis and Cleveland manufacturing sites prioritize instrument refresh cycles over rapid platform adoption.
US Pharmaceutical Sterility Testing Market Key Industry Players
Northeast-based laboratory networks anchor one tier; European and diversified North American specialists hold differentiated positions through accreditation breadth and technology platform breadth. The vendor base organizes around three strategic archetypes: integrated safety testing conglomerates, pure-play microbiology laboratories, and diversified analytical services platforms. Consolidation pressure intensifies as large pharmaceutical manufacturers unbundle sterility testing from broader safety portfolios. Capacity expansion and rapid method technology licensing constitute the dominant competitive vectors.
Among integrated testing conglomerates, Charles River Laboratories and Thermo Fisher Scientific exemplify archetypes leveraging biologics safety footprints and instrument-installed base advantages respectively. SGS SA occupies a position emphasizing geographic coverage through ISO 17025-accredited laboratory networks. These three entities represent the scale-driven, technology-anchored, and accreditation-breadth competitive positions within the market structure.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Thermo Fisher Scientific |
| SGS SA |
| Laboratory Corporation of America Holdings |
| STERIS |
| Pacific Biolabs |
| Boston Analytical |
| Pace Analytical |
| Nelson Laboratories |
| Others |
Cost & Logistics Intelligence
Microbiology talent scarcity in the Massachusetts and New Jersey corridors widens pricing spreads between rapid-method specialists and traditional growth-based laboratories, compressing margins in the standard tier while premium ATP bioluminescence validation commands sustained rate premiums.
Pricing Analysis
Volume concentrates in membrane filtration services while margins accrue to rapid sterility platforms. Three-tier pricing structure across premium rapid-method, standard automated, and economy manual levels reflects certification intensity and release-speed guarantees. Price differentiation hinges on ISO 17025 accreditation tier and FDA equivalence study documentation. Pricing pressure stems from instrument capital intensity forcing amortization across higher volumes. Generic injectables manufacturers in the Midwest exhibit highest price sensitivity; cell therapy sponsors in California corridors demonstrate lowest sensitivity due to patient-treatment-window constraints.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese suppliers of ATP bioluminescence detection reagents and automated incubation systems. Consumables draw from specialized fermentation media producers in the United States and European Union. Equipment sourcing rests on precision robotics manufacturers in Switzerland and South Korea. Tariff exposure on analytical instruments creates margin compression for laboratory buildouts. Distribution runs through direct manufacturer relationships with large parenteral producers, supplemented by regional distributor networks serving independent quality control laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as sterile injectables producers build captive rapid-method capabilities to capture release-timeline advantages and protect proprietary biologics data.
For Market Incumbents: Lock in rapid-method validation expertise through targeted hiring of FDA-equivalence specialists in the Northeast corridor, insulating against ATP bioluminescence platform commoditization. Expand ISO 17025-accredited capacity in Texas and North Carolina biomanufacturing clusters before CDMOs establish competing rapid sterility infrastructure. Anchor relationships with gene therapy sponsors through integrated clinical-to-commercial testing programs. For New Entrants and Emerging Players: Digital-channel partnerships with laboratory information management system vendors offer lower-friction entry points than direct sales to consolidated pharmaceutical manufacturers. Target underpenetrated Texas medical center ecosystems with rapid-turnaround sterility services for emerging cell therapy sponsors. Differentiate through 24-hour ATP bioluminescence release guarantees backed by dedicated validation scientist assignments. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale microbiology laboratories possessing existing ISO 17025 frameworks and rapid-method validation capabilities given FDA's sterility test modernization initiative. Long-term viability favors platforms with demonstrated equivalence study portfolios and geographic proximity to Massachusetts and California biotech clusters. Monitor FDA guidance publication velocity as inflection indicator for capital deployment timing into rapid-method infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Rapid Method Validation Group Establishment | Biologics manufacturers with internal QC laboratories are building dedicated teams to manage FDA equivalence study requirements. |
| ISO 17025 Accreditation Expansion | Contract testing organizations are extending certified laboratory networks to capture cell therapy CDMO outsourcing decisions. |
| Automated System Refresh Cycles | Large parenteral manufacturers are upgrading instrument-installed bases to align with FDA data integrity guidance. |
| Single-Source Rapid Sterility Qualification | Gene therapy sponsors in California are consolidating testing relationships for clinical-to-commercial transitions. |
| Geographic Cluster Capacity Buildout | Laboratories are establishing rapid validation capabilities in Texas and North Carolina to match autologous therapy production cadences. |
Research Approach
Document review covered FDA guidance publications, USP Chapter 71 compendial standards, and ISO 11737 validation protocols, complemented by interviews with regulatory affairs leads at biologics manufacturers, quality control directors at contract testing organizations, and microbiology laboratory managers. Secondary validation drew from FDA 483 inspection observations, laboratory accreditation databases, and pharmaceutical manufacturing facility investment disclosures. Bottom-up demand modeling triangulated against top-down market sizing from industry association reports.
Historical capacity deployment patterns cross-referenced against expert panel input on rapid microbiological method adoption timelines shaped the analytical framework. Segmentation modeling captured testing method, product type, end-user category, and technology platform dimensions alongside regional regulatory cluster intensity. CAGRs derived from weighted scenario analysis incorporating biologics pipeline expansion rates and FDA equivalence study completion velocities. Forecast inputs included cell therapy manufacturing capacity announcements and IRA manufacturing credit utilization patterns.
The model holds under continued FDA preference for compendial reference method equivalence; deviation in rapid method validation acceptance thresholds or ISO 17025 accreditation processing timelines would shift capacity expansion trajectories. Forecasts reflect documented assumptions regarding biologics manufacturing growth and regulatory guidance evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Sports Drug Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Drug Testing Equipment Market
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Retrovirus Testing Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
STD Testing Devices Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Point of Care Testing Market
Testing Services
US at-Home Testing Kits Market