
 Electrophysiology Equipment and Recording Systems Market | 2026-2036
Electrophysiology Equipment and Recording Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electrophysiology Equipment and Recording Systems Market Foresight
A shortage of board-certified electrophysiologists is redrawing competitive dynamics across developed healthcare systems. Abbott Laboratories leverages its integrated catheter and mapping portfolio to capture complex ablation workflows. Medtronic sustains technology leadership through deep investments in robotic navigation platforms. Boston Scientific Corporation anchors its position in Europe with specialized cryoablation catheter lines.
Electrophysiology equipment and recording systems encompass cardiac mapping platforms, multichannel signal amplifiers, and ablation energy generators designed to acquire, process, and display intracardiac electrical signals with microvolt precision during diagnostic or therapeutic catheter procedures. These systems enable real-time three-dimensional reconstruction of cardiac anatomy alongside electrogram interpretation to guide targeted tissue modification. Mapping systems command premium pricing due to software complexity and recurring catheter attachment revenues, while stimulators represent a mature hardware segment with slower replacement cycles. Electrophysiology catheters generate the highest absolute revenue pool because of single-use economics and expanding ablation procedure volumes across hospital settings.
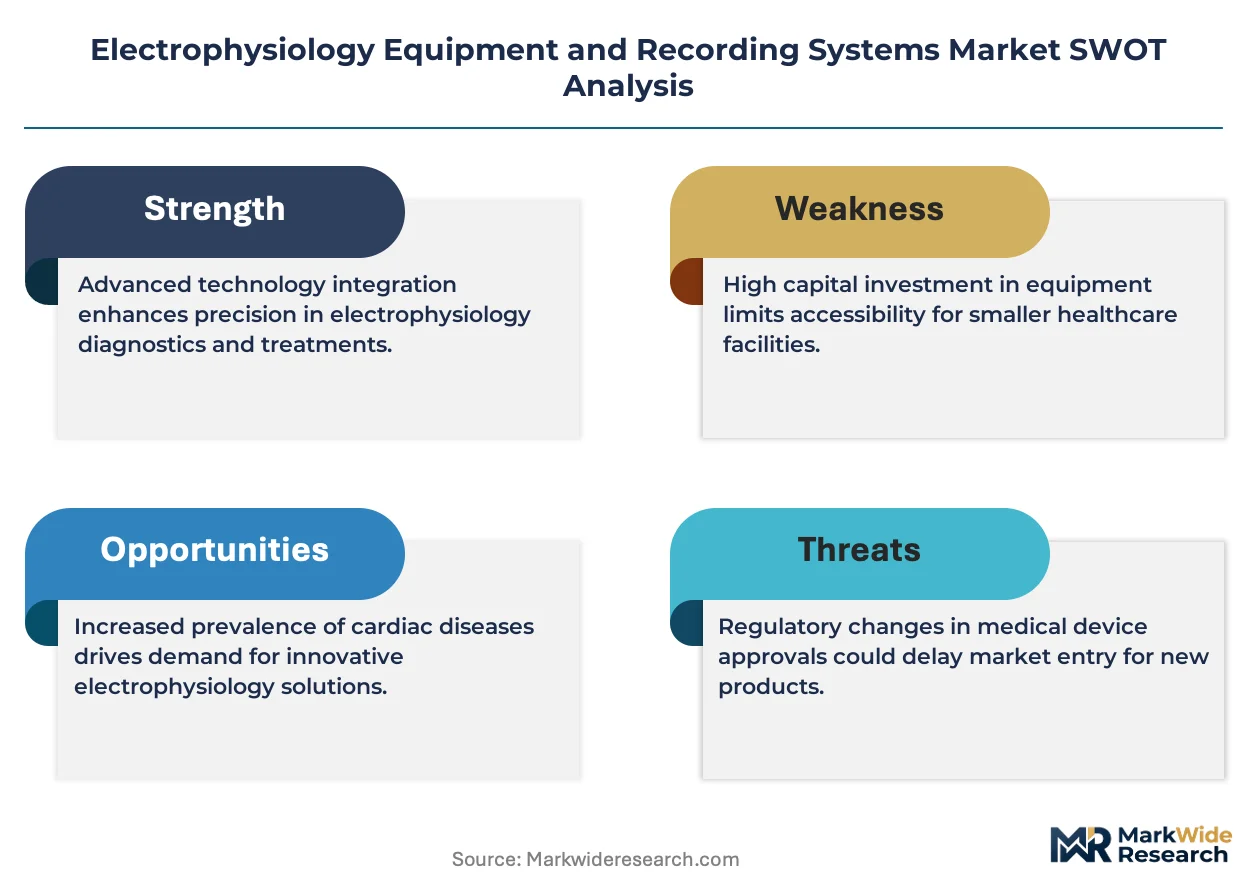
FDA premarket approval pathways, EU MDR conformity assessment frameworks, and Japan PMDA quality management standards collectively elevate clinical evidence and post-market surveillance burdens for device manufacturers seeking multi-regional commercialization. Regulators increasingly require randomized trial data for novel ablation modalities, extending development timelines and favoring established players with robust quality systems. Stakeholders must monitor evolving reimbursement decisions for pulsed field ablation and magnetic navigation technologies across major healthcare systems.
Market Dynamics
Pulsed field ablation technology is compressing procedure times and redrawing capital equipment replacement cycles across hospital electrophysiology departments. This energy modality eliminates thermal collateral damage while enabling faster lesion formation, forcing mapping system vendors to integrate real-time impedance feedback protocols.
Growth Catalysts
- Japan PMDA fast-track pathways:Expedited approval timelines for catheter platforms with demonstrated safety profiles accelerate commercial entry for novel ablation technologies in Japanese tertiary centers.
- Catheter-based ablation volume expansion:Hospital electrophysiology labs in Germany and the United States are scaling procedural throughput as atrial fibrillation patient cohorts age and symptomatic burden thresholds for intervention decline.
- Robotic navigation integration:Magnetic and mechanical steering platforms reduce fluoroscopy exposure and operator fatigue, expanding treatable patient anatomies including complex atrial flutter substrates.
Market Restraints
- MDR conformity assessment bottlenecks:Extended EU notified body review timelines for Class III electrophysiology devices delay market entry and inflate regulatory compliance costs for European commercialization.
- Palladium and platinum supply concentration:Electrode tip manufacturing depends on Russian and South African precious metal refining capacity, exposing catheter producers to price volatility and potential supply interruption.
- Radiofrequency generator commoditization:Mature hardware platforms face replacement cycle extension as hospital capital budgets prioritize mapping system upgrades over stimulator refreshes.
Strategic Opportunities
- Underpenetrated Indian electrophysiology infrastructure:Tier-2 and Tier-3 cities lack dedicated cardiac electrophysiology labs, creating greenfield installation demand for integrated mapping and ablation platforms as domestic cardiology training programs expand.
- Hybrid operating room convergence:Surgical electrophysiology suites combining epicardial access with endocardial catheter navigation enable combined procedures for persistent atrial fibrillation and ventricular tachycardia storm management.
- Reimbursement stabilization for complex ablation:United States CMS coding updates and German DRG refinements for pulmonary vein isolation with advanced mapping support procedure economics for high-acuity cases.
Industry Challenges
- Electrophysiologist training pipeline constraints:Fellowship positions fail to match procedural volume growth, creating procedural backlogs and forcing hospitals to rely on visiting proctors for complex case coverage.
- Legacy system interoperability friction:Proprietary data formats between mapping platforms from different manufacturers block seamless electrogram exchange and complicate multi-vendor lab configurations.
- Catheter sterility assurance validation:Reprocessing qualification for certain electrode designs faces FDA scrutiny, threatening single-use economics and supply security for high-volume ablation centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrophysiology Equipment and Recording Systems Market |
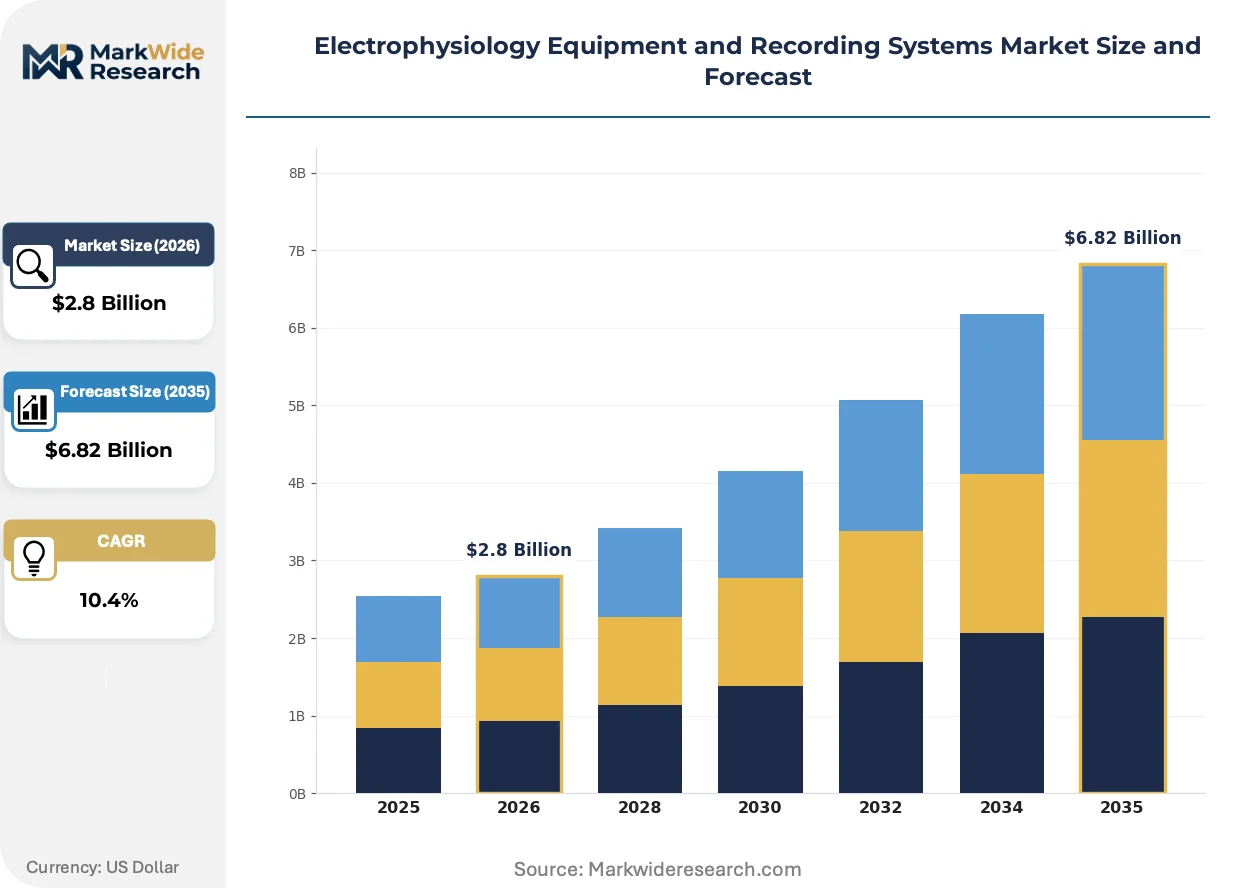
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.82 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrophysiology Catheters, Recording Systems, Mapping Systems, Stimulators Application: Arrhythmia Management, Cardiac Ablation, Diagnostic Tests, Research End User: Hospitals, Cardiology Clinics, Research Labs, Ambulatory Surgical Centers Technology: 3D Mapping, Electrode Technology, Robotic Navigation, Signal Processing |
| Companies Covered | Abbott Laboratories, Medtronic, Boston Scientific Corporation, Johnson & Johnson, Biotronik, Koninklijke Philips, GE Healthcare, AtriCure, Acutus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrophysiology Equipment and Recording Systems Market Shifts & Advancements
Real-time computational modeling and contact-force sensing are converging to enable lesion prediction rather than retrospective assessment. This capability shift demands software architecture overhaul and positions cloud-based electrogram repositories as competitive differentiators.
Contact-force sensing catheters with integrated temperature compensation are bifurcating the ablation catheter market into premium precision instruments and economy-oriented conventional designs. Academic medical centers in the United States and Germany are standardizing force-guided workflows for pulmonary vein isolation, while community hospitals retain conventional platforms for simpler flutter ablations. This segmentation is bifurcating vendor sales strategies and service contract structures across account tiers.
FDA premarket approval pathways for novel energy modalities now mandate randomized controlled trial evidence against established thermal ablation, extending development timelines and elevating clinical evidence costs. The agency's heightened scrutiny of durable pulmonary vein isolation claims compresses labeling flexibility for emerging platforms. Pulsed field ablation manufacturers are responding with large-scale sham-controlled studies and extended follow-up protocols to satisfy this evidentiary threshold.
Hospital purchasing consortia are consolidating electrophysiology equipment procurement across integrated delivery networks, displacing individual hospital vendor relationships with multi-year enterprise agreements. This concentration shifts negotiation leverage toward standardized platform commitments and bundled catheter supply contracts. The phenomenon is most pronounced in United States health systems exceeding twenty hospitals, where mapping system standardization reduces training variability and inventory complexity.
Electrophysiology Equipment and Recording Systems Market Segmentation
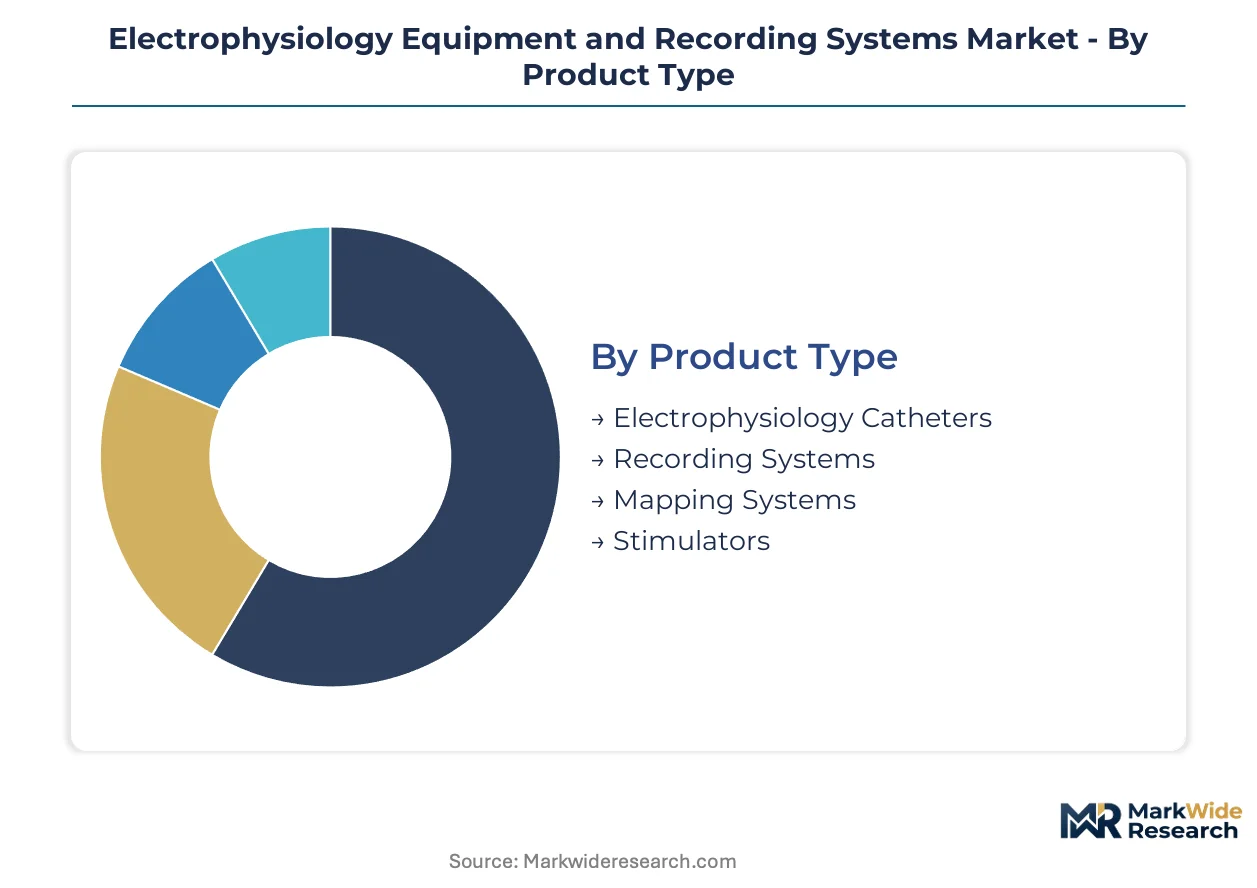
Electrophysiology equipment segmentation reveals distinct procurement patterns across hospital systems, academic centers, and outpatient facilities. Each category carries specific technical requirements, regulatory pathways, and replacement economics that shape vendor positioning and pricing architecture.
Product Type:
Domestic production concentrates on stimulators and base recording hardware, while mapping systems and advanced catheters flow through import-dependent supply chains concentrated in the United States, Germany, and Japan.
- Electrophysiology Catheters:Single-use devices with electrode arrays at distal tips deliver radiofrequency, cryothermal, or pulsed field energy to cardiac tissue. Demand clusters in United States tertiary centers performing high-volume atrial fibrillation ablations, driven by single-use economics and expanding procedure volumes. Reimbursement stability for complex ablation supports premium pricing for contact-force sensing variants.
- Mapping Systems:Three-dimensional electroanatomical platforms reconstruct cardiac anatomy from electromagnetic location data and intracardiac electrograms. German and Japanese hospitals lead replacement cycles for integrated systems combining magnetic navigation with real-time imaging. Software complexity and proprietary catheter interfaces create substantial switching costs for installed accounts.
- Recording Systems:Multichannel amplifiers acquire and filter intracardiac signals with microvolt precision during diagnostic procedures. Community hospitals in the United States prioritize cost-effective upgrades over full platform replacements.
- Stimulators:Programmable pulse generators deliver controlled electrical stimuli for arrhythmia induction and conduction system assessment. Mature hardware segment faces extended replacement intervals as capital budgets shift toward mapping technology.
Mapping systems command the established base. The steepest expansion runs through electrophysiology catheters.
Application:
Cost tier differentiation separates capital-intensive therapeutic procedures from diagnostic workflows and research applications with variable funding streams.
- Arrhythmia Management:Comprehensive care pathways encompassing diagnosis, risk stratification, and long-term rhythm monitoring for atrial and ventricular arrhythmias. United States integrated delivery networks standardize device selection across electrophysiology service lines to reduce training overhead and inventory complexity.
- Cardiac Ablation:Catheter-based tissue modification to isolate arrhythmia substrates, primarily pulmonary vein isolation for atrial fibrillation. German DRG refinements and United States CMS coding updates stabilize procedure economics for high-acuity cases requiring advanced mapping support.
- Diagnostic Tests:Electrophysiology studies to characterize conduction abnormalities and guide treatment decisions. Cardiology clinics in Japan leverage PMDA fast-track pathways to adopt novel catheter platforms with demonstrated safety profiles.
- Research:Investigational applications in academic medical centers exploring novel energy modalities and computational modeling. Funding concentration in National Institutes of Health grant recipients and European Research Council awardees creates geographic demand clustering.
Cardiac ablation anchors revenue concentration. Research applications are gaining share fastest through academic-industry collaboration frameworks.
End User:
Customer type determines procurement leverage, with consolidated hospital systems extracting volume discounts unavailable to standalone cardiology clinics.
- Hospitals:Tertiary and community facilities with dedicated electrophysiology labs performing diagnostic and therapeutic procedures. United States health systems exceeding twenty hospitals increasingly mandate enterprise-wide platform standardization to reduce training variability.
- Cardiology Clinics:Outpatient facilities specializing in arrhythmia diagnosis and device management. Tier-2 and Tier-3 cities in India lack dedicated electrophysiology infrastructure, creating greenfield installation demand as domestic cardiology training programs expand.
- Research Labs:Academic and industry facilities investigating electrophysiology mechanisms and device performance. Equipment procurement depends on grant funding cycles and institutional core facility budgets.
- Ambulatory Surgical Centers:Outpatient settings performing selected diagnostic electrophysiology studies and simple ablation procedures. Reimbursement differential versus hospital-based sites shapes equipment configuration choices toward cost-optimized platforms.
Hospitals retain the dominant installed base. Ambulatory surgical centers are climbing the fastest as site-of-care migration accelerates for selected procedures.
Technology:
Supply concentration for critical components—palladium and platinum for electrode tips, specialized magnetic sensors—exposes manufacturers to price volatility and potential interruption.
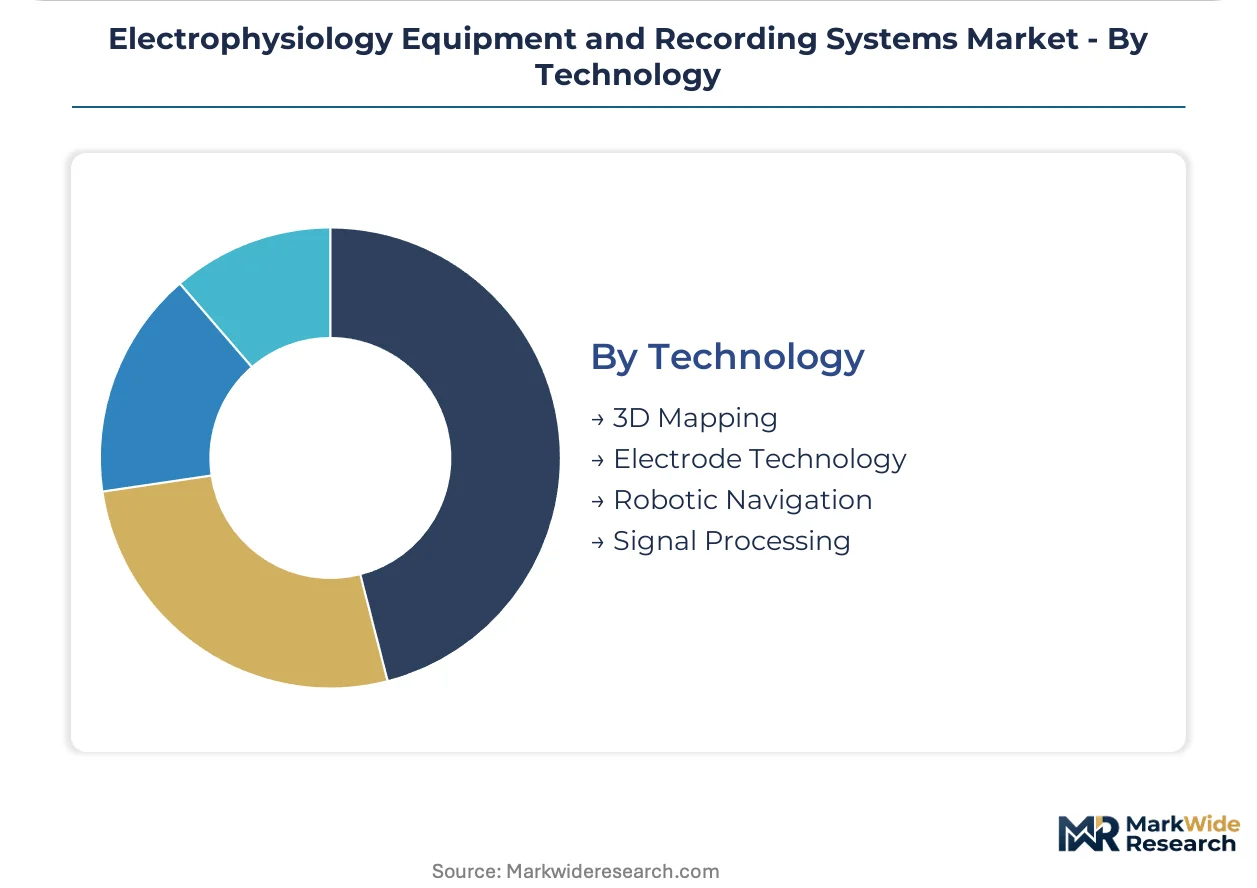
- 3D Mapping:Electromagnetic tracking systems enabling real-time three-dimensional cardiac reconstruction with submillimeter spatial resolution. Integration demands with robotic navigation platforms and imaging systems create complex vendor ecosystem dependencies.
- Electrode Technology:Materials science and microfabrication advances for catheter tip design, including contact-force sensing and temperature compensation. Russian and South African precious metal refining capacity concentrates supply risk for high-performance electrode production.
- Robotic Navigation:Magnetic and mechanical steering platforms reducing fluoroscopy exposure and operator fatigue during complex procedures. FDA premarket approval pathways mandate randomized controlled trial evidence against manual catheter manipulation, extending development timelines.
- Signal Processing:Computational algorithms for real-time electrogram interpretation, artifact rejection, and arrhythmia classification. Cloud-based electrogram repositories emerge as competitive differentiators requiring substantial software architecture investment.
Electrode technology secures the established revenue base. Pulsed field ablation integration is driving the steepest technology transition across mapping platform roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways anchor the United States as the dominant geography, where CMS reimbursement decisions cascade across hospital purchasing cycles and shape vendor platform standardization strategies.
United States
Integrated delivery networks exceeding twenty hospitals mandate enterprise-wide mapping system standardization to reduce training variability. CMS coding updates for pulmonary vein isolation with advanced mapping support procedure economics. The Cleveland Clinic and Mayo Clinic anchor academic-industry collaboration frameworks for novel energy modality validation.
Germany
DRG refinements for complex ablation stabilize hospital reimbursement for high-acuity pulmonary vein isolation cases. EU MDR conformity assessment frameworks extend notified body review timelines for Class III electrophysiology devices. The Rhine-Ruhr metropolitan cluster concentrates catheter-based ablation volume expansion across tertiary electrophysiology labs.
Japan
PMDA fast-track pathways accelerate commercial entry for catheter platforms with demonstrated safety profiles in Japanese tertiary centers. METI industrial policy supports domestic cardiology training program expansion. The Kanto region surrounding Tokyo hosts the highest density of dedicated electrophysiology labs performing diagnostic and therapeutic procedures.
India
Tier-2 and Tier-3 cities lack dedicated cardiac electrophysiology infrastructure, creating greenfield installation demand for integrated mapping and ablation platforms. CDSCO regulatory pathways for imported Class III devices require local clinical bridging studies. Maharashtra and Karnataka anchor domestic cardiology fellowship expansion programs training the next electrophysiologist cohort.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex ablation procedures at designated cardiac centers with advanced mapping capability. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment timelines for novel catheter platforms. The London-Southeast corridor concentrates academic medical center research funding for computational electrophysiology modeling.
Electrophysiology Equipment and Recording Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the electrophysiology equipment sector. The market structure consolidates around diversified medical technology conglomerates with integrated catheter and mapping portfolios, while specialized navigation platform developers occupy niche positions. Three archetypes dominate: full-solution providers with proprietary catheter-system integration, robotic navigation specialists with magnetic steering platforms, and cryoablation-focused vendors with differentiated energy delivery. Competitive moves center on multi-year enterprise purchasing agreements with hospital consortia and software architecture investments for cloud-based electrogram repositories.
Among diversified medical technology conglomerates, Abbott Laboratories and Medtronic exemplify full-solution providers with integrated portfolios spanning catheters, mapping systems, and energy generators. Boston Scientific Corporation occupies a position within the specialized therapeutic catheter tier, particularly anchored in cryoablation platform development. These three entities represent the dominant competitive anchors shaping hospital standardization decisions and vendor ecosystem configurations across major healthcare systems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Biotronik |
| Koninklijke Philips |
| GE Healthcare |
| AtriCure |
| Acutus Medical |
| Others |
Supply & Pricing Matrix
Ninety-to-one-hundred-twenty-day lead times for Class III electrophysiology device imports from the United States and Germany concentrate pricing power with established vendors possessing validated EU MDR quality systems and FDA-compliant manufacturing infrastructure. Hospital purchasing consortia exploit extended replacement cycles for stimulators and recording systems to negotiate bundled catheter supply contracts that compress margins on mature hardware while preserving premium capture for integrated mapping platforms.
Pricing Analysis
United States tertiary centers pay premium multiples over Indian Tier-2 hospitals for identical contact-force sensing catheter configurations. The market runs on a hybrid pricing structure combining capital equipment leases with per-procedure catheter consumption contracts. Price differentiation rests on FDA PMA tier versus CE Mark conformity level and after-sales field service bundling. Cost compression in the stimulator segment is intensifying because hospital capital budgets prioritize mapping system upgrades. Community hospitals exhibit highest price sensitivity; academic medical centers with NIH funding streams show lowest.
Supply Chain Analysis
Sixty-day inventory buffers for palladium and platinum electrode tip feedstock expose catheter manufacturers to spot price volatility from Russian and South African refining capacity. Manufacturing concentrates in the United States, Germany, and Ireland for final assembly of Class III devices. Raw material dependencies span precious metal electrodes, specialized magnetic sensors, and medical-grade polymers. Single-source vulnerability runs through South African platinum group metal supply. Distribution runs through hospital purchasing consortia and specialized cardiovascular device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulsed field ablation technology threatens to displace thermal energy modalities, forcing incumbents to defend installed base economics against faster procedure times and reduced catheter consumption per case.
For Market Incumbents: Fortify proprietary catheter-system interfaces to increase switching costs for hospital accounts evaluating multi-vendor configurations. Deepen backward integration into electrode tip manufacturing to hedge palladium supply volatility. Lock in multi-year enterprise agreements with United States health systems exceeding twenty hospitals before PFA platforms achieve full reimbursement parity. For New Entrants and Emerging Players: Cloud-based electrogram repository services represent an under-served layer where Abbott and Medtronic under-invest relative to hardware development. Target Tier-2 Indian cities lacking dedicated electrophysiology infrastructure for greenfield platform installation. Pursue CDSCO regulatory partnerships with domestic cardiology training programs to accelerate clinical adoption curves. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because electrophysiologist training pipeline constraints and MDR conformity bottlenecks favor scaled quality systems over venture-stage innovation. Target acquisition candidates with validated robotic navigation platforms and established EU notified body relationships. Monitor FDA PMA approval timelines for novel PFA systems as inflection signal for thermal ablation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Randomized controlled trial mandates against thermal ablation extend development timelines and elevate clinical evidence costs for emerging PFA platforms. |
| EU MDR Conformity Assessment | Extended notified body review timelines for Class III devices delay market entry and inflate compliance expenditures for European commercialization. |
| Hospital System Partnership | Enterprise-wide platform standardization across United States integrated delivery networks reduces training variability and locks in recurring catheter revenues. |
| Software Companion Development | Cloud-based electrogram repositories with real-time computational modeling differentiate mapping platforms and create recurring SaaS revenue streams. |
| Reimbursement Strategy | CMS coding updates and German DRG refinements for pulmonary vein isolation stabilize procedure economics for high-acuity cases requiring advanced mapping. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineering directors, and GPO contracts managers. Secondary validation drew from FDA PMA filings, EUDAMED conformity assessment records, CMS Medicare claims data, and hospital procurement databases. Bottom-up procedure volume modeling triangulated against top-down equipment installation estimates across the analysis window.
Across the projection horizon, the analytical framework segmented revenue by product type, application, end user, and technology tier. CAGRs derived from logistic diffusion curves for novel energy modalities and replacement cycle elasticity for mature hardware segments. Forecast inputs incorporated PMDA fast-track pathway utilization rates and electrophysiologist fellowship completion trajectories.
Underlying assumptions cover reimbursement stability for complex ablation and precious metal supply continuity, with deviation risk concentrated in EU MDR notified body capacity constraints and FDA evidentiary threshold elevation for novel energy platforms. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
Autoclaves Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
Global Medical Vacuum System Market