
 United Kingdom Remote Patient Monitoring Market | 2026-2036
United Kingdom Remote Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Remote Patient Monitoring Market Insights
NHS workforce shortages in community nursing is rotating investment toward automated vital-sign capture and algorithm-driven triage. Philips leverages its Sleep and Respiratory Care division to sustain dominance in continuous glucose and cardiac monitoring for Type 1 diabetes patients. Medtronic anchors its UK position through the MyDataHelps platform, which integrates with NHS Digital's interoperability standards. Teladoc Health competes via its chronic care management offering, recently contracted by several integrated care boards in the Midlands.
Remote patient monitoring encompasses wearable biosensors, connected inhalers, implantable cardiac devices, and cloud-based telemetry systems that transmit physiological data to clinical teams without requiring physical presence. These systems typically operate through Bluetooth Low Energy or cellular modules paired with FDA-cleared or UKCA-marked hardware, enabling early detection of decompensation in heart failure, COPD, and post-acute surgical recovery. Wearable Devices and Monitoring Sensors command the largest installed base, though Telehealth Platforms capture disproportionate margin pools through recurring software licensing. Artificial Intelligence and Big Data Analytics represent the fastest-expanding technology layer, as predictive algorithms reduce false-alert fatigue and stratify patients by readmission risk.
The Care Quality Commission enforces digital health standards that mandate encrypted data transmission and audit trails for all patient-facing remote monitoring tools. NHS Digital's DTAC framework and the Medicines and Healthcare products Regulatory Agency's UKCA marking requirements create a dual-gate compliance structure that filters out uncertified vendors. Stakeholders must monitor how NHS England's forthcoming medtech funding mandates reshape procurement criteria for virtual ward infrastructure.
Market Dynamics
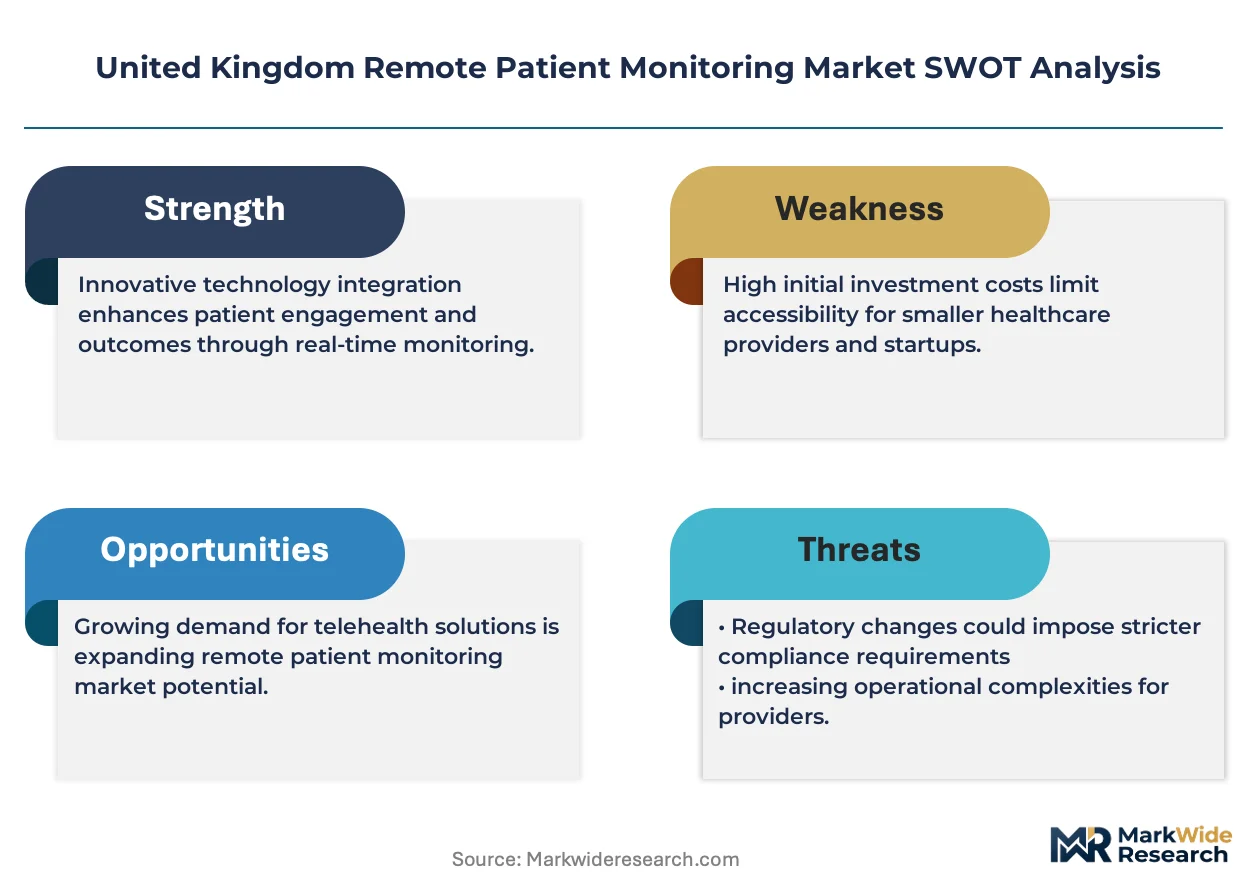
NHS England's virtual ward mandates are compressing deployment timelines for connected care infrastructure, forcing integrated care systems to absorb capital costs previously borne by acute trusts.
Growth Catalysts
- Workforce shortage automation:Community nursing vacancies exceeding 40,000 posts across England are accelerating investment in algorithm-driven triage systems that reduce clinical touchpoints.
- DTAC framework standardization:NHS Digital's Digital Technology Assessment Criteria creates procurement clarity that filters uncertified vendors and accelerates purchasing decisions.
- Cardiac implantable ecosystem expansion:Bluetooth-enabled pacemakers and implantable cardioverter-defibrillators are extending monitoring continuity from hospital to home settings.
Market Restraints
- UKCA marking transition friction:The Medicines and Healthcare products Regulatory Agency's post-Brexit conformity assessment requirements impose dual certification burdens on manufacturers holding CE marks.
- Cellular module supply concentration:Narrow sourcing of NB-IoT chipsets from East Asian foundries creates vulnerability in connected inhaler and wearable production schedules.
- Lithium battery chemistry constraints:Extended-life power requirements for implantable devices conflict with thermal safety thresholds in continuous glucose monitors.
Strategic Opportunities
- Greater Manchester health innovation cluster:Devolved health and care spending authority enables faster pilot-to-scale pathways for respiratory monitoring platforms.
- AI-augmented predictive analytics:Machine learning integration with continuous vital-sign streams is opening subscription revenue models beyond hardware sales.
- Social care integration mandates:The Health and Care Act 2022's pooled budget requirements are creating procurement channels that bypass traditional NHS supply routes.
Industry Challenges
- Interoperability engineering scarcity:Shortages of FHIR-standard developers are delaying integration with NHS Digital's Spine infrastructure.
- Data governance complexity:Care Quality Commission audit trail requirements for encrypted transmission are extending deployment timelines by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Remote Patient Monitoring Market |
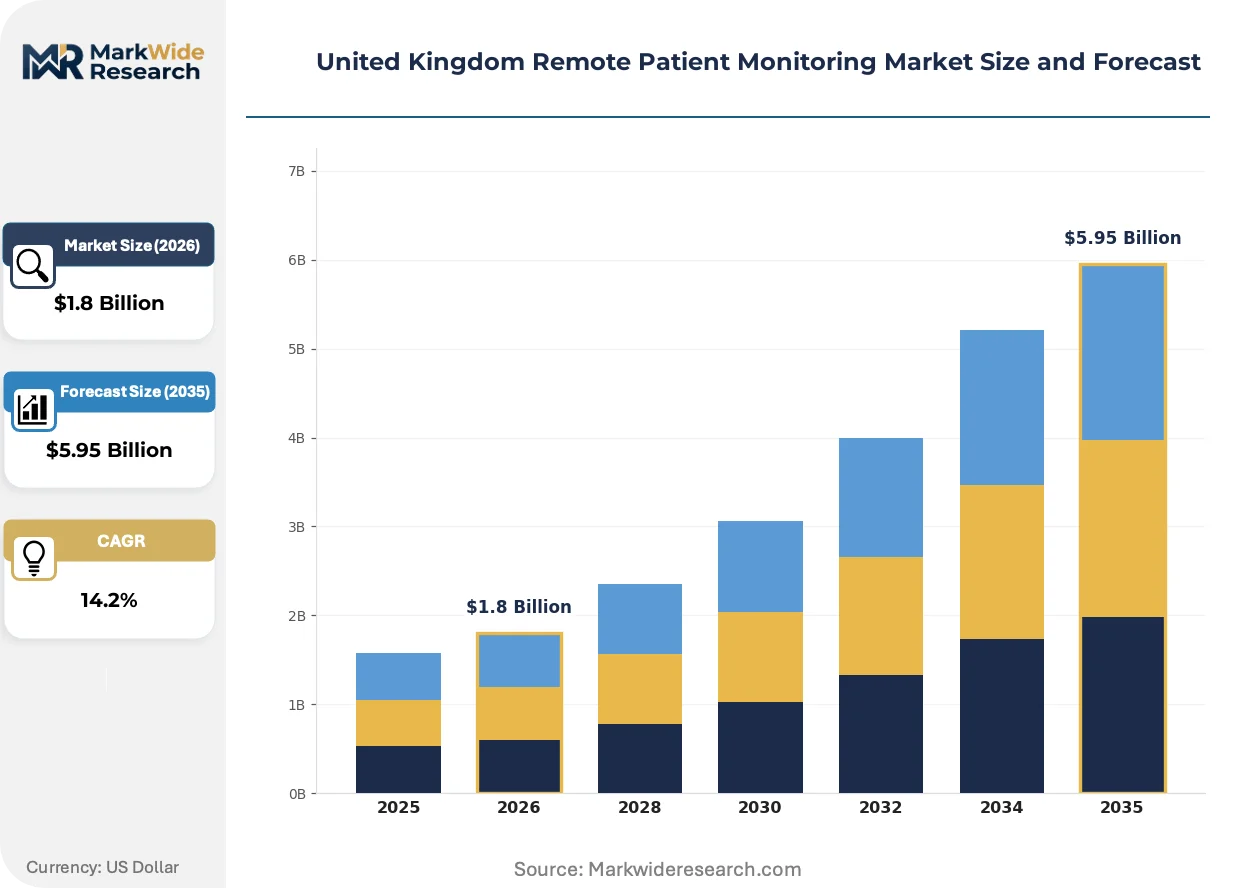
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Telehealth Platforms, Monitoring Sensors Technology: Cloud Computing, IoT, Artificial Intelligence, Big Data Analytics End User: Patients, Healthcare Providers, Family Caregivers, Insurance Companies Service Type: Real-time Monitoring, Data Analysis, Consultation Services, Emergency Alerts |
| Companies Covered | Abbott Laboratories, GE Healthcare, Boston Scientific Corporation, Koninklijke Philips, Medtronic, Becton Dickinson and Company, Johnson & Johnson, Dragerwerk, Teladoc Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Remote Patient Monitoring Market Trends and Innovations
Cloud-native telemetry architectures are displacing on-premise hospital servers, enabling real-time physiological data streaming without capital-intensive infrastructure.
Continuous glucose monitoring systems with factory-calibrated sensors are supplanting traditional finger-prick blood glucose meters among Type 1 diabetes cohorts. Integrated care boards in Greater London are mandating their inclusion in virtual ward protocols. This shift is compressing point-of-care testing revenue while expanding recurring consumable streams.
The Care Quality Commission's updated digital health standards now mandate end-to-end encryption for all patient-facing remote monitoring transmissions. Device manufacturers must demonstrate audit trail capabilities to maintain market access. Wearable biosensor vendors are responding by embedding hardware security modules at the chipset level.
Integrated care boards are consolidating purchasing authority previously distributed across acute trusts and primary care networks. This concentration is displacing fragmented procurement through NHS Supply Chain with direct vendor negotiations. The Midlands region exhibits the most advanced consolidation, with several boards operating unified remote monitoring frameworks.
United Kingdom Remote Patient Monitoring Market Segmentation
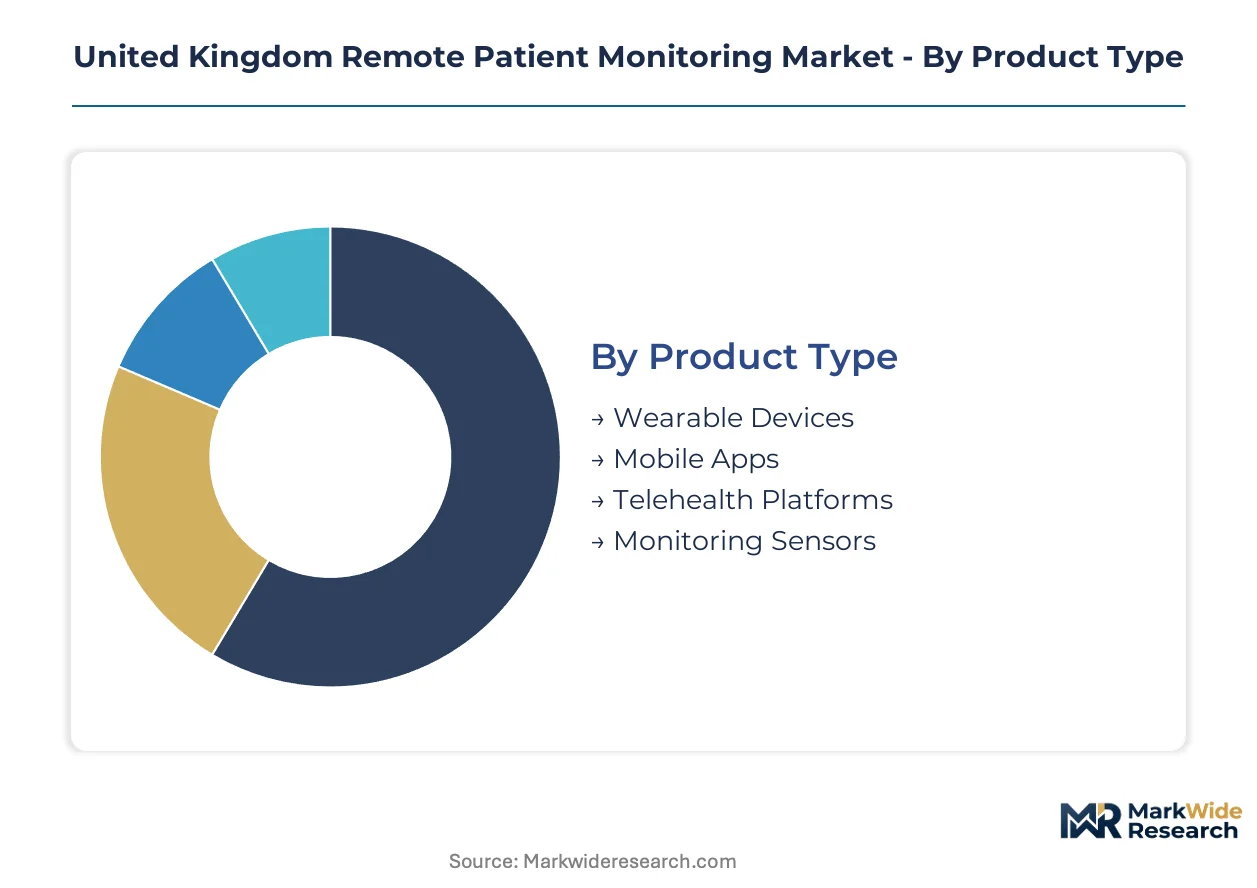
Segmentation in the United Kingdom Remote Patient Monitoring Market reveals distinct margin architectures across hardware, software, and service layers. Procurement authority consolidation within integrated care systems is reshaping which segments capture recurring revenue versus one-time device sales.
Product Type:
Margin pools concentrate in consumable sensor streams and platform licensing rather than capital hardware.
- Wearable Devices:Bluetooth Low Energy biosensors and wrist-worn vital-sign monitors transmit continuous physiological data. NHS England's virtual ward protocols in Greater London are mandating their inclusion in post-acute discharge bundles, compressing procurement cycles.
- Monitoring Sensors:Implantable cardiac devices and factory-calibrated glucose sensors generate recurring consumable revenue through replaceable transmitter units. The Care Quality Commission's encryption mandates are embedding hardware security modules at the chipset level, raising unit economics.
- Telehealth Platforms:Cloud-based telemetry dashboards integrate with NHS Digital's Spine infrastructure via FHIR standards.
- Mobile Apps:Patient-facing interfaces for medication adherence and symptom logging operate on smartphone ecosystems.
The dominant share belongs to Wearable Devices, while Monitoring Sensors is closing the gap fastest.
Technology:
Artificial Intelligence and predictive analytics command premium pricing through outcome-based contracting with integrated care boards.
- Artificial Intelligence:Machine learning algorithms stratify readmission risk and reduce false-alert fatigue in continuous vital-sign streams. Several Midlands integrated care boards have shifted to subscription pricing for AI-augmented triage capabilities.
- Big Data Analytics:Population health dashboards aggregate de-identified cohort data to identify deterioration patterns across virtual ward patient pools. The Health and Care Act 2022's pooled budget requirements are opening procurement channels beyond traditional NHS supply routes.
- Cloud Computing:Native telemetry architectures displace on-premise hospital servers, enabling real-time streaming without capital-intensive infrastructure.
- IoT:Cellular NB-IoT and Bluetooth Low Energy modules connect inhalers, patches, and implantables to clinical dashboards.
Cloud Computing holds the installed base advantage, though Artificial Intelligence is expanding most quickly through recurring software licensing.
End User:
Procurement authority is migrating toward healthcare providers as integrated care boards consolidate purchasing previously fragmented across acute trusts.
- Healthcare Providers:Integrated care systems and virtual ward teams purchase enterprise licenses for multi-patient dashboards. The Midlands region exhibits the most advanced consolidation, with several boards operating unified remote monitoring frameworks.
- Patients:Direct-to-consumer glucose monitors and cardiac event recorders bypass institutional procurement through pharmacy retail channels.
- Family Caregivers:Secondary account access in telehealth platforms enables remote oversight of elderly patient cohorts.
- Insurance Companies:Private medical insurers are piloting remote monitoring incentives to reduce claims frequency in chronic disease populations.
Healthcare Providers dominate current spending, while Insurance Companies are gaining share fastest through value-based care pilots.
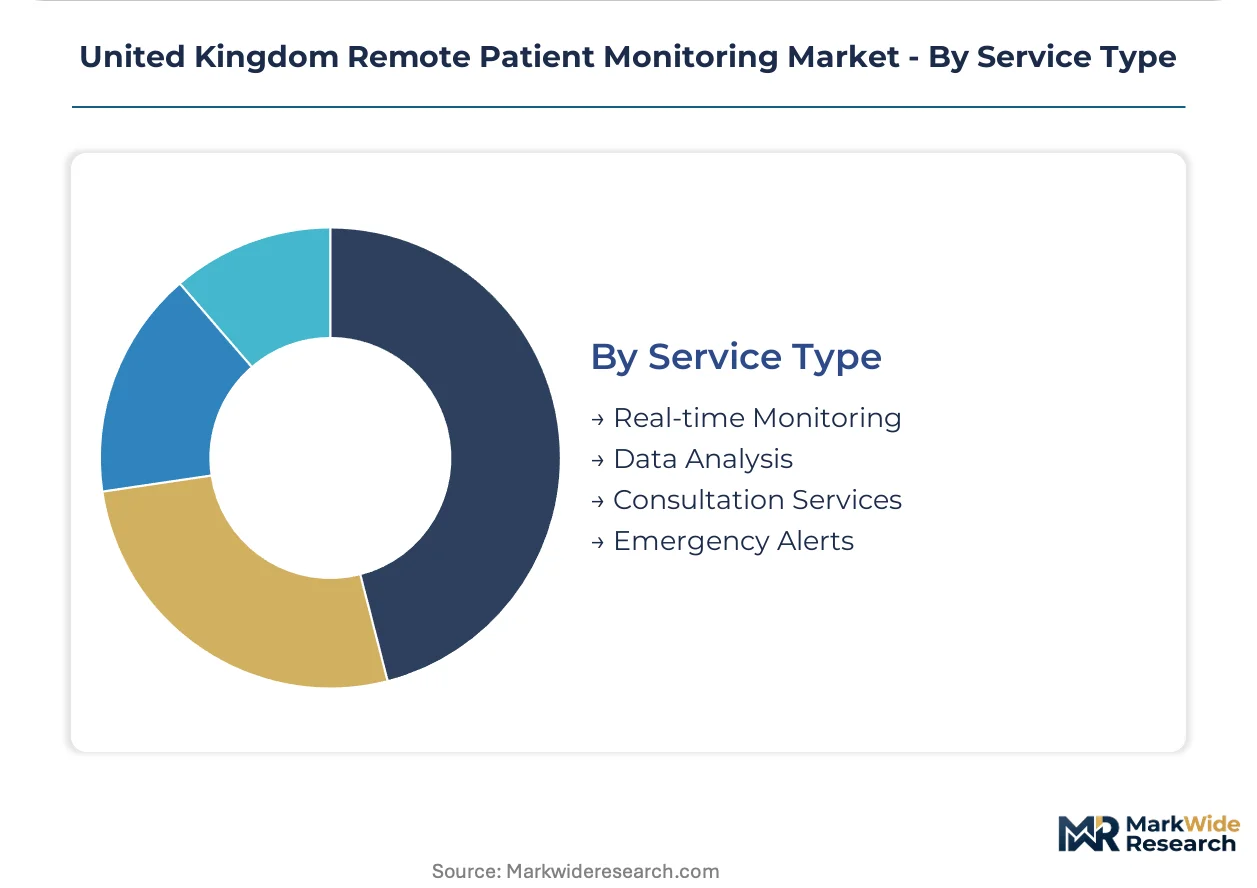
Service Type:
Emergency response capabilities differentiate pricing tiers, with automated escalation protocols commanding substantial premiums.
- Emergency Alerts:Automated threshold breaches trigger direct dispatch to community rapid response teams. The Care Quality Commission's audit trail requirements for encrypted transmission are extending deployment timelines by six to nine months.
- Real-time Monitoring:Continuous telemetry streams enable immediate clinical intervention without physical patient presence.
- Data Analysis:Retrospective cohort reporting supports population health management and virtual ward outcome measurement.
- Consultation Services:Asynchronous clinician review of flagged vital-sign patterns supplements synchronous telehealth visits.
Emergency Alerts captures the highest per-patient revenue, while Data Analysis is climbing the fastest through mandatory virtual ward reporting requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHS England anchors procurement authority through integrated care systems that consolidate purchasing previously fragmented across acute trusts. The Care Quality Commission's digital health standards enforce encrypted data transmission requirements that reshape device certification timelines. Virtual ward mandates in Greater London and the Midlands are compressing deployment schedules for connected care infrastructure.
Greater London
Integrated care systems in Greater London mandate wearable biosensor inclusion in post-acute discharge bundles. NHS Digital's DTAC framework creates procurement clarity that filters uncertified vendors from virtual ward tenders. The capital's health innovation cluster concentrates AI-augmented triage platform development with several pilot-to-scale pathways operational.
Midlands
Community nursing vacancies exceeding 10,000 posts across the Midlands accelerate investment in automated vital-sign capture systems. The Care Quality Commission's audit trail requirements for encrypted transmission extend deployment timelines by six to nine months in this region. Several integrated care boards here operate unified remote monitoring frameworks with consolidated purchasing authority.
Greater Manchester
Devolved health and care spending authority in Greater Manchester enables faster pilot-to-scale pathways for respiratory monitoring platforms. The Health and Care Act 2022's pooled budget requirements create procurement channels that bypass traditional NHS supply routes. Bluetooth-enabled connected inhaler deployments concentrate in this health innovation cluster.
Scotland
NHS Scotland's virtual ward programs drive demand for continuous glucose monitoring systems among Type 1 diabetes cohorts. The country's national health service operates distinct procurement frameworks from NHS England, creating dual compliance pathways for device manufacturers. Edinburgh's digital health cluster anchors algorithm-driven triage development for remote patient monitoring.
United Kingdom Remote Patient Monitoring Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United Kingdom Remote Patient Monitoring Market. Philips and Medtronic occupy positions that emphasize platform integration with NHS Digital's interoperability standards, while mid-tier specialists compete on deployment speed and localized service capabilities. The vendor base stratifies into three archetypes: diversified medtech conglomerates with enterprise-scale platforms, mid-cap specialists with vertical focus on cardiac or respiratory monitoring, and emerging digital health firms with cloud-native architectures. Competitive moves concentrate on strategic partnerships with integrated care boards and portfolio diversification into AI-augmented predictive analytics.
Within the diversified medtech tier, Koninklijke Philips and Medtronic exemplify platform-scale positioning through their integration with NHS Digital's Spine infrastructure. Teladoc Health occupies a position representing the digital-native archetype, competing via chronic care management offerings contracted by integrated care boards. These three companies anchor distinct competitive vectors: hardware-integrated platforms, implantable device ecosystems, and software-centric service models.
| Leading Market Players |
|---|
| Abbott Laboratories |
| GE Healthcare |
| Boston Scientific Corporation |
| Koninklijke Philips |
| Medtronic |
| Becton Dickinson and Company |
| Johnson & Johnson |
| Dragerwerk |
| Teladoc Health |
| Others |
Pricing and Supply Chain Analysis
Bluetooth Low Energy module substitution for proprietary radio protocols is redrawing component sourcing maps from East Asian foundries toward European semiconductor packaging facilities while compressing hardware margins through commoditization pressure on connectivity chipsets.
Pricing Analysis
Geographic price spreads between Greater London integrated care systems and Midlands procurement boards reach three-to-one multiples for identical wearable biosensor bundles. Three-tier pricing structure across premium, standard, and economy levels stratifies by DTAC certification tier and FHIR integration depth. Cost compression in economy-tier glucose monitors stems from factory-calibrated sensor standardization. Community nursing procurement teams exhibit highest price sensitivity; private medical insurers demonstrate lowest.
Supply Chain Analysis
Inventory lead times for NB-IoT cellular modules stretched to twenty-six weeks through 2023 as foundry capacity concentrated in Taiwan, South Korea, and mainland China. Lithium polymer cell supply draws from Japanese and South Korean chemical processors, while hardware security module fabrication rests on German and Dutch semiconductor packaging. Single-source vulnerability concentrates in East Asian NB-IoT chipset foundries. Distribution runs through NHS Supply Chain consolidation toward direct integrated care board negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated care board procurement consolidation that displaced fragmented acute trust purchasing, compressing vendor margins and privileging platform-scale suppliers with DTAC pre-certification.
For Market Incumbents: Secure algorithm-driven triage capabilities through in-house AI development or targeted specialist acquisition to defend against cloud-native entrants with superior predictive analytics. Deepen backward integration into hardware security module supply to mitigate UKCA marking transition friction and capture encryption-mandate premium pricing. For New Entrants and Emerging Players: Anchor in Greater Manchester's devolved health innovation cluster where pilot-to-scale pathways bypass traditional NHS Supply Chain gatekeeping. Target respiratory monitoring platforms for COPD virtual wards, the most penetrable segment given workforce shortage automation mandates and underdeveloped incumbent specialization. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors enterprise-scale vendors with Spine interoperability certification over point-solution specialists. Five-to-ten year viability hinges on AI-augmented subscription revenue displacement of hardware transactional models. Monitor NHS England's forthcoming medtech funding mandates as inflection signal for procurement criteria shifts favoring outcome-based contracting.| Strategic Initiative | Industry Significance |
|---|---|
| DTAC Pre-Certification Investment | Accelerates procurement cycles with integrated care boards filtering uncertified vendors from tenders. |
| FHIR-Standard Developer Acquisition | Addresses interoperability engineering scarcity delaying Spine infrastructure integration timelines. |
| AI-Augmented Triage Platform Launch | Captures subscription revenue pools beyond hardware sales through outcome-based integrated care board contracts. |
| Greater Manchester Innovation Cluster Partnership | Exploits devolved spending authority for faster pilot-to-scale respiratory monitoring deployment pathways. |
| Hardware Security Module Integration | Meets Care Quality Commission encryption mandates while raising unit economics on implantable sensor production. |
Research Methodology
The analysis maps wearable biosensor hardware, telehealth platform software, AI-augmented analytics services, and implantable device ecosystems, each validated through hospital procurement committees, biomedical engineers, integrated care board digital leads, and GPO contracts managers. Primary fieldwork combined with secondary validation against NHS Digital procurement databases, Care Quality Commission audit filings, MHRA UKCA registration records, and integrated care board tender documents. Bottom-up patient volume modeling triangulated against top-down healthcare expenditure flow analysis.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, technology layer, end-user archetype, and service tier, cross-referenced with regional integrated care system maturity. CAGRs derived from patient cohort expansion rates, virtual ward mandate penetration curves, and consumable sensor replacement frequencies. Forecast inputs incorporated NHS workforce vacancy trajectories and DTAC framework adoption timelines.
Material uncertainties — NHS funding mandate revisions, UKCA marking enforcement intensity, cellular module supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding virtual ward scale-up velocity and AI algorithm regulatory acceptance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Coronary Pressure Monitors Market