
 Global Radiation Therapy Equipment Market | 2026-2036
Global Radiation Therapy Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radiation Therapy Equipment Market Foresight
ISO 13485 certification for medical device quality management is rotating the competitive set toward manufacturers with established regulatory infrastructure. Siemens Healthineers leverages its MR-linac integration to anchor premium system deployments across North American academic medical centers. Elekta sustains broad geographic coverage through standardized linear accelerator architectures that simplify service logistics. Varian Medical Systems dominates adaptive therapy software ecosystems, creating high switching costs for installed base customers.
Radiation therapy equipment comprises electromechanical systems that generate and direct ionizing radiation beams with sub-millimeter positional accuracy, typically operating at energy levels between 4 and 25 MV for external beam applications. These systems serve the primary commercial purpose of delivering tumoricidal doses while sparing adjacent healthy tissue through computerized beam modulation and real-time imaging feedback. Linear accelerators occupy the largest installed base due to decades of clinical validation and reimbursement familiarity, while proton therapy systems represent the fastest-growing product category as centers pursue dose escalation for pediatric and central nervous system indications. Image-guided radiation therapy technology commands disproportionate margin pools because software upgrades extend system utility without capital replacement cycles.
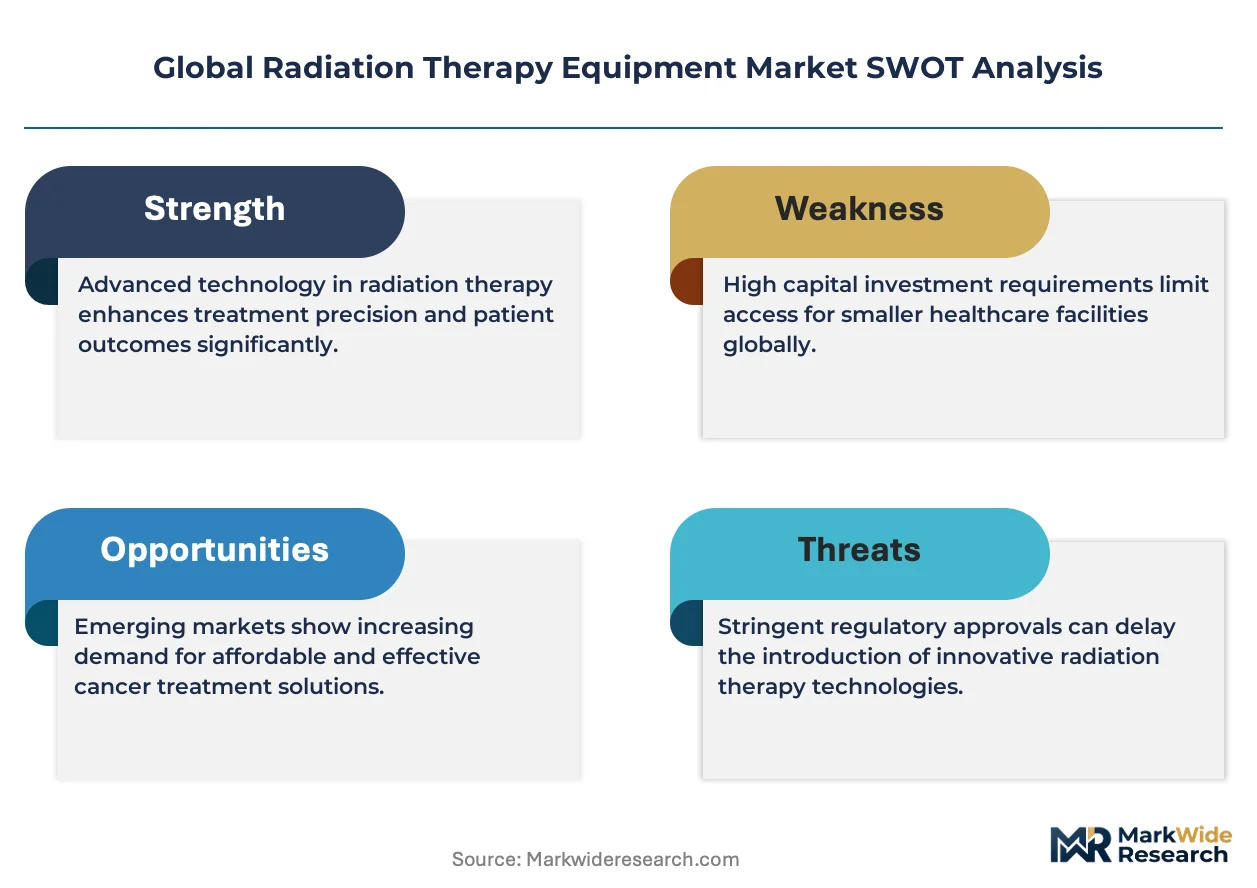
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation reshape competitive dynamics by elevating clinical evidence burdens for new entrants. Japan's PMDA enforces Japan Industrial Standards for electromagnetic compatibility that add localization costs for non-domestic manufacturers. Stakeholders must monitor reimbursement parity between proton and photon therapies across Medicare, national health systems, and private insurers to calibrate capital deployment timing.
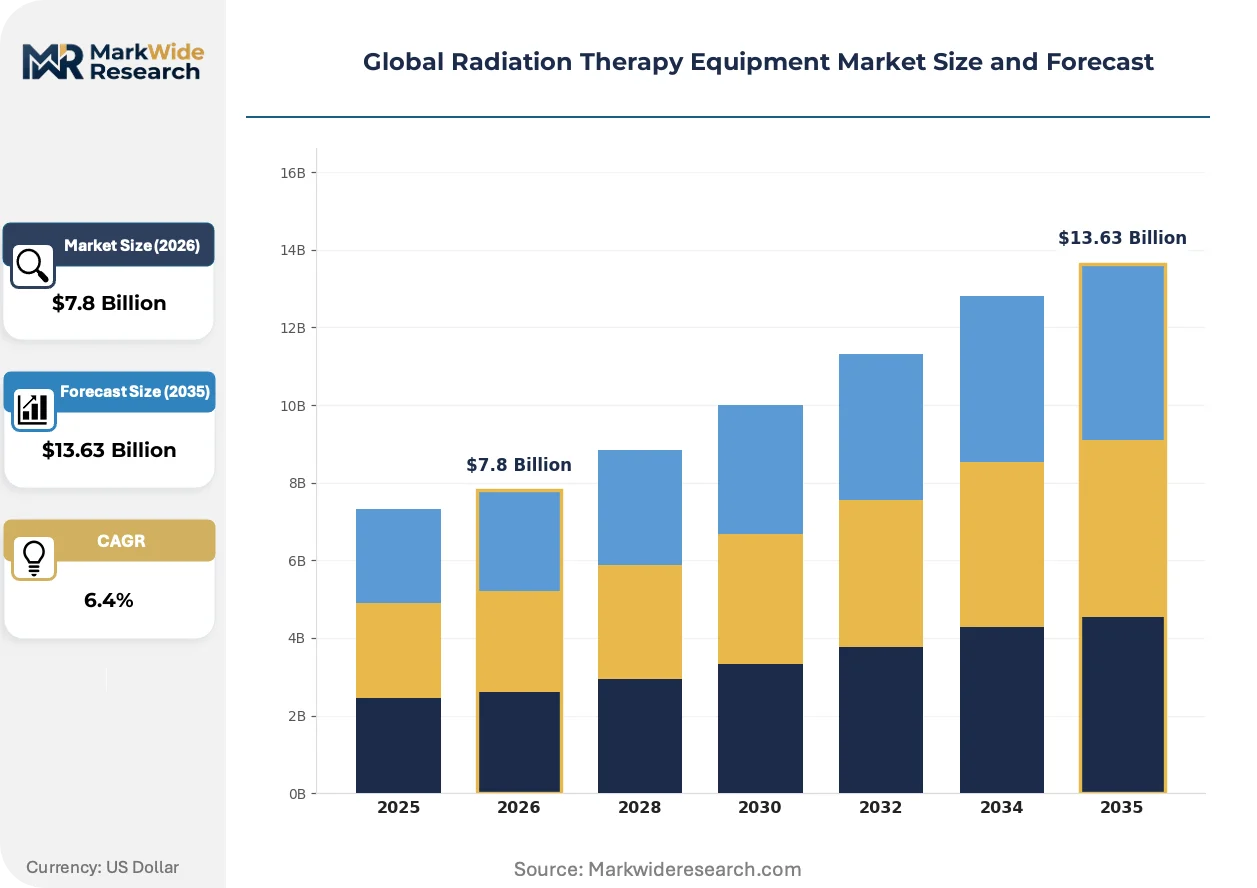
Market Dynamics
Adaptive radiation therapy software is compressing treatment planning cycles from weeks to days, forcing hardware manufacturers to integrate real-time imaging feedback or lose procurement contests at major oncology centers.
Growth Catalysts
- FDA 510(k) pathway streamlining:Pre-market notification requirements for software-guided systems are accelerating clearance timelines for adaptive therapy platforms in the United States.
- Proton therapy infrastructure:University hospitals in Germany are anchoring European capacity expansion for pediatric and central nervous system indications.
- MR-linac convergence:Magnetic resonance imaging integration with linear accelerators enables real-time soft-tissue visualization during treatment delivery.
Market Restraints
- Capital intensity barriers:Proton therapy systems require bunker construction and cyclotron installation costs that limit deployment to academic medical centers with philanthropic backing.
- Supply concentration risk:Superconducting magnet production for MR-linac platforms concentrates among a handful of specialized European suppliers.
- Reimbursement friction:Medicare parity gaps between proton and photon therapies create uncertainty for capital deployment timing in the United States.
Strategic Opportunities
- Underpenetrated markets:India's oncology infrastructure expansion presents white space for linear accelerator deployment as CDSCO streamlines medical device registration.
- Software unbundling:Adaptive planning algorithms are separating from hardware sales, creating recurring revenue streams through subscription licensing.
- Carbon ion therapy:Japan's PMDA experience with heavy particle systems offers regulatory precedent for next-generation radiation modalities entering clinical trials.
Industry Challenges
- Clinical physics workforce scarcity:Radiation therapy planning requires board-certified medical physicists, with training pipeline gaps extending hiring timelines at new centers.
- Legacy system integration:Picture archiving and communication systems at established cancer centers require costly middleware development to interface with adaptive software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radiation Therapy Equipment Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy Equipment, Proton Therapy Systems, CyberKnife Systems, Gamma Knife Equipment Technology: Intensity-Modulated Radiation Therapy, Stereotactic Body Radiation Therapy, Image-Guided Radiation Therapy, Three-Dimensional Conformal Radiation Therapy, Adaptive Radiation Therapy Application: Breast Cancer, Lung Cancer, Prostate Cancer, Brain Tumors, Head and Neck Tumors, Cervical Cancer End User: Oncology Centers, Research Institutes, Specialty Clinics, Cancer Treatment Facilities |
| Companies Covered | Siemens Healthineers, Elekta, Accuray Incorporated, Varian Medical Systems, IBA Worldwide, Hitachi, GE Healthcare, Philips Healthcare, Mevion Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radiation Therapy Equipment Market Shifts & Advancements
Artificial intelligence is penetrating treatment planning workflows, compressing contouring time and enabling same-day adaptive replanning that was previously impossible with manual protocols.
Flash radiotherapy is bifurcating preclinical research from clinical translation. Ultra-high dose-rate delivery demonstrates normal tissue sparing in animal models. Major proton centers in the United States and Germany are installing dedicated research beamlines. This modality is bifurcating capital allocation between conventional fractionation systems and next-generation pulsed delivery platforms.
The EU Medical Device Regulation is elevating clinical evidence requirements for software-as-a-medical-device classifications. Radiation therapy planning algorithms now face notified body scrutiny comparable to implantable devices. European manufacturers are responding by consolidating post-market surveillance databases across national competent authorities.
Service contract unbundling is disrupting traditional equipment financing. Academic medical centers in the United States are separating hardware procurement from maintenance agreements, pressuring manufacturers to compete on pure service metrics. Independent service organizations are capturing linear accelerator maintenance volumes previously held by original equipment manufacturers.
Global Radiation Therapy Equipment Market Segmentation
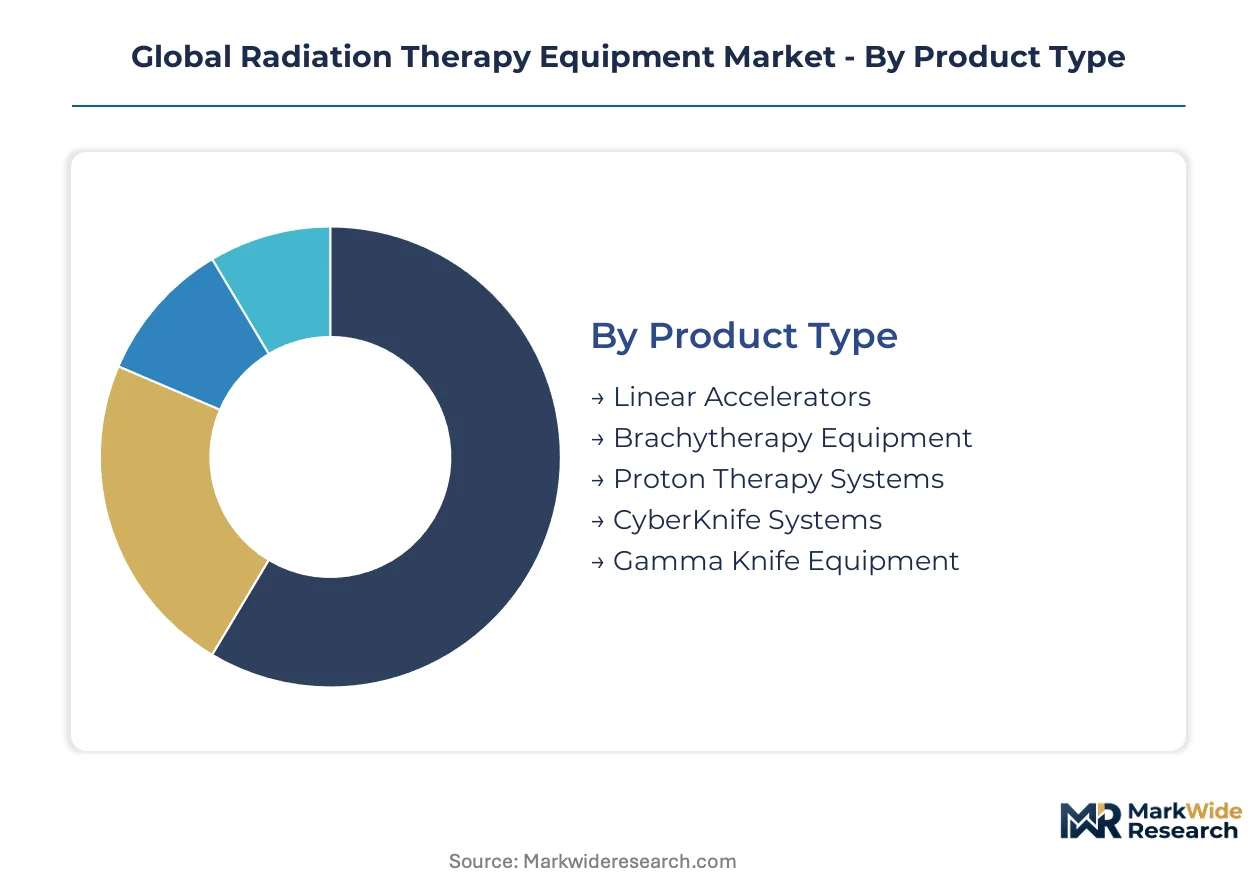
Radiation therapy equipment segmentation reveals distinct substitution pressures across hardware modalities and software platforms. Technology convergence is blurring traditional product boundaries as imaging integration becomes standard.
Product Type:
Linear accelerators face intensifying substitution pressure from proton systems in pediatric and central nervous system indications, while CyberKnife and Gamma Knife platforms compete for intracranial lesion market share.
- Linear Accelerators:Electromechanical systems generating X-ray beams at 4-25 MV through microwave-accelerated electrons. Demand concentrates in India's expanding oncology infrastructure as CDSCO registration pathways mature for imported systems.
- Proton Therapy Systems:Cyclotron-based particle accelerators delivering Bragg peak dose deposition with superior tissue sparing. German university hospitals anchor European capacity expansion for pediatric indications, though capital intensity limits deployment to philanthropic-backed academic centers.
- Brachytherapy Equipment:Afterloader systems delivering radioactive isotopes via catheters for localized gynecological and prostate treatments.
- CyberKnife Systems:Robotic linear accelerators enabling frameless stereotactic radiosurgery for extracranial and intracranial targets.
- Gamma Knife Equipment:Cobalt-60 collimator arrays producing focused gamma radiation for intracranial lesions without surgical incision.
Linear accelerators retain volume leadership; proton therapy systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium adaptive platforms from legacy conformal systems, with reimbursement differentials driving hospital procurement decisions.
- Adaptive Radiation Therapy:Software-guided replanning using daily imaging feedback to modify dose distributions. Siemens Healthineers leverages MR-linac integration to anchor premium deployments across North American academic medical centers.
- Image-Guided Radiation Therapy:Real-time positional verification through integrated CT, MR, or kV imaging during treatment delivery. Varian Medical Systems dominates software ecosystems, creating high switching costs for installed base customers.
- Intensity-Modulated Radiation Therapy:Computer-optimized multileaf collimator modulation producing concave dose distributions around critical structures.
- Stereotactic Body Radiation Therapy:Hypofractionated high-dose delivery to extracranial targets with sub-millimeter accuracy requirements.
- Three-Dimensional Conformal Radiation Therapy:CT-based beam shaping representing the baseline technology standard for community oncology practices.
Image-guided systems dominate current procurement; adaptive platforms are climbing the fastest as FDA 510(k) pathways compress clearance timelines.
Application:
Volume concentration in prostate and breast indications creates margin pressure, while brain and pediatric tumors command premium pricing for advanced modalities.
- Prostate Cancer:External beam and brachytherapy combinations represent the largest treated population. US oncology centers are expanding proton therapy capacity specifically for this indication.
- Brain Tumors:Stereotactic requirements and critical structure proximity drive demand for sub-millimeter accuracy systems. Elekta sustains geographic coverage through standardized architectures that simplify service logistics for remote installations.
- Breast Cancer:Hypofractionation protocols and deep inspiration breath-hold techniques reducing cardiac exposure.
- Lung Cancer:Motion management challenges from respiratory excursion requiring 4D-CT and gating capabilities.
- Head and Neck Tumors:Complex anatomy demanding intensity modulation to spare salivary glands and optic structures.
- Cervical Cancer:Brachytherapy integration with external beam for definitive treatment protocols.
Prostate applications retain volume leadership; brain tumor indications hold the steepest expansion curve.
End User:
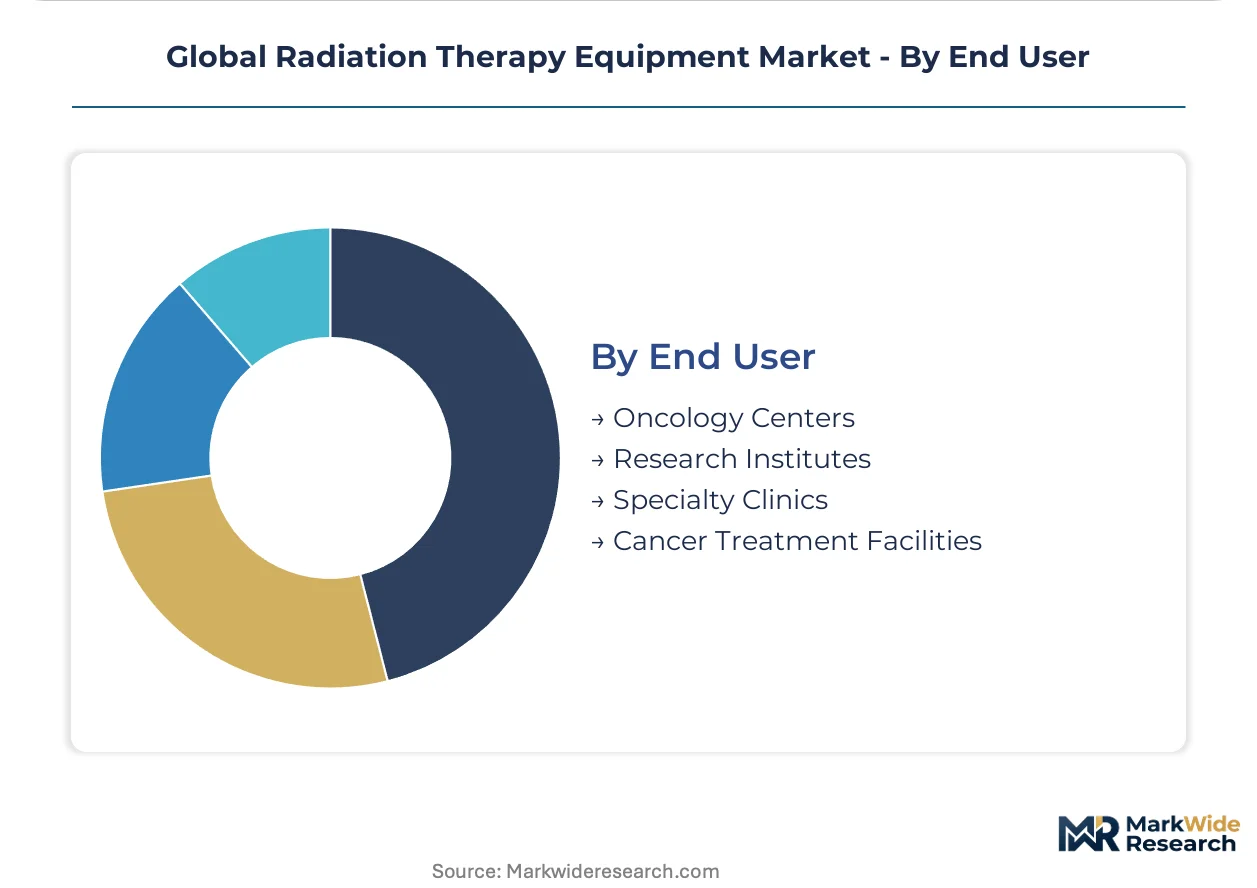
Customer type segmentation reflects capital intensity stratification, with academic medical centers capturing advanced modalities and community settings constrained to photon-based systems.
- Oncology Centers:Comprehensive cancer programs combining medical, surgical, and radiation oncology under unified administration.
- Cancer Treatment Facilities:Dedicated radiation therapy sites with single or multiple linear accelerator deployments.
- Research Institutes:Flash radiotherapy and carbon ion clinical trial infrastructure requiring specialized beamline construction.
- Specialty Clinics:Focused practices in urology or neurosurgery offering targeted radiation services.
Oncology centers retain volume leadership; research institutes hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Heidelberg Ion Beam Therapy Center anchors European proton capacity through its dedicated research beamline infrastructure. University hospitals in Germany leverage this facility to expand pediatric and central nervous system treatment protocols. Cyclotron supply chains concentrate in Swiss and German superconducting magnet fabrication clusters.
United States
Academic medical centers in Boston and Houston are installing proton therapy systems with philanthropic endowment backing. FDA 510(k) pathway streamlining for adaptive therapy software compresses clearance timelines for new platform entrants. The MD Anderson Cancer Center in Texas anchors flash radiotherapy clinical trial infrastructure.
Germany
University hospitals in Heidelberg and Munich anchor European MR-linac deployment through integrated research and clinical programs. EU Medical Device Regulation elevates clinical evidence requirements for software-guided adaptive systems. The DKFZ German Cancer Research Center cluster drives regulatory precedent for carbon ion therapy expansion.
Japan
National Cancer Center hospitals in Tokyo and Kashiwa deploy heavy particle systems for clinical trials. PMDA enforces Japan Industrial Standards for electromagnetic compatibility that add localization costs for imported linear accelerators. The Chiba Prefecture carbon ion facility cluster represents the deepest global experience with next-generation radiation modalities.
India
Tata Memorial Centre in Mumbai and AIIMS Delhi anchor linear accelerator deployment as oncology infrastructure expands. CDSCO streamlines medical device registration pathways for imported radiation therapy systems. Private hospital chains in Bangalore and Chennai are procuring image-guided platforms for tier-1 city coverage.
China
Proton therapy construction concentrates in Shanghai and Guangzhou through municipal hospital expansion programs. NMPA medical device registration requires extensive clinical trial data for imported linear accelerator systems. The Beijing proton center cluster leverages government-backed capital deployment for pediatric indication capacity.
Global Radiation Therapy Equipment Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded conglomerates dominating premium system deployments while private specialists capture maintenance service unbundling opportunities. Market structure concentrates around three to four integrated platform vendors with full hardware-software stacks, supplemented by regional specialists in proton cyclotron fabrication and independent service organizations. Strategic archetypes include imaging-integrated platform vendors, proton beam specialists, and software-centric adaptive therapy developers. Competitive moves center on MR-linac convergence investments and service contract unbundling to capture recurring revenue streams.
Within the imaging-integrated platform tier, Siemens Healthineers and GE Healthcare exemplify conglomerate-backed equipment vendors leveraging diagnostic imaging synergies. Elekta and Varian Medical Systems occupy positions as dedicated radiation therapy specialists with standardized accelerator architectures. Among proton beam specialists, IBA Worldwide and Mevion Medical Systems represent cyclotron-based system developers focused on particle therapy infrastructure. Accuray Incorporated anchors robotic delivery platform development for stereotactic applications. Hitachi and Philips Healthcare sit within diversified industrial and health technology conglomerates respectively, with radiation therapy representing one vertical within broader medical device portfolios.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Elekta |
| Accuray Incorporated |
| Varian Medical Systems |
| IBA Worldwide |
| Hitachi |
| GE Healthcare |
| Philips Healthcare |
| Mevion Medical Systems |
| Others |
Supply & Pricing Matrix
MR-linac convergence is displacing conventional linear accelerator procurement at academic medical centers, simultaneously concentrating superconducting magnet sourcing in Swiss and German fabrication clusters while compressing price premiums for legacy photon-only systems. This substitution dynamic concentrates supplier power among cyclotron and cryogenic component specialists, forcing buyers to accept extended lead times or premium positioning for integrated imaging-accelerator platforms.
Pricing Analysis
Certification level creates the primary spread between premium adaptive systems and standard linear accelerator deployments. Three-tier pricing structure across FDA-cleared adaptive platforms, CE-marked image-guided systems, and baseline conformal equipment reflects clinical evidence burdens and software upgrade entitlements. Cost compression in standard linear accelerator tiers is intensifying because independent service organizations are unbundling maintenance contracts and eroding OEM service margins. Community oncology practices exhibit highest price sensitivity due to reimbursement rate compression, while university hospitals with philanthropic endowments absorb premium positioning for proton and MR-linac systems.
Supply Chain Analysis
Strategic stockpiling of superconducting magnets and radiofrequency components dominates inventory strategy given cyclotron fabrication lead times stretching eighteen to twenty-four months. Manufacturing concentrates in Germany, Switzerland, and the United States for precision accelerator components, with Japan supplying specialized ceramic electron gun assemblies. Cyclotron production draws from niobium-titanium superconductor feedstock anchored in Japanese and European metallurgical facilities. Single-source vulnerability permeates cryogenic cooling system sourcing, where two German suppliers control global capacity for medical-grade helium refrigeration. Distribution runs through direct OEM-hospital procurement relationships for capital equipment, with regional distributors handling aftermarket consumables and replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flash radiotherapy clinical translation is accelerating capital deployment timelines for next-generation pulsed delivery platforms, positioning the market at early-cycle expansion with substantial white space in pediatric and central nervous system indications.
For Market Incumbents: Shield installed base relationships by embedding adaptive software ecosystems that raise switching costs for hospital customers contemplating competitive platform migration. Deepen backward integration into superconducting magnet production to reduce dependency on Swiss and German cyclotron suppliers. Prioritize FDA 510(k) pathway investments for real-time imaging feedback modules that compress clearance timelines against emerging software-centric entrants.
For New Entrants and Emerging Players: Anchor in India's expanding oncology infrastructure where CDSCO registration streamlining and linear accelerator demand concentration create procurement entry points. Target software unbundling opportunities in adaptive planning algorithms sold via subscription licensing rather than capital-intensive hardware competition. Pursue carbon ion therapy regulatory precedent from Japan's PMDA experience as differentiation against entrenched proton system vendors.
For Investors and Strategic Acquirers: The market sits at a technology convergence phase that favors imaging-integrated platform vendors with diagnostic synergies and recurring software revenue streams. Long-term viability hinges on adaptive therapy software ecosystem control rather than pure hardware manufacturing scale. Acquisition targets should display installed base density in academic medical centers with research beamline access. The signal to watch is Medicare reimbursement parity determination between proton and photon therapies, which would trigger accelerated capital deployment across United States oncology centers.
| Strategic Initiative | Industry Significance |
|---|---|
| MR-Linac Platform Integration | Siemens Healthineers leverages diagnostic imaging synergies to anchor premium academic medical center deployments. |
| Adaptive Software Ecosystem Development | Varian Medical Systems creates high switching costs through treatment planning algorithm control and daily imaging feedback loops. |
| Proton Therapy Infrastructure Expansion | German university hospitals anchor European capacity for pediatric indications with dedicated research beamline construction. |
| Service Contract Unbundling | Independent service organizations capture linear accelerator maintenance volumes previously held by original equipment manufacturers. |
| Flash Radiotherapy Clinical Translation | MD Anderson Cancer Center anchors ultra-high dose-rate research infrastructure for next-generation normal tissue sparing protocols. |
Research Methodology
Operator-level perspectives from radiation oncology department chairs, hospital biomedical engineers, GPO contracts managers, and medical physicists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement records, and CMS reimbursement filings. Bottom-up installed base enumeration triangulated against top-down capital expenditure tracking across major oncology center networks.
Sensitivity analysis tested forecast robustness across proton therapy reimbursement scenarios, MR-linac adoption curves, and cyclotron supply constraints throughout the projection horizon. Segmentation modeling incorporated technology tier, application indication, end-user capital intensity, and regional regulatory cluster dimensions. CAGRs derived from equipment replacement cycles, capacity expansion announcements, and software upgrade penetration trajectories. Forecast inputs included clinical trial enrollment for flash radiotherapy, PMDA carbon ion precedent, and CDSCO registration pathway maturation.
Decision-makers should treat outputs as directional under sustained reimbursement parity assumptions for advanced modalities; material deviation would warrant model refresh. Revision becomes warranted when Medicare proton-photon parity determination or EU MDR software classification enforcement crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Proctologic Table Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Cath Lab Market
Medical Equipment
Contact Type Liquid Handling Workstation Market