
 Medication Pouch Inspection Systems Market | 2026-2036
Medication Pouch Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Medication Pouch Inspection Systems Market Outlook
Hospital pharmacy automation is broadening the addressable base for medication pouch inspection systems as acute-care facilities replace manual blister verification with inline optical and barcode systems. Loma Systems leverages its checkweighing heritage to anchor positions in high-speed pouch lines where weight deviation flags dosing anomalies. Precia SA competes through specialized load-cell integration that sustains precision across variable pouch formats in contract manufacturing environments.
Medication pouch inspection systems combine optical sensors, precision weighing modules, and software algorithms to verify unit-dose pouch contents against prescribed parameters at throughput rates exceeding 300 pouches per minute. The equipment serves pharmacies and hospitals by eliminating human error in high-volume automated dispensing workflows. Automated systems occupy the largest value share due to capital-intensive central fill deployments, while AI-powered solutions represent the fastest-expanding technology segment as machine-learning defect classification reduces false-reject rates. Software Solutions capture disproportionate margin pools because recurring license revenue attaches to hardware installations across pharmacy and hospital end users.
FDA unit-dose regulations and EU MDR traceability requirements are elevating inspection stringency, compelling pharmacies and contract manufacturers to upgrade legacy manual stations. The country's national pharmaceutical regulator in Japan and Health Canada impose comparable verification standards that shape product development roadmaps for vendors seeking multi-regional approvals. Stakeholders must monitor how AI validation frameworks evolve across FDA, EMA, and PMDA jurisdictions to anticipate compliance-driven replacement cycles.
Market Dynamics
Central fill pharmacy automation is compressing verification timelines and forcing inspection system vendors to engineer sub-100-millisecond defect detection cycles that match pouch line speeds without human intervention.
Growth Catalysts
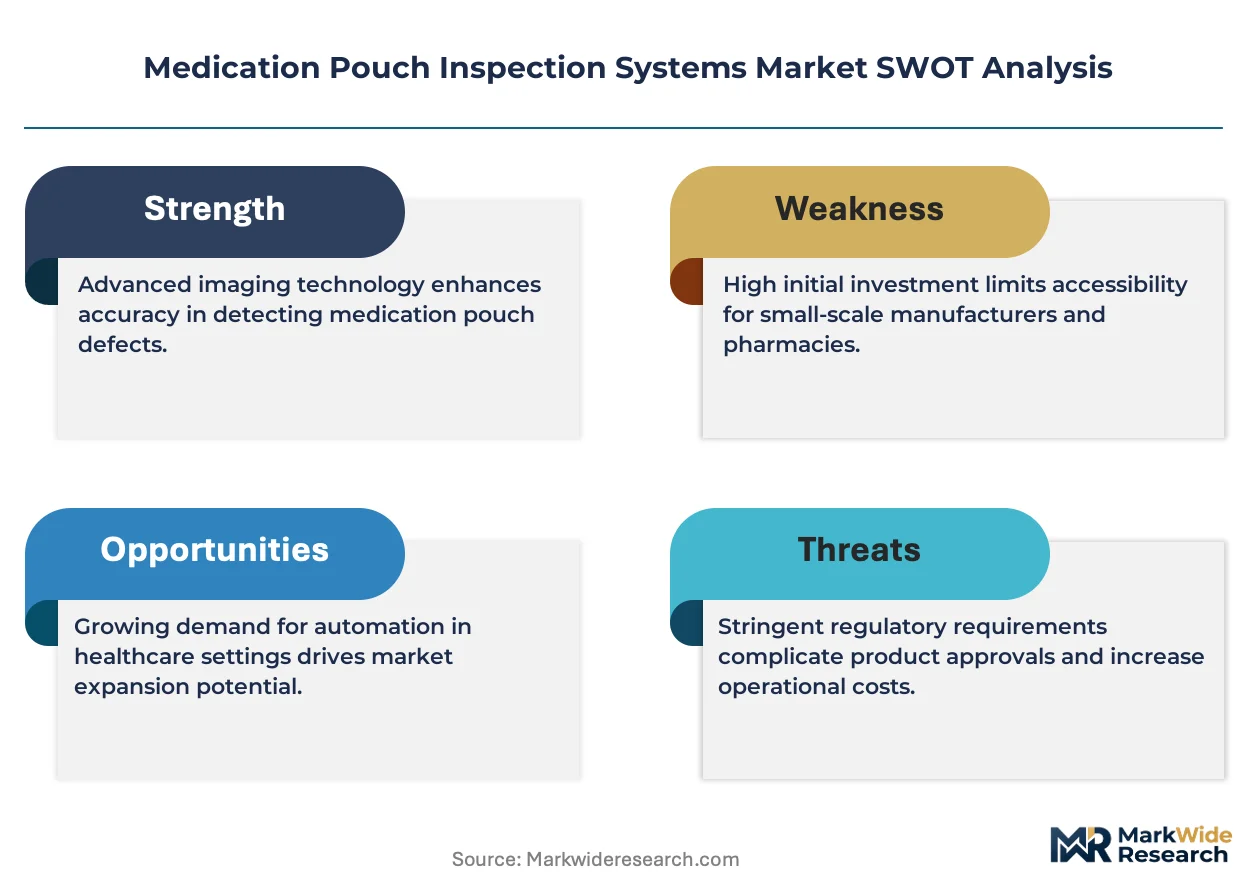
- FDA Unit-Dose Enforcement:Tightened verification standards for hospital-dispensed medications mandate optical and gravimetric inspection at every pouch line, compelling pharmacy automation upgrades.
- Machine Vision Convergence:Deep learning algorithms trained on defect libraries now classify pouch anomalies with precision exceeding human visual acuity, reducing false rejects in high-throughput environments.
- Germany:Dense networks of automated central fill pharmacies and stringent pharmaceutical packaging regulations create concentrated demand for multi-sensor inspection platforms.
Market Restraints
- Capital Intensity:Fully automated inspection lines require six-figure hardware investments plus software licensing, limiting adoption among independent community pharmacies.
- Component Supply Concentration:Precision load cells and high-resolution CMOS sensors originate from specialized German and Japanese suppliers, exposing lead time volatility.
- Legacy Integration Friction:Existing pouch packaging equipment from 2015-2019 vintage lacks standardized data interfaces, complicating retrofit installations.
Strategic Opportunities
- AI-Powered Defect Classification:Machine learning modules that learn facility-specific pouch variations offer recurring SaaS revenue streams atop hardware installations.
- Contract Manufacturing Expansion:Third-party packagers serving long-term care facilities represent an underpenetrated channel requiring portable, validated inspection units.
- EU MDR Traceability Mandate:Serialization and verification requirements for unit-dose medications create replacement demand across European hospital pharmacies.
Industry Challenges
- Validation Timeline Compression:FDA 21 CFR Part 11 compliance documentation and IQ/OQ/PQ protocols extend deployment cycles by 4-8 months.
- Cross-Functional Talent Scarcity:Field service engineers must integrate optical engineering, pharmaceutical regulations, and software diagnostics simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medication Pouch Inspection Systems Market |
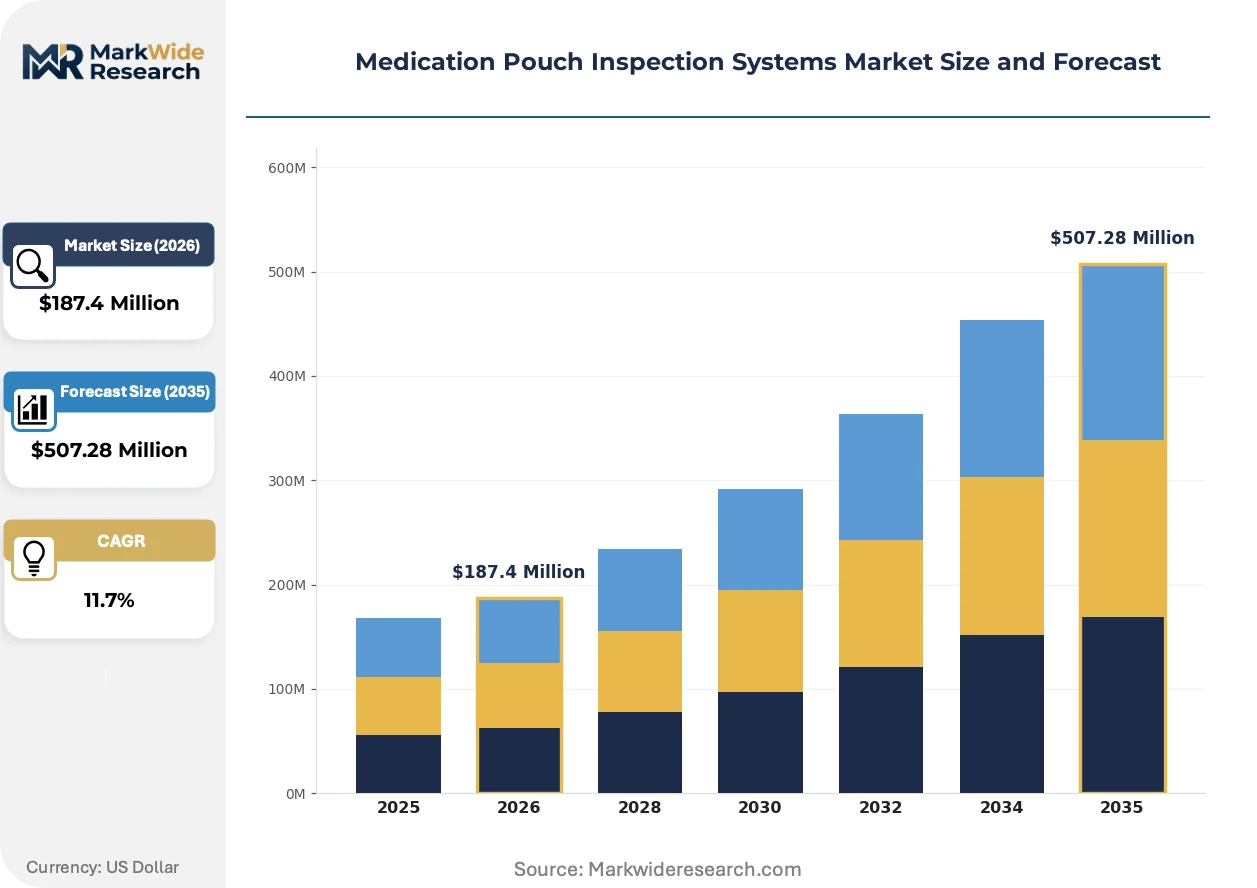
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Inspection Tools, Conveyor Systems, Software Solutions End User: Pharmacies, Hospitals, Distribution Centers, Contract Manufacturers Technology: Optical Inspection, X-Ray Inspection, Barcode Scanning, AI-Powered Solutions Application: Quality Control, Compliance Verification, Product Tracking, Inventory Management |
| Companies Covered | Precia SA, Loma Systems, ESPERA-WERKE GmbH, Ossid LLC, WIPOTEC-OCS GmbH, Aja Ltd, Xact, Marel, Parata Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medication Pouch Inspection Systems Market Strategic Shifts
Inspection technology is pivoting from rule-based threshold detection toward adaptive learning systems that recalibrate sensitivity based on real-time pouch characteristics.
Hyperspectral imaging is automating chemical composition verification within sealed medication pouches, detecting substitution errors invisible to standard RGB cameras. Hospital pharmacies in the United States are piloting these systems for high-risk narcotic verification. This capability is automating the elimination of destructive sampling protocols that previously delayed batch release.
EMA MDR traceability requirements now mandate unique device identification on unit-dose packaging, forcing inspection systems to integrate 2D barcode grading alongside content verification. Contract manufacturers serving European markets are retrofitting existing lines with combined optical-barcode modules. German central fill operators report 15-20% throughput penalties during dual-verification transitions.
Consolidated buying by pharmacy benefit managers and health system purchasing coalitions is compressing vendor evaluation cycles from 18 months to 6-9 months. Equipment specifications now prioritize total cost of ownership metrics over upfront capital expenditure. This pattern concentrates procurement authority among three to five national hospital networks in the United States.
Medication Pouch Inspection Systems Market Segmentation
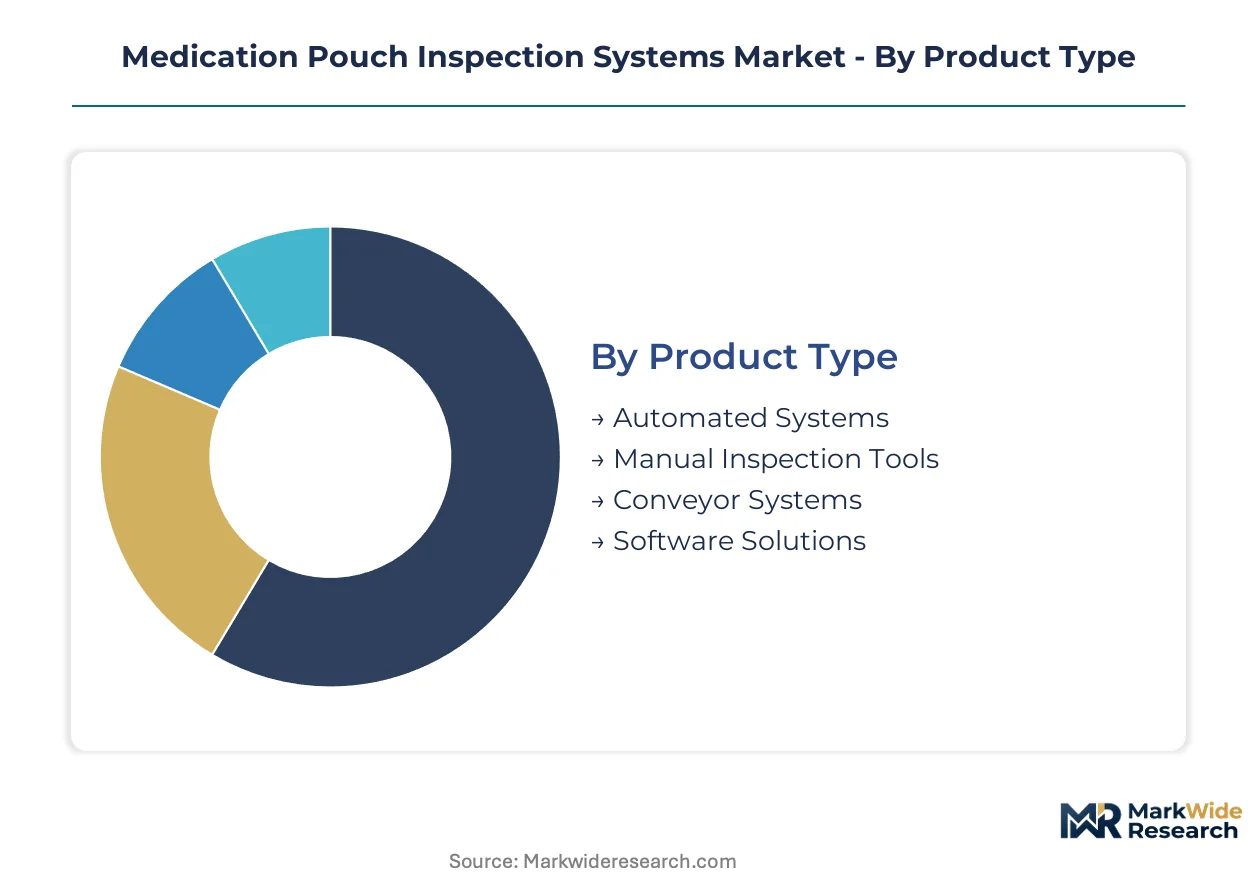
Medication pouch inspection systems segment across hardware, software, and service layers that command divergent margin profiles and replacement cycles. Understanding these splits reveals where capital deployment concentrates versus where recurring revenue accumulates.
Product Type:
Volume deployment favors integrated systems while premium margin pools concentrate in software and specialized modules.
- Automated Systems:Multi-sensor platforms combining optical arrays, precision load cells, and rejection mechanisms process 300+ pouches per minute in central fill environments. Hospital networks in the United States and Germany anchor demand as they consolidate dispensing operations into automated hubs. Capital intensity limits penetration among independent pharmacies.
- Software Solutions:License-based platforms providing algorithmic defect classification, audit trail management, and regulatory reporting generate recurring revenue streams atop hardware installations. FDA 21 CFR Part 11 compliance requirements and EU MDR traceability mandates drive upgrade cycles. Margin profiles exceed hardware due to near-zero incremental delivery cost.
- Manual Inspection Tools:Portable magnifiers and handheld barcode verifiers serve low-volume pharmacies and backup verification roles.
- Conveyor Systems:Belt mechanisms with integrated sensors retrofit existing packaging lines without full automation replacement.
Mature deployment sits with Automated Systems. Newer deployment is concentrated in Software Solutions.
End User:
Customer type determines throughput requirements and regulatory exposure, with acute-care facilities facing the strictest verification mandates.
- Hospitals:Acute-care institutions deploy inline inspection to eliminate dispensing errors in high-risk medication workflows. FDA unit-dose enforcement and Joint Commission accreditation standards compel capital expenditure. German university hospitals and United States health systems lead procurement scale.
- Contract Manufacturers:Third-party packagers serving long-term care and specialty pharmacy require portable, validated units that shift between production campaigns. EU MDR serialization deadlines accelerate replacement of legacy manual stations. Quality agreements with pharmaceutical sponsors dictate inspection protocol rigor.
- Pharmacies:Retail and independent dispensing operations adopt lower-throughput solutions constrained by capital availability.
- Distribution Centers:Wholesale operations verify pouch integrity during consolidation and repackaging workflows.
Procurement authority clusters with Hospitals. Technology refresh urgency concentrates in Contract Manufacturers.
Technology:
Inspection modality selection trades detection depth against processing speed, with emerging methods gaining validation in high-risk applications.
- Optical Inspection:RGB and near-infrared camera arrays detect physical defects, label misalignment, and print quality deviations at line speed. Deep learning classification layers now reduce false-reject rates below 2% in production environments. Deployment concentrates in German central fill pharmacies and United States hospital automation projects.
- AI-Powered Solutions:Machine learning modules trained on facility-specific defect libraries adapt sensitivity thresholds without engineering intervention. SaaS delivery models create recurring revenue attachment to hardware installations. Pilot programs at United States health systems target narcotic verification workflows.
- X-Ray Inspection:Penetrating radiation detects internal pouch anomalies and chemical composition deviations invisible to surface imaging.
- Barcode Scanning:2D matrix verification ensures serialization compliance and product authentication throughout distribution chains.
Installed base dominance rests with Optical Inspection. Capability expansion is climbing the fastest in AI-Powered Solutions.
Application:
Use case priority reflects regulatory pressure hierarchy, with compliance and quality commanding capital allocation ahead of operational efficiency.
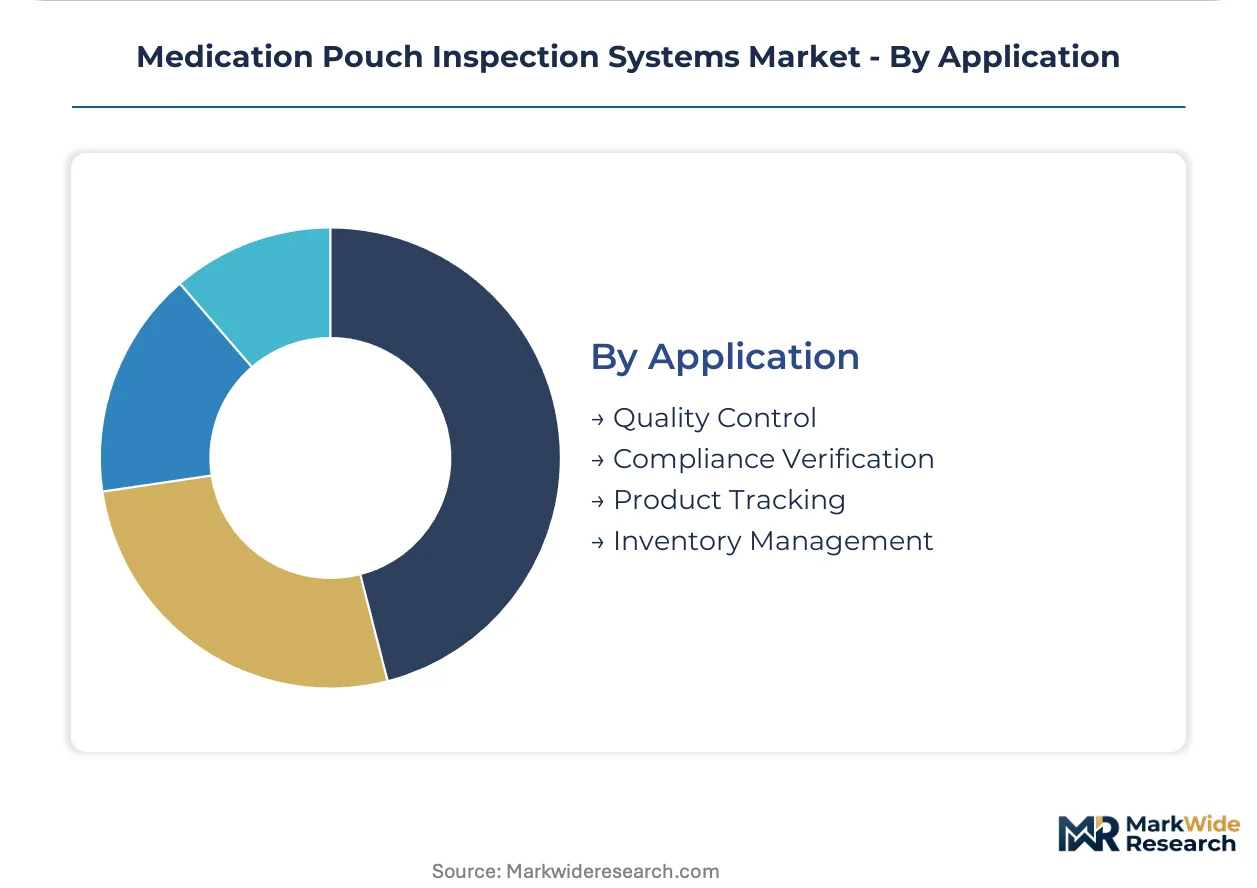
- Compliance Verification:Regulatory documentation, audit trail generation, and FDA 21 CFR Part 11 adherence constitute non-negotiable system requirements. EU MDR unique device identification mandates expand addressable demand across European hospital pharmacies. Software modules for electronic record retention capture disproportionate margin.
- Quality Control:Content verification, weight deviation detection, and seal integrity inspection prevent dispensing errors reaching patients. Optical-gravimetric fusion systems anchor positions in high-volume central fill deployments. Japan's PMDA and Health Canada impose comparable verification standards that shape product specifications.
- Product Tracking:Serialization and aggregation support supply chain visibility and recall efficiency.
- Inventory Management:Pouch-level data integration with pharmacy information systems optimizes stock rotation and waste reduction.
System design centers on Compliance Verification. Functional expansion is gaining share fastest in Quality Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan where precision sensor manufacturing clusters dominate component supply. Consumption tilts toward the United States and Germany where hospital pharmacy automation and central fill networks drive equipment deployment. Regulatory divergence across FDA, EMA, and PMDA jurisdictions shapes regional product specifications.
United States
Hospital networks consolidate dispensing into automated central fill hubs that process millions of unit-dose pouches annually. FDA unit-dose verification standards and Joint Commission accreditation requirements compel optical-gravimetric inspection adoption. Major health systems in the Midwest and Southeast anchor procurement volume as they replace 2015-2019 vintage packaging lines.
Germany
Dense networks of automated central fill pharmacies generate concentrated demand for multi-sensor inspection platforms exceeding 300 pouches per minute. EU MDR traceability mandates and national pharmaceutical packaging regulations tighten compliance requirements. The Baden-Württemberg and Bavaria industrial corridors host precision load cell and CMOS sensor suppliers that feed global equipment assembly.
Japan
PMDA verification standards for unit-dose medications align with FDA stringency, creating dual-approval pathways for vendors. Hospital pharmacies in the Kanto and Kansai regions pilot hyperspectral imaging systems for narcotic verification workflows. Domestic precision engineering clusters in Nagoya and Osaka sustain component supply for high-resolution optical modules.
Canada
Health Canada imposes comparable unit-dose verification standards that shape procurement specifications for hospital pharmacies and contract packagers. Provincial health system consolidation concentrates buying authority in Ontario and Quebec. Long-term care facility networks in British Columbia drive demand for portable validated inspection units.
United Kingdom
NHS pharmacy automation programs accelerate replacement of manual blister verification with inline inspection systems. MHRA alignment with EU MDR traceability requirements sustains serialization and verification mandates post-Brexit. Hospital pharmacy hubs in London and the Midlands lead capital deployment for error-reduction initiatives.
Medication Pouch Inspection Systems Market Competitive Environment
Top-tier vendors anchor automated system supply for high-throughput central fill environments, while mid-tier specialists occupy retrofit and portable equipment niches. The market structure reflects tiered capability concentration: precision weighing heritage from industrial checkweighing merges with machine vision expertise from semiconductor inspection. Three archetypes dominate: sensor-integrated platform builders, software-centric algorithm developers, and precision component specialists. Competitive moves concentrate on AI validation partnerships and multi-regulatory approval acceleration rather than price-based displacement.
Within the precision weighing archetype, Precia SA and Loma Systems exemplify heritage industrial checkweighing vendors that have migrated capabilities into pharmaceutical pouch inspection. WIPOTEC-OCS GmbH occupies a position among German-engineered multi-sensor platform builders. These companies represent how industrial automation expertise transfers into regulated pharmaceutical environments through compliance documentation and validation protocol development.
| Leading Market Players |
|---|
| Precia SA |
| Loma Systems |
| ESPERA-WERKE GmbH |
| Ossid LLC |
| WIPOTEC-OCS GmbH |
| Aja Ltd |
| Xact |
| Marel |
| Parata Systems |
| Others |
Value Chain & Pricing Dynamics
Precision load cells from German and Japanese suppliers anchor hardware cost structures, flowing through three-tier pricing stratification across premium, standard, and economy levels before reaching hospital networks, contract manufacturers, and independent pharmacies downstream.
Pricing Analysis
Cost-down pressure on mid-tier automated systems accelerates because consolidated health system purchasing coalitions compress vendor evaluation cycles and prioritize total cost of ownership metrics over upfront capital expenditure. Three-tier pricing structure across premium, standard, and economy levels segments by throughput capability, FDA 21 CFR Part 11 certification tier, and software license bundling. Independent community pharmacies exhibit highest price sensitivity due to six-figure hardware barriers, while German central fill operators and United States hospital networks absorb premium pricing for sub-100-millisecond defect detection speeds.
Supply Chain Analysis
Single-source vulnerability sits with high-resolution CMOS sensors originating from specialized Japanese suppliers and precision load cells manufactured in German industrial corridors. Component assembly draws from Germany, Japan, and the United States, with raw material dependencies spanning semiconductor-grade silicon, specialized optical glass, and pharmaceutical-grade stainless steel. Tariff exposure on precision sensor imports presents structural risk to equipment lead times. Distribution runs through direct sales forces serving hospital networks, specialized distributors targeting contract manufacturers, and OEM channel partnerships for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medication pouch inspection systems market sits in a technology-transition phase where AI-powered defect classification modules displace rule-based threshold detection systems across high-throughput central fill environments.
For Market Incumbents: To counter margin compression from consolidated health system purchasing coalitions, anchor defensive positioning through backward integration into precision load cell manufacturing and captive development of facility-specific machine learning defect libraries. Certification investment in simultaneous FDA, EMA, and PMDA approval pathways preserves pricing power in multi-regional deployments. For New Entrants and Emerging Players: Launch via portable validated inspection units targeting contract manufacturers serving long-term care facilities, the most penetrable segment constrained by capital availability but facing EU MDR serialization deadlines. White-space concentration sits with SaaS-delivered AI modules that attach recurring revenue to existing hardware installations without full automation replacement. For Investors and Strategic Acquirers: FDA issuance of formal AI validation guidance for pharmaceutical inspection equipment is the leading indicator that machine-learning defect classification will compel replacement cycles across installed base. Long-term viability favors acquisition targets possessing dual competency in precision weighing heritage and regulatory compliance documentation, with signal monitoring focused on health system purchasing coalition consolidation patterns.| Strategic Initiative | Industry Significance |
|---|---|
| AI Validation Partnership | Collaboration with FDA on machine-learning defect classification frameworks accelerates multi-regional approval pathways for vendors. |
| Precision Component Backward Integration | In-house production of load cells and optical sensors insulates against Japanese and German supplier lead time volatility. |
| Contract Manufacturing Channel Expansion | Portable unit development for third-party packagers captures EU MDR-driven replacement demand in underpenetrated long-term care segments. |
| SaaS Revenue Model Attachment | Recurring license platforms for algorithmic defect classification generate margin pools exceeding hardware through near-zero incremental delivery cost. |
| Multi-Regulatory Approval Acceleration | Simultaneous FDA, EMA, and PMDA compliance documentation preserves premium positioning in Germany, United States, and Japanese hospital pharmacy markets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across pharmacy automation directors, biomedical equipment procurement managers, contract manufacturing quality leads, and FDA regulatory affairs specialists. FDA 510(k) premarket notifications, EMA medical device registration databases, Health Canada device licenses, and Japanese PMDA approval records provided validation anchors. Bottom-up equipment shipment analysis and top-down pharmaceutical packaging capital expenditure estimates were triangulated.
Reconciliation of volume and value data streams across the projection horizon employed segmented modeling by product type, end user, technology modality, and application priority. Treatment line differentiation, regulatory compliance tier, and regional automation adoption patterns shaped analytical framework construction. CAGRs were derived from installed base replacement cycles, central fill pharmacy expansion pipelines, and AI module penetration curves.
Regulatory timeline delays, AI validation framework uncertainty, and health system capital expenditure freezes are the dominant revision risks to modeled assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
MRI Transport Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Manufacturing on Demand for Medical Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Global Platelet Incubator Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Global Ultra Low Temperature Freezers Market