
 Irradiation Apparatus Market | 2026-2036
Irradiation Apparatus Market Size, Share, and Industry Trends Forecast 2026-2036
Irradiation Apparatus Market Foresight
A widening capital-intensity gap between proton-therapy specialists and conventional linac manufacturers is redrawing competitive boundaries in the irradiation apparatus landscape. Siemens Healthineers leverages its integrated imaging-therapy platforms to anchor premium hospital contracts across Europe and North America. Elekta competes through software-defined treatment planning systems that reduce clinician training burdens. IBA Radiopharma Solutions specializes in proton-therapy gantries and cyclotron infrastructure, occupying a defensible niche where few rivals match its installed base expertise.
Irradiation apparatus encompasses equipment that generates controlled ionizing or non-ionizing radiation for medical treatment, sterilization, material modification, or analytical testing, with beam energies ranging from kilovolt X-ray tubes to 250 MeV proton cyclotrons and dose rates precisely calibrated for tissue sparing or microbial inactivation. Linear accelerators dominate medical treatment applications due to their tunable megavoltage output and compact footprint relative to isotope-based alternatives, while gamma irradiators retain structural importance in industrial sterilization for medical device packaging where penetration depth outweighs speed considerations. Pulsed light systems are gaining share in food safety lines that require surface decontamination without thermal degradation, though their shallow penetration limits application to smooth-surface produce and packaging films.
FDA 510(k) and PMA pathways govern US market entry for therapeutic radiation devices, while EMA Medical Device Regulation and CE marking requirements shape European product development priorities and clinical evidence standards. EPA regulations on radioactive source security and disposal constrain isotope-based gamma irradiator deployment, nontrivially raising total cost of ownership for cobalt-60 facilities. NMPA streamlining of innovative medical device review in China is accelerating local registrations for foreign manufacturers. Stakeholders must weigh proton-therapy capital commitments against reimbursement uncertainty and cyclotron supply chain concentration as they allocate R&D budgets across beam-modality portfolios.
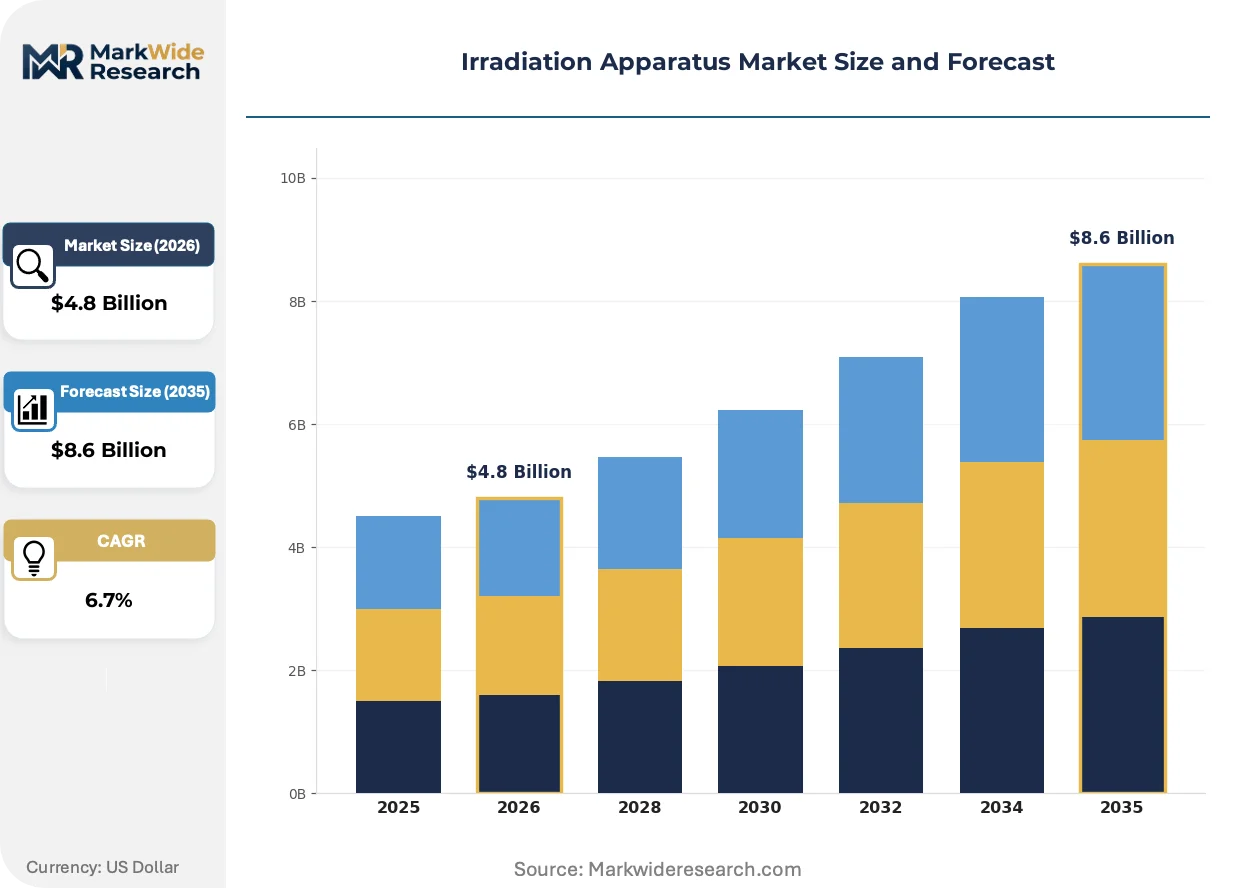
Market Dynamics
The irradiation apparatus market is experiencing a structural compression between proton-therapy capital requirements and reimbursement uncertainty, forcing manufacturers to optimize beam-delivery portfolios while hospital networks delay cyclotron investments until payment parity clarifies.
Growth Catalysts
- NMPA Streamlining:China's accelerated innovative device review pathway reduces registration timelines for foreign proton-therapy manufacturers, unlocking access to the country's expanding oncology infrastructure.
- Heavy-Ion Therapy Expansion:Germany and Japan are commissioning carbon-ion treatment centers that require specialized gantries and beam-line components, creating pull-through demand for high-energy apparatus.
- Industrial Sterilization Mandates:FDA enforcement of sterile packaging requirements for implantable devices sustains cobalt-60 gamma irradiator utilization despite proton alternatives.
Market Restraints
- Cyclotron Supply Concentration:Superconducting magnet fabrication depends on a limited supplier base concentrated in Western Europe, creating single-source vulnerability for proton-therapy system builders.
- EPA Source Security Costs:Radioactive material tracking and disposal regulations under EPA jurisdiction add recurring compliance burdens that inflate total cost of ownership for gamma irradiation facilities.
- Beam Energy Limitations:Pulsed light systems cannot penetrate irregular surfaces or dense packaging, restricting their displacement of gamma methods in medical device sterilization.
Strategic Opportunities
- India's Oncology Infrastructure:The country's hospital network expansion under Ayushman Bharat creates first-mover advantage for linear accelerator manufacturers establishing local service capabilities.
- Flash Radiotherapy Convergence:Integration of ultra-high dose-rate delivery with real-time MRI guidance represents a technology pairing that could command premium positioning in radiosurgery segments.
- CE Marking Acceleration:EMA Medical Device Regulation Article 54 provisions for equivalent device recognition allow faster European market entry for apparatus already cleared under FDA PMA pathways.
Industry Challenges
- Medical Physicist Shortage:Treatment planning system complexity outpaces training program output, extending commissioning timelines for newly installed proton-therapy suites.
- Legacy Linac Integration:Hospital networks face interoperability friction when connecting software-defined planning platforms to decade-old accelerator hardware with proprietary control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irradiation Apparatus Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Machines, UV Lamps, Beta Irradiators, Gamma Irradiators End User: Hospitals, Research Laboratories, Industrial Plants, Agriculture Technology: Linear Accelerators, Isotope-Based, Non-Ionizing Radiation, Pulsed Light Application: Food Safety, Medical Treatment, Sterilization, Material Testing |
| Companies Covered | Siemens Healthineers, Elekta, GE HealthCare, Koninklijke Philips, Accuray, Canon Medical Systems, Hitachi, IBA Radiopharma Solutions, ViewRay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irradiation Apparatus Market Shifts & Advancements
Beam-delivery architectures are fragmenting between precision proton systems and adaptive linac platforms, with software-defined treatment planning emerging as the decisive differentiator rather than hardware specifications alone.
Adaptive radiotherapy workflows are bifurcating treatment delivery into two distinct operational models. Daily imaging-integrated replanning enables margin reduction for complex thoracic and abdominal cases. Academic medical centers in the United States and Germany are deploying these capabilities at scale. Community oncology networks are bifurcating their capital allocation between premium adaptive platforms and conventional fractionation systems based on payer mix.
EMA Medical Device Regulation clinical evidence requirements are elevating post-market surveillance obligations for therapeutic radiation devices. Manufacturers must now maintain active implant registries and periodic safety update reports across their European installed base. Proton-therapy systems with limited long-term outcome data face heightened scrutiny during notified body conformity assessments.
Service contract unbundling is separating hardware maintenance from software subscription fees in radiotherapy equipment procurement. Hospital procurement departments in the United States are negotiating multi-vendor service agreements that break traditional single-source dependencies. This pattern concentrates in integrated delivery networks managing distributed linac fleets across multiple satellite clinics.
Irradiation Apparatus Market Segmentation
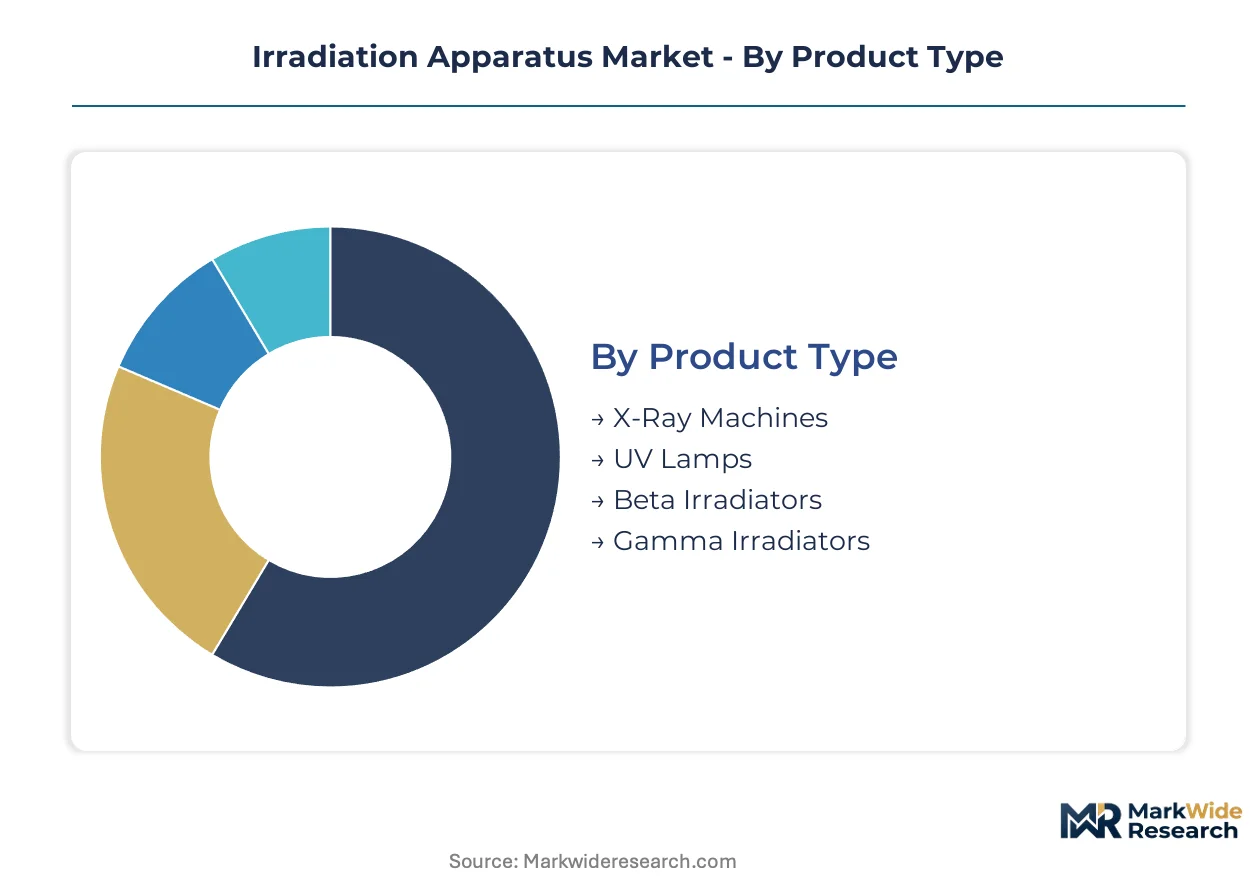
Beam modality and end-use concentration determine procurement patterns across irradiation apparatus categories. Manufacturers align R&D portfolios against segment-specific regulatory pathways and capital intensity thresholds.
Product Type:
X-Ray Machines and Gamma Irradiators anchor domestic production in the United States and Germany, while UV Lamps and Beta Irradiators flow primarily through export-led supply chains concentrated in East Asian manufacturing hubs.
- X-Ray Machines:These systems generate controlled ionizing radiation through electron bombardment of metal targets, producing diagnostic or therapeutic beams with energies from 10 kV to 25 MV. Demand concentrates in German hospital networks expanding radiotherapy capacity, driven by EMA Medical Device Regulation compliance requirements that favor established CE-marked platforms.
- Gamma Irradiators:Cobalt-60 source arrays deliver penetrating ionizing radiation for industrial sterilization and blood irradiation applications. The United States retains significant installed base utilization despite EPA radioactive material security costs, as FDA sterile packaging mandates sustain demand for medical device sterilization where penetration depth outweighs speed.
- UV Lamps:Mercury-vapor and LED-based systems emit ultraviolet-C radiation for surface and air decontamination.
- Beta Irradiators:Electron beam systems provide shallow-penetration ionizing radiation for polymer crosslinking and pharmaceutical packaging.
X-Ray Machines command the established base. The steepest expansion runs through UV Lamps.
End User:
Cost tier stratification separates premium proton-therapy deployments in academic medical centers from standardized linac installations in community hospital networks.
- Hospitals:Oncology departments in hospital networks represent the dominant revenue concentration, scaling radiotherapy capacity through linear accelerator procurement and proton-therapy suite construction. China's NMPA streamlining accelerates foreign manufacturer access to hospital procurement channels under the country's expanding oncology infrastructure.
- Research Laboratories:Academic and government research facilities utilize specialized irradiation apparatus for radiobiology studies, materials science, and beam physics development. Germany and Japan concentrate heavy-ion therapy research demand, commissioning carbon-ion treatment centers that require specialized gantries.
- Industrial Plants:Medical device manufacturers and food processors deploy gamma and electron beam systems for sterilization and pasteurization.
- Agriculture:Phytosanitary treatment facilities utilize irradiation for pest disinfestation in export commodity shipments.
Hospitals absorb the majority of capital expenditure. Research Laboratories are climbing the fastest as heavy-ion therapy expansion accelerates specialized apparatus procurement.
Technology:
Volume concentration favors Linear Accelerators in medical treatment, while Isotope-Based systems retain structural position in industrial sterilization despite regulatory headwinds.
- Linear Accelerators:RF-driven electron acceleration systems produce tunable megavoltage X-ray and electron beams with compact footprint relative to cyclotron alternatives. Siemens Healthineers and Elekta compete through integrated imaging-therapy platforms and software-defined treatment planning, reducing clinician training burdens in United States and European hospital networks.
- Isotope-Based:Cobalt-60 and cesium-137 source systems depend on radioactive material supply chains and face EPA disposal constraints in the United States. Industrial sterilization for implantable medical devices sustates utilization where gamma penetration advantages outweigh proton alternatives.
- Non-Ionizing Radiation:Microwave and radiofrequency systems generate thermal effects for targeted tissue ablation and industrial processing.
- Pulsed Light:High-intensity flash lamps deliver surface decontamination without thermal degradation, gaining share in food safety lines with smooth-surface produce and packaging films.
Linear Accelerators dominate installed capacity. Pulsed Light is gaining share fastest in food safety applications where surface decontamination speed outweighs penetration requirements.
Application:
Customer type bifurcation separates regulated medical applications with stringent FDA and EMA clinical evidence requirements from industrial sterilization governed by packaging standards.
- Medical Treatment:External beam radiotherapy, brachytherapy, and intraoperative radiation delivery require precise dose calibration and real-time imaging integration. Adaptive radiotherapy workflows in United States academic medical centers enable daily imaging-integrated replanning for complex thoracic and abdominal cases.
- Sterilization:Terminal sterilization of medical devices, pharmaceuticals, and packaging materials utilizes gamma, electron beam, and X-ray modalities. FDA enforcement of sterile packaging requirements for implantable devices sustains cobalt-60 gamma irradiator utilization despite proton alternatives.
- Food Safety:Pathogen reduction and phytosanitary treatment for fresh produce, spices, and refrigerated meat products.
- Material Testing:Radiation hardness testing for aerospace electronics, polymer degradation studies, and archaeological dating applications.
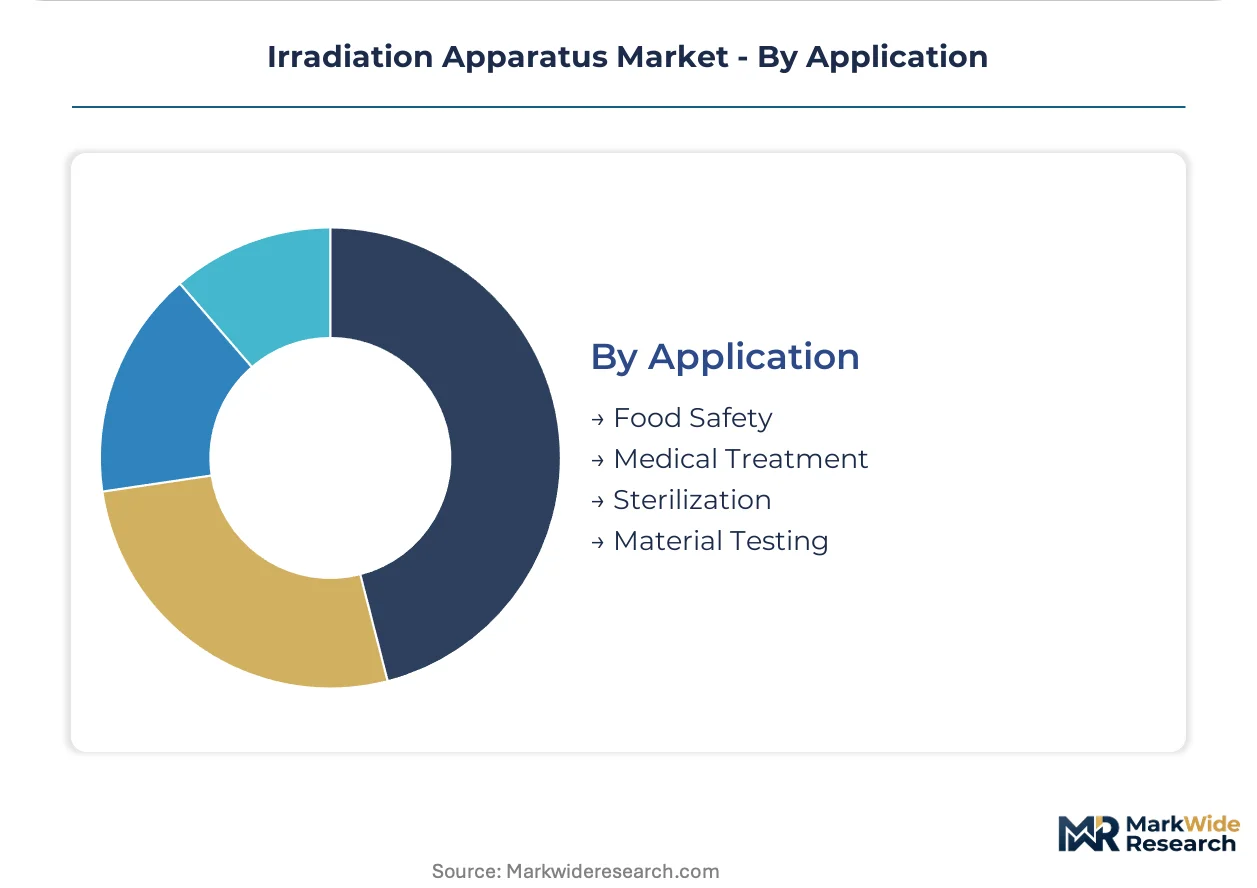
Sterilization commands the established base. Medical Treatment shows the steepest expansion trajectory as proton and heavy-ion therapy infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes proton-therapy infrastructure despite reimbursement uncertainty, while Germany and China scale conventional linac capacity through distinct regulatory pathways. Industrial sterilization demand concentrates in North America and Western Europe where FDA and EMA packaging mandates sustain gamma irradiator utilization.
United States
Academic medical centers in Boston and Houston are commissioning proton-therapy suites with integrated MRI guidance. FDA PMA pathways for novel beam-delivery platforms compress product development cycles for domestic manufacturers. The Research Triangle in North Carolina anchors heavy-ion therapy research infrastructure.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are expanding carbon-ion treatment capacity through specialized gantry procurement. EMA Medical Device Regulation clinical evidence requirements elevate post-market surveillance obligations for therapeutic radiation devices. The Heidelberg region hosts concentrated heavy-ion therapy research facilities.
China
Oncology departments in Beijing and Shanghai are scaling radiotherapy capacity to address rising cancer caseloads. NMPA streamlining of innovative medical device review accelerates local registrations for foreign proton-therapy manufacturers. The Yangtze River Delta corridor concentrates domestic linear accelerator production.
Japan
Research laboratories in Kansai and Chubu regions are commissioning carbon-ion treatment centers requiring specialized beam-line components. METI industrial policy supports domestic cyclotron fabrication capabilities for medical isotope production. The Osaka-Tokyo corridor anchors adaptive radiotherapy platform deployment.
India
Hospital network expansion under Ayushman Bharat creates procurement opportunities for linear accelerator manufacturers establishing local service capabilities. CDSCO medical device regulations are converging toward international standards for foreign OEM market entry. The Delhi-Mumbai corridor concentrates emerging oncology infrastructure investment.
Irradiation Apparatus Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Siemens Healthineers and Elekta commanding premium positioning through software-integrated platforms. The middle tier contains regional equipment fabricators and component specialists serving sterilization and research segments. Two strategic archetypes dominate: imaging-therapy integrators leveraging hospital system contracts, and proton-therapy specialists defending cyclotron expertise. Competitive moves center on service contract unbundling and adaptive therapy software licensing.
Among imaging-therapy integrators, Siemens Healthineers and GE HealthCare exemplify the consolidated tier through their multi-modality hospital system presence. IBA Radiopharma Solutions occupies a defensible position within proton-therapy infrastructure, where cyclotron supply chain concentration limits rival entry. These three entities represent distinct competitive vectors: integrated imaging platforms, diversified health technology portfolios, and specialized particle-therapy systems.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Elekta |
| GE HealthCare |
| Koninklijke Philips |
| Accuray |
| Canon Medical Systems |
| Hitachi |
| IBA Radiopharma Solutions |
| ViewRay |
| Others |
Supply & Pricing Matrix
FDA PMA and EMA MDR certification requirements simultaneously gate supplier qualification and stratify price tiers across proton-therapy and conventional linac portfolios, compressing margins for non-certified fabricators while amplifying premiums for dual-cleared platforms in United States and European hospital procurement cycles.
Pricing Analysis
Long-term service contracts with unbundled software subscriptions now dominate radiotherapy equipment procurement, replacing historical single-source bundled arrangements. Three-tier pricing structure across premium adaptive platforms, standard linac systems, and economy refurbished units reflects certification grade and imaging integration depth. Cost compression in the economy tier is intensifying because hospital networks delay cyclotron investments amid reimbursement uncertainty. Community oncology networks exhibit highest price sensitivity, while academic medical centers prioritize clinical capability over capital outlay.
Supply Chain Analysis
Western Europe and the United States anchor superconducting magnet fabrication and precision gantry manufacturing for proton-therapy systems, while East Asian manufacturing hubs concentrate UV lamp and beta irradiator component production. Beam-delivery apparatus draws from specialized cobalt-60 source suppliers, niobium-titanium superconductor feedstock, and precision RF cavity fabricators. Single-source vulnerability in superconducting magnet supply creates structural risk for proton-therapy system builders. Distribution runs through hospital procurement committees, integrated delivery networks, and specialized radiation oncology distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from software-defined treatment planning platforms that reduce hardware differentiation, requiring defensive positioning around integrated imaging-therapy workflows and cyclotron expertise.
For Market Incumbents: Secure cyclotron supply chain exclusivity through backward integration into superconducting magnet fabrication or captive supplier arrangements in Western Europe. Deepen software subscription attach rates to lock hospital networks into proprietary treatment planning ecosystems, insulating against open-architecture competitors. Pulsed light sterilization systems represent an emerging substitute threat in food safety applications where surface decontamination suffices. For New Entrants and Emerging Players: Differentiate on localized service capabilities in India's expanding oncology infrastructure under Ayushman Bharat, where incumbent footprint remains thin. Target research laboratory segments in Germany and Japan commissioning carbon-ion treatment centers, as heavy-ion apparatus expertise concentrates among few qualified suppliers. A software companion strategy for legacy linac interoperability offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across proton-therapy infrastructure as cyclotron fabrication costs escalate and reimbursement uncertainty extends payback periods. Long-term viability favors acquisition targets with installed base service contracts and software recurring revenue rather than pure hardware fabricators. Monitor NMPA clearance timelines for foreign manufacturers as the signal indicating whether China's oncology infrastructure expansion accelerates or stalls.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | EMA Article 54 provisions compress European entry timelines for FDA-cleared beam-delivery platforms. |
| Hospital System Partnership | Integrated delivery network contracts concentrate procurement leverage for multi-site linac fleet standardization. |
| Software Companion Development | Adaptive radiotherapy workflows command premium positioning through daily imaging-integrated replanning capabilities. |
| Reimbursement Strategy | Payment parity advocacy for proton therapy determines cyclotron investment viability in United States hospital networks. |
| Backward Integration | In-house superconducting magnet production mitigates single-source supply risk for proton-therapy system builders. |
Research Methodology
Operator-level perspectives from radiation oncology department heads, hospital procurement committee members, biomedical physicists, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview intelligence combined with secondary validation from FDA 510(k) and PMA filing databases, EMA notified body conformity assessment records, hospital capital expenditure tracking systems, and CMS Medicare reimbursement data. Bottom-up installed base modeling and top-down healthcare infrastructure spending analysis provided triangulation across the analysis window.
Sensitivity analysis tested forecast outputs against variable assumptions for proton-therapy reimbursement parity timing, cyclotron supply chain disruption scenarios, and NMPA regulatory pathway acceleration. Segmentation dimensions modeled include beam modality, end-user concentration, technology architecture, and application category across the projection horizon. CAGRs derived from regression analysis of historical capital expenditure patterns and projected oncology infrastructure buildout. Industry-specific inputs incorporated medical physicist training program output rates and radioactive source disposal cost trajectories.
Decision-makers should treat outputs as directional under base assumptions of stable FDA and EMA regulatory pathways and continued cobalt-60 source availability; material deviation in reimbursement policy or isotope supply would warrant model refresh. Specific risk factors include EPA radioactive material security cost escalation, flash radiotherapy clinical trial outcomes, and cyclotron superconductor feedstock price volatility. Recalibration cycles align with material shifts in national reimbursement schedules and notified body guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Operating Table Market
Medical Equipment
Autopsy Equipment Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Global Steam Autoclaves Market