
 Medical Air Sterilizer Market | 2026-2036
Medical Air Sterilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Air Sterilizer Market Insights
Multi-source procurement for HEPA filtration components is recalibrating how original equipment manufacturers secure critical supply. Steris PLC leverages captive manufacturing of UV-C lamp assemblies to reduce lead-time volatility. Getinge AB anchors its competitive stance through sterile processing integration that spans pre-filter to terminal sterilization. Daikin Industries, Ltd. dominates compact fan-coil sterilizer modules for retrofit installations in aging hospital infrastructure.
Medical air sterilizers are electromechanical systems engineered to reduce viable airborne microorganisms through filtration, irradiation, or oxidative processes, typically achieving log-reduction thresholds against bacteria and viral aerosols in enclosed clinical volumes. These units deploy UV-C wavelengths near 254 nanometers or HEPA media rated at H13-H14 efficiency classes to meet airborne infection isolation room standards. Portable units command premium pricing in emergency department expansions where permanent HVAC modifications prove cost-prohibitive. Centralized systems sustain longer replacement cycles but lock margin pools into multi-year service contracts. Plasma technology segments are gaining fastest traction in pharmaceutical cleanroom applications where chemical residues from traditional methods risk batch contamination.
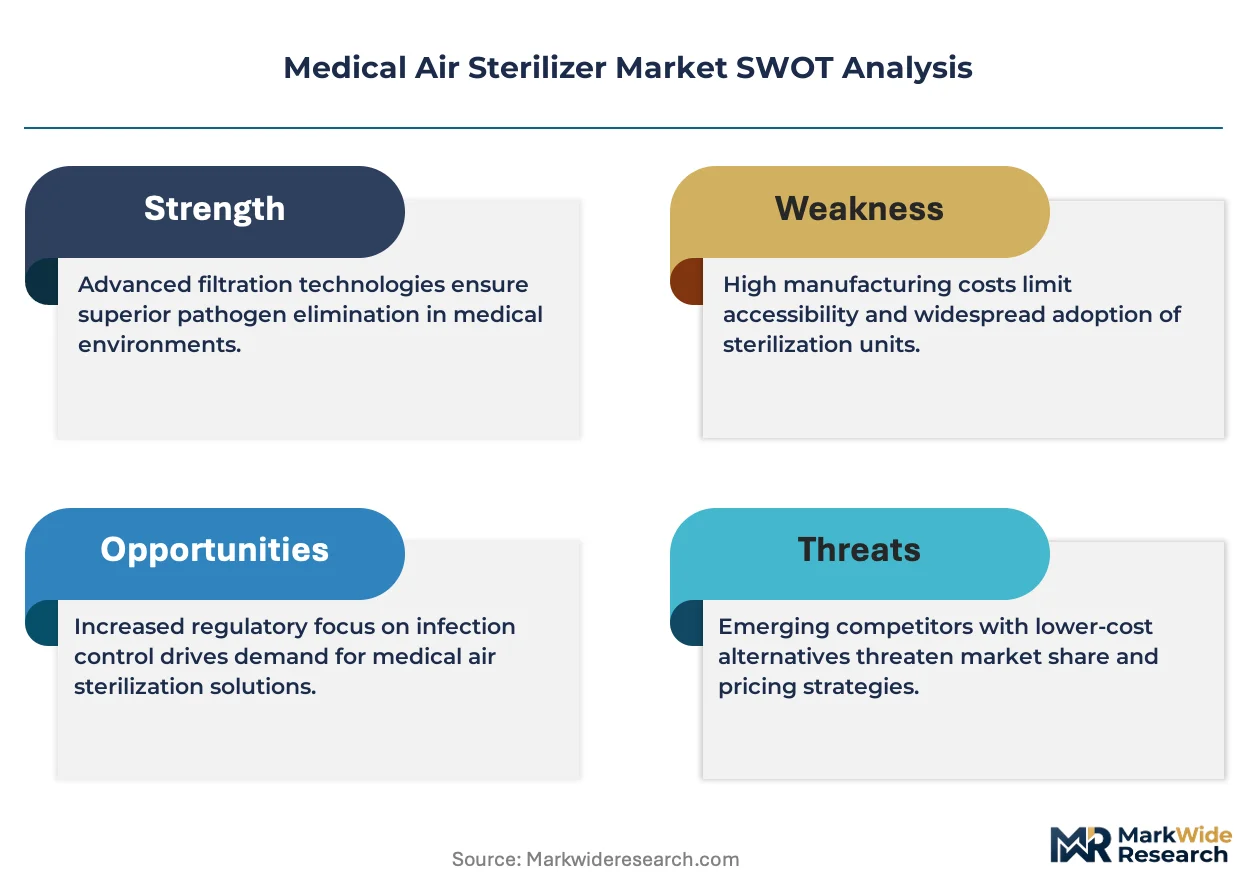
The FDA enforces 510(k) premarket notification pathways for sterilizer devices marketed with antimicrobial claims, while EPA regulates pesticidal devices under FIFRA compliance frameworks that govern ozone-generating and ionizing systems. EU MDR and REACH constrain material selection for filter housings and UV lamp doping elements, extending certification timelines for manufacturers seeking dual-market access. Stakeholders must monitor evolving ASHRAE Standard 170 ventilation guidelines for healthcare facilities, as these directly dictate minimum air changes per hour and filtration tiers that sterilizer specifications must satisfy or supplement.
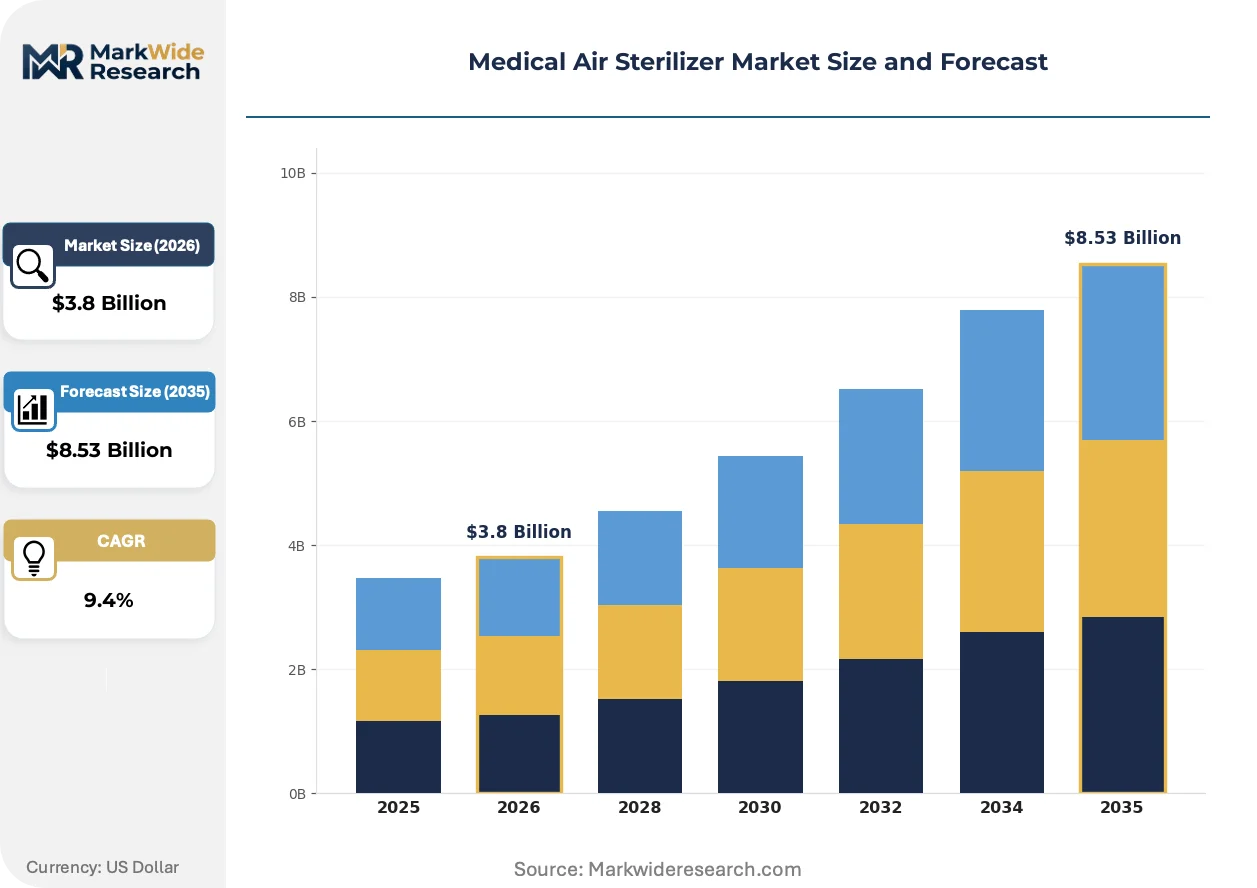
Market Dynamics
Hospital infrastructure renewal cycles are compressing procurement timelines as aging HVAC systems face simultaneous replacement pressure from ASHRAE Standard 170 updates and post-pandemic infection control mandates. This structural squeeze is forcing sterilizer specifications upstream into architectural planning phases rather than downstream equipment procurement.
Growth Catalysts
- FDA 510(k) pathway streamlining:Antimicrobial claim premarket notifications for UV-C and plasma systems are clearing faster than ozone-based alternatives, accelerating hospital adoption of irradiation technologies over oxidative methods.
- Japan METI hospital modernization grants:Subsidized indoor air quality upgrades in tertiary care facilities are creating concentrated demand for compact retrofit sterilizer modules.
- HEPA H13-H14 media supply diversification:Multi-source procurement strategies are stabilizing component availability and reducing original equipment manufacturer lead-time volatility.
Market Restraints
- UV-C lamp rare earth doping concentration:Europium and terbium supply chains concentrate in limited processing jurisdictions, creating input cost volatility for irradiation system manufacturers.
- ECHA REACH substance restrictions:Filter housing polymer formulations face extended compliance timelines, constraining material selection flexibility for dual-market EU-US access.
- Terminal sterilization substitution:Ethylene oxide and vaporized hydrogen peroxide systems retain entrenched positions in surgical suite applications, limiting air sterilizer penetration in highest-acuity zones.
Strategic Opportunities
- Pharmaceutical cleanroom plasma convergence:Low-temperature plasma technology intersects with chemical residue elimination requirements, opening batch contamination-sensitive manufacturing segments.
- Emergency department portable deployment:Permanent HVAC modification cost barriers in rapid-expansion clinical settings create premium pricing acceptance for mobile sterilizer units.
- EU MDR service contract bundling:Extended certification timelines favor multi-year maintenance agreements that lock recurring revenue streams for centralized system installations.
Industry Challenges
- Electromechanical integration complexity:Legacy hospital building management systems require custom protocol bridges for sterilizer sensor feedback loops, extending commissioning timelines.
- Dual certification timeline compression:Simultaneous FDA 510(k) and EPA FIFRA compliance for ozone-generating devices creates parallel review bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Air Sterilizer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Wall-Mounted Systems, Centralized Systems, Room Size Units Application: Hospitals, Clinics, Laboratories, Operating Theaters Technology: UV-C Light, HEPA Filtration, Plasma Technology, Chemicals End User: Healthcare Facilities, Research Institutions, Pharmaceutical Companies, Dental Offices |
| Companies Covered | Steris PLC, Getinge AB, 3M Company, Advanced Sterilization Products Services Inc., Daikin Industries, Ltd., Honeywell International Inc., Sharp Corporation, Camfil AB, WellAir, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Air Sterilizer Market Trends and Innovations
Active pharmaceutical ingredient manufacturing contamination protocols are migrating into clinical settings, compressing the technology adoption gap between pharmaceutical cleanrooms and hospital environments. This cross-industry transfer is reshaping sterilizer performance benchmarks and procurement specifications.
Photocatalytic oxidation systems incorporating titanium dioxide-coated substrates are overtaking traditional UV-C standalone configurations in ambulatory surgical center retrofits. These hybrid units achieve broader microbial spectrum coverage without mercury lamp disposal liabilities. Equipment lessors in Germany and Japan are prioritizing photocatalytic portfolios for ten-year total cost of ownership advantages.
ASHRAE Standard 170 ventilation guideline revisions are mandating minimum equivalent air changes per hour in airborne infection isolation rooms, forcing sterilizer specifications to supplement rather than replace mechanical HVAC capacity. Hospital engineering departments in the United States are recalibrating equipment selection criteria toward filtration-irradiation hybrid architectures. Daikin Industries and Steris PLC are repositioning product lines to capture this supplementary specification role.
Buying committees are unbundling after-sales service contracts from initial equipment procurement, fragmenting vendor relationships into specialized maintenance providers. This disintermediation concentrates in United States hospital systems with dedicated clinical engineering departments. Third-party service firms certified under ISO 13485 quality management standards are capturing recurring revenue pools previously retained by original equipment manufacturers.
Medical Air Sterilizer Market Segmentation
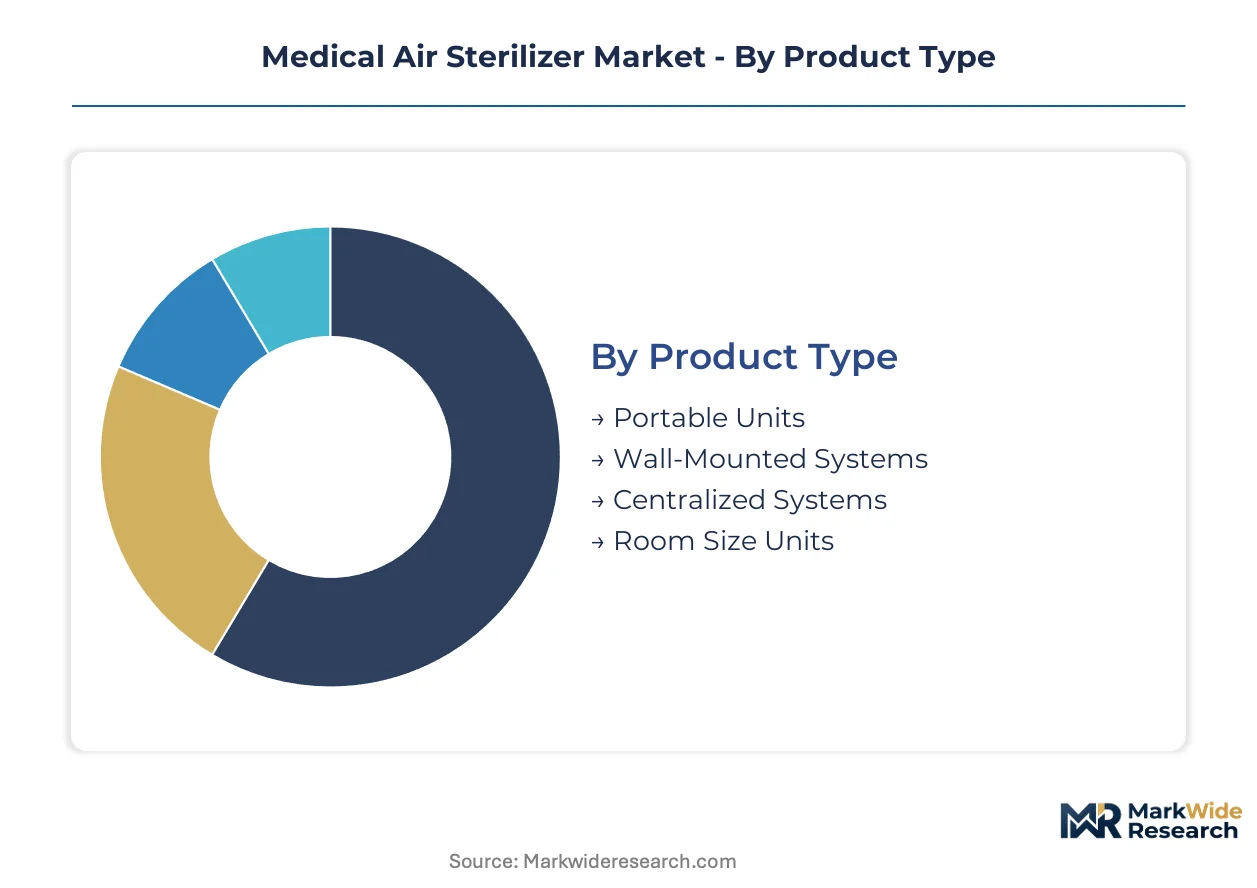
Medical air sterilizer procurement diverges sharply across deployment scales and clinical acuity levels. Specification committees weigh mobility against permanent infrastructure integration, while technology selection hinges on residue tolerance and microbial spectrum requirements.
Product Type:
The customization-to-standardization spectrum spans from site-engineered centralized architectures to plug-and-play portable configurations.
- Portable Units:Self-contained electromechanical systems with castor-mounted chassis deploy UV-C or HEPA modules rated for 500-2,000 cubic foot volumes. Emergency departments in the United States specify these for rapid isolation room conversions where HVAC retrofit timelines exceed patient surge capacity.
- Centralized Systems:Building-integrated sterilization infrastructure connects to existing air handling units through duct-mounted irradiation arrays or terminal HEPA banks. Hospital infrastructure renewal programs in Germany favor these for airborne infection isolation suites requiring sustained 99.97% particulate capture.
- Wall-Mounted Systems:Semi-permanent installations anchor to clinical wall structures with dedicated electrical feeds and localized filtration stages. Ambulatory surgical centers select these for intermediate-cost sterilization coverage.
- Room Size Units:Floor-standing equipment sized to specific volumetric footprints without permanent mounting. Clinics in Japan deploy these for standardized patient room dimensions under METI modernization grants.
Most installed capacity flows through Centralized Systems. Expansion is steepest in Portable Units.
Application:
Clinical acuity tiers dictate sterilizer performance thresholds and certification rigor.
- Hospitals:Tertiary care facilities enforce ASHRAE Standard 170 compliance for airborne infection isolation rooms, mandating H13-H14 filtration or equivalent UV-C dosage. Procurement committees in the United States bundle sterilizer specifications into HVAC renewal contracts.
- Operating Theaters:Surgical suites require terminal sterilization-grade air quality with real-time particle monitoring. Vaporized hydrogen peroxide systems retain entrenched positions here, constraining air sterilizer penetration.
- Clinics:Outpatient settings prioritize compact footprint and rapid deployment over centralized infrastructure. Photocatalytic oxidation systems gain preference for mercury-free operation.
- Laboratories:Research environments demand chemical residue elimination alongside microbial control, opening plasma technology adoption.
Revenue concentration sits with Hospitals. Steepest expansion trajectory runs through Operating Theaters.
Technology:
Regulatory pathway efficiency separates commercially viable methods from compliance-burdened alternatives.
- UV-C Light:Mercury-vapor lamps emitting 254 nanometer wavelengths achieve 3-5 log reduction against bacterial and viral aerosols. FDA 510(k) pathway streamlining accelerates hospital adoption relative to oxidative methods.
- HEPA Filtration:Pleated fiber media rated H13-H14 captures 99.95-99.995% of 0.3 micron particles per EN 1822 standards. Multi-source procurement strategies stabilize component availability for original equipment manufacturers.
- Plasma Technology:Low-temperature ionized gas generates reactive species for microbial inactivation without chemical residues. Pharmaceutical cleanroom applications drive fastest segment traction.
- Chemicals:Ozone-generating and vapor-phase hydrogen peroxide systems face EPA FIFRA compliance burdens and dual certification bottlenecks.
Deployment volume concentrates in HEPA Filtration. Gaining share fastest is Plasma Technology.
End User:
Budget authority and procurement sophistication vary across institutional categories.
- Healthcare Facilities:Hospital systems with dedicated clinical engineering departments unbundle service contracts from equipment procurement. Third-party ISO 13485-certified maintenance firms capture recurring revenue pools.
- Pharmaceutical Companies:Active pharmaceutical ingredient manufacturers migrate contamination protocols into clinical settings, compressing technology adoption gaps.
- Research Institutions:Academic medical centers balance grant-funded equipment acquisition against institutional maintenance capabilities.
- Dental Offices:Small-practice settings prioritize compact fan-coil sterilizer modules for aging infrastructure retrofit.
Procurement volume concentrates in Healthcare Facilities. Expansion is climbing the fastest in Pharmaceutical Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as compliance cost differentials widen between jurisdictions with stringent EPA FIFRA frameworks and markets with streamlined device registration pathways. Production capacity is migrating toward regions offering faster certification timelines for emerging plasma and photocatalytic technologies.
United States
Hospital infrastructure renewal programs and ASHRAE Standard 170 ventilation mandates are accelerating procurement of HEPA-UV hybrid systems. The FDA's streamlined 510(k) pathway for irradiation devices clears antimicrobial claims faster than oxidative alternatives. The Boston-Cambridge medical technology corridor anchors sterilizer engineering talent concentration.
Germany
Healthcare facility HVAC modernization contracts bundle sterilizer specifications into multi-year service agreements. ECHA REACH substance restrictions on filter housing polymers extend certification timelines for dual-market access. The Rhine-Ruhr industrial basin concentrates captive UV-C lamp assembly manufacturing.
Japan
METI hospital modernization grants subsidize compact retrofit sterilizer modules for aging tertiary care infrastructure. JIS standards alignment with international filtration efficiency benchmarks reduces import friction for H13-H14 media. The Osaka-Kobe manufacturing belt dominates fan-coil sterilizer module fabrication.
China
Domestic healthcare infrastructure expansion is absorbing localized sterilizer production at cost points below imported equivalents. NMPA medical device registration reforms are compressing approval timelines for Class II sterilization equipment. The Yangtze River Delta clusters photocatalytic oxidation component suppliers.
India
Central government health mission procurement is standardizing sterilizer specifications across public hospital networks. CDSCO medical device rules are tightening quality management system requirements for domestic manufacturers. The Maharashtra-Gujarat pharmaceutical corridor is migrating cleanroom contamination protocols into clinical settings.
Medical Air Sterilizer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue photocatalytic and plasma technology niches where regulatory pathways remain less congested. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive healthcare divisions, specialized sterilization equipment pure-plays, and regional fabricators serving price-sensitive procurement channels. Dominant competitive moves include backward integration into critical component supply and multi-year service contract bundling to capture recurring revenue streams.
Among diversified industrial conglomerates, Steris PLC and Daikin Industries, Ltd. exemplify contrasting strategic positions. Steris PLC anchors the sterile processing integration archetype through captive manufacturing of UV-C lamp assemblies. Daikin Industries, Ltd. occupies the compact retrofit module specialization, leveraging HVAC system expertise for aging infrastructure penetration. Getinge AB represents the third archetype—sterile processing pure-plays with terminal sterilization-to-filtration portfolio breadth.
| Leading Market Players |
|---|
| Steris PLC |
| Getinge AB |
| 3M Company |
| Advanced Sterilization Products Services Inc. |
| Daikin Industries, Ltd. |
| Honeywell International Inc. |
| Sharp Corporation |
| Camfil AB |
| WellAir |
| Others |
Pricing and Supply Chain Analysis
Rare earth europium and terbium price indices cascade through UV-C lamp manufacturing into sterilizer pricing tiers, compressing margins for irradiation system producers while HEPA media supply diversification stabilizes filtration-focused equipment costs.
Pricing Analysis
Input-cost pass-through from europium-doped mercury lamp assemblies concentrates pricing pressure on UV-C sterilizer tiers, while HEPA-based systems maintain firmer margin structures through multi-source media procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared hospital-grade units from CE-marked clinical configurations and uncertified consumer-adjacent equipment. Cost compression in the UV-C segment is intensifying because rare earth processing jurisdiction concentration limits supplier switching. Dental offices and small clinics exhibit highest price sensitivity, while tertiary hospital systems with dedicated clinical engineering budgets absorb premium positioning for ASHRAE Standard 170-compliant architectures.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO medical device rules and China's NMPA Class II registration reforms are reshaping sourcing patterns toward localized filter housing fabrication and captive UV-C lamp assembly. Component supply concentrates in Germany for H13-H14 pleated media, Japan for compact fan-coil modules, and the United States for plasma generation subsystems. Rare earth doping elements for UV-C lamps draw from limited processing jurisdictions, creating single-source vulnerability for irradiation system manufacturers. Distribution runs through hospital GPO contracts in the United States, multi-year HVAC bundling agreements in Germany, and METI-subsidized procurement channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical Air Sterilizer Market represents a late-cycle quality story as hospital infrastructure renewal programs shift procurement specifications toward ASHRAE Standard 170-compliant HEPA-UV hybrid architectures over standalone economy-tier alternatives.
For Market Incumbents: Anticipate plasma technology entrants eroding pharmaceutical cleanroom share by accelerating photocatalytic oxidation R&D investments and securing captive titanium dioxide substrate supply agreements. Backward integration into HEPA media pleating equipment preserves margin pools against component cost volatility from REACH-constrained polymer formulations. For New Entrants and Emerging Players: ISO 13485-certified third-party service firms offer the most penetrable channel for recurring revenue capture, as United States hospital systems with clinical engineering departments unbundle maintenance from initial equipment procurement. Target ambulatory surgical center retrofits with mercury-free photocatalytic units positioned on ten-year total cost of ownership advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with plasma technology specialists holding pharmaceutical cleanroom validation credentials and low-temperature reactive species patents. Five-to-ten year viability hinges on EU MDR service contract bundling capabilities that lock recurring revenue streams. Monitor ASHRAE Standard 170 revision timing as the inflection signal for filtration-irradiation hybrid specification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct GPO contract access secures multi-year sterilizer specification bundling into HVAC renewal programs. |
| FDA 510(k) Pathway Streamlining | Expedited antimicrobial claim clearance accelerates irradiation technology adoption over oxidative alternatives. |
| Backward Integration into UV-C Lamp Assembly | Captive europium-doped mercury vapor production insulates lead times from rare earth supply volatility. |
| CE Marking Pathway Investment | Dual EU-US market access requires REACH-compliant polymer selection for filter housing formulations. |
| Software Companion Development | Sensor feedback loop integration with legacy building management systems shortens hospital commissioning timelines. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract review, and CMS Medicare facility survey data — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, sterile processing directors, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification filings, EPA FIFRA registration databases, ASHRAE Standard 170 ventilation guideline documentation, and ECHA REACH substance restriction updates. Bottom-up equipment shipment tracking and top-down healthcare infrastructure spending analysis were triangulated to anchor volume estimates.
Historical sterilizer deployment patterns were cross-referenced against expert panel input from clinical engineering departments and HVAC specification consultants. Segmentation modeling spanned product type, application acuity tier, technology pathway, and end-user budget authority across the projection horizon. CAGRs were derived from log-linear trend fitting adjusted for regulatory pathway efficiency differentials between irradiation and oxidative sterilization methods. Forecast inputs incorporated METI hospital modernization grant disbursement schedules and ASHRAE guideline revision implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply chain disruptions, EU MDR certification timeline extensions, and terminal sterilization technology substitution in surgical suite applications. Forecasts reflect documented assumptions regarding infrastructure renewal cycle pacing and regulatory pathway streamlining sustainability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market
Medical Equipment
Birthing Beds Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Dial Thermometers Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Electric Bed Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
CO2 Medical Laser Systems Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market