
 Fluoroscopy Equipment Market | 2026-2036
Fluoroscopy Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoroscopy Equipment Market Intelligence
The integration of AI-powered image analysis and automated dose management software is reconfiguring the development of next-generation fluoroscopy equipment. This shift moves value from pure hardware performance to intelligent, data-driven workflows that enhance diagnostic accuracy and patient safety. Siemens Healthineers leverages its extensive software ecosystem to integrate these features, while Philips Healthcare differentiates through its focus on comprehensive workflow solutions that connect imaging with patient data systems. Canon Medical Systems competes on the basis of its advanced detector technology and image processing algorithms.
Fluoroscopy equipment consists of medical imaging systems that use X-rays to provide real-time, dynamic visualization of internal body structures. These systems typically employ a flat-panel detector to convert X-ray radiation into a live video feed for immediate analysis. Their primary purpose is to guide minimally invasive procedures in areas like surgery, cardiology, and gastroenterology. C-Arm systems represent the largest product segment, valued for their mobility and flexibility in operating rooms. While hospitals remain the dominant end-user, demand from outpatient facilities and specialized diagnostic imaging centers is accelerating.
Regulatory frameworks heavily influence product design and market access, with a strong focus on radiation safety. The US FDA's Initiative to Reduce Unnecessary Radiation Exposure from Medical Imaging sets stringent expectations for dose monitoring features. In parallel, the EU's Medical Device Regulation (MDR) mandates more rigorous clinical evidence for safety and performance, impacting development timelines. Manufacturers must navigate these divergent requirements to maintain access to key markets. The critical decision for vendors is how to invest in software-driven dose reduction technologies without significantly increasing system costs.
Market Dynamics
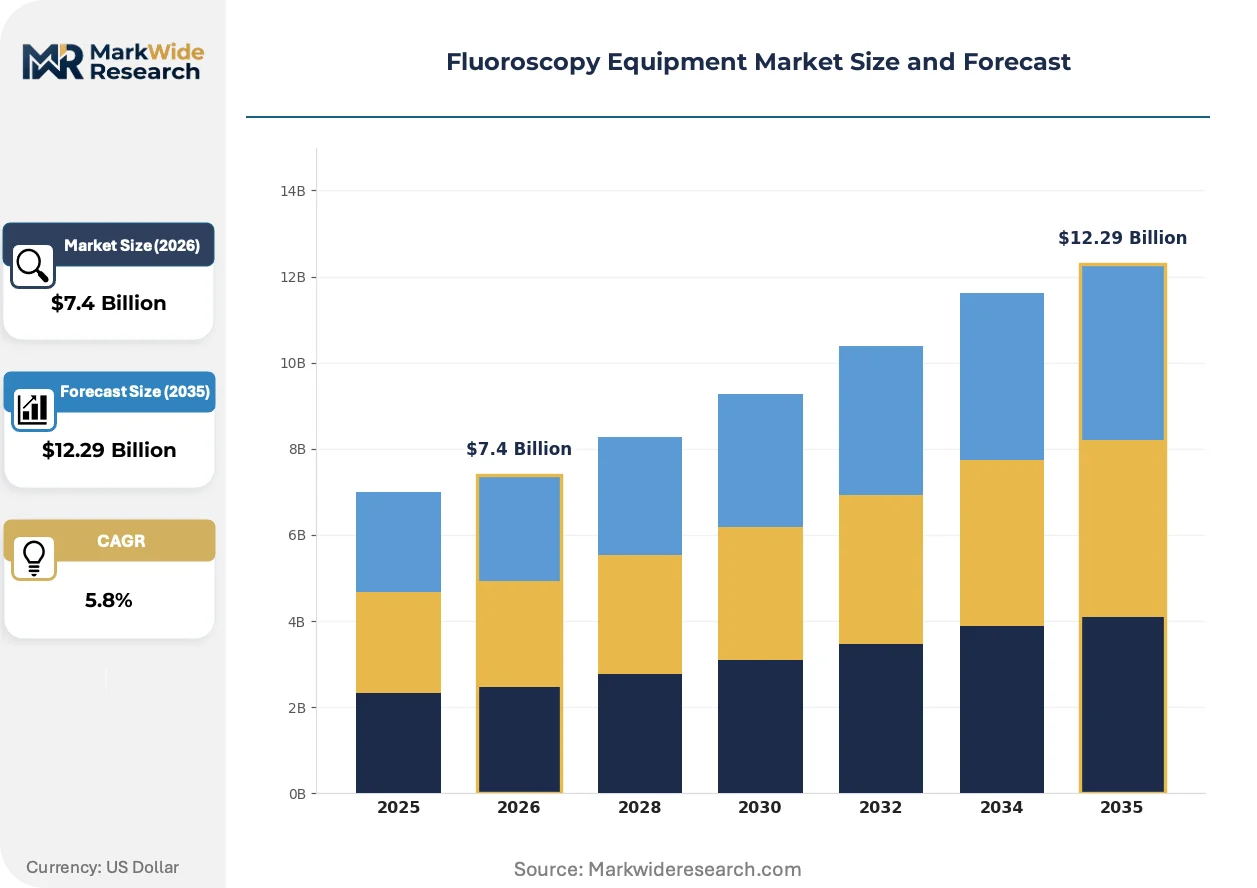
The market's central force is the convergence of software-driven workflows and stringent regulatory mandates on radiation safety. This dynamic shifts competitive value from hardware specifications to intelligent dose management and AI-enhanced diagnostic accuracy, reconfiguring product development priorities.
Growth Catalysts
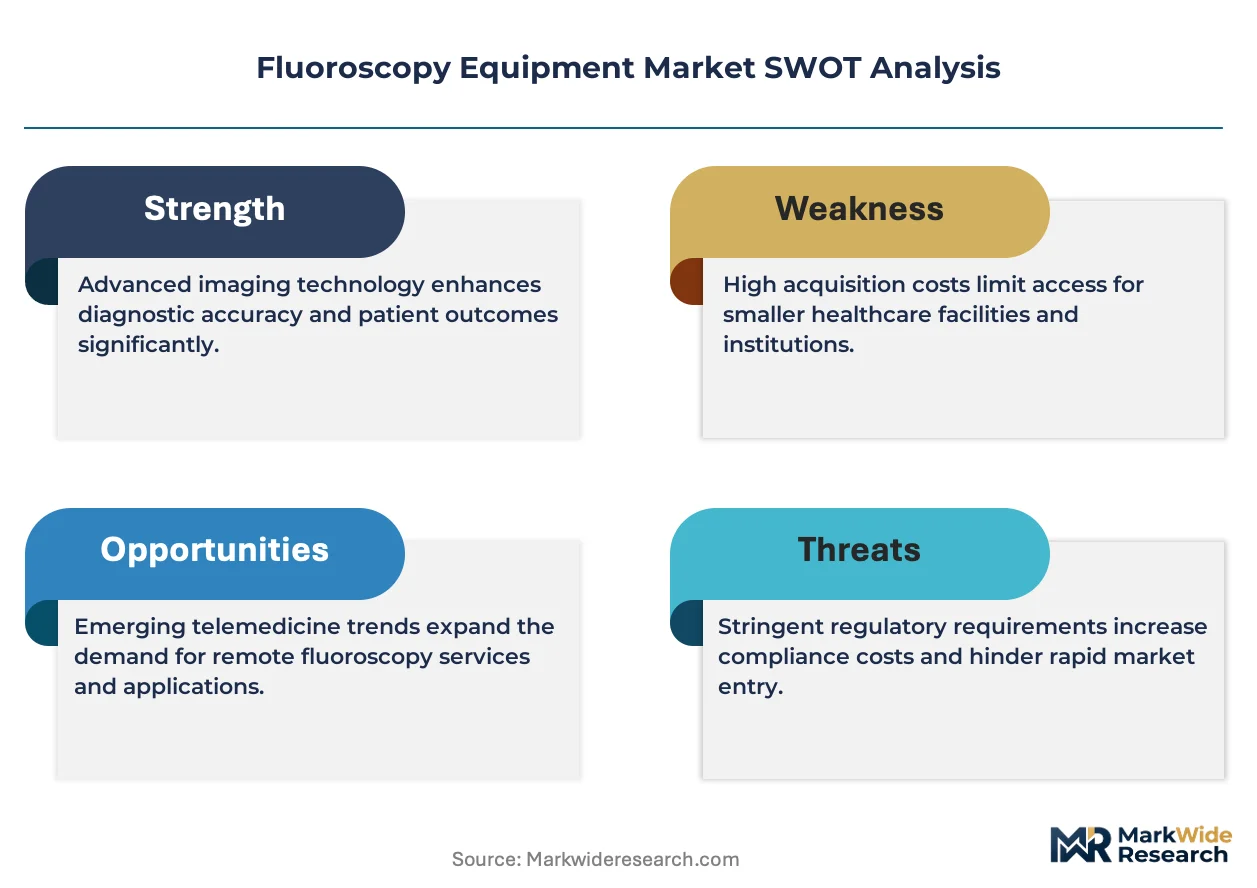
- Flat-Panel Detectors:The technological migration from image intensifiers to digital flat-panel detectors enhances image clarity and reduces patient radiation dose, stimulating system upgrades in orthopedic and surgical settings.
- Infrastructure Investment in China:Large-scale hospital construction and healthcare modernization initiatives in China create sustained demand for advanced diagnostic imaging systems to serve its large, aging population.
- Minimally Invasive Procedures:The rising volume of complex, minimally invasive surgeries in cardiology and gastroenterology requires the real-time visualization that fluoroscopy provides, driving system adoption in procedural suites.
Market Restraints
- High System Cost:The significant capital expenditure required for new digital fluoroscopy systems, especially those with advanced software packages, remains a primary barrier for smaller hospitals and clinics in developing economies.
- Regulatory Divergence:Navigating conflicting and rigorous regulations, such as the EU's MDR and the FDA's radiation safety initiatives, increases development costs and lengthens time-to-market for manufacturers.
- Alternative Modalities:For certain diagnostic applications, the availability of non-ionizing imaging techniques like magnetic resonance imaging and advanced ultrasound presents a substitution threat, limiting fluoroscopy's addressable use cases.
Strategic Opportunities
- Augmented Reality Integration:Combining fluoroscopic imaging with AR overlays for surgical guidance presents an opportunity to create next-generation systems that offer superior procedural precision and reduce cognitive load on surgeons.
- Emerging Economies:Markets in Southeast Asia and Latin America are actively upgrading their healthcare infrastructure, offering new growth avenues for vendors beyond the saturated primary markets of North America and Europe.
- Interventional Pain Management:The application of fluoroscopy to guide injections and nerve blocks for chronic pain management represents a growing clinical niche with significant expansion potential outside traditional hospital departments.
Industry Challenges
- Systems Integration Complexity:Ensuring seamless interoperability between new fluoroscopy equipment and existing hospital information systems, including PACS and electronic health records, poses a significant technical and logistical challenge for healthcare providers.
- Specialized Skills Gap:A shortage of technologists and radiologists proficient in operating advanced software features and complex dose-reduction protocols can limit the effective use and clinical benefit of modern systems.
- Clinical Evidence Burden:The EU's Medical Device Regulation imposes strict requirements for extensive clinical data to prove safety and performance, creating a substantial and costly hurdle for market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoroscopy Equipment Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: C-Arm Systems, Fluoroscopy Systems, Mobile Fluoroscopy, Fixed Fluoroscopy Application: Orthopedic Surgery, Gastroenterology, Cardiovascular Surgery, Pain Management End User: Hospitals, Diagnostic Imaging Centers, Outpatient Facilities, Academic Research Institutions Technology: Digital Fluoroscopy, Analog Fluoroscopy, Hybrid Fluoroscopy, Radiation Dose Management |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Shimadzu Corporation, Ziehm Imaging, Canon Medical Systems, Hitachi Medical Corporation, Carestream Health, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoroscopy Equipment Market Strategic Shifts & Innovations
Product development is pivoting from an emphasis on pure hardware performance to creating intelligent systems. This evolution prioritizes automated, data-driven workflows that improve patient safety and diagnostic efficiency, redefining the standard for next-generation equipment.
Artificial intelligence-powered image analysis software provides automated anatomical recognition and real-time image optimization. Interventional radiology and cardiology departments are increasingly adopting these tools to reduce procedure times and improve clinical outcomes. This software-centric approach is virtualizing the need for many manual system adjustments, embedding expert-level guidance directly into the imaging process.
The US FDA's Initiative to Reduce Unnecessary Radiation Exposure from Medical Imaging is a key regulatory driver. It compels manufacturers to integrate automated dose tracking and reporting functionalities as standard features within the system's core software. Mobile C-Arm systems, frequently used in long-duration orthopedic and vascular procedures, are the most impacted segment, requiring design updates to comply with these safety mandates.
A notable behavioral shift involves hospital networks moving away from single-unit purchases toward comprehensive, long-term managed equipment services. This disrupts the transactional sales model, disadvantaging vendors who compete solely on hardware and favoring those offering integrated service, software, and analytics packages. This procurement model is most prominent in large healthcare systems across North America and Western Europe seeking to standardize technology and control lifecycle costs.
Fluoroscopy Equipment Market Segmentation
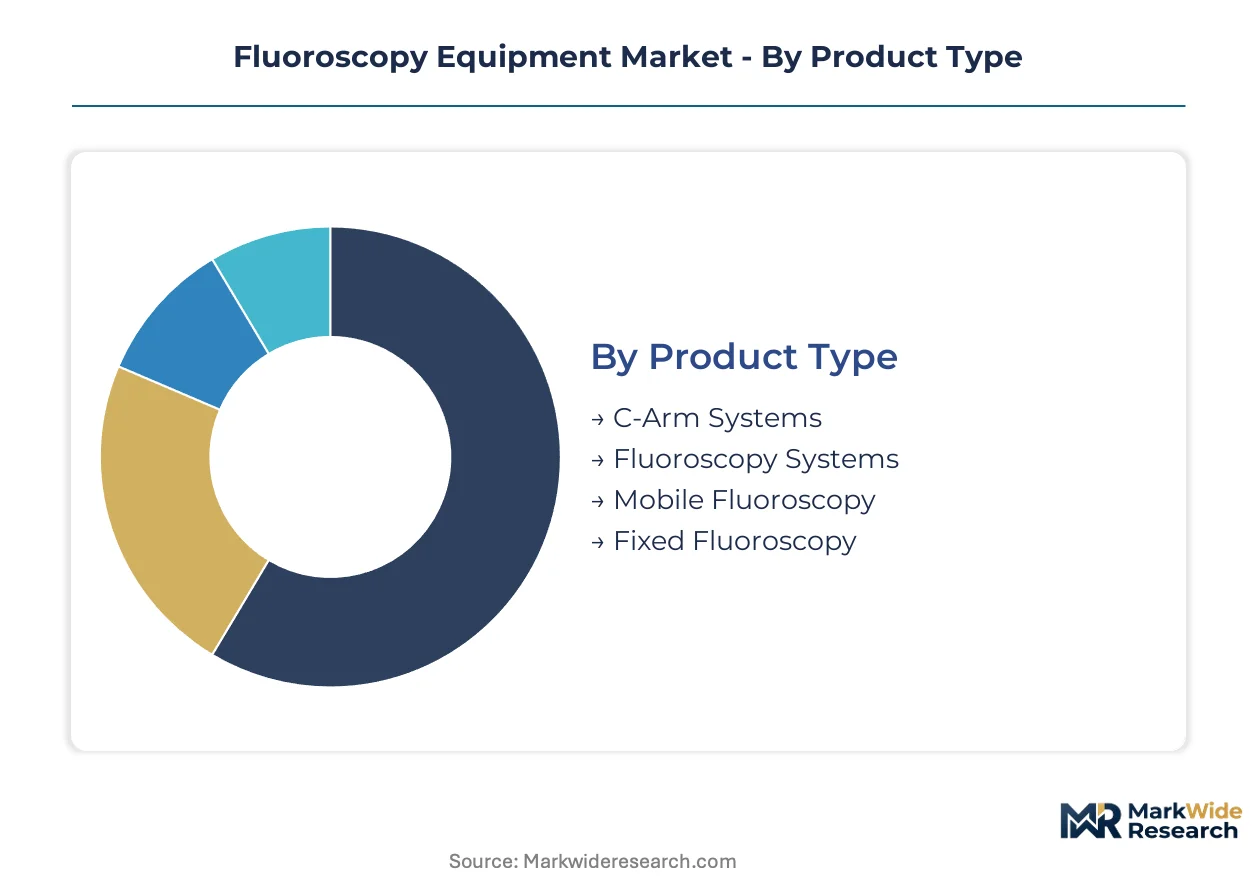
The fluoroscopy equipment market segments across product type, clinical application, end-user facility, and underlying technology. This detailed segmentation highlights the diverse operational requirements and technological preferences driving procurement decisions across various healthcare settings globally.
Product Type:
Product design and mobility define the primary categories of fluoroscopy equipment.
- C-Arm Systems:These mobile X-ray image intensifiers or flat-panel detectors provide real-time imaging during surgical procedures. Demand concentrates in operating rooms for orthopedic and vascular surgeries, driven by the need for flexible, intraoperative guidance.
- Mobile Fluoroscopy:Portable units offering real-time imaging capabilities, often used for bedside procedures or in emergency departments. Their mobility supports efficient workflow in dynamic clinical environments across Europe and North America.
- Fluoroscopy Systems:This general category encompasses both fixed and mobile units that provide dynamic X-ray visualization for diagnostic and interventional purposes. These systems are foundational in radiology departments.
- Fixed Fluoroscopy:Permanently installed systems offering high-power X-ray generation and large field-of-view detectors. These are typically found in high-volume diagnostic imaging centers requiring detailed, comprehensive studies.
Fixed Fluoroscopy holds installed capacity. Mobile Fluoroscopy is rotating up the share rankings.
Application:
Clinical utility dictates the specific procedural contexts where fluoroscopy systems are deployed.
- Orthopedic Surgery:Fluoroscopy provides real-time guidance for fracture reduction, joint replacements, and spinal procedures. Demand is strong in surgical suites across China and the United States, supporting complex minimally invasive bone and joint interventions.
- Cardiovascular Surgery:Used for visualizing blood vessels, guiding catheter placement, and deploying stents during interventional cardiology procedures. Cardiac cath labs in Germany and Japan rely on these systems for precision in complex cardiac interventions.
- Gastroenterology:Employed for dynamic imaging of the digestive tract during procedures like barium swallows and endoscopic retrograde cholangiopancreatography (ERCP). These applications support diagnostic and therapeutic interventions in digestive health.
- Pain Management:Guides injections and nerve blocks for chronic pain conditions, ensuring precise needle placement. Specialized pain clinics in Canada and Australia utilize fluoroscopy to enhance procedural accuracy and patient outcomes.
Orthopedic Surgery applications currently dominate volume. Interventional Pain Management shows the steepest expansion trajectory.
End User:
The organizational structure and patient volume of healthcare facilities shape the procurement of fluoroscopy equipment.
- Hospitals:Large medical institutions providing a comprehensive range of diagnostic and interventional services across multiple departments. Hospitals in India and Brazil represent the largest end-user segment for advanced fluoroscopy systems due to their broad procedural volumes.
- Outpatient Facilities:Ambulatory surgical centers and specialized clinics offering focused diagnostic and procedural services. These facilities are gaining traction in the US and UK for cost-effective, patient-centric care delivery.
- Diagnostic Imaging Centers:Standalone centers focused solely on providing various medical imaging services, including fluoroscopy. These centers prioritize high throughput and specialized imaging capabilities.
- Academic Research Institutions:Universities and research hospitals conducting clinical trials, developing new techniques, and providing medical education. They often require state-of-the-art fluoroscopy equipment for advanced studies.
Hospitals represent the foundational demand base. Outpatient Facilities are rapidly expanding their share of new installations.
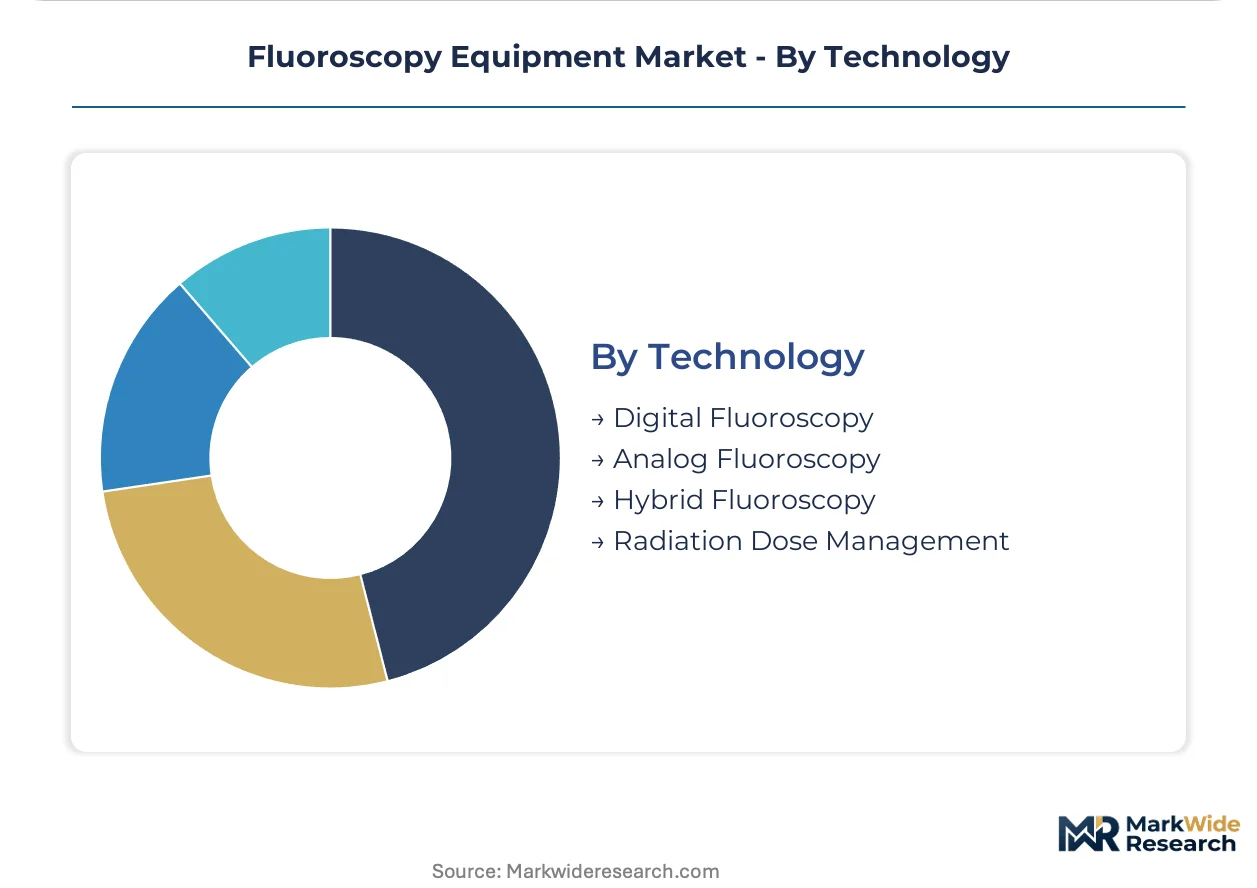
Technology:
Underlying imaging principles and dose management capabilities differentiate fluoroscopy system technologies.
- Digital Fluoroscopy:Utilizes flat-panel detectors to convert X-rays into digital images, offering superior image quality and lower radiation dose. This technology is standard in new installations across developed markets like the United States and Europe.
- Radiation Dose Management:Software and hardware features designed to monitor, track, and reduce patient and operator radiation exposure. Regulatory bodies like the US FDA and EU MDR mandate these features for patient safety across all new equipment.
- Analog Fluoroscopy:Older systems relying on image intensifiers to convert X-rays into visible light, then captured by a camera. These legacy systems are gradually being replaced by digital alternatives.
- Hybrid Fluoroscopy:Combines fluoroscopy with other imaging modalities, such as ultrasound or CT, for enhanced procedural guidance. These integrated systems support highly complex interventional procedures.
Digital Fluoroscopy has achieved market dominance. Radiation Dose Management features are becoming indispensable for new system compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade flow of advanced fluoroscopy equipment from European manufacturers to North American healthcare systems reflects a mature market dynamic. European innovation in digital imaging and dose management often finds early adoption in the United States. This corridor emphasizes technology transfer and regulatory alignment.
United States
Demand for advanced C-Arm systems in orthopedic surgery remains robust due to an aging population requiring joint replacements. The US FDA's Initiative to Reduce Unnecessary Radiation Exposure from Medical Imaging drives manufacturer compliance. Major medical device clusters in California and Massachusetts are developing next-generation software-driven systems.
Germany
Investment in digital fluoroscopy systems supports the country's high-standard healthcare infrastructure and specialized cardiac catheterization labs. The EU's Medical Device Regulation mandates rigorous clinical evidence, influencing product development for European manufacturers. Bavaria and North Rhine-Westphalia host significant medical technology manufacturing and R&D centers.
China
Large-scale hospital construction and healthcare modernization initiatives generate substantial demand for diagnostic imaging capabilities. The National Medical Products Administration (NMPA) regulates market access, prioritizing local manufacturing and technology transfer. Cities like Shanghai and Beijing are central to the expansion of advanced medical facilities.
Japan
The country's rapidly aging population and focus on precision medicine sustain demand for high-resolution fluoroscopy in interventional radiology. Japan's Ministry of Health, Labour and Welfare (MHLW) oversees medical device approvals, with a strong emphasis on patient safety. Tokyo and Osaka serve as key hubs for medical device innovation and clinical research.
India
Expanding healthcare infrastructure and a rising prevalence of cardiovascular diseases are driving the adoption of mobile fluoroscopy units in urban centers. The Central Drugs Standard Control Organization (CDSCO) regulates medical device imports and local manufacturing. Major metropolitan areas like Mumbai and Delhi are witnessing significant investment in new diagnostic facilities.
Fluoroscopy Equipment Market Key Industry Players
Channel-controlling players compete with product-specialist players in the fluoroscopy equipment market, creating a tiered competitive structure. Large diversified medical technology conglomerates often offer integrated solutions across imaging modalities, leveraging extensive distribution networks. Specialized manufacturers focus on specific product segments like mobile C-Arms or advanced detector technology, catering to niche clinical needs. Strategic partnerships to integrate AI software and portfolio diversification into comprehensive workflow solutions are common competitive moves among vendors.
On the premium-tier vector, Siemens Healthineers and Philips Healthcare, both well-established global players, exemplify the archetype of diversified medical technology providers that integrate extensive software ecosystems. These companies offer comprehensive imaging portfolios, connecting diagnostic and interventional systems with patient data management platforms. Canon Medical Systems, a Japan-based entity, represents another major player, known for its advanced detector technology and image processing algorithms within the broader imaging landscape, often competing on image quality and efficiency. These entities navigate complex regulatory environments while continuously investing in R&D to maintain their market positions.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Shimadzu Corporation |
| Ziehm Imaging |
| Canon Medical Systems |
| Hitachi Medical Corporation |
| Carestream Health |
| Hologic |
| Others |
Cost & Logistics Intelligence
European medical technology clusters, particularly in Germany, drive significant R&D investment. This capacity for innovation directly enables premium pricing for next-generation digital fluoroscopy systems in global markets.
Pricing Analysis
Cost-plus contracts, frequently indexed to advanced component costs like flat-panel detectors, define procurement for digital fluoroscopy systems. Pricing stratifies across premium, standard, and economy tiers based on integrated AI software features and after-sales support. Cost compression in the mid-tier segment stems from increasing competition and the availability of refurbished systems. Hospitals prioritize value-based outcomes, while smaller outpatient facilities exhibit higher price sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common for large hospital networks acquiring high-value fluoroscopy equipment. Supply concentrates in Germany, Japan, and the United States for core manufacturing, sourcing critical flat-panel detector arrays and specialized X-ray tubes globally. Single-source vulnerability for advanced detector components presents a structural risk. Downstream distribution primarily runs through direct sales channels for complex systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fluoroscopy equipment market offers fragmentation opportunities. The shift towards specialized minimally invasive procedures, particularly in pain management and cardiology, creates distinct niches for tailored system designs.
For Market Incumbents:Insulate core market share by deepening software integration for AI-powered image analysis and automated dose management. Expand comprehensive managed equipment services to counter the transactional sales model shift. This strategy mitigates threats from alternative non-ionizing imaging modalities. Investment in R&D for hybrid fluoroscopy systems offers a further protective lever.
For New Entrants and Emerging Players:Pursue underpenetrated markets in Southeast Asia and Latin America, focusing on essential digital fluoroscopy systems. Target the rapidly expanding interventional pain management segment with mobile C-Arm solutions for outpatient facilities. A go-to-market angle emphasizing cost-effectiveness combined with robust radiation safety compliance can secure early adoption.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialists in software-driven dose reduction and AI-powered image analysis. The market offers sustained long-term viability, driven by the increasing complexity of minimally invasive procedures. Acquisition targets should focus on agile firms with proven integration capabilities. The signal to watch is the adoption rate of mandatory dose monitoring features in emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand AI-powered software ecosystem | Enhances diagnostic accuracy and automates workflow for clinicians. |
| Form AR integration partnerships | Improves surgical precision and reduces cognitive load for surgeons. |
| Accelerate EU MDR clinical evidence generation | Secures market access and strengthens compliance for European manufacturers. |
| Develop comprehensive managed equipment services | Attracts large hospital networks seeking standardized technology and controlled lifecycle costs. |
| Invest in hybrid fluoroscopy R&D | Supports highly complex interventional procedures requiring multi-modality guidance. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, medical device company annual reports, and healthcare expenditure databases. Interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers provided qualitative insights. This approach triangulated data from both bottom-up market observations and top-down industry analysis.
Forecast inputs considered historical market performance, technological advancements, and evolving regulatory landscapes across the analysis window. The quantitative framework modeled segmentation by product type, clinical application, end-user facility, underlying technology, and regional healthcare spending. Compound annual growth rates were derived from historical trends and projected adoption rates for digital systems, with minimally invasive procedure volumes and aging population demographics serving as key inputs.
Sensitivities concentrate around unforeseen changes in healthcare policy, economic downturns, and rapid shifts in competitive dynamics. Forecasts reflect assumptions documented at the time of publication. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
Medical Suction Units Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Medical Gas Cylinders Market