
 Thermal Cycler Market | 2026-2036
Thermal Cycler Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Cycler Market Analytics
Aftermarket service revenue is narrowing toward real-time cycler calibration and optical module replacement as instrument complexity rises. Thermo Fisher Scientific leverages its installed base of QuantStudio systems to sustain recurring consumables revenue across clinical and research accounts. Bio-Rad Laboratories anchors its position through vertical integration into PCR plastics and reagent kits that lock in cycler utilization. QIAGEN competes by specializing in sample-to-insight workflows that bundle cyclers with extraction chemistry and bioinformatics.
A thermal cycler is a laboratory instrument that automates temperature cycling for DNA amplification via polymerase chain reaction, typically operating across 4°C to 99°C with ramp rates of 1-6°C per second and thermal uniformity within ±0.5°C. Real-time cyclers with integrated optical detection now dominate capital procurement budgets as laboratories shift from endpoint to quantitative analysis. Portable cyclers represent the fastest-growing product category, driven by point-of-care infectious disease testing and field-based agricultural diagnostics. Academic institutions remain the largest end-user segment by unit volume, though pharmaceutical companies command higher per-site spending through multiplex and high-throughput configurations.
The U.S. FDA and EPA shape thermal cycler demand through clinical diagnostic validation requirements and environmental DNA monitoring protocols, respectively. ISO 13485 and the EU In Vitro Diagnostic Regulation force manufacturers to requalify supply chains and quality management systems for CE-marked instruments. China's NMPA accelerates domestic registration timelines for locally manufactured qPCR platforms, redirecting procurement toward indigenous suppliers. Stakeholders must monitor how regulatory divergence between FDA and NMPA pathways affects global product architecture decisions and regional manufacturing footprints.
Market Dynamics
The thermal cycler market is undergoing a fundamental reorientation as real-time quantitative PCR displaces endpoint amplification in clinical workflows, compressing replacement cycles and elevating optical precision requirements for instrument suppliers.
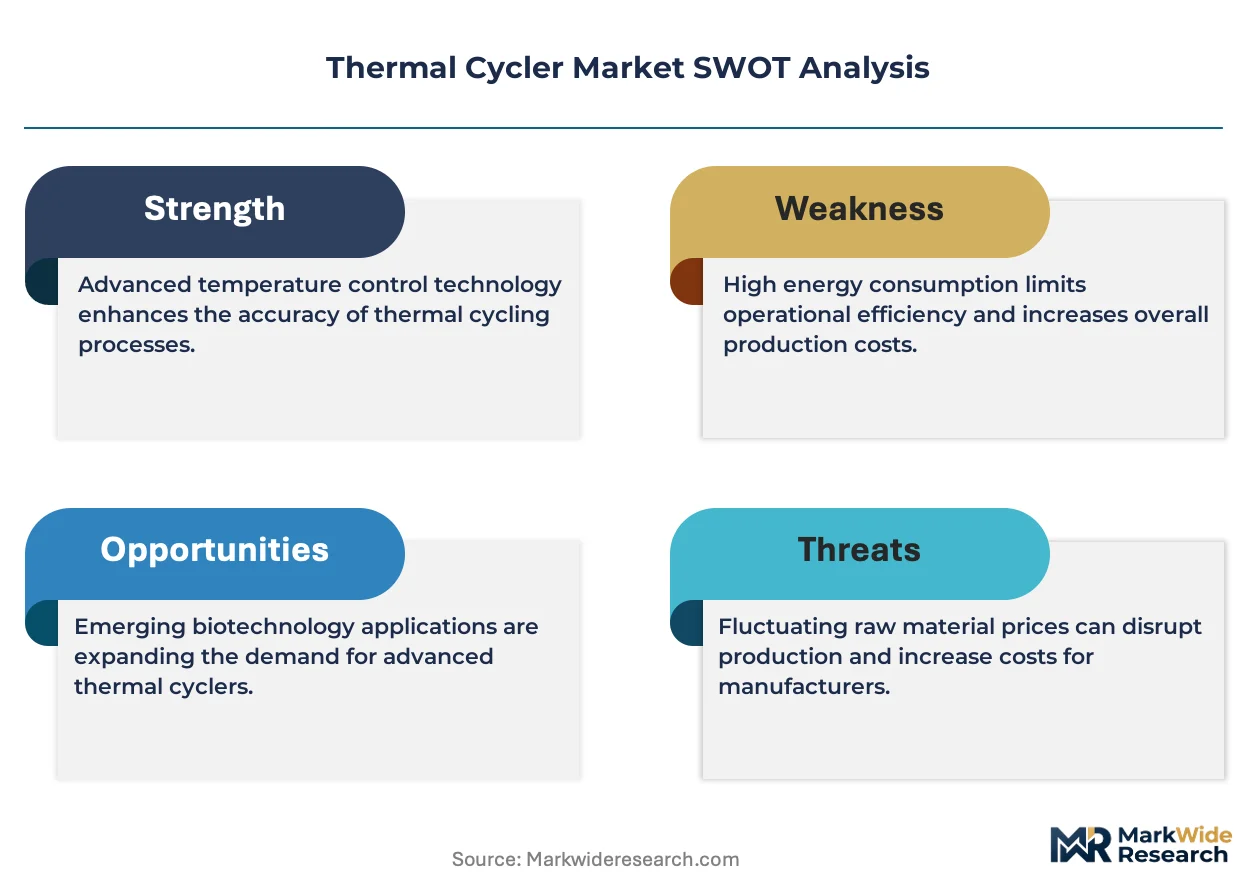
Growth Catalysts
- Companion diagnostic mandates:The U.S. FDA's expanding guidance on laboratory-developed tests requires validated qPCR platforms for oncology biomarker testing, pulling high-throughput cyclers into hospital central laboratories.
- Point-of-care decentralization:Portable thermal cyclers are penetrating infectious disease diagnostics at rural clinics and border screening stations, bypassing centralized reference laboratory bottlenecks.
- Environmental DNA protocols:The U.S. EPA's standardized eDNA monitoring frameworks for aquatic invasive species and biodiversity assessment are creating dedicated instrument procurement streams in government environmental agencies.
Market Restraints
- Optical component supply concentration:High-precision photodiodes and filter sets for real-time detection concentrate among Japanese and German specialty suppliers, exposing cycler manufacturers to single-source risk.
- Reagent kit lock-in costs:Proprietary consumables for validated clinical assays create switching friction that elevates total cost of ownership beyond instrument capital expenditure alone.
- Technical performance ceilings:Thermal ramp rates above 6°C per second introduce well-to-well temperature non-uniformity that compromises quantitative accuracy in 384-well formats.
Strategic Opportunities
- China NMPA domestic registration acceleration:Streamlined approval pathways for locally manufactured qPCR systems are redirecting public hospital procurement toward indigenous suppliers.
- CRISPR amplification convergence:Isothermal amplification methods paired with CRISPR detection are hybridizing with portable cycler form factors to enable instrument-agnostic nucleic acid testing.
- Veterinary diagnostics expansion:Agricultural biosecurity programs for African swine fever and avian influenza are creating dedicated procurement channels outside human clinical budgets.
Industry Challenges
- Field service technician scarcity:Optical module calibration and thermal block refurbishment require specialized training that outpaces technical education pipeline output in emerging markets.
- CE-IVDR transition complexity:The EU In Vitro Diagnostic Regulation's expanded clinical evidence requirements are extending recertification timelines for legacy cycler platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Cycler Market |
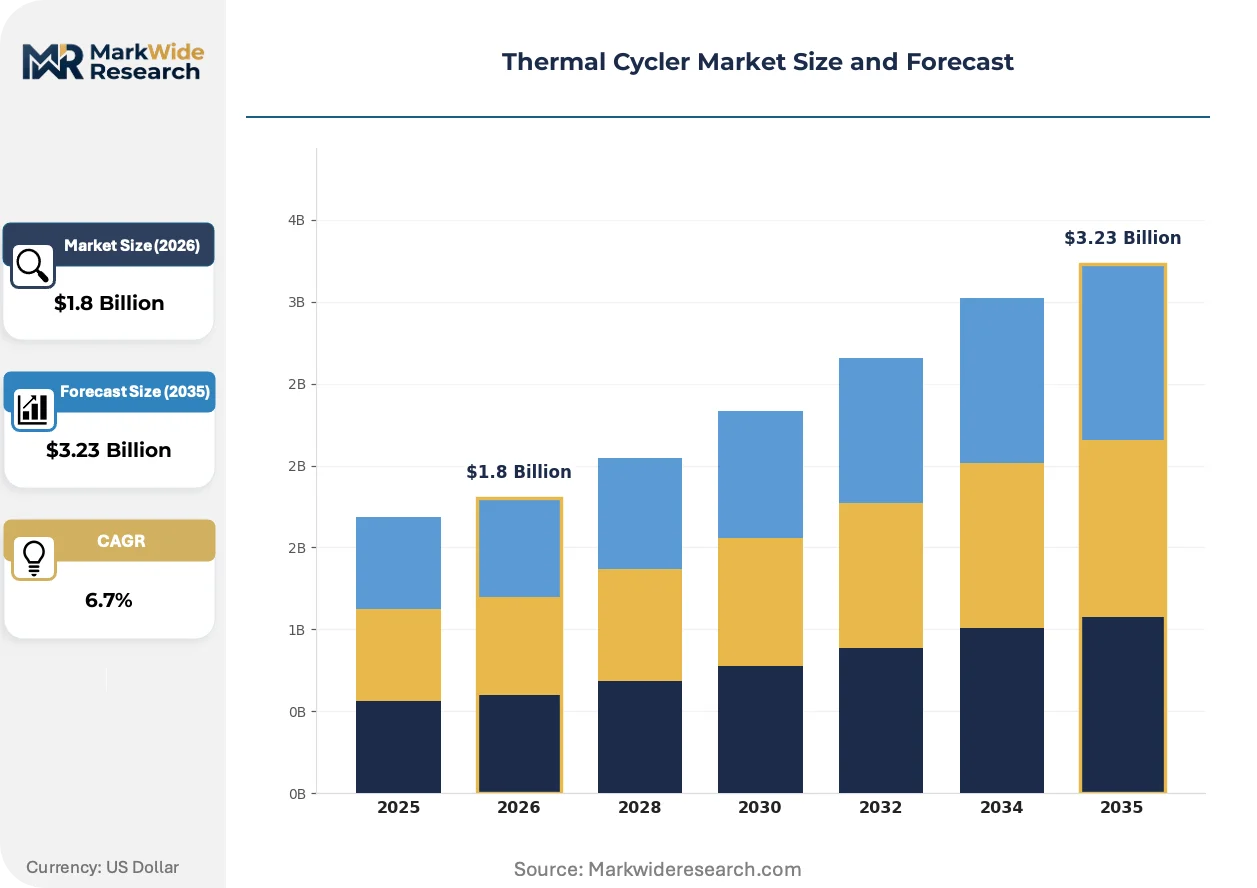
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cyclers, Real-Time Cyclers, Multi-Block Cyclers, Portable Cyclers Application: Clinical Diagnostics, Research Laboratories, Forensic Science, Agricultural Testing End User: Academic Institutions, Pharmaceutical Companies, Contract Research Organizations, Hospitals Technology: Conventional Technology, Advanced Technology, Optical Technology, Automation Technology |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Agilent Technologies, Roche Diagnostics, QIAGEN, Eppendorf, Analytik Jena, Abbott, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Cycler Market Evolving Landscape
Digital PCR technology is fragmenting the quantitative nucleic acid analysis landscape, while regulatory pressure on diagnostic accuracy and supply chain localization are reshaping instrument architecture decisions across manufacturing footprints.
Microfluidic cartridge integration is hybridizing with traditional block-based thermal cycling to enable walk-away automation in high-volume clinical laboratories. Hospital systems in the United States and Germany are adopting these integrated workflows to reduce hands-on time for molecular diagnostics staff. The convergence is compressing demand for discrete sample preparation instruments while elevating consumables attach rates for cycler OEMs.
The EU In Vitro Diagnostic Regulation's quality management system requirements are forcing manufacturers to requalify supplier audits and post-market surveillance protocols for CE-marked instruments. This regulatory friction is extending product development cycles by 12-18 months for platforms targeting European clinical laboratories. Manufacturers are responding by segmenting product architectures into EU-compliant and research-use-only variants to preserve market access.
Leasing and reagent rental agreements are displacing outright capital purchases in pharmaceutical quality control and food safety testing segments. End-users in Japan and South Korea prefer operational expenditure models that bundle instrument maintenance with guaranteed consumables supply. This financing shift is concentrating purchasing authority at regional procurement offices rather than individual laboratory managers.
Thermal Cycler Market Segmentation
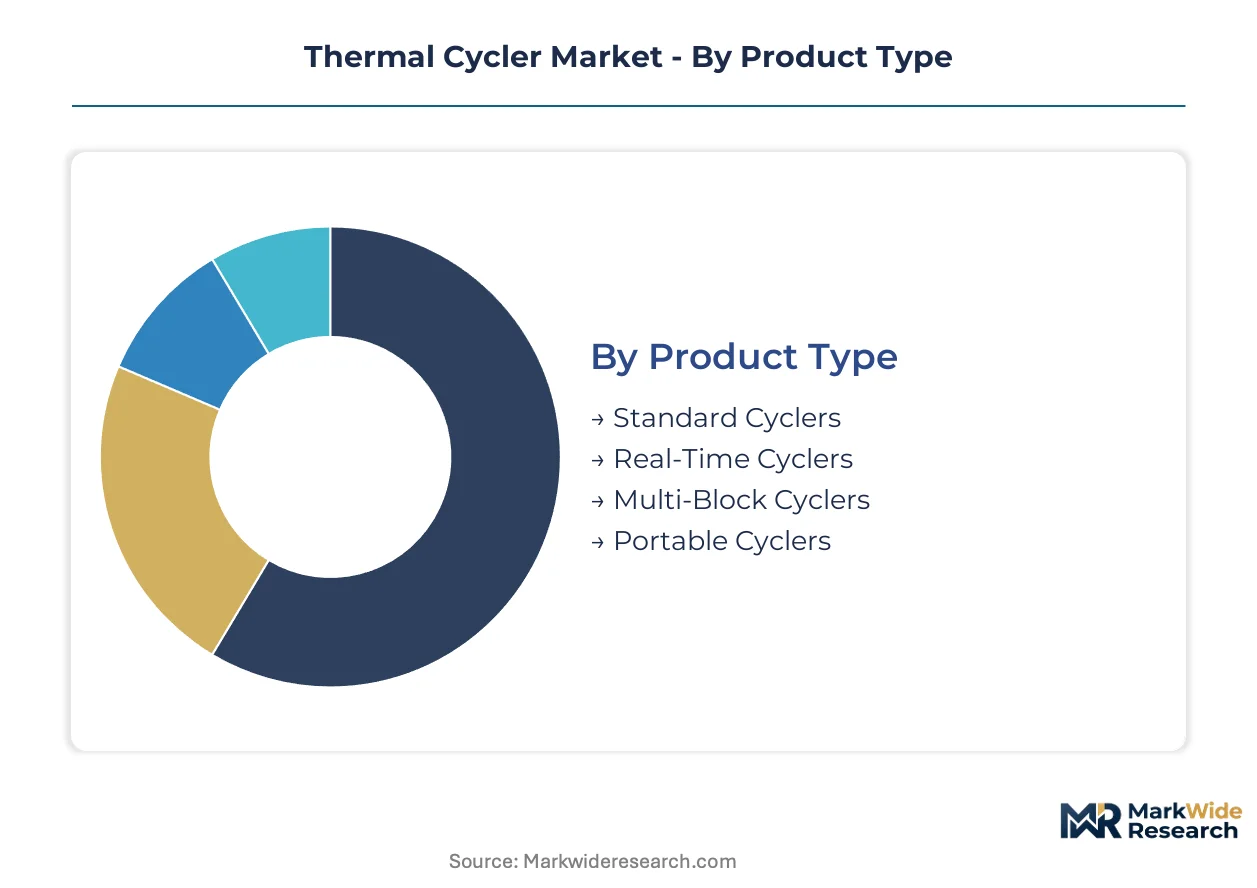
Thermal cycler segmentation reveals divergent procurement patterns between mature clinical workflows and emerging point-of-care deployments. Product architecture choices cascade through application requirements, end-user budgets, and technology integration priorities.
Product Type:
Mature block-based systems anchor hospital capital budgets while emerging portable formats penetrate decentralized testing networks.
- Standard Cyclers:Endpoint amplification instruments with fixed thermal blocks serve high-volume reference laboratories performing batch infectious disease screening. Academic core facilities in Germany and Japan sustain replacement demand for these workhorse platforms despite optical detection limitations.
- Real-Time Cyclers:Integrated optical modules enable quantitative PCR with cycle-by-cycle fluorescence monitoring. Hospital central laboratories in the United States prioritize these systems for companion diagnostic workflows under FDA guidance on validated qPCR platforms.
- Multi-Block Cyclers:Independent temperature zones accommodate simultaneous protocol optimization for assay development teams.
- Portable Cyclers:Battery-operated units with reduced well counts target field-based agricultural diagnostics and border screening stations.
Real-Time Cyclers handle the majority of throughput; Portable Cyclers are gaining share fastest.
Application:
Cost tier stratification separates regulated clinical assays from exploratory research workflows with divergent validation burdens.
- Clinical Diagnostics:FDA-cleared instruments for pharmacogenomics and oncology biomarker testing command premium pricing through locked reagent ecosystems. Hospital systems consolidate procurement around validated platforms to satisfy laboratory-developed test requirements.
- Research Laboratories:Exploratory gene expression studies and CRISPR validation drive demand for flexible open-system cyclers. Academic institutions prioritize multi-block configurations for protocol parallelization over optical precision.
- Forensic Science:CODIS-compliant DNA profiling requires documented chain-of-custody and audit trail capabilities.
- Agricultural Testing:Plant pathogen detection and GMO verification create dedicated procurement streams outside human clinical budgets.
Clinical Diagnostics absorbs the largest capital allocation; Agricultural Testing is expanding most quickly.
End User:
Customer type determines volume scale versus per-site spending intensity across institutional purchasing patterns.
- Academic Institutions:Core facilities and individual laboratories constitute the largest unit volume segment through distributed departmental budgets. Multi-block and standard cyclers dominate these price-sensitive procurement decisions.
- Pharmaceutical Companies:Quality control and high-throughput screening operations command the highest per-site instrument spending. These users prioritize real-time detection with 384-well formats and automation integration.
- Contract Research Organizations:Service providers require flexible platform configurations to accommodate diverse client assay portfolios.
- Hospitals:Central laboratory consolidation favors validated clinical systems with comprehensive service contracts.
Academic Institutions drive unit volume; Pharmaceutical Companies generate the steepest revenue per installation.
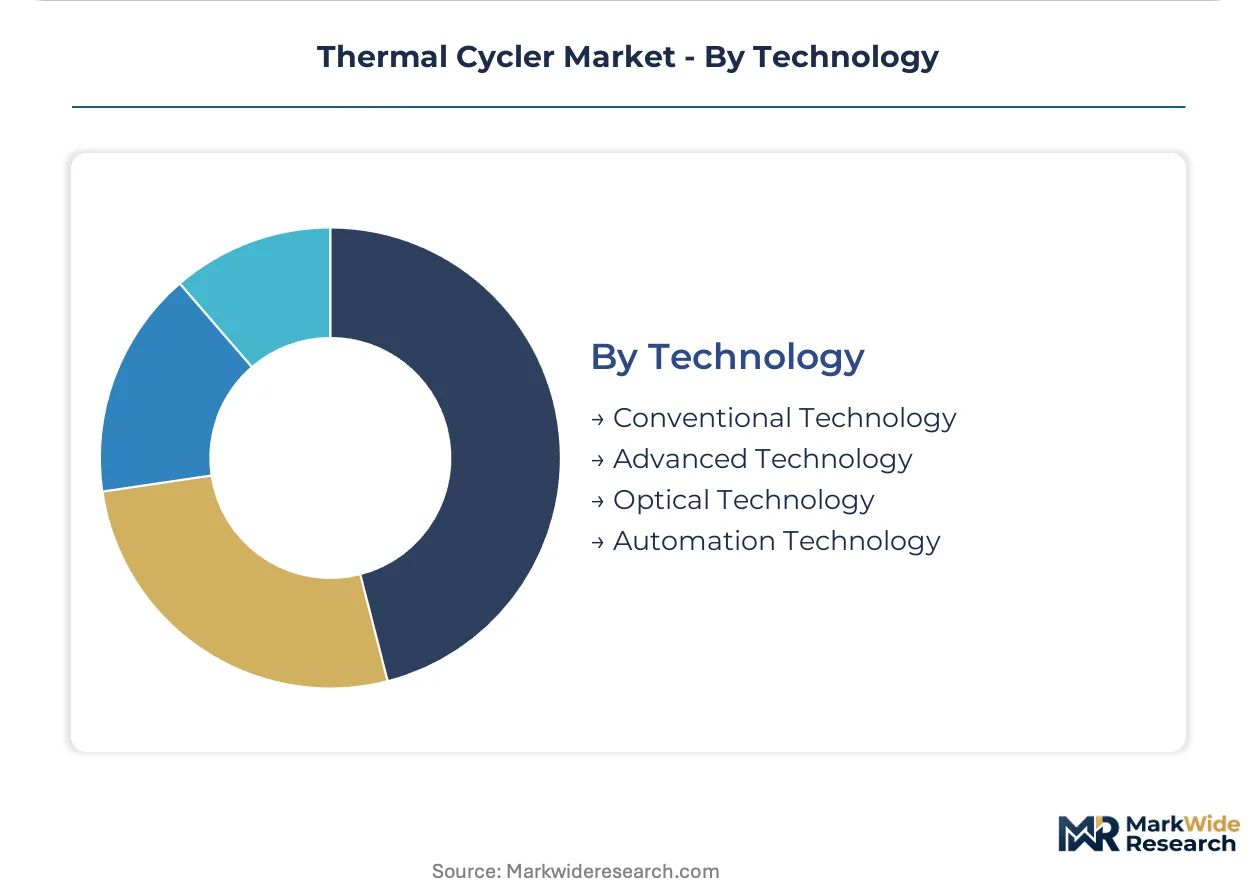
Technology:
Supply concentration in optical components and thermal control systems shapes competitive differentiation across technology tiers.
- Conventional Technology:Peltier-based thermal cycling with endpoint detection serves cost-optimized research applications. These systems minimize proprietary consumable lock-in for academic users with limited operational budgets.
- Advanced Technology:Rapid thermal ramp rates and improved thermal uniformity address quantitative accuracy requirements in 384-well formats. Manufacturing constraints on precision thermoelectric modules limit supplier diversity.
- Optical Technology:High-precision photodiodes and filter sets for multiplex fluorescence detection concentrate among Japanese and German specialty component suppliers.
- Automation Technology:Robotic integration and microfluidic cartridge handling enable walk-away operation in high-volume clinical settings.
Conventional Technology retains installed base dominance; Automation Technology shows the sharpest trajectory acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: clinical laboratories in the United States and Germany prioritize validated qPCR platforms for companion diagnostics, while China's biotech corridor scales domestic production for local hospital procurement and agricultural testing networks in Brazil deploy portable units for field-based pathogen surveillance.
United States
FDA guidance on laboratory-developed tests and companion diagnostics pulls high-throughput real-time cyclers into hospital central laboratories. The EPA's standardized environmental DNA monitoring frameworks create dedicated procurement streams in federal and state environmental agencies. Greater Boston and San Diego biotech clusters concentrate assay development activity for oncology biomarker testing.
China
NMPA acceleration of domestic registration timelines redirects public hospital procurement toward locally manufactured qPCR systems. The country's dual carbon goals influence energy-efficient instrument design requirements for government tenders. Yangtze River Delta biotech manufacturers scale production for both hospital systems and contract research organizations serving multinational pharmaceutical clients.
Germany
EU In Vitro Diagnostic Regulation compliance requirements extend recertification timelines for CE-marked instruments in clinical laboratories. Academic core facilities sustain replacement demand for multi-block configurations used in protocol optimization. Baden-Württemberg precision engineering suppliers concentrate production of high-precision photodiodes and thermal control modules.
Japan
METI industrial policy supports domestic production of optical components for real-time detection systems. Pharmaceutical quality control operations command premium spending on automation-integrated platforms. Osaka-based precision manufacturers supply filter sets and photodiodes to global cycler OEMs, creating single-source dependencies.
Brazil
ANVISA regulatory pathways for in vitro diagnostics shape instrument qualification requirements for clinical laboratories. Agricultural biosecurity programs for African swine fever and avian influenza create dedicated procurement channels outside human clinical budgets. São Paulo state research institutions deploy portable cyclers for field-based agricultural diagnostics.
Thermal Cycler Market Competitive Landscape
Capability concentration sits with specialty optical component suppliers; scale advantage sits with diversified life science conglomerates. The market structure tiers into three segments: full-platform providers with locked reagent ecosystems, precision component specialists supplying detection modules, and regional fabricators serving price-sensitive academic accounts. Dominant competitive moves include backward integration into PCR plastics and reagent chemistry, plus geographic expansion through localized manufacturing footprints aligned with NMPA and ANVISA registration requirements.
Among diversified life science conglomerates, Thermo Fisher Scientific, Bio-Rad Laboratories, and QIAGEN exemplify contrasting strategic archetypes. Thermo Fisher Scientific occupies a position anchored by installed base leverage and recurring consumables revenue. Bio-Rad Laboratories represents vertical integration into PCR plastics and reagent kits that lock in cycler utilization. QIAGEN sits within the sample-to-insight workflow specialization, bundling instruments with extraction chemistry and bioinformatics rather than competing on hardware specifications alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Roche Diagnostics |
| QIAGEN |
| Eppendorf |
| Analytik Jena |
| Abbott |
| Becton Dickinson |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's Yangtze River Delta precision manufacturing corridor is compressing margins for thermal cycler OEMs while simultaneously accelerating supplier consolidation among optical component vendors. This utilization asymmetry between instrument assembly and critical subsystem production is reshaping how manufacturers negotiate long-term supply agreements and position pricing tiers across clinical versus research market segments.
Pricing Analysis
Long-term reagent rental contracts dominate hospital and pharmaceutical procurement, bundling instrument placement with minimum consumables commitments. Price differentiation separates FDA-cleared clinical systems with locked assay workflows from open-platform research units with flexible chemistry compatibility. Pricing pressure stems from NMPA-registered domestic manufacturers undercutting multinational list prices in Chinese public tenders. Academic institutions exhibit highest price sensitivity through decentralized departmental purchasing, while pharmaceutical quality control operations accept premium positioning for automation integration and validation documentation.
Supply Chain Analysis
Contract manufacturing for thermal cyclers concentrates among precision engineering specialists in Germany, Japan, and China's Jiangsu province. High-precision photodiodes and filter sets draw from Japanese and German specialty component suppliers, creating single-source dependencies for real-time detection modules. Supply chain risk centers on tariff exposure for optical subsystems crossing multiple regulatory jurisdictions. Distribution runs through direct field sales for hospital systems and academic core facilities, with regional distributors serving price-sensitive research accounts in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection as CRISPR amplification methods hybridize with portable cycler architectures, eroding proprietary reagent lock-in and forcing interoperability investments across previously closed ecosystems.
For Market Incumbents: Harden consumables revenue streams through backward integration into PCR plastics and extraction chemistry, insulating against isothermal amplification substitutes. Accelerate service contract penetration in hospital central laboratories to embed switching costs before NMPA-registered domestic competitors achieve optical performance parity. Prioritize CE-IVDR recertification investment to preserve European clinical access during regulatory transition windows. For New Entrants and Emerging Players: Veterinary diagnostics and agricultural biosecurity networks in Brazil and Southeast Asia represent the most penetrable entry point, bypassing entrenched reagent ecosystems in human clinical markets. Portable cycler configurations for field-based pathogen surveillance offer lowest competitive density relative to technical validation requirements. Pursue ANVISA registration pathways early to establish reference laboratory credibility before scaling to hospital procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable and point-of-care instrument sub-segments as microfluidic cartridge integration commoditizes thermal control hardware. Target acquisition profiles should emphasize sample-to-insight workflow specialists with captive extraction chemistry and bioinformatics assets rather than pure hardware manufacturers. Monitor NMPA registration velocity for indigenous Chinese qPCR platforms as the signal indicating when global pricing compression will accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PCR Plastics | Captures consumables margin and locks in cycler utilization across clinical accounts. |
| NMPA Domestic Registration Acceleration | Redirects Chinese public hospital procurement toward locally manufactured qPCR systems. |
| Microfluidic Cartridge Integration | Enables walk-away automation in high-volume hospital laboratories while elevating attach rates. |
| CE-IVDR Recertification Investment | Preserves European clinical market access amid expanded quality management requirements. |
| Veterinary Diagnostics Channel Development | Creates dedicated procurement streams outside saturated human clinical budget competition. |
Research Methodology
The analysis maps standard cyclers, real-time systems, portable units, and automation-integrated platforms, each validated through instrument development engineers, hospital laboratory directors, CRO procurement managers, and regulatory affairs specialists. Primary fieldwork combined structured interviews with secondary triangulation across FDA 510(k) filings, NMPA registration databases, EU MDR/IVDR notified body documentation, and ISO 13485 audit records. Bottom-up unit demand modeling and top-down market sizing converged through iterative stakeholder feedback loops.
Forecast assumptions held regulatory divergence between FDA and NMPA pathways fixed while varying adoption rates for portable and point-of-care configurations across the projection horizon. Segmentation dimensions modeled include product architecture, application workflow, end-user budget tier, and regional registration cluster. CAGRs derived from instrument replacement cycle compression, consumables attach rate trajectories, and geographic procurement policy shifts. Industry-specific inputs incorporated environmental DNA protocol standardization and companion diagnostic mandate expansion.
Practitioners should monitor NMPA registration timelines, EPA eDNA procurement budget allocations, and optical component supplier consolidation for early signals of forecast revision. Forecasts reflect assumptions about regulatory stability and reagent ecosystem lock-in persistence. Quarterly review of domestic manufacturer pricing in Chinese tenders and CE-IVDR recertification completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Cryochambers Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
MRI Transport Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Medical Automation Market