
 Spinal Surgery Tables Market | 2026-2036
Spinal Surgery Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Surgery Tables Market Analytics
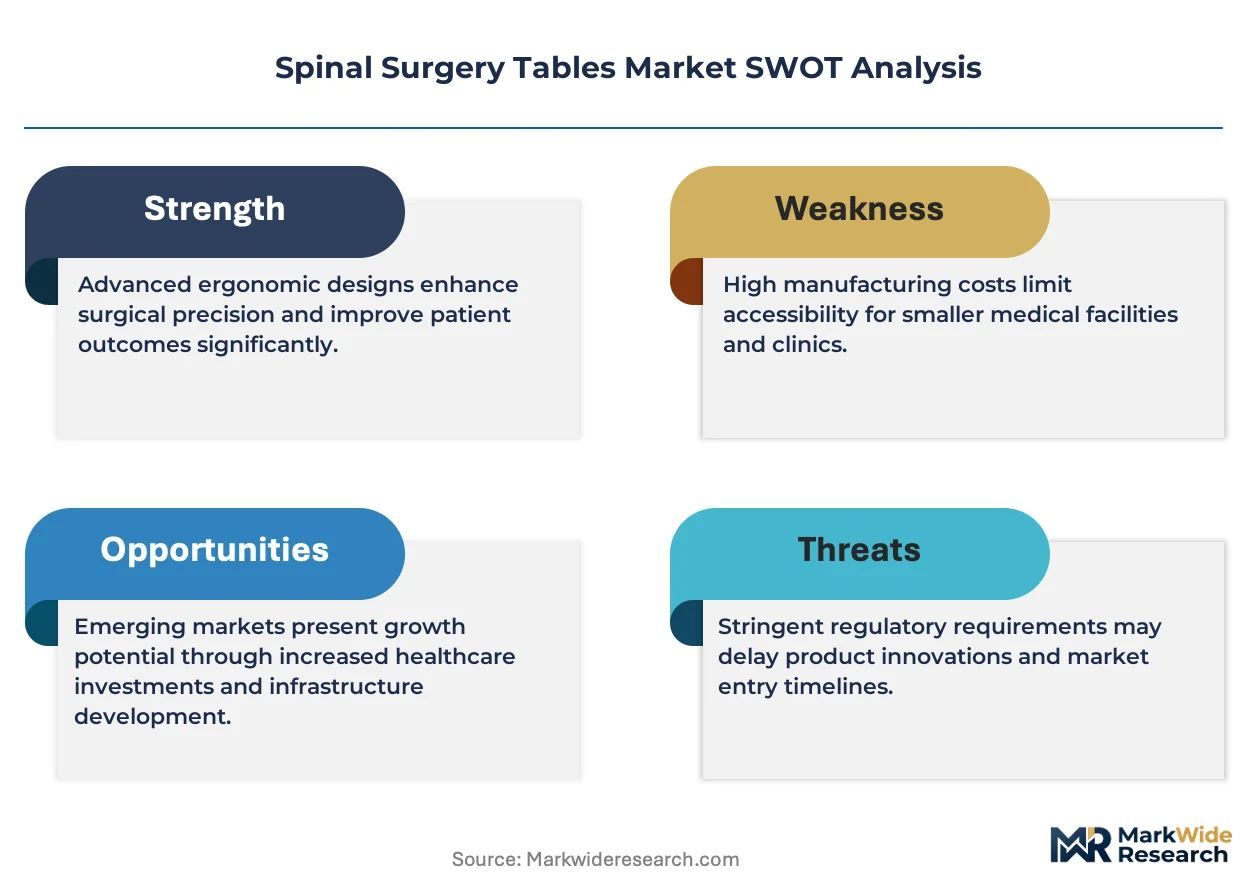
A shortage of certified biomedical technicians is unwinding service coverage in secondary markets and slowing table deployment outside tier-one hospital networks. Stryker leverages its field engineering density to sustain uptime guarantees across North American accounts. Mizuho OSI specializes in radiolucent carbon-fiber platforms that dominate intraoperative imaging workflows. Getinge controls aftermarket parts logistics through regional distribution hubs, locking in multi-year service contracts.
Spinal surgery tables are motorized or manually adjustable platforms engineered to position patients during dorsal and lateral approaches, typically supporting loads exceeding 500 pounds while permitting fluoroscopic access through radiolucent tabletop sections. Their primary purpose is to maintain precise spinal alignment under traction or flexion during fusion, decompression, or instrumentation procedures. Electric tables command the dominant share of replacement spending as hospitals phase out manual crank systems that disrupt surgical workflow timing. Ambulatory surgical centers represent the fastest-growing end-user category, driven by migration of single-level fusions to outpatient settings where space-constrained facilities prioritize compact, multi-position platforms. Integrated imaging technology commands premium positioning as vendors bundle tables with real-time navigation compatibility.
FDA 510(k) premarket notification requirements govern electromechanical table safety and electromagnetic compatibility, while IEC 60601-1 third-edition standards define electrical safety benchmarks for devices used in sterile surgical fields. The EU Medical Device Regulation imposes stricter clinical evidence thresholds on motorized positioning systems, lengthening approval timelines for manufacturers without established European notified body relationships. Stakeholders must weigh capital allocation between robotic-assisted table platforms and conventional motorized systems as reimbursement pathways for outpatient spinal procedures continue diverging across payor categories.
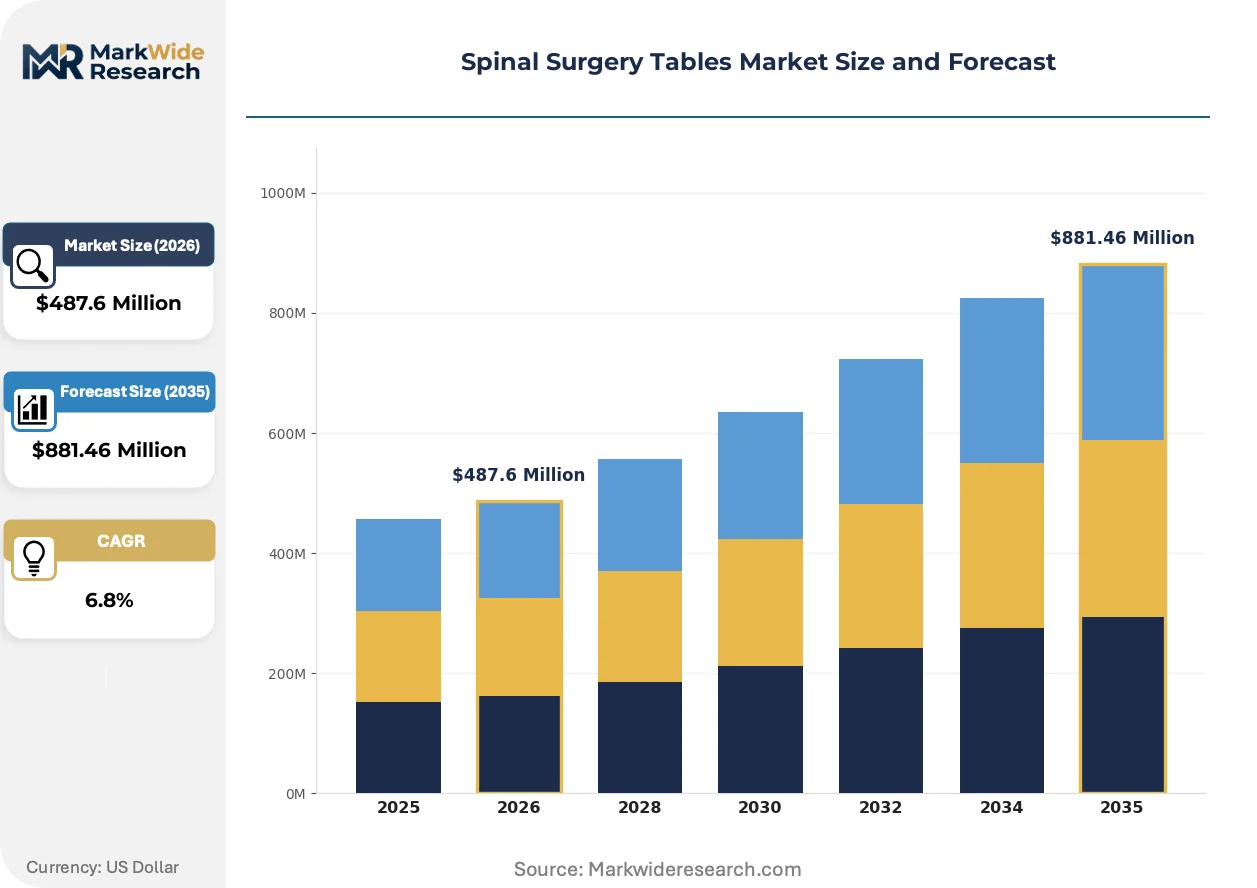
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing procurement cycles and favoring standardized fleet purchases over individual unit sales, reshaping vendor-customer relationships across the spinal surgery tables market.
Growth Catalysts
- Outpatient Procedure Migration:Single-level spinal fusions are relocating to ambulatory surgical centers, generating demand for compact, multi-position platforms that maximize limited floor space while maintaining full imaging compatibility.
- FDA 510(k) Streamlining:The FDA's premarket notification pathway for motorized positioning systems reduces clearance timelines, enabling domestic manufacturers to accelerate product launches against European competitors facing stricter MDR evidence requirements.
- Carbon-Fiber Tabletop Adoption:Radiolucent carbon-fiber construction is penetrating intraoperative imaging workflows, permitting uninterrupted fluoroscopic visualization during dorsal and lateral approaches without repositioning the patient.
Market Restraints
- Certified Biomedical Technician Scarcity:A shortage of qualified service personnel is unwinding coverage in secondary markets, delaying table deployment outside tier-one hospital networks and extending downtime for malfunctioning units.
- EU MDR Compliance Burden:The European Medical Device Regulation imposes steeper clinical evidence thresholds on motorized positioning systems, lengthening approval timelines for manufacturers lacking established notified body relationships.
- Manual Crank System Replacement:Hospitals face capital allocation pressure between phasing out legacy manual systems and investing in electric platforms, with budget cycles often delaying full fleet modernization.
Strategic Opportunities
- Real-Time Navigation Integration:Bundling tables with surgical navigation compatibility commands premium positioning, as vendors capture value from the convergence of positioning hardware and imaging software ecosystems.
- Multi-Year Service Contract Expansion:Regional distribution hubs for aftermarket parts enable vendors to lock in extended service agreements, transforming one-time equipment sales into recurring revenue streams.
- Compact Platform Development:Space-constrained ambulatory facilities present white space for purpose-built tables that sacrifice maximum load capacity for maneuverability and rapid room turnover.
Industry Challenges
- Electromagnetic Compatibility Certification:IEC 60601-1 third-edition testing for electrical safety in sterile surgical fields demands specialized engineering resources and extends product development timelines.
- Legacy System Integration:New motorized platforms must interface with existing operating room infrastructure, creating compatibility friction that complicates sales cycles and implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Surgery Tables Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tables, Manual Tables, Hybrid Tables, Radiolucent Tables Application: Orthopedic Surgery, Neurosurgery, Trauma Surgery, Spinal Fusion End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Technology: Robotic Assisted, Computerized, Adjustable Height, Integrated Imaging |
| Companies Covered | Getinge, STERIS Healthcare, Stryker, Hill-Rom, Mizuho OSI, OPT SurgiSystems, Skytron, ALVO Medical, Mindray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Surgery Tables Market Evolving Landscape
Motorized positioning technology is actively displacing manual systems across surgical workflows, while regulatory divergence between major markets and evolving procurement models are forcing vendors to recalibrate product and service strategies simultaneously.
Carbon-fiber tabletop construction is supplanting traditional metal surfaces in premium table configurations. The material's radiolucent properties enable continuous fluoroscopic imaging without patient repositioning. Ambulatory surgical centers are adopting these platforms fastest, driven by space constraints and throughput pressure. This material shift is compressing the competitive advantage of vendors without in-house composite manufacturing capabilities.
EU MDR clinical evidence requirements are tightening approval pathways for motorized positioning systems. The regulation demands expanded documentation of safety and performance data, particularly for electromechanical devices used in sterile fields. Manufacturers without established European notified body relationships face extended timelines, creating competitive headroom for incumbent players with regulatory infrastructure already deployed.
Consolidated procurement through integrated delivery networks is displacing individual hospital purchasing autonomy. Large health systems now mandate standardized equipment fleets across multiple facilities, compressing vendor negotiation leverage. This concentration is most visible in United States markets where hospital merger activity has accelerated, forcing table manufacturers to restructure sales organizations around enterprise account management rather than territorial representation.
Spinal Surgery Tables Market Segmentation
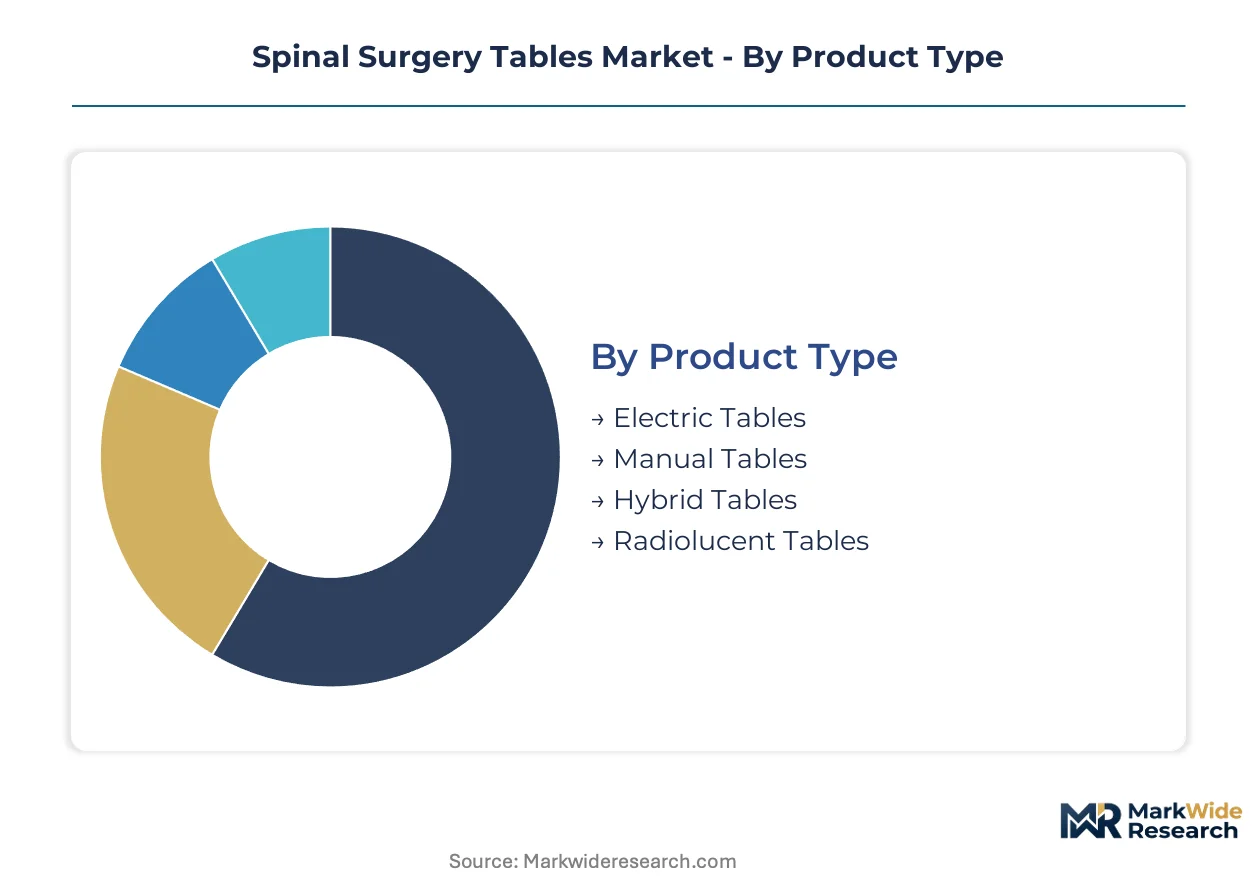
Segmentation in spinal surgery tables reveals how regulatory pathways, reimbursement structures, and surgical workflow requirements fragment demand across distinct equipment specifications. Each dimension carries unique procurement logic that shapes vendor positioning and product development priorities.
Product Type:
FDA 510(k) clearance timelines diverge sharply between electromechanical and manual systems, compressing competitive windows for motorized platforms while legacy crank mechanisms face extended replacement cycles.
- Electric Tables:Motorized positioning systems with programmable memory presets dominate replacement spending as hospitals phase out manual crank platforms that disrupt surgical workflow timing. Demand concentrates in United States integrated delivery networks where standardized fleet purchasing mandates electric platforms across multiple facilities.
- Manual Tables:Crank-operated mechanical systems retain foothold in budget-constrained secondary markets and developing healthcare infrastructure. Procurement persists in regions where capital allocation pressures delay full fleet modernization despite recognized workflow inefficiencies.
- Hybrid Tables:Dual-mode platforms combining manual backup with limited motorized functions occupy transitional market position.
- Radiolucent Tables:Carbon-fiber construction enables uninterrupted fluoroscopic imaging during dorsal and lateral approaches.
Established volume favors Electric Tables; emerging adoption favors Radiolucent Tables.
Application:
Surgical complexity and reimbursement differentiation create tiered equipment requirements across procedure categories, with spinal fusion commanding premium platform specifications.
- Spinal Fusion:Multi-hour procedures requiring sustained traction, flexion positioning, and continuous imaging compatibility drive demand for highest-specification motorized platforms with load capacities exceeding 500 pounds. United States ambulatory surgical centers represent steepest expansion trajectory as single-level fusions migrate to outpatient settings.
- Orthopedic Surgery:General musculoskeletal procedures utilize standardized positioning platforms with moderate imaging access requirements. Demand clusters in high-volume hospital systems where throughput pressure prioritizes rapid room turnover over specialized functionality.
- Neurosurgery:Cranial and spinal cord procedures require extreme precision positioning with micro-movement capability.
- Trauma Surgery:Emergency spinal stabilization demands rapid deployment platforms with simplified controls.
Reimbursement rates favor Spinal Fusion; procedure volume favors Orthopedic Surgery.
End User:
Facility scale and capital deployment horizons segment procurement behavior from enterprise fleet purchasing to single-unit acquisition.
- Hospitals:Large acute-care facilities drive standardized fleet purchasing through consolidated procurement offices, favoring multi-year service contracts and vendor interoperability guarantees. United States hospital consolidation into integrated delivery networks compresses negotiation leverage toward volume-based pricing structures.
- Ambulatory Surgical Centers:Space-constrained outpatient facilities prioritize compact, multi-position platforms with rapid turnover capability. These centers are expanding most quickly as spinal procedure migration accelerates and reimbursement pathways stabilize for outpatient fusion.
- Clinics:Limited-procedure settings utilize basic positioning platforms without advanced imaging integration.
- Research Institutions:Academic medical centers demand experimental compatibility and data capture functionality.
Capital commitment depth favors Hospitals; facility count expansion favors Ambulatory Surgical Centers.
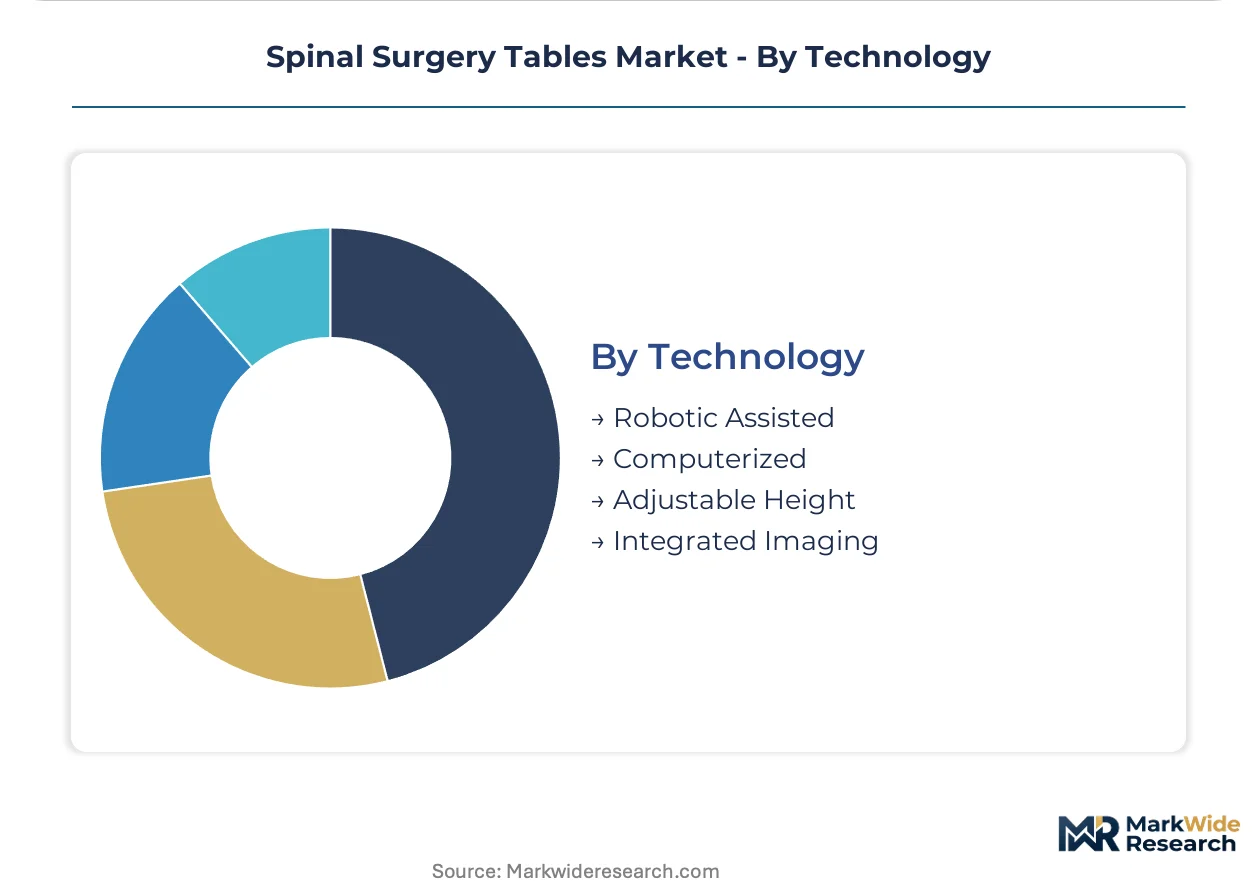
Technology:
Integration complexity and regulatory burden stratify development investment across technology tiers, with navigation compatibility commanding premium positioning.
- Integrated Imaging:Real-time fluoroscopy compatibility with radiolucent tabletops and navigation system interface commands highest price points. United States premium hospital systems lead procurement as vendors bundle positioning hardware with imaging software ecosystems.
- Computerized:Programmable position memory and automated safety interlocks balance functionality against cost. Demand concentrates in mid-tier hospitals seeking workflow efficiency without full navigation integration.
- Robotic Assisted:Active positioning control linked to surgical robotic systems represents emerging specification tier.
- Adjustable Height:Basic vertical positioning without programmable features serves cost-sensitive segments.
Current revenue concentration favors Computerized; technology roadmap priority favors Integrated Imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals deploy motorized platforms with navigation compatibility at rates exceeding other markets, while European facilities face extended procurement cycles under stricter clinical evidence requirements. Ambulatory surgical center expansion concentrates in North American metropolitan corridors. Carbon-fiber tabletop adoption clusters in premium hospital systems across Germany and Japan.
United States
Hospital consolidation into integrated delivery networks compresses procurement cycles and mandates standardized fleet purchasing across multi-facility systems. FDA 510(k) clearance pathways accelerate time-to-market for domestic motorized positioning manufacturers. The Dallas-Fort Worth metroplex anchors ambulatory surgical center construction, with outpatient spinal fusion volumes expanding fastest in Texas and Florida corridor markets.
Germany
Academic medical centers drive demand for radiolucent carbon-fiber platforms with intraoperative imaging compatibility. EU MDR compliance burdens lengthen approval timelines for motorized systems lacking established notified body relationships. The Baden-Württemberg cluster around Stuttgart concentrates precision engineering capabilities for surgical table component manufacturing.
Japan
Aging demographics and spinal disorder prevalence sustain replacement demand for electric positioning systems in acute-care facilities. PMDA regulatory frameworks govern electromechanical safety certification for devices deployed in sterile surgical fields. The Osaka-Kobe manufacturing belt hosts specialized fabricators supplying carbon-fiber tabletop assemblies to domestic and export markets.
China
Tier-one hospital networks in coastal provinces prioritize motorized table procurement, while inland facilities retain manual systems under capital constraints. NMPA registration requirements for Class II medical devices structure market entry pathways for domestic and international manufacturers. The Yangtze River Delta corridor around Shanghai concentrates distribution infrastructure for imported surgical equipment.
India
Private hospital chains in metropolitan centers drive electric table adoption, contrasting with government facilities reliant on manual platforms. CDSCO medical device regulations impose quality standards on motorized positioning systems entering the domestic market. The Maharashtra-Gujarat industrial corridor hosts emerging domestic fabricators targeting cost-competitive electric table segments.
Spinal Surgery Tables Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling aftermarket service logistics and multi-year contract structures. The middle tier fragments across regional manufacturers competing on capital equipment pricing. Three archetypes dominate: full-stack integrators bundling hardware with navigation ecosystems, component specialists commanding carbon-fiber tabletop supply, and regional value-oriented fabricators. Competitive moves concentrate on service contract expansion and radiolucent material integration rather than pure equipment pricing.
Among integrated North American operators, Stryker and Getinge exemplify the full-stack archetype through field engineering density and regional parts distribution infrastructure. Mizuho OSI occupies a specialist position representing radiolucent platform engineering capabilities. These three anchors illustrate how competitive positioning stratifies between service-integrated leaders and technology-focused component suppliers across procurement cycles.
| Leading Market Players |
|---|
| Getinge |
| STERIS Healthcare |
| Stryker |
| Hill-Rom |
| Mizuho OSI |
| OPT SurgiSystems |
| Skytron |
| ALVO Medical |
| Mindray |
| Others |
Value Network & Pricing Analysis
Carbon-fiber composite manufacturing scale in Germany and Japan anchors production economics for radiolucent tabletops, concentrating supply-side leverage among vendors with captive composite fabrication while compressing price floors for competitors sourcing externally. This scale concentration feeds into procurement dynamics where integrated delivery networks extract volume concessions from manufacturers lacking backward integration into specialty materials.
Pricing Analysis
Long-term service contracts dominate capital equipment transactions, with multi-year aftermarket agreements bundling parts, field engineering, and uptime guarantees. Price differentiation separates premium navigation-compatible platforms from standard motorized systems and economy manual crank alternatives. Cost compression in the standard tier intensifies as ambulatory surgical centers prioritize capital efficiency over maximum feature sets. Hospital procurement committees exhibit lowest price sensitivity, while independent ambulatory facilities face acute budget constraints.
Supply Chain Analysis
Strait of Malacca transit routes underpin carbon-fiber precursor supply from Asian petrochemical complexes to European and North American composite fabricators. Component manufacturing concentrates in Germany, Japan, and the United States, with precision electromechanical actuators sourced from Swiss and German industrial automation specialists. Single-source vulnerability persists for medical-grade carbon-fiber weaves certified under IEC 60601-1 electrical safety standards. Distribution runs through regional equipment distributors holding FDA-registered device establishment credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as outpatient spinal fusion migration creates demand niches underserved by hospital-focused incumbents, with ambulatory surgical centers requiring purpose-built compact platforms rather than adapted acute-care equipment.
For Market Incumbents: Consolidate service contract portfolios to lock in recurring revenue against emerging competitors offering disruptive pricing on bare equipment sales. Expand field engineering density in Texas and Florida corridor markets where ambulatory construction accelerates fastest. Prioritize backward integration into carbon-fiber tabletop fabrication to defend margin position against component specialists. For New Entrants and Emerging Players: Lead with compact platform development targeting space-constrained ambulatory surgical centers in United States metropolitan corridors. The radiolucent-electric hybrid segment offers lowest competitive density among motorized categories. Pursue direct-to-facility sales bypassing legacy distributor networks that favor established vendor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors controlling regional parts distribution infrastructure and multi-year service agreements. Long-term viability favors full-stack integrators bundling positioning hardware with navigation software ecosystems. Monitor FDA 510(k) clearance velocity for motorized positioning systems as an inflection indicator for domestic manufacturing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise fleet purchasing through integrated delivery networks locks in standardized equipment mandates across multi-facility systems. |
| FDA Submission | Premarket notification pathways for motorized positioning systems compress clearance timelines against European MDR competitors. |
| CE Marking Pathway | Established notified body relationships accelerate EU market entry for electromechanical devices under stricter clinical evidence requirements. |
| Software Companion Development | Navigation compatibility integration commands premium positioning as surgical robotics converge with positioning hardware ecosystems. |
| Reimbursement Strategy | Outpatient spinal procedure coding alignment stabilizes capital deployment horizons for ambulatory surgical center equipment procurement. |
Research Methodology
The analysis maps electric, manual, hybrid, and radiolucent table platforms, each validated through biomedical engineering directors, hospital purchasing committee members, ambulatory surgical center administrators, and GPO contracts managers. Primary fieldwork combined with secondary validation from FDA 510(k) clearance databases, hospital procurement records, CMS Medicare reimbursement filings, and integrated delivery network capital expenditure disclosures. Bottom-up unit demand modeling triangulated against top-down market sizing across manufacturer revenue reporting.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. Segmentation dimensions modeled include product type, application category, end-user facility scale, and technology integration level. CAGRs derived from procedure volume trajectories, replacement cycle analysis, and reimbursement pathway evolution. Industry-specific forecast inputs incorporated spinal fusion migration rates to outpatient settings and carbon-fiber adoption curves in intraoperative imaging workflows.
Underlying assumptions cover stable FDA 510(k) clearance timelines, continued hospital consolidation into integrated delivery networks, and sustained reimbursement support for outpatient spinal procedures, with deviation risk concentrated in EU MDR approval delays and certified biomedical technician scarcity extending service coverage gaps. Practitioners should keep alternative scenarios live as regulatory divergence between United States and European pathways evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Medical Equipment Management Software Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Tanning Units Market
Medical Equipment
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Global Medical Carts Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Global Ultra Low Temperature Freezers Market