
 Veterinary Point-Of-Care Diagnostics Market | 2026-2036
Veterinary Point-Of-Care Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Point-Of-Care Diagnostics Market Intelligence
CE marking under the EU Medical Device Regulation is collapsing the set of qualified suppliers for European veterinary clinics. IDEXX Laboratories dominates instrument placement in North American companion animal practices. Zoetis leverages its pharmaceutical footprint to bundle diagnostic consumables with vaccine portfolios. Thermo Fisher Scientific anchors molecular testing workflows in academic veterinary hospitals through reagent supply agreements.
Veterinary point-of-care diagnostics encompass portable analytical systems that process whole blood, serum, or urine samples at or near the patient site, typically delivering results within fifteen minutes through cartridge-based reagent chemistry. These devices serve the primary commercial purpose of enabling rapid clinical decisions during single-visit consultations, reducing referral delays and improving patient outcomes. Immunoassays occupy the largest revenue pool among product types due to their versatility across infectious disease and endocrine panels. Microfluidics technology represents the fastest-growing segment as manufacturers miniaturize multi-analyte platforms. Clinical chemistry maintains mature, stable demand in high-throughput animal hospitals where volume justifies larger benchtop systems.
FDA oversight of veterinary diagnostic devices shapes product development timelines and labeling requirements for US market entry, while the EU AI Act increasingly governs algorithm-driven interpretation modules in automated analyzers. ISO 13485 quality management certification functions as a baseline gate for supplier qualification across OECD veterinary markets. Stakeholders must monitor how evolving software-as-medical-device classifications in major jurisdictions will recalibrate validation burdens for AI-enhanced pathology readers.
Market Dynamics
Microfluidics miniaturization is compressing assay turnaround times from hours to minutes, forcing cartridge economics and platform lock-in strategies to dominate competitive positioning in companion animal practices.
Growth Catalysts
- Pet insurance penetration:Reimbursement structures in the United States, Germany, and Japan normalize advanced diagnostic spending during single-visit consultations, expanding addressable test volume per patient.
- CE marking under EU MDR:Collapsing supplier pools accelerate instrument placement cycles for qualified manufacturers serving European veterinary clinics.
- AI-enhanced pathology modules:Algorithm-driven interpretation reduces veterinarian cognitive load and enables standardized result reporting across distributed practice networks.
Market Restraints
- Reagent cartridge costs:Proprietary consumable pricing constrains margin recovery for independent clinics outside corporate practice groups.
- Supply concentration in North America:Instrument manufacturing clusters in Massachusetts and California create geographic vulnerability to logistics disruptions.
- ISO 13485 certification timelines:Quality management validation extends product launch schedules by 12-18 months for new market entrants.
Strategic Opportunities
- Brazilian agribusiness expansion:Large-animal production facilities in Mato Grosso and Paraná present untapped demand for rapid infectious disease screening.
- EU AI Act compliance:Early alignment with algorithm governance standards creates differentiation for automated analyzer vendors entering European markets.
- Telemedicine integration:Remote consultation platforms enable point-of-care data transmission to specialist networks, extending diagnostic reach beyond urban centers.
Industry Challenges
- Veterinary clinical pathologist shortage:Specialized training programs fail to match deployment needs for complex immunoassay interpretation.
- Legacy LIS integration:Practice management software from the 2010s lacks API architectures for seamless analyzer connectivity.
- Software-as-medical-device reclassification:Evolving FDA guidance on algorithm-driven modules forces retrospective validation of deployed systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Point-Of-Care Diagnostics Market |
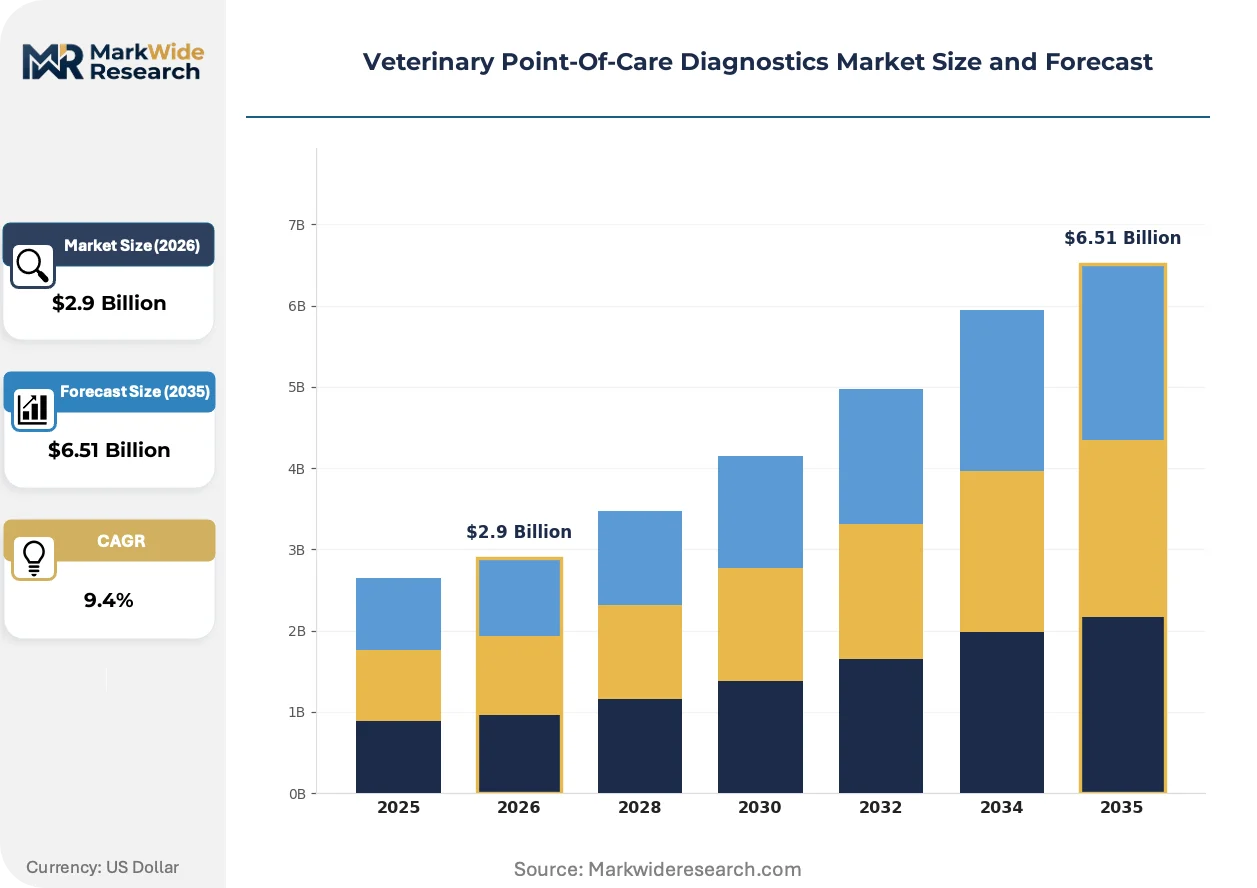
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Molecular Tests, Clinical Chemistry, Hematology Analyzers Technology: Microfluidics, Point-of-Care Testing Devices, Automated Analyzers, Optical Detection End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Universities Application: Infectious Diseases, Oncology, Endocrinology, Health Monitoring |
| Companies Covered | IDEXX Laboratories, Zoetis, Virbac, Thermo Fisher Scientific, Mindray, FUJIFILM Corporation, Antech Diagnostics, Heska Corporation, Woodley Equipment Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Point-Of-Care Diagnostics Market Strategic Shifts & Innovations
Cartridge-based chemistry is displacing wet reagent workflows, compressing laboratory footprints and enabling non-specialist staff operation. Regulatory frameworks are recalibrating around algorithmic decision support, while procurement consolidation among corporate practice groups is reshaping vendor contracting terms.
Microfluidic multi-analyte platforms are displacing single-parameter test strips in companion animal emergency settings. Emergency and critical care veterinarians in university hospitals and specialty referral centers adopt these systems within 18-month replacement cycles. This displacement compresses the addressable market for legacy lateral flow devices while locking clinics into closed reagent ecosystems.
The EU AI Act's risk classification framework for algorithmic medical devices is recalibrating development roadmaps for automated pathology systems. Manufacturers must now document training data provenance and performance across diverse animal populations prior to CE marking. Veterinary software vendors serving European markets are responding by segregating EU-specific algorithm versions from global product builds.
Corporate practice groups are consolidating procurement decisions at regional headquarters, displacing individual clinic autonomy in instrument selection. Mars Veterinary Health and Vetcor negotiate enterprise pricing tiers that independent practices cannot replicate. This concentration is most visible in the United States, where the top ten practice owners control over thirty percent of companion animal diagnostic spending.
Veterinary Point-Of-Care Diagnostics Market Segmentation
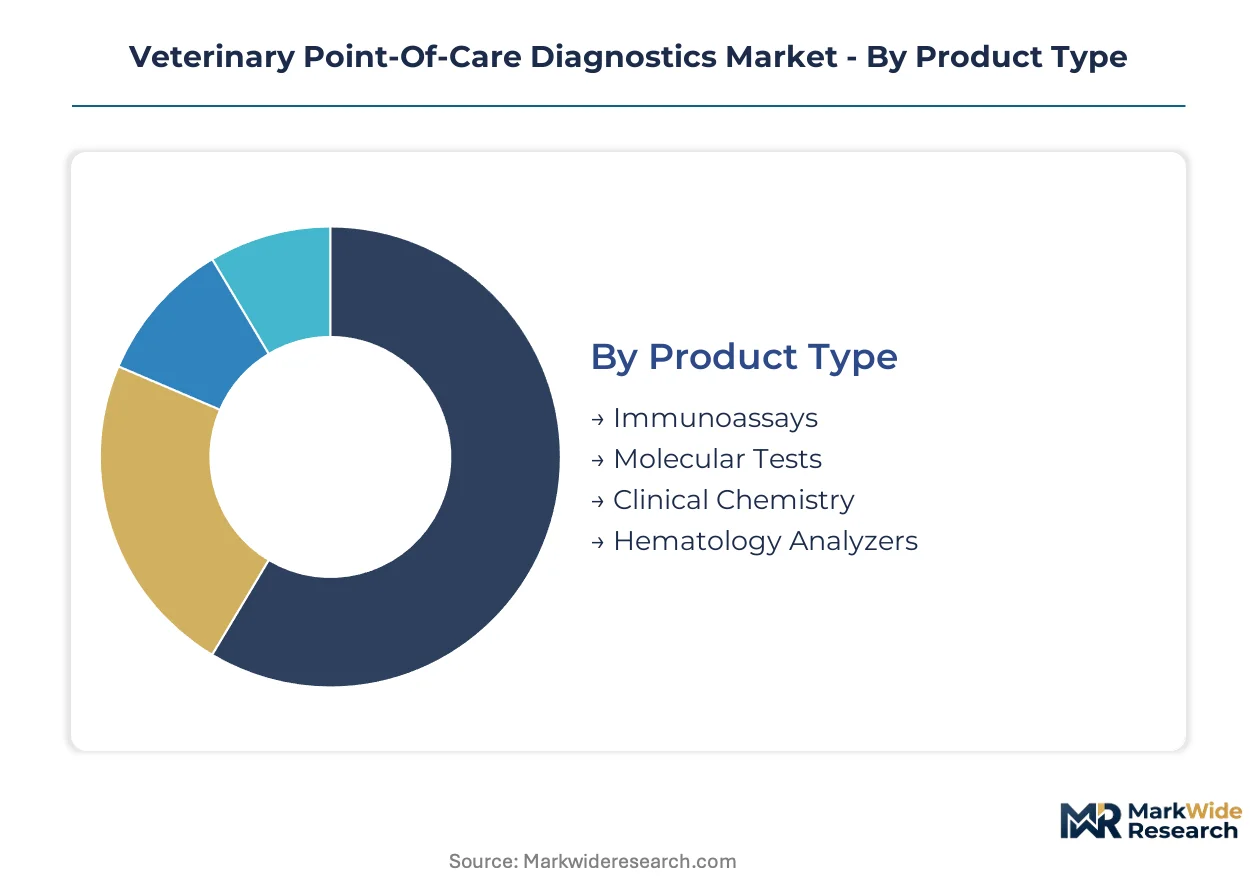
Segmentation in veterinary point-of-care diagnostics reveals distinct margin architectures across product types and technologies. Understanding these profit pools enables targeted resource allocation for manufacturers navigating platform lock-in dynamics and cartridge economics.
Product Type:
Margin concentration follows test complexity and consumable attachment rates, with cartridge-based platforms commanding superior lifetime value per instrument placement.
- Immunoassays:These antibody-antigen detection systems process serum and plasma samples for infectious disease and endocrine panels. Demand clusters in United States companion animal practices where pet insurance reimbursement supports advanced screening protocols. The segment benefits from established reimbursement codes and high test frequency in wellness programs.
- Molecular Tests:Nucleic acid amplification platforms deliver pathogen identification through PCR-based chemistry at the patient site. Academic veterinary hospitals in Germany and Japan deploy these systems for rapid outbreak investigation in dense urban pet populations. Sensitivity specifications drive premium positioning against culture-based alternatives.
- Clinical Chemistry:Benchtop analyzers quantify electrolytes, enzymes, and metabolites in whole blood samples. These systems serve high-throughput animal hospitals in Massachusetts and California where daily test volumes exceed fifty samples.
- Hematology Analyzers:Automated cell counters generate complete blood counts within minutes of sample collection. Emergency and critical care settings in Texas and Florida prioritize these instruments for trauma triage decisions.
The dominant share belongs to Immunoassays, while Molecular Tests is closing the gap fastest.
Technology:
Volume deployment varies sharply by capital intensity and operator skill requirements, with miniaturized platforms penetrating independent clinics previously excluded from in-house diagnostics.
- Microfluidics:Chip-based fluid handling integrates sample preparation, reaction, and detection in disposable cartridges. Companion animal emergency departments in university hospitals adopt these platforms within eighteen-month replacement cycles, displacing legacy lateral flow devices. Miniaturization enables non-specialist staff operation while compressing laboratory footprints.
- Point-of-Care Testing Devices:Handheld or small-footprint instruments deliver single-parameter results at the examination table. Rural veterinary practices across Kansas and Nebraska favor these systems for immediate client consultation value. Portability constraints limit menu breadth but maximize utilization in mobile practice models.
- Automated Analyzers:High-throughput systems process batch samples with minimal technician intervention. Corporate practice groups in Illinois and Ohio standardize on these platforms across multi-site networks to ensure result uniformity.
- Optical Detection:Spectrophotometric and fluorometric readout methods underpin analyte quantification in cartridge and cuvette formats. Reagent manufacturers in Pennsylvania specialize in optical signal stability for extended shelf-life products.
Microfluidics holds the largest installed base, though Point-of-Care Testing Devices is expanding most quickly into previously underserved geographies.
End User:
Procurement authority consolidation is reshaping vendor relationships, with enterprise purchasing displacing individual clinic autonomy in the largest addressable segments.
- Veterinary Clinics:General practice settings generate the highest test volume per capita in insured pet populations. Mars Veterinary Health and Vetcor negotiate enterprise pricing tiers that independent practices in Arizona and Colorado cannot replicate.
- Animal Hospitals:Specialty referral and emergency centers command premium pricing for rapid turnaround services. These facilities in New York and Washington state maintain twenty-four-hour diagnostic capabilities for critical care admissions.
- Research Laboratories:Contract research organizations and pharmaceutical testing sites require GLP-compliant documentation chains. Preclinical toxicology studies in New Jersey drive demand for species-specific reference ranges.
- Universities:Veterinary teaching hospitals integrate diagnostic platforms into clinical training curricula. Cornell and UC Davis anchor molecular testing workflows through reagent supply agreements with major manufacturers.
Veterinary Clinics capture the dominant revenue share, while Animal Hospitals are gaining share fastest through specialty service expansion.
Application:
Clinical utility and reimbursement accessibility determine penetration depth, with chronic disease management sustaining recurring revenue streams against one-time infectious disease screening.
- Infectious Diseases:Pathogen detection panels address zoonotic risk and outbreak containment in dense pet populations. Screening protocols for canine parvovirus and feline leukemia virus anchor routine wellness visits in Florida and California clinics.
- Oncology:Tumor marker quantification and chemotherapy monitoring support specialty cancer care. Academic centers in North Carolina and Minnesota deploy these assays for clinical trial enrollment and treatment response assessment.
- Endocrinology:Thyroid and cortisol testing manages chronic metabolic conditions in geriatric companion animals. Diabetic monitoring protocols in German practices generate monthly reagent consumption per established patient.
- Health Monitoring:Preventive screening panels establish baseline values and detect subclinical abnormalities. Wellness program adoption in Japanese pet insurance markets normalizes annual comprehensive testing.
Infectious Diseases maintains the leading position, though Oncology is climbing the fastest as specialty referral capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet insurance subsidies and streamlined regulatory pathways are accelerating instrument deployment across OECD veterinary markets. Diagnostic platform adoption concentrates where reimbursement structures normalize advanced testing expenditure during single-visit consultations.
United States
Companion animal clinics in Texas and Florida drive immunoassay volume through wellness program enrollment. The FDA's streamlined 510(k) pathway compresses veterinary device approval timelines. Massachusetts and California host dense clusters of instrument manufacturing and reagent formulation facilities serving domestic and export markets.
Germany
Endocrinology monitoring protocols in Bavarian and North Rhine-Westphalian practices generate recurring reagent consumption per insured patient. CE marking under the EU Medical Device Regulation consolidates qualified supplier pools for European clinics. Academic veterinary hospitals in Leipzig and Munich anchor molecular testing workflows through specialized reagent supply arrangements.
Japan
Pet insurance penetration in Tokyo and Osaka metropolitan areas normalizes annual comprehensive health screening panels. The PMDA governs software-as-medical-device classifications for algorithm-driven pathology modules. Corporate practice groups in Kansai region standardize on automated analyzer platforms across multi-site networks.
United Kingdom
Specialty referral centers in London and Southeast England command premium pricing for rapid turnaround oncology services. The MHRA aligns veterinary device oversight with post-Brexit regulatory autonomy. University teaching hospitals in Edinburgh and Glasgow integrate diagnostic platforms into clinical training curricula.
Brazil
Large-animal production facilities in Mato Grosso and Paraná present expanding demand for rapid infectious disease screening in agribusiness operations. ANVISA regulates veterinary diagnostic device registration timelines for commercial entry. Regional veterinary distributors in São Paulo state consolidate procurement channels for southern agricultural zones.
Veterinary Point-Of-Care Diagnostics Market Key Industry Players
Listed leaders compete with private specialists across platform technology and reagent chemistry dimensions. The market structure shows moderate concentration with tiered positioning between integrated diagnostic conglomerates and specialized consumable suppliers. Three strategic archetypes dominate: instrument manufacturers with captive reagent ecosystems, pharmaceutical-diagnostics bundlers leveraging vaccine portfolios, and independent reference laboratory networks. M&A activity targets molecular testing capabilities and regional distribution assets.
Among US-based diagnostics conglomerates, IDEXX Laboratories and Zoetis exemplify platform lock-in strategies through instrument placement and consumable attachment. Thermo Fisher Scientific occupies a position anchoring molecular reagent supply to academic veterinary hospitals. These three represent distinct competitive vectors: point-of-care instrument saturation, pharmaceutical-diagnostic bundling, and high-complexity laboratory workflow integration.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Zoetis |
| Virbac |
| Thermo Fisher Scientific |
| Mindray |
| FUJIFILM Corporation |
| Antech Diagnostics |
| Heska Corporation |
| Woodley Equipment Company |
| Others |
Cost & Logistics Intelligence
Cartridge-based chemistry substitution for wet reagent workflows simultaneously concentrates manufacturing in Massachusetts and California clusters while compressing margin recovery for independent veterinary clinics outside corporate practice groups. This displacement locks buyers into proprietary consumable ecosystems where instrument placement economics dominate lifetime value capture.
Pricing Analysis
Certification level creates the primary spread across veterinary diagnostic platforms, with FDA 510(k)-cleared and CE-marked systems commanding premium positioning against non-certified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 validation status, cartridge menu breadth, and after-sales service bundling. Cost compression in the independent clinic tier is intensifying because corporate practice groups negotiate enterprise pricing tiers that smaller buyers cannot replicate. Corporate buyers in Illinois and Ohio show the least price sensitivity due to volume scale, while rural practices in Kansas and Nebraska face acute margin pressure from proprietary reagent costs.
Supply Chain Analysis
Port congestion along the trans-Pacific trade lane from Shanghai to Long Beach periodically constrains microfluidic chip and optical component availability for instrument manufacturers. Manufacturing gravity centers on Massachusetts, California, and Pennsylvania, where reagent formulation and optical signal stability expertise clusters. Supply chains draw from German precision optics, Japanese electronic components, and domestic polymer substrates for cartridge housings. Single-source vulnerability in specialized microfluidic chip fabrication creates chokepoint exposure. Distribution runs through regional veterinary distributors in São Paulo state for Brazilian agribusiness markets and direct sales forces for North American corporate practice groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a post-pandemic pet ownership cyclical upswing that normalizes advanced diagnostic spending through expanded pet insurance enrollment.
For Market Incumbents: Compound platform lock-in through accelerated microfluidics R&D in California clusters and exclusive reagent supply agreements with Mars Veterinary Health and Vetcor procurement networks. ISO 13485 certification investment functions as the priority defensive lever against emerging Asian instrument manufacturers. Backward integration into polymer substrate production mitigates cartridge cost volatility. For New Entrants and Emerging Players: FDA streamlined 510(k) pathway acceleration enables faster US market entry against entrenched European competitors burdened by EU MDR transition timelines. Brazilian agribusiness expansion in Mato Grosso and Paraná presents the most penetrable white-space for rapid infectious disease screening platforms. Telemedicine integration partnerships with remote consultation networks offer differentiated go-to-market positioning beyond urban specialty centers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors molecular testing capability acquisitions and regional distribution asset accumulation. Long-term viability hinges on algorithm-driven pathology module differentiation as EU AI Act compliance reshapes competitive moats. Watch for PMDA software-as-medical-device classification signals in Japan as the inflection indicator for AI-enhanced diagnostic validation burdens.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance collapses supplier pools, accelerating placement cycles for qualified manufacturers. |
| Reimbursement Strategy | Pet insurance penetration in Germany and Japan normalizes advanced test expenditure per patient visit. |
| Hospital System Partnership | Cornell and UC Davis anchor molecular testing workflows through specialized reagent supply agreements. |
| Software Companion Development | Algorithm-driven interpretation modules reduce veterinarian cognitive load across distributed practice networks. |
| Backward Integration | In-house polymer substrate production mitigates proprietary cartridge cost pressure on independent clinics. |
Research Approach
A spread of perspectives from veterinary practice owners, diagnostic platform engineers, regulatory affairs specialists, and corporate procurement directors converged on the working assumptions governing market size and growth trajectory. Primary interviews with emergency and critical care veterinarians in Texas and Florida, reagent formulation chemists in Pennsylvania, and GPO contracts managers at Mars Veterinary Health combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation, and pet insurance reimbursement databases. Bottom-up instrument placement estimates and top-down diagnostic spending flows underwent cross-triangulation to reconcile volume and value outputs.
Segmentation dimensions modeled include product type, technology platform, end-user category, and application area across the projection horizon. Analytical framework deployment tracked immunoassay versus molecular test substitution dynamics, microfluidics adoption curves in university hospital settings, and corporate practice group procurement consolidation patterns. CAGRs emerged from logistic diffusion modeling of platform replacement cycles and reagent consumption intensity per insured patient. Forecast inputs incorporated ISO 13485 certification timeline data and EU AI Act algorithm classification risk tiering.
Underlying assumptions cover stable pet insurance penetration trajectories and FDA 510(k) pathway continuity, with deviation risk concentrated in EU MDR implementation delays and veterinary clinical pathologist shortage impacts on complex assay interpretation throughput. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Isoxazoline Market
Veterinary
Canine Arthritis Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Veterinary Thermography Market
Veterinary
Veterinary Scales Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Veterinary Supplements Market
Veterinary
Global Porcine Vaccine Market
Veterinary
France Veterinary Healthcare Market
Veterinary
Animal Microchip Implant Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Global Animal Vaccine Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
Animal Antibiotics Market
Veterinary
Global Canine Atopic Dermatitis Market