
 Europe Portable X-Ray Devices Market | 2026-2036
Europe Portable X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Portable X-Ray Devices Market Foresight
High-resolution digital detector specifications is collapsing the price premium between mid-tier and premium portable units. GE Healthcare leverages its detector manufacturing scale to anchor supply contracts with major German hospital networks. Siemens Healthineers AG sustains R&D intensity in wireless flat-panel technology, while Koninklijke Philips NV dominates ambulatory care channel control across the Netherlands and Belgium.
Europe portable X-ray devices are self-contained radiographic systems typically operating at 5-40 kVp with digital flat-panel detectors weighing under 15 kg, designed for bedside imaging in clinical environments where patient transport to fixed radiology suites is impractical or contraindicated. Mobile units lead volume deployment across European hospital systems, while handheld wireless configurations represent the fastest-growing margin pool as emergency departments adopt point-of-care trauma protocols. Digital radiography technology captures the dominant installed base, though computed radiography retains residual share in cost-sensitive Eastern European clinics transitioning from film-based workflows.
CE marking under the EU MDR and compliance with IEC 60601-2-54 standards govern product access across member states, while EMA coordination on radiation safety influences national procurement specifications in France and Italy. Germany's KBA-equivalent medical device regulator, the BfArM, enforces post-market surveillance requirements that shape manufacturer service network investments. Stakeholders must monitor how the EU AI Act classification rules affect emerging machine-learning diagnostic features in next-generation portable systems.
Market Dynamics
Hospital consolidation across Germany, France, and Italy is compressing procurement cycles and forcing portable X-ray vendors to restructure service networks around centralized buying consortia rather than individual facility relationships.
Growth Catalysts
- Emergency department point-of-care protocols:Trauma units in French and Italian hospitals are mandating bedside imaging capabilities to reduce patient transport risks. Mobile digital radiography systems satisfy these clinical requirements.
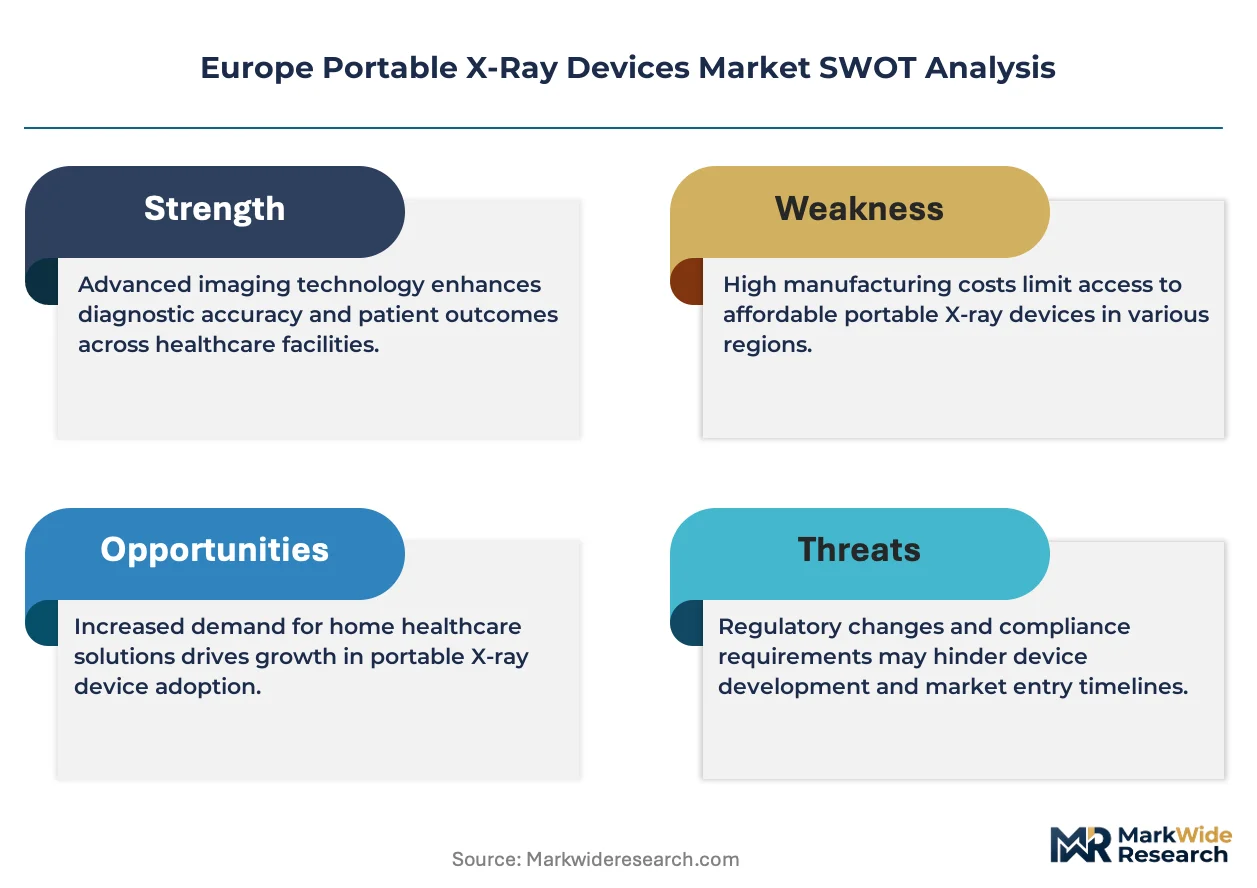
- EU Medical Device Regulation (MDR) quality tiering:Stricter CE marking requirements under MDR Article 10 are filtering out low-quality imports. Compliant manufacturers gain preferential access to German hospital networks.
- Wireless flat-panel detector maturation:Reduced weight and improved image latency enable handheld configurations for neonatal and intensive care applications previously served by mobile units.
Market Restraints
- Detector component concentration:Amorphous silicon flat-panel production concentrates among three Asian substrate suppliers, exposing European assemblers to input volatility and extended lead times.
- MDR transition compliance costs:Small Eastern European manufacturers face disproportionate burdens from clinical evaluation requirements and notified body backlogs, accelerating market exit.
- Fixed radiology suite substitution:Hospital groups with centralized imaging departments in Nordic countries question incremental portable unit deployment where patient transport remains feasible.
Strategic Opportunities
- Poland and Romania clinic modernization:Computed radiography-to-digital conversion programs in cost-sensitive Eastern European markets create volume openings for mid-tier portable systems with CR-compatible workflows.
- EU AI Act diagnostic feature pathway:Machine learning-enabled image quality optimization and automated positioning assistance face favorable classification as Class IIa devices, accelerating regulatory clearance timelines.
- Ambulatory surgery center channel expansion:Day-procedure facilities in Belgium and the Netherlands require compact imaging for orthopedic and chest examinations, bypassing traditional hospital procurement hierarchies.
Industry Challenges
- Clinical engineering workforce scarcity:Qualified biomedical technicians capable of servicing wireless detector calibration and tube head alignment remain concentrated in Western European urban centers.
- Legacy PACS integration complexity:Hospitals with decade-old picture archiving systems demand costly middleware development to accommodate new DICOM standards in portable devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Portable X-Ray Devices Market |
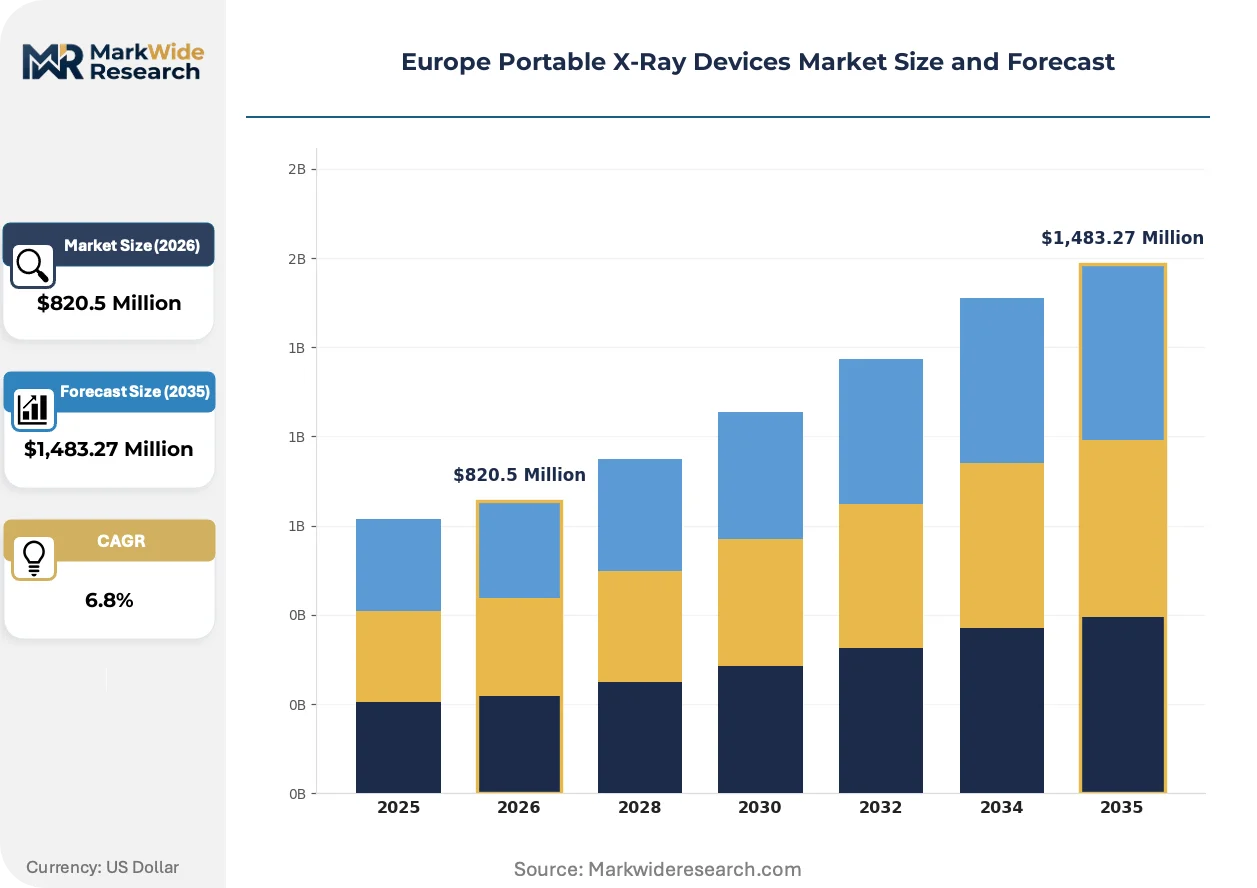
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,483.27 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Mobile, Stationary, Compact Technology: Digital Radiography, Computed Radiography, Film-Based, Wireless End User: Hospitals, Clinics, Diagnostic Centers, Home Care Application: Trauma, Orthopedics, Dentistry, Veterinary |
| Companies Covered | GE Healthcare, Siemens Healthineers AG, Koninklijke Philips NV, Canon Medical Systems, FUJIFILM Corporation, Carestream Health, Shimadzu Corporation, Varian Medical Systems Inc., Hitachi Medical Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Portable X-Ray Devices Market Shifts & Advancements
Detector technology convergence and regulatory classification of artificial intelligence features are restructuring competitive advantage around software-enabled service contracts rather than hardware specifications alone.
Wireless cassette-format detectors with integrated battery and data transmission modules are supplanting tethered configurations in emergency department deployments. Spanish and Portuguese hospital networks have accelerated adoption timelines from five-year replacement cycles to three-year refreshes. The technology is compressing price differentiation between mobile and handheld product categories as performance specifications converge.
The EU AI Act's risk-based classification framework for medical device software is reshaping product development roadmaps. Manufacturers must demonstrate clinical validation for algorithmic image enhancement features previously marketed as quality-of-life improvements. French notified bodies are processing the highest volume of AI-enabled portable X-ray pre-submissions, establishing de facto regulatory precedent for other member states.
Buying committees in German hospital networks are unbundling equipment procurement from multi-year service agreements. Separate tendering for detector replacement, software updates, and preventive maintenance is fragmenting vendor revenue streams. This pattern is most visible in North Rhine-Westphalia and Bavaria, where consolidated procurement entities leverage scale to drive component-level competition.
Europe Portable X-Ray Devices Market Segmentation
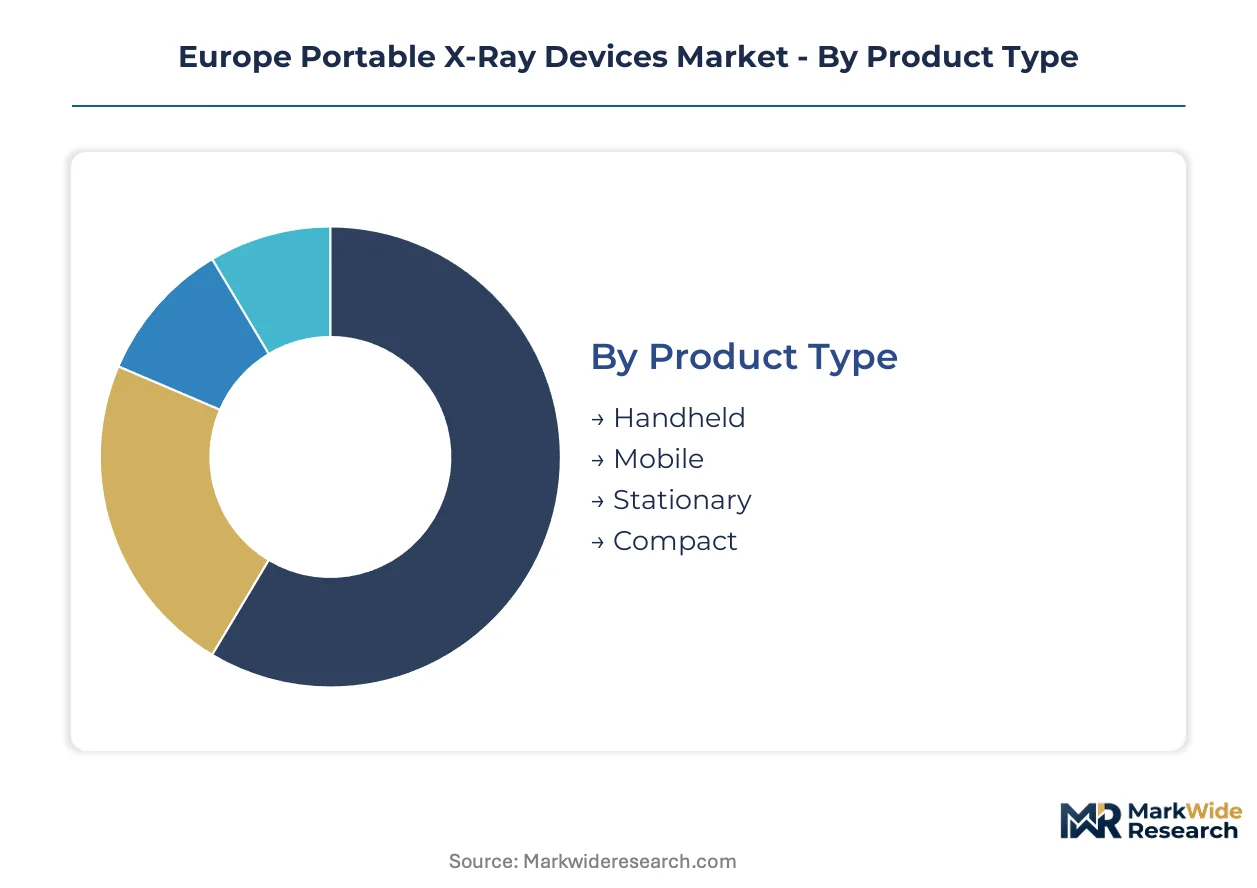
Portable X-ray segmentation in Europe reflects divergent clinical workflows and regulatory cost burdens across care settings. Product configuration choices directly determine CE marking pathway complexity and service network requirements under EU MDR enforcement.
Product Type:
Mobile configurations face intensifying substitution pressure from wireless handheld units as flat-panel detector weight drops below 3 kg and image latency improves to under 3 seconds.
- Handheld:Battery-powered wireless detectors with integrated transmission modules enable single-operator positioning in neonatal intensive care and emergency trauma bays. French and Italian hospitals are mandating these units for bedside protocols that eliminate patient transport risks.
- Mobile:Motorized column systems with tethered detectors dominate German hospital network procurement through centralized buying consortia. These units retain preference for orthopedic and general radiography where power reserves and tube stability matter.
- Stationary:Wall-mounted pivot-arm configurations serve dedicated imaging rooms in smaller Eastern European clinics transitioning from film-based workflows.
- Compact:Reduced-footprint mobile units with collapsible columns address space constraints in Belgian and Dutch ambulatory surgery centers.
Mobile configurations retain volume leadership across consolidated hospital networks; handheld units hold the steepest expansion curve as emergency departments adopt point-of-care trauma protocols.
Technology:
Technology choice in Europe stratifies sharply by procurement budget and legacy infrastructure, with cost tier rather than clinical outcome driving adoption in Eastern European markets.
- Digital Radiography:Amorphous silicon flat-panel detectors with direct conversion layers deliver dose efficiency and immediate image availability. German hospital networks specify DR exclusively for new procurement, while Polish and Romanian clinics deploy DR in phased modernization programs.
- Wireless:Cassette-format detectors with embedded batteries eliminate cable management and enable detector sharing across multiple tube heads. Spanish hospital networks have compressed replacement cycles from five years to three years for this technology.
- Computed Radiography:Photostimulable phosphor plate systems persist in cost-sensitive Bulgarian and Hungarian facilities where CR-compatible workflows ease transition from analog film.
- Film-Based:Analog screen-film combinations retain marginal share in remote rural clinics with limited technical service access and minimal digital infrastructure.
Digital Radiography commands the dominant installed base; wireless configurations are climbing the fastest as detector specifications converge with handheld form factors.
End User:
Customer type determines procurement channel structure, with hospital consolidation fragmenting vendor relationships while ambulatory channels enable direct equipment placement.
- Hospitals:Acute care facilities across Germany, France, and Italy operate centralized buying committees that unbundle equipment from service contracts. North Rhine-Westphalia and Bavaria procurement entities leverage scale for component-level competition.
- Clinics:Multi-specialty outpatient facilities in Poland and Romania drive volume demand for mid-tier portable systems with CR-compatible workflows during modernization programs.
- Diagnostic Centers:Independent imaging providers in the Netherlands and Belgium require rapid throughput configurations for high-volume chest and extremity examinations.
- Home Care:Palliative and post-operative monitoring services in France are piloting handheld units for bedbound patient imaging, though reimbursement frameworks remain unsettled.
Hospitals retain volume leadership through consolidated procurement power; home care channels hold the steepest expansion curve as reimbursement pilots expand in France.
Application:
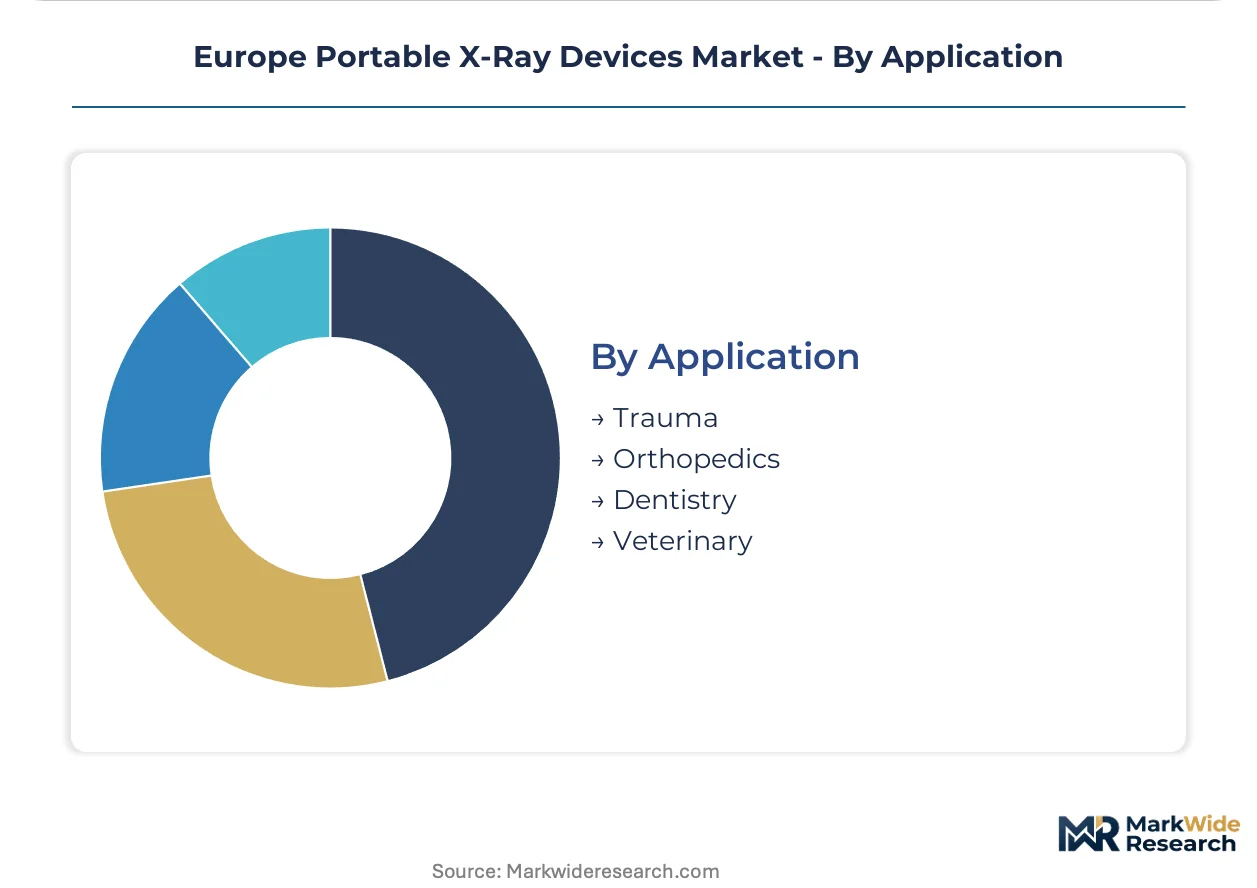
Application segmentation tracks surgical volume concentration and regulatory reimbursement codes, with trauma and orthopedics anchoring equipment utilization rates.
- Trauma:Emergency department point-of-care protocols mandate immediate imaging for cervical spine clearance and extremity fracture assessment. French hospital networks specify wireless handheld units for trauma bay deployment.
- Orthopedics:Pre-operative templating and post-operative alignment verification drive repeat imaging cycles in German and Italian orthopedic departments. Mobile digital units with weight-bearing capability command premium positioning.
- Dentistry:Intraoral and extraoral imaging for implant planning and temporomandibular assessment operates on separate regulatory and procurement pathways with distinct CE marking requirements.
- Veterinary:Equine and small-animal practices in the UK and Germany deploy portable units for field and clinic-based imaging, with detector durability specifications exceeding human-medical standards.
Orthopedics retains volume leadership through repeat imaging cycles; trauma applications hold the steepest expansion curve as emergency protocols mandate bedside imaging capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across European markets. German hospital networks exhibit price inelasticity for premium digital systems, while Polish and Romanian clinics prioritize cost-sensitive computed radiography transitions.
Germany
Hospital consolidation in North Rhine-Westphalia and Bavaria drives bulk procurement through centralized buying committees. BfArM enforces stringent post-market surveillance requirements that reshape manufacturer service network investments. The Rhine-Ruhr metropolitan cluster anchors deployment of motorized mobile units for orthopedic departments.
France
Emergency department point-of-care trauma protocols mandate wireless handheld configurations for cervical spine clearance. ANSM coordinates with EMA on radiation safety specifications that influence national procurement standards. The Paris-Saclay hospital network pilots machine-learning diagnostic features under EU AI Act pre-submission pathways.
Italy
Trauma bay bedside imaging requirements expand demand for lightweight detector systems across Lombardy and Emilia-Romagna. MDR Article 10 compliance timelines filter non-compliant imports from Eastern European suppliers. The Milan-Turin-Genoa industrial corridor concentrates service technician training programs for wireless calibration.
Netherlands
Ambulatory surgery centers in the Randstad region bypass traditional hospital procurement hierarchies for compact imaging systems. CE marking under EU MDR governs product access alongside national health technology assessment frameworks. The Eindhoven medical technology cluster supports rapid throughput configurations for diagnostic centers.
Poland
Clinic modernization programs in Warsaw and Krakow create volume openings for mid-tier portable systems with CR-compatible workflows. Cost-sensitive procurement favors phased digital radiography transitions over immediate full replacement. The country's national medical device regulator enforces IEC 60601-2-54 standards alongside EU harmonized requirements.
Europe Portable X-Ray Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European portable X-ray landscape. The market structure consolidates around diversified medical technology conglomerates with detector manufacturing scale, while mid-tier specialists compete on CR-compatible workflow transitions. Three archetypes dominate: integrated imaging system providers with captive detector supply, wireless technology specialists focused on emergency department protocols, and regional assemblers serving cost-sensitive Eastern European clinics. Competitive moves center on unbundling equipment procurement from service contracts and accelerating wireless flat-panel refresh cycles.
Within the integrated conglomerate tier, GE Healthcare, Siemens Healthineers AG, and Koninklijke Philips NV occupy positions shaped by manufacturing scale and channel control. GE Healthcare anchors supply relationships with major German hospital networks through detector production scale. Siemens Healthineers AG exemplifies sustained R&D positioning in wireless flat-panel development. Koninklijke Philips NV represents ambulatory care channel dominance across the Netherlands and Belgium. These three entities collectively illustrate how technology leadership converges with procurement influence in consolidated European health systems.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips NV |
| Canon Medical Systems |
| FUJIFILM Corporation |
| Carestream Health |
| Shimadzu Corporation |
| Varian Medical Systems Inc. |
| Hitachi Medical Corporation |
| Others |
Supply & Pricing Matrix
EU MDR Article 10 compliance requirements gate both supplier qualification and price differentiation simultaneously, as notified body certification costs filter low-quality imports while creating tiered access for compliant manufacturers serving German hospital networks. This regulatory architecture compresses margins for non-compliant assemblers while anchoring premium positioning for integrated conglomerates with captive detector supply.
Pricing Analysis
Multi-year service and detector replacement contracts drive lifetime value beyond initial hardware placement, with German buying committees unbundling these components for separate tendering. Pricing stratifies across premium wireless configurations, standard mobile units, and economy CR-compatible systems based on MDR certification tier and detector specification grade. Cost compression in mid-tier segments intensifies as Spanish networks compress replacement cycles. Eastern European clinics exhibit highest price sensitivity, while German orthopedic departments show inelastic demand for weight-bearing digital systems.
Supply Chain Analysis
Inbound logistics costs from Asian substrate suppliers through Rotterdam and Hamburg ports expose European assemblers to container availability volatility and extended lead times. Amorphous silicon flat-panel production concentrates in Japan, South Korea, and Taiwan, drawing from specialized glass substrate and thin-film transistor foundries. Single-source vulnerability in phosphor plate chemistry creates supply chain risk for CR-compatible workflow transitions. Distribution runs through manufacturer-direct service networks for German hospital consortia and regional distributor channels for Polish and Romanian clinic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-enabled service contracts expand faster than hardware placement as AI diagnostic features and wireless detector refresh cycles generate recurring revenue streams detached from capital equipment sales cycles.
For Market Incumbents: Consolidate service network density around North Rhine-Westphalia and Bavaria procurement entities to defend against unbundling pressure. Deepen backward integration into detector manufacturing to anchor supply relationships with major German hospital networks. Capture wireless flat-panel refresh cycles through three-year replacement programs in Spanish and Portuguese markets. For New Entrants and Emerging Players: Differentiate on CR-to-digital workflow compatibility for Polish and Romanian clinic modernization programs. Target ambulatory surgery centers in Belgium and the Netherlands with compact configurations bypassing traditional hospital procurement hierarchies. Pursue direct channel partnerships with diagnostic centers requiring rapid throughput systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wireless technology specialists focused on emergency department protocols. Long-term viability hinges on AI Act compliance capabilities and software service attach rates. Monitor EU AI Act pre-submission volumes through French notified bodies as inflection indicator for regulatory clearance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Detector Refresh Programs | Spanish hospital networks compress replacement cycles from five years to three years. |
| AI Diagnostic Feature Development | French notified bodies establish de facto regulatory precedent for Class IIa classification pathways. |
| Service Contract Unbundling Response | German buying committees in North Rhine-Westphalia fragment vendor revenue streams. |
| CR-Compatible Workflow Transitions | Polish and Romanian clinic modernization creates volume openings for mid-tier systems. |
| Ambulatory Surgery Center Channel Expansion | Belgian and Dutch day-procedure facilities bypass traditional hospital procurement hierarchies. |
Research Methodology
The analysis maps handheld wireless, mobile column, compact, and stationary configurations, each validated through hospital purchasing committees, biomedical engineering directors, GPO contracts managers, and notified body regulatory specialists. Primary fieldwork combined with secondary validation from EMA coordination documents, BfArM surveillance databases, hospital procurement records, and IEC 60601-2-54 standards filings. Bottom-up unit deployment tracking triangulates against top-down market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, technology tier, end-user channel, and application segmentation. CAGRs derived from modeled adoption curves incorporating MDR transition timelines, AI Act classification pathways, and wireless detector specification convergence. Industry-specific inputs include detector weight reduction trajectories and emergency department point-of-care protocol expansion rates.
The analysis sits within stated boundaries; outcomes outside EU MDR enforcement intensity, AI Act implementation timelines, or amorphous silicon substrate supply stability would require recalibration. Forecasts reflect documented assumptions regarding hospital consolidation trajectories and reimbursement framework evolution for home care pilots. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Australia Magnetic Resonance Imaging Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
PACS and RIS Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
Medical Imaging Market
Medical Imaging
US Diagnostic Imaging Services Market